
 Sorbitol Market | 2026-2036
Sorbitol Market Size, Share, and Industry Trends Forecast 2026-2036
Sorbitol Market Intelligence
The divergence between high-purity pharmaceutical-grade sorbitol and commodity-grade food sweeteners is consolidating the market into distinct tiers of quality and price. Cargill, Incorporated leverages its extensive corn processing infrastructure to achieve scale in commodity grades. Roquette Frères specializes in plant-based ingredients, including a broad portfolio of polyols for specialized applications. Archer Daniels Midland Company competes on its global manufacturing footprint and logistics network, supplying major food and beverage manufacturers.
Sorbitol is a sugar alcohol, or polyol, produced through the catalytic hydrogenation of glucose, which is typically derived from corn syrup. It functions primarily as a low-calorie bulk sweetener, humectant, and texturizing agent in various consumer and industrial products. Liquid sorbitol formats dominate volume due to their ease of integration in food processing lines. In contrast, powder sorbitol commands higher margins, particularly in demanding pharmaceutical formulations where purity is paramount.
Market access is governed by food additive and pharmaceutical excipient regulations. The U.S. FDA classifies sorbitol as Generally Recognized as Safe (GRAS), while the European Food Safety Authority (EFSA) approves it under the E-number E420. Similar standards from bodies like India's FSSAI and China's SAMR define acceptable usage levels in consumer goods, forcing producers to align manufacturing and quality control with specific purity requirements of target end-markets.
Market Dynamics
The primary structural force shaping the sorbitol market is regulatory pressure from global health organizations to reduce sugar consumption. This is creating a distinct bifurcation between high-volume, price-sensitive food-grade applications and high-margin, purity-driven pharmaceutical and personal care segments.
Growth Catalysts
- WHO Sugar Reduction Initiatives:Recommendations from the World Health Organization advocating for lower sugar intake directly compel food and beverage manufacturers to substitute sugar with low-calorie alternatives like sorbitol in confectionery, baked goods, and beverages.
- Pharmaceutical Excipient Demand:The growing use of sorbitol as a stable, non-reactive excipient in liquid oral medications, syrups, and as a plasticizer in gelatin capsules provides a consistent, high-value demand stream for pharmaceutical-grade products.
- Chinese Manufacturing Scale:China's extensive food processing and pharmaceutical manufacturing industries create concentrated demand, supported by domestic production capacity for corn-derived glucose, the primary feedstock for sorbitol synthesis.
Market Restraints
- Feedstock Price Volatility:The market's dependence on corn syrup as the primary source of glucose links sorbitol production costs directly to the price volatility of agricultural corn, impacting manufacturer margins.
- Threat from Other Polyols:Sorbitol faces direct substitution risk from other sugar alcohols such as erythritol, xylitol, and maltitol, which offer different sweetness profiles, caloric values, and digestive tolerance levels for formulators.
- Digestive Tolerance Limits:The known laxative effect of sorbitol when consumed in large quantities limits its maximum inclusion level in food products, constraining its use as a primary bulk sweetener in some applications.
Strategic Opportunities
- Plant-Based Food Applications:Sorbitol's function as a humectant and texturizing agent presents an opportunity for its expanded use in the rapidly growing plant-based meat and dairy alternative sectors to improve mouthfeel and shelf life.
- Penetration in Southeast Asia:Rising disposable incomes and nascent sugar-reduction policies in countries across Southeast Asia represent a significant growth frontier for sorbitol in processed foods and beverages.
- Synergistic Sweetener Blends:Developing proprietary blends that combine sorbitol with high-intensity sweeteners or other polyols allows producers to offer customized solutions that optimize taste, cost, and functional properties for specific food applications.
Industry Challenges
- Multi-Jurisdictional Compliance:Manufacturers face the operational challenge of adhering to disparate purity standards and monograph requirements for pharmaceutical-grade sorbitol, such as those defined by the USP, Ph. Eur., and JP.
- Capital-Intensive Production:The catalytic hydrogenation process requires substantial capital investment in high-pressure reactors and multi-stage purification systems, creating a high barrier to entry and constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorbitol Market |
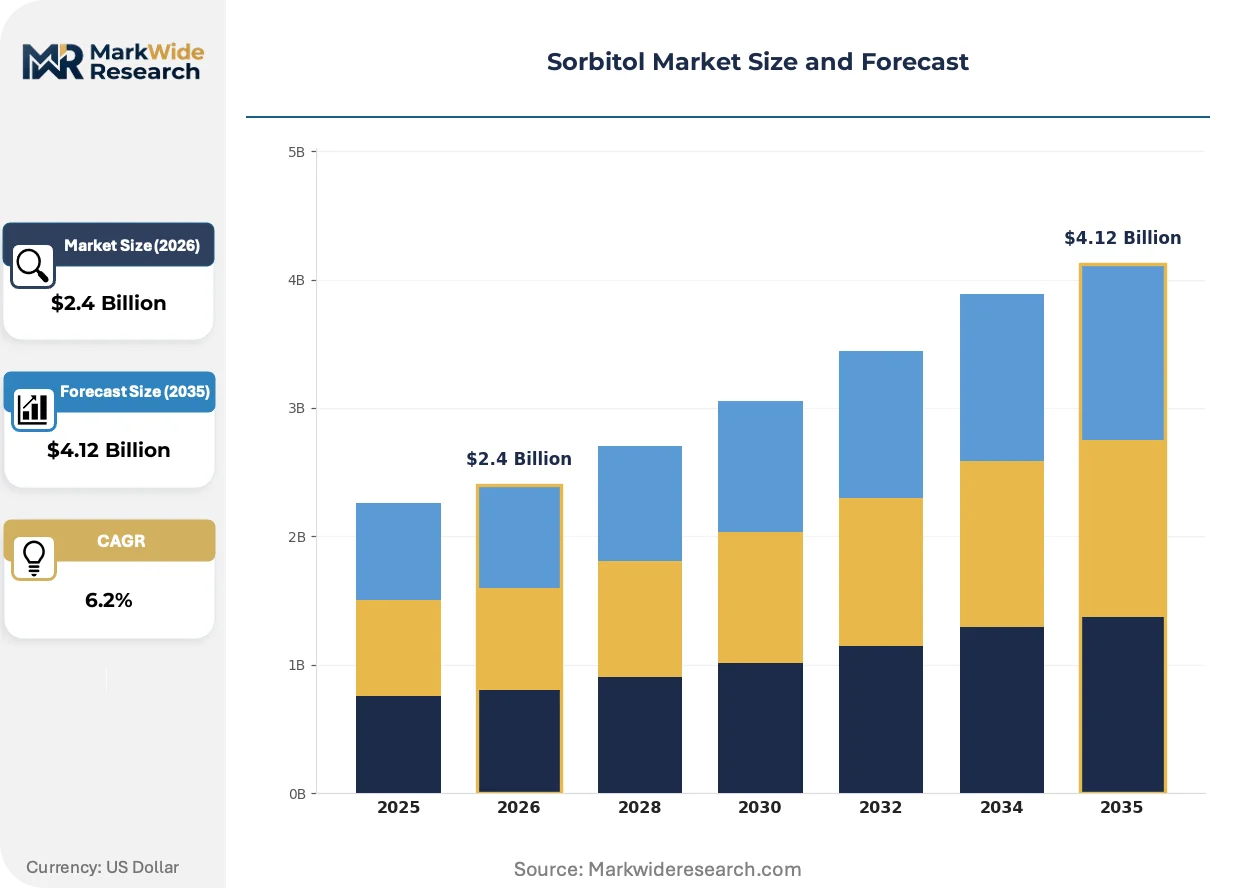
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Sorbitol, Liquid Sorbitol, D-Sorbitol, Sorbitol Syrup, Granular Sorbitol Application: Pharmaceutical Formulations, Food Sweeteners, Personal Care Products, Cosmetic Ingredients, Industrial Solvents End User: Food & Beverage Manufacturers, Pharmaceutical Companies, Cosmetic Producers, Chemical Industries Packaging Type: Drums, Bulk Bags, Bottles, Totes, Pails |
| Companies Covered | Tereos Group, Gulshan Polyols Ltd, Roquette Frères, Merck KGaA, SPI Pharma Inc., Cargill, Incorporated, Ingredion Incorporated, Ecogreen Oleochemicals, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorbitol Market Strategic Shifts & Innovations
The market is evolving along two parallel tracks: one focused on optimizing cost and logistics for commodity food applications, and the other centered on purity and functional innovation for specialty pharmaceutical and personal care use. This divergence is defining investment in new capacity and R&D.
Advanced chromatographic separation methods are enabling the production of ultra-high-purity sorbitol grades. Pharmaceutical and nutraceutical formulators are rapidly adopting these specialized products for sensitive applications like biopharmaceutical stabilization and injectable formulations. In terms of value creation, the demand for these certified, low-endotoxin grades is overtaking that for standard food-grade sorbitol.
Regulatory scrutiny from bodies like the European Food Safety Authority (EFSA) on food additives, including E420 (sorbitol), is a persistent trend. These ongoing safety re-evaluations require manufacturers to maintain robust data on toxicology and production processes, increasing the compliance burden. Food companies operating within the EU are most affected, frequently adapting formulations to align with any revised acceptable daily intake levels.
A preference for "clean label" ingredients is altering procurement behavior among food and beverage brand owners. This movement away from purchasing based solely on price disrupts the supply of undifferentiated commodity sweeteners, placing a new emphasis on source transparency and non-GMO certification. This shift is most visible in the health and wellness food categories across North American and European markets.
Sorbitol Market Segmentation
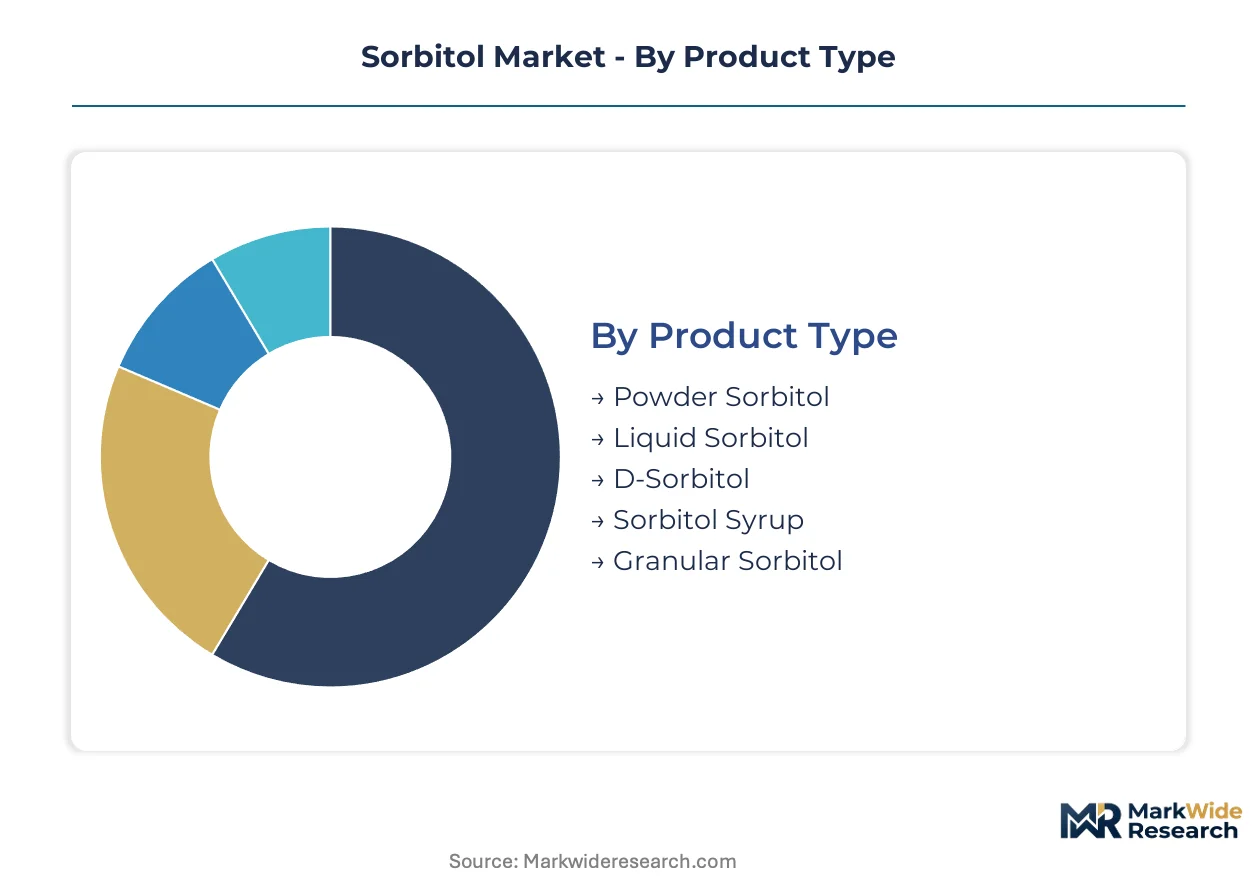
The sorbitol market's segmentation reflects the diverse functional demands across its end-use sectors, influencing production scale, purity requirements, and distribution channels. Understanding these distinct segments is crucial for manufacturers to align their product portfolios with specific market needs and regulatory landscapes.
Product Type:
Capital intensity differentiates sorbitol product types, with specialized purification processes demanding higher upfront investment for certain forms.
- Liquid Sorbitol:This format, typically an aqueous solution of 70% sorbitol, is a viscous, clear liquid primarily used as a bulk sweetener and humectant. Demand concentrates in the food processing industry, particularly for confectionery and baked goods, due to its ease of integration into liquid formulations.
- Powder Sorbitol:Crystalline powder sorbitol offers high purity and specific particle sizes, making it ideal for solid dosage forms and applications requiring precise blending. Pharmaceutical formulations and nutraceuticals drive demand for this high-value product, especially in Europe and North America, where strict excipient standards apply.
- D-Sorbitol:Chemically identical to sorbitol, D-sorbitol emphasizes its specific stereoisomeric form, often relevant for biochemical or highly sensitive applications. It finds use in specialized laboratory reagents and certain cosmetic formulations.
- Sorbitol Syrup:A broader category than liquid sorbitol, sorbitol syrup can include varying concentrations and polyol mixtures, offering flexibility for industrial applications. It serves as a cost-effective humectant in animal feed and certain industrial chemical processes.
- Granular Sorbitol:This form provides enhanced flowability and reduced dust, making it suitable for direct compression in tablet manufacturing and dry mix food products. Its primary application is in sugar-free chewing gum and compressed candies.
Most installed capacity flows through Liquid Sorbitol. Expansion is steepest in Powder Sorbitol.
Application:
Margin differentiation drives the application segments, with pharmaceutical and personal care uses commanding premium pricing due to stringent quality control and formulation requirements.
- Pharmaceutical Formulations:Sorbitol functions as an excipient, diluent, and humectant in tablets, capsules, and liquid oral medications, providing stability and taste masking. Global pharmaceutical companies prioritize ultra-high purity grades for these applications, particularly in regulated markets like the United States and Germany.
- Food Sweeteners:Sorbitol serves as a low-calorie bulk sweetener, humectant, and texturizing agent in sugar-free confectionery, baked goods, and diet beverages. Regulatory initiatives from the World Health Organization advocating for sugar reduction propel its use in processed foods across China and Southeast Asia.
- Personal Care Products:Sorbitol acts as a humectant in toothpastes, mouthwashes, and skincare products, preventing moisture loss and providing a smooth texture. Cosmetic producers in France and South Korea incorporate it for its mildness and moisturizing properties.
- Cosmetic Ingredients:Similar to personal care, sorbitol is used in makeup and hair care products for its emollient and conditioning effects. Its natural origin appeals to clean label cosmetic brands.
- Industrial Solvents:Sorbitol finds niche applications as a chemical intermediate or solvent in specific industrial processes, including the production of ascorbic acid (Vitamin C). Chemical manufacturers in India utilize it for its polyol structure.
Demand for Food Sweeteners remains substantial. Pharmaceutical Formulations are gaining momentum.
End User:
Volume requirements largely define the end-user segments, with large-scale food and beverage manufacturers consuming the greatest quantities of commodity-grade sorbitol.
- Food & Beverage Manufacturers:These companies utilize sorbitol extensively as a sugar substitute, humectant, and texturizer in a wide array of products, from chewing gum to diet drinks. Their procurement focuses on cost-effectiveness and consistent supply for high-volume production lines.
- Pharmaceutical Companies:Requiring high-purity, often certified-grade sorbitol, these users integrate it as a critical excipient in drug formulations. Compliance with pharmacopoeial standards from the USP, Ph. Eur., and JP is paramount for their sourcing decisions.
- Cosmetic Producers:Manufacturers of personal care and beauty products use sorbitol for its moisturizing and conditioning properties. They seek stable, high-quality ingredients that align with consumer preferences for natural-derived components.
- Chemical Industries:This segment uses sorbitol as a raw material or intermediate in various chemical syntheses, including the production of resins and polyurethanes. Their demand is often for technical-grade sorbitol in bulk quantities.
The largest procurement volumes originate from Food & Beverage Manufacturers. Niche specialization drives growth for Pharmaceutical Companies.
Packaging Type:
Logistical efficiency and scale of operations dictate the choice of packaging type, with bulk options dominating for large industrial users.
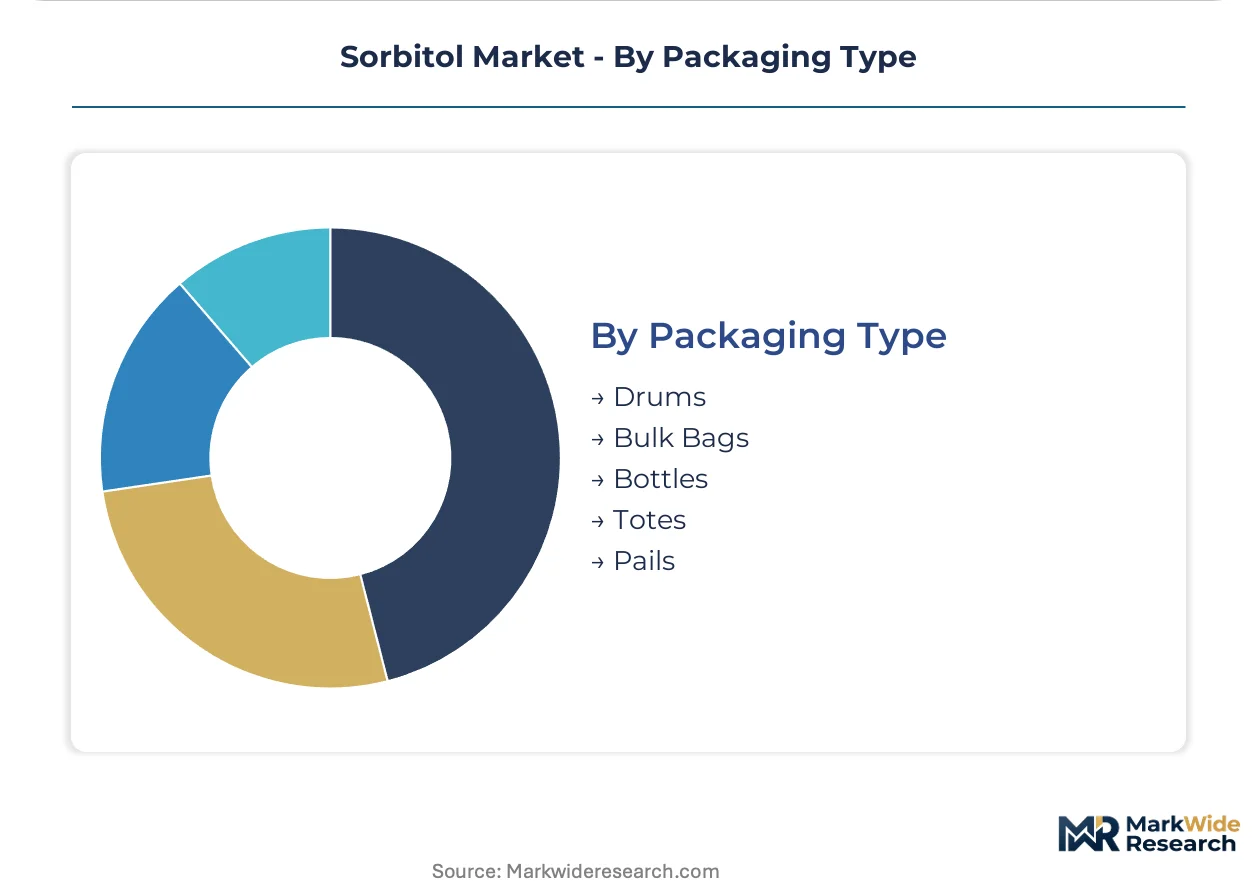
- Drums:These containers, typically 200-liter capacity, provide a standard solution for shipping liquid and powdered sorbitol to mid-sized industrial customers. They offer a balance between bulk volume and ease of handling for various manufacturing sites.
- Bulk Bags:Also known as Flexible Intermediate Bulk Containers (FIBCs), these large bags hold up to a metric ton of powdered sorbitol, optimizing transport and storage for high-volume users. Food processing facilities and large pharmaceutical ingredient suppliers extensively use bulk bags.
- Bottles:Smaller volumes of specialized or pharmaceutical-grade liquid sorbitol are packaged in bottles for precise dispensing or for distribution to smaller formulators. This format ensures product integrity for sensitive applications.
- Totes:Intermediate bulk containers (IBCs) or totes offer a reusable solution for transporting liquid sorbitol in quantities larger than drums but smaller than tank trucks. They are common in chemical and food ingredient distribution networks.
- Pails:Smallest among industrial packaging, pails are used for specific, often higher-value, sorbitol grades or for customers requiring limited quantities. They are suitable for laboratory use or small-batch cosmetic production.
Logistical optimization prioritizes Bulk Bags formats. Specialized handling supports Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled chemical engineers and food scientists anchoring research hubs across major economic zones drive sorbitol market dynamics. Regulatory frameworks and local feedstock availability significantly influence production capabilities and market penetration. Regional demand profiles diverge between high-volume food applications and high-margin pharmaceutical segments, reflecting varying economic development stages.
China
Extensive food processing and pharmaceutical manufacturing create concentrated demand for sorbitol. The State Administration for Market Regulation (SAMR) defines acceptable usage levels in consumer goods, influencing product formulations. Industrial clusters in the Yangtze River Delta actively produce corn-derived glucose, the primary feedstock for sorbitol synthesis.
United States
Pharmaceutical companies require high-purity sorbitol as a critical excipient in drug formulations. The U.S. FDA classifies sorbitol as Generally Recognized as Safe (GRAS), facilitating its widespread use in food products. Major pharmaceutical and food ingredient manufacturers in the Northeast corridor drive significant procurement volumes.
Germany
European pharmaceutical formulators prioritize ultra-high purity sorbitol for sensitive applications. The European Food Safety Authority (EFSA) approves sorbitol under the E-number E420, guiding food and beverage industry usage. Advanced chemical and pharmaceutical manufacturing in the Rhine-Main region focuses on specialized sorbitol grades.
India
Chemical manufacturers utilize sorbitol as a raw material in various syntheses, including ascorbic acid production. The Food Safety and Standards Authority of India (FSSAI) sets acceptable usage levels, impacting food sweetener applications. Gujarat's robust chemical manufacturing sector provides a strong base for industrial sorbitol demand.
France
Cosmetic producers incorporate sorbitol for its mildness and moisturizing properties in personal care products. The French National Agency for Medicines and Health Products Safety (ANSM) oversees pharmaceutical excipient quality, ensuring stringent standards. The Cosmetic Valley cluster in central France drives innovation in sorbitol-containing beauty formulations.
Sorbitol Market Key Industry Players
Top-tier vendors anchor integrated global supply chains, while specialized producers focus on high-purity grades. The market structure exhibits a clear bifurcation between commodity-scale production and niche specialty segments. Key archetypes include large agricultural processors, dedicated polyol manufacturers, and pharmaceutical ingredient specialists. Dominant competitive moves involve capacity expansion in emerging markets and portfolio diversification into higher-value applications.
At the scale-driven end, Cargill, Incorporated, and Archer Daniels Midland Company exemplify large-scale agricultural processors leveraging extensive corn processing infrastructure. These companies compete on cost-effectiveness and consistent supply for high-volume food and beverage manufacturers. Roquette Frères, conversely, represents a specialized ingredient player with a broad portfolio of plant-based polyols for diverse applications. These firms navigate multi-jurisdictional compliance requirements to access various end-markets.
| Leading Market Players |
|---|
| Tereos Group |
| Gulshan Polyols Ltd |
| Roquette Frères |
| Merck KGaA |
| SPI Pharma Inc. |
| Cargill, Incorporated |
| Ingredion Incorporated |
| Ecogreen Oleochemicals |
| Archer Daniels Midland Company |
Cost & Logistics Intelligence
Advanced chromatographic separation methods are reshaping cost economics and concentrating supply in ultra-high purity sorbitol grades. This technological shift creates a distinct cost structure between commodity food applications and specialized pharmaceutical uses.
Pricing Analysis
The bundled-vs-unbundled service split drives pricing differentiation across the sorbitol market. Pricing stratifies across premium, standard, and economy tiers based on purity requirements and volume scale. Pharmaceutical-grade sorbitol commands premium prices due to stringent quality control and certification levels, such as USP or Ph. Eur. Pricing pressure stems from feedstock price volatility and direct substitution risk from other polyols in the food-grade segment. Food & Beverage Manufacturers exhibit the highest price sensitivity, while Pharmaceutical Companies are least sensitive due to critical application needs.
Supply Chain Analysis
Dual-sourcing requirements from major buyers influence the sorbitol supply chain, promoting resilience. Geographic supply concentrates in China, which produces corn-derived glucose, and in Europe, where specialized polyol manufacturers operate. The market relies heavily on corn syrup as a primary feedstock, linking production costs to agricultural commodity markets. Feedstock price volatility presents a structural risk for manufacturers. Distribution runs through direct sales channels for large industrial users and specialized distributors for niche, high-purity applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, leveraging cost-effective production in Asia against high-margin demand in regulated Western markets. Regulatory disparities, such as those from the U.S. FDA versus China's SAMR, create distinct value pools.
For Market Incumbents: Cement market share in commodity food-grade sorbitol through strategic capacity expansion in regions like China. Invest in advanced purification technologies to meet evolving pharmaceutical excipient standards, mitigating the threat from specialized polyol competitors. Leverage existing corn processing infrastructure to achieve cost leadership, protecting margins against feedstock price fluctuations.
For New Entrants and Emerging Players: Specialty chemical distributors offer a viable entry point for novel sorbitol products. Target the rapidly growing plant-based food applications in Southeast Asia, focusing on sorbitol's humectant and texturizing properties. Emphasize clean label certifications and non-GMO sourcing to appeal to health-conscious consumers in North American and European markets. Powder sorbitol for nutraceuticals represents a penetrable segment.
For Investors and Strategic Acquirers: Valuations sit cheapest among commodity-grade sorbitol producers with strong feedstock integration. The long-term viability of the sorbitol market is underpinned by persistent sugar reduction initiatives and stable pharmaceutical excipient demand. Identify acquisition targets that possess proprietary blending technologies or specialized purification capabilities for ultra-high purity grades. A signal to watch is increased M&A activity in specialized polyol segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Increases supply efficiency for food-grade sorbitol, serving China's large food processing sector. |
| Green Manufacturing Transition | Enhances brand appeal and compliance with evolving sustainability mandates from European customers. |
| Long-term Feedstock Supply Agreements | Mitigates cost volatility risks associated with corn syrup, stabilizing production expenses for manufacturers. |
| Product Launch of Synergistic Blends | Offers customized solutions to food and beverage manufacturers, optimizing taste and functional properties. |
| Regulatory Approval Pathway Acceleration | Expedites market access for new pharmaceutical excipient applications with bodies like the U.S. FDA. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. This involved in-depth interviews with food processing R&D leads, pharmaceutical procurement managers, chemical plant engineers, and regulatory affairs specialists. Secondary validation drew from WHO guidelines, FDA GRAS classifications, EFSA opinions, FSSAI standards, and trade association publications. Bottom-up and top-down triangulation ensured data integrity across all market segments.
Rate-of-change decomposition framed the analytical framework across the projection horizon. The quantitative model incorporated segmentation across product type, application, end-user, packaging format, and regional regulatory environment. Compound annual growth rates were derived from historical growth patterns and projected adoption rates. Industry-specific forecast inputs included corn price trends and global sugar consumption reduction targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and feedstock price volatility. Forecasts reflect assumptions regarding technological advancements and market dynamics. Deviation in the emergence of novel polyols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Mannitol Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
China Food Sweetener Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
South America Stevia Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Sugar Syrups Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
Agave Nectar Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Palm Sugar Market
Sweeteners
Cassava Syrup Market