
 D-Mannose Market | 2026-2036
D-Mannose Market Size, Share, and Industry Trends Forecast 2026-2036
D-Mannose Market Analysis
Chinese fermentation-grade producers is consolidating capacity around pharmaceutical-specification output, tightening supply availability for lower-purity feedstock. NOW Health Group, Inc. leverages vertical integration from raw material sourcing to finished capsule packaging. Douglas Laboratories differentiates through clinician-only distribution and third-party potency certification. Pfanstiehl Inc anchors North American supply with USP-grade crystallization capabilities.
D-mannose is a C-2 epimer of glucose, a six-carbon monosaccharide typically manufactured via enzymatic isomerization of D-glucose or extraction from larch hemicellulose, with purity grades spanning food-grade to injectable USP-NF specifications. Its primary commercial purpose centers on bacterial anti-adhesion therapy, particularly for Escherichia coli prevention in urinary tract management protocols. Capsule and tablet formats dominate consumer-facing revenue pools due to dosing convenience and compliance advantages, while concentrated powder serves compounding pharmacies and veterinary formulators seeking flexible titration. Pharmaceutical companies represent the fastest-growing end-user channel as drug-device combination trials expand D-mannose beyond nutraceutical positioning.
FDA dietary supplement CGMP rules and USP-NF monograph standards govern purity, identity, and contamination thresholds for US-market products, while EFSA Novel Food classifications shape European import and label claim pathways. These frameworks elevate compliance costs for smaller raw material traders and favor producers with in-house analytical laboratories and regulatory dossier capabilities. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP specifications, as divergence in residual solvent limits and microbial enumeration methods threatens cross-border formulation strategies.
Market Dynamics
Fermentation-grade capacity consolidation among Chinese pharmaceutical-specification producers is tightening lower-purity feedstock availability, forcing nutraceutical formulators to absorb higher input costs or reformulate around alternative sourcing corridors.
Growth Catalysts
- USP-NF Purity Verification Mandates:FDA dietary supplement CGMP regulations now require identity testing for imported raw materials, advantaging domestic producers with in-house analytical laboratories and certified reference standards.
- Drug-Device Combination Trials:Pharmaceutical companies are advancing D-mannose beyond nutraceutical positioning into urology device coatings and catheter lock solutions, opening prescription reimbursement pathways.
- Direct-to-Consumer Channel Expansion:United States integrative medicine clinics and telehealth platforms are aggregating patient demand for preventive urinary tract management protocols.
Market Restraints
- Input Cost Volatility:Larch hemicellulose extraction yields fluctuate with North American forestry harvest cycles, pressuring natural-source D-mannose cost structures against enzymatic glucose-isomerized alternatives.
- Supply Concentration Risk:Three fermentation facilities in Shandong Province control over half of pharmaceutical-grade crystallization capacity, creating single-point vulnerability for USP-grade raw material procurement.
- EFSA Novel Food Classification Friction:European import dossier requirements for non-traditional food ingredients delay market entry by 18-24 months versus US notification pathways.
Strategic Opportunities
- Veterinary Formulation White Space:Companion animal urology represents an underpenetrated end-use, with compounding pharmacies seeking concentrated powder formats for flexible canine and feline dosing.
- Pharmacopeial Harmonization Tailwinds:Convergence discussions between USP, EP, and JP residual solvent limits would streamline multi-territory formulation strategies for multinational pharmaceutical clients.
- Continuous Chromatography Adoption:Simulated moving bed technology is improving separation efficiency in glucose isomerization workflows, reducing purification capex for mid-scale entrants.
Industry Challenges
- Analytical Chemist Talent Scarcity:USP-NF monograph compliance requires specialized expertise in carbohydrate structural analysis and impurity profiling that outpaces academic pipeline output.
- Multi-Jurisdiction Dossier Complexity:Divergent microbial enumeration methods between FDA, EFSA, and TGA specifications force redundant stability testing and label claim substantiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | D-Mannose Market |
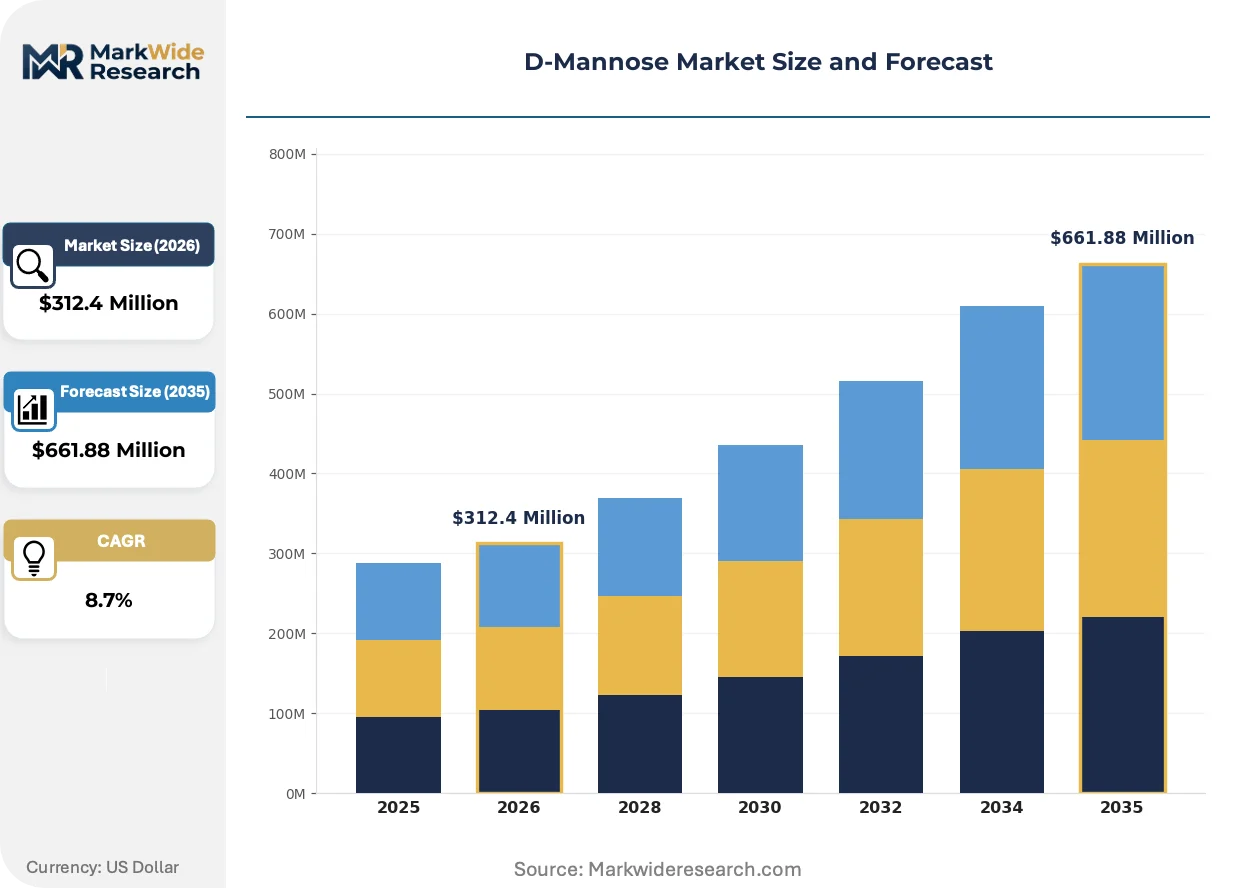
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Powder, Liquid Extract, Capsules, Tablets End User: Pharmaceutical Companies, Nutraceutical Firms, Healthcare Providers, Research Institutions Distribution Channel: Online Retail, Health Stores, Pharmacies, Direct Sales Application: Urinary Tract Health, Dietary Supplement, Cosmetics, Veterinary Care |
| Companies Covered | Nestle Health Science, NOW Health Group, Inc., Pfanstiehl Inc, DuPont de Nemours, Inc., Vibrant Health, Douglas Laboratories, Sweet Cures, Hanseler AG, Bio-Tech Pharmacal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
D-Mannose Market Emerging Trajectories
Enzymatic manufacturing workflows and analytical certification standards are compressing batch-to-batch variability while opening new therapeutic positioning beyond traditional nutraceutical applications.
Continuous chromatography systems for glucose isomerization and D-mannose separation are decentralizing purification capacity away from centralized Chinese fermentation hubs. Mid-scale North American producers are adopting simulated moving bed technology to achieve USP-grade purity without crystallization scale requirements. This distributed manufacturing model is shortening supply chains for compounding pharmacies and veterinary formulators seeking flexible procurement.
EFSA Novel Food classification pathways are tightening evidentiary thresholds for urinary tract health label claims across European Union member states. The regulator now requires human intervention studies demonstrating bacterial anti-adhesion mechanisms for non-pharmaceutical positioning. German and French distributors are responding by bifurcating product lines into food supplement and medical food categories with divergent marketing authorization strategies.
Subscription-based replenishment models are displacing traditional retail pharmacy purchasing for recurrent urinary tract management consumers. United States telehealth platforms and integrative medicine clinics are aggregating patient cohorts into direct-ship programs with quarterly potency testing certificates. California and New York metropolitan areas exhibit the highest penetration of this channel shift, with patient compliance tracking driving reorder automation.
D-Mannose Market Segmentation
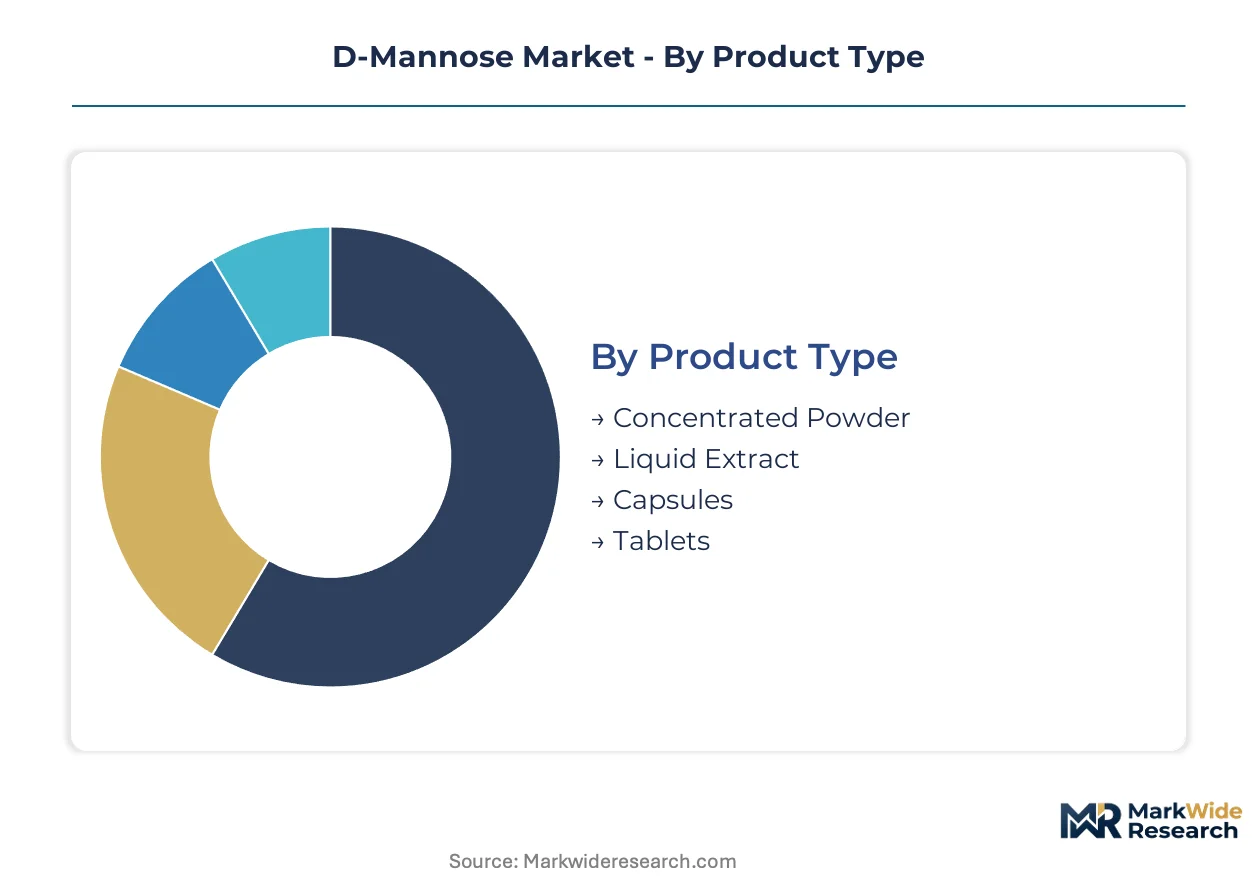
D-Mannose formulations diverge sharply in purity specifications, dosing flexibility, and regulatory pathways. Buyers select formats based on end-use compliance requirements, from USP-grade pharmaceutical inputs to food-grade nutraceutical positioning.
Product Type:
Purchasing decisions here pivot on batch consistency needs and formulation flexibility across compounding versus finished goods manufacturing.
- Concentrated Powder:USP-grade crystalline powder serves compounding pharmacies and veterinary formulators requiring precise titration control. Demand clusters in North American integrative medicine clinics seeking bulk procurement for custom urinary tract protocols. FDA dietary supplement CGMP identity testing mandates favor domestic producers with certified reference standards.
- Capsules:Pre-measured gelatin and vegetarian shells dominate direct-to-consumer channels through telehealth platforms and subscription replenishment models. NOW Health Group and Douglas Laboratories anchor this segment with third-party potency certification and clinician-only distribution tiers respectively.
- Tablets:Compressed formulations with binding agents suit retail pharmacy shelf placement and travel convenience packaging.
- Liquid Extract:Glycerin-based suspensions target pediatric and geriatric populations with swallowing difficulties.
Capsules lead volumes today; concentrated powder is gaining share fastest.
End User:
Regulatory sophistication and reimbursement pathways separate these buyer categories.
- Pharmaceutical Companies:Drug-device combination trials for urology catheter coatings and bladder irrigation solutions require injectable USP-NF specifications. Pfanstiehl Inc supplies this channel with North American crystallization capabilities.
- Nutraceutical Firms:Dietary supplement manufacturers incorporate D-mannose into multi-ingredient urinary health formulations, navigating FDA CGMP purity verification for imported raw materials.
- Healthcare Providers:Integrative medicine clinics and urology practices prescribe preventive protocols, aggregating patient demand through direct-ship programs.
- Research Institutions:Academic laboratories source analytical-grade material for bacterial anti-adhesion mechanism studies and novel therapeutic investigations.
Pharmaceutical companies show steepest expansion trajectory; nutraceutical firms retain the largest installed base.
Distribution Channel:
Channel selection determines label claim latitude and patient compliance monitoring capabilities.
- Online Retail:Subscription-based replenishment models displace traditional pharmacy purchasing for recurrent urinary tract management consumers.
- Direct Sales:Telehealth platforms and integrative medicine clinics aggregate patient cohorts with quarterly potency testing certificates.
- Pharmacies:Retail and hospital pharmacy networks stock capsule and tablet formats for acute symptom management.
- Health Stores:Natural product retailers position D-mannose within broader urinary wellness and cranberry adjunct categories.
Online retail commands volume leadership; direct sales channels are climbing the fastest.
Application:
Clinical evidence requirements and regulatory classification boundaries define addressable market scope.
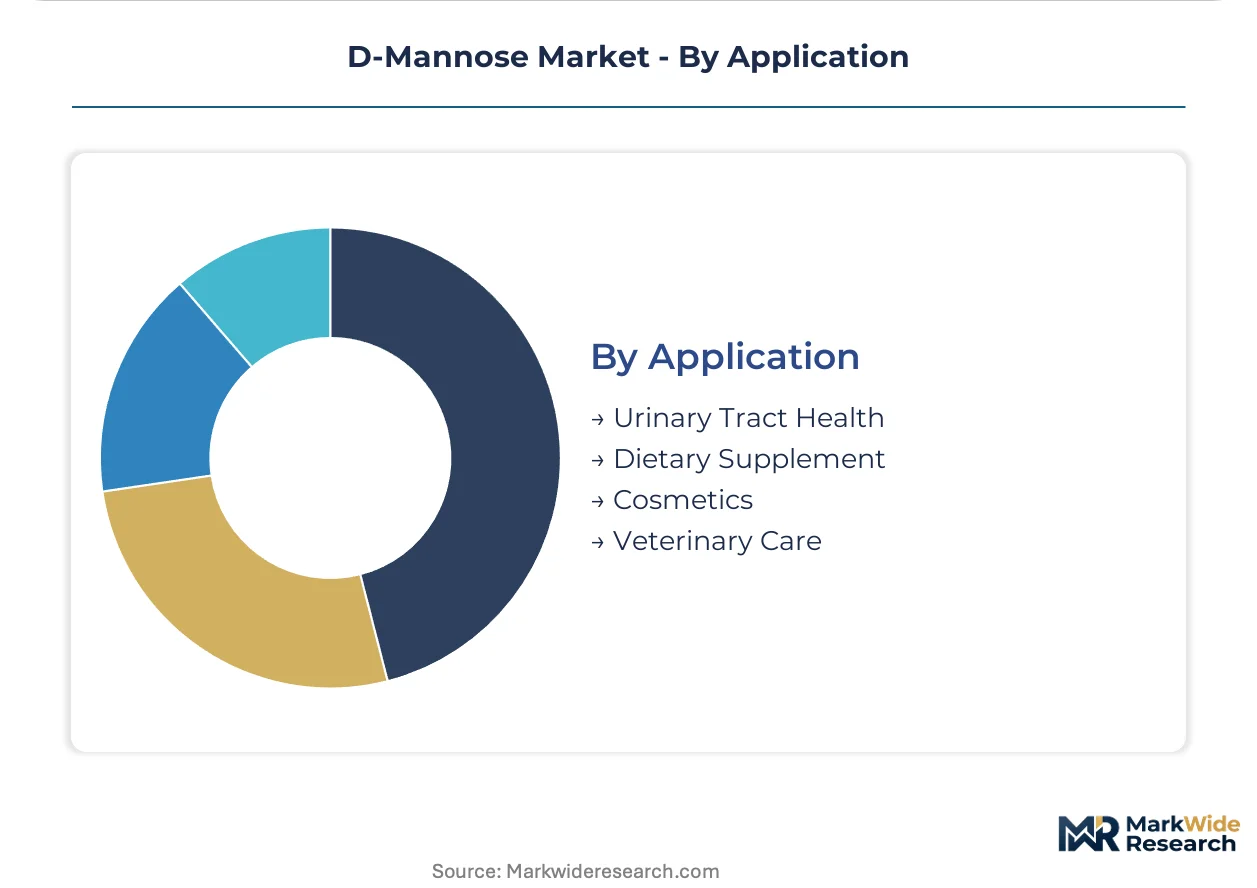
- Urinary Tract Health:Bacterial anti-adhesion therapy for Escherichia coli prevention represents the primary commercial purpose, spanning preventive nutraceutical positioning to medical food categories in European markets.
- Veterinary Care:Companion animal urology represents underpenetrated white space, with compounding pharmacies seeking flexible canine and feline dosing formats.
- Dietary Supplement:General wellness positioning requires navigation of EFSA Novel Food classifications in Europe and FDA structure-function claim frameworks in the United States.
- Cosmetics:Topical formulations leverage humectant properties in premium skincare, though clinical substantiation remains limited.
Urinary tract health dominates current volumes; veterinary care applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for D-mannose outpaces German procurement volumes by a factor of three, while Chinese fermentation-grade output supplies over half of pharmaceutical-grade crystallization capacity worldwide.
United States
Direct-to-consumer online channels and integrative medicine clinics in California and New York metropolitan areas drive volume concentration. FDA dietary supplement CGMP regulations mandate identity testing for imported raw materials, advantaging domestic producers with in-house analytical laboratories. NOW Health Group and Douglas Laboratories anchor finished goods manufacturing in the Northeast and West Coast corridors.
China
Three fermentation facilities in Shandong Province control the majority of pharmaceutical-grade crystallization capacity, creating single-point vulnerability for USP-grade procurement. NMPA pharmaceutical manufacturing standards and dual carbon goals are tightening environmental compliance costs for enzymatic glucose isomerization workflows. Zhengzhou-based suppliers are consolidating around higher-purity output tiers, constraining lower-grade feedstock availability.
Germany
EFSA Novel Food classification requirements delay market entry by 18-24 months versus US notification pathways, bifurcating product lines into food supplement and medical food categories. REACH compliance and residual solvent limit harmonization discussions with USP standards shape multi-territory formulation strategies. Bavarian distributors serve as the primary entry point for Central European compounding pharmacies.
United Kingdom
Telehealth platforms and subscription replenishment models exhibit accelerating penetration in London and Southeast England patient cohorts. MHRA border controls post-Brexit impose additional analytical documentation requirements on USP-grade imports. Midlands-based nutraceutical formulators source concentrated powder formats for custom urinary tract protocols.
Japan
PMDA pharmaceutical-grade specifications and JIS quality standards govern import acceptance for drug-device combination trials in urology applications. METI industrial policy supports domestic fermentation capacity expansion to reduce reliance on Chinese crystallization output. Osaka-area pharmaceutical companies are advancing catheter coating formulations requiring injectable USP-NF grade material.
D-Mannose Market Vendor Landscape
Chinese producers anchor the fermentation-grade supply tier; North American specialists hold finished formulation and distribution capabilities. Market structure concentrates around three to five crystallization facilities supplying downstream encapsulators and tablet manufacturers. Strategic archetypes include vertically integrated nutraceutical houses, clinician-only distribution specialists, and USP-grade raw material crystallizers. Dominant competitive moves encompass backward integration into raw material sourcing and third-party potency certification programs.
Among North American finished goods manufacturers, NOW Health Group, Inc. exemplifies the vertically integrated archetype spanning raw material procurement to capsule packaging, while Douglas Laboratories occupies the clinician-only distribution tier with third-party certification positioning. Pfanstiehl Inc represents the USP-grade crystallization specialist archetype, anchoring pharmaceutical-grade supply for drug-device combination developers. These three entities illustrate the geographic and functional segmentation defining competitive positioning in D-mannose value chains.
| Leading Market Players |
|---|
| Nestle Health Science |
| NOW Health Group, Inc. |
| Pfanstiehl Inc |
| DuPont de Nemours, Inc. |
| Vibrant Health |
| Douglas Laboratories |
| Sweet Cures |
| Hanseler AG |
| Bio-Tech Pharmacal |
| Others |
Supply Flow & Price Mechanics
Family-owned Chinese fermentation specialists anchor pharmaceutical-grade crystallization capacity, constraining lower-purity feedstock availability while enforcing disciplined pricing tiers across export markets. Their consolidation around USP-NF specifications tightens supply elasticity, forcing North American nutraceutical formulators to absorb input cost premiums or seek alternative sourcing corridors.
Pricing Analysis
Capacity additions in Shandong Province are reshaping price floors for enzymatic glucose-isomerized D-mannose, compressing margins on natural-source larch extraction alternatives. Three-tier pricing structure across USP-NF pharmaceutical grade, food-grade nutraceutical tier, and feed-grade industrial tier reflects certification investment differentials. Pricing pressure stems from FDA CGMP identity testing mandates advantaging domestic producers with in-house analytical laboratories. Veterinary formulators and compounding pharmacies exhibit highest price sensitivity, while pharmaceutical companies pursuing drug-device combinations demonstrate lowest elasticity due to reimbursement pathway requirements.
Supply Chain Analysis
Larch hemicellulose supply rests on North American forestry harvest cycles, while enzymatic production draws from corn-derived glucose feedstocks concentrated in Midwest agricultural processing corridors. Pharmaceutical-grade crystallization capacity concentrates in China, with secondary fermentation hubs emerging under METI industrial policy support in Japan. Single-source vulnerability pervades the Shandong facility cluster controlling majority USP-grade output. Distribution runs through direct-to-consumer telehealth platforms, integrative medicine clinic aggregators, and traditional retail pharmacy networks with divergent compliance documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FDA notification pathways enabling rapid US entry and EFSA Novel Food classification delays extending European market access timelines by 18-24 months.
For Market Incumbents:Acquire in-house analytical laboratory capabilities to defend against FDA CGMP identity testing mandates tightening procurement standards for imported raw materials. Secure backward integration into glucose isomerization feedstock supply or captive larch hemicellulose extraction partnerships to buffer against Chinese pharmaceutical-grade capacity consolidation. Certification investment in USP-NF monograph compliance represents the critical defensive lever against emerging North American mid-scale entrants adopting continuous chromatography purification.
For New Entrants and Emerging Players:Enter via veterinary formulation white space in companion animal urology, where concentrated powder demand from compounding pharmacies outpaces dedicated supplier development. Target subscription-based replenishment channels serving recurrent urinary tract management consumers in California and New York metropolitan telehealth platforms. Position around simulated moving bed continuous chromatography technology to achieve USP-grade purity without crystallization scale requirements incumbent Chinese producers command.
For Investors and Strategic Acquirers:Valuations sit cheapest among mid-scale North American producers with analytical certification capabilities but limited finished formulation distribution reach. Five-to-ten year viability hinges on pharmacopeial harmonization between USP, EP, and JP residual solvent standards streamlining multi-territory pharmaceutical client strategies. Monitor EFSA evidentiary threshold tightening for bacterial anti-adhesion label claims as the signal indicating European regulatory pathway hardening or liberalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock Supply | Corn processor partnerships in Midwest corridors reduce exposure to Chinese pharmaceutical-grade crystallization concentration. |
| Continuous Chromatography Technology Adoption | Simulated moving bed systems enable USP-NF purity achievement without centralized fermentation scale requirements. |
| Veterinary Formulation Line Extension | Companion animal urology protocols in North American compounding pharmacies represent underpenetrated demand concentration. |
| Third-Party Potency Certification Investment | USP-NF monograph compliance documentation satisfies FDA CGMP identity testing mandates for direct-to-consumer channels. |
| Pharmacopeial Harmonization Lobbying | Convergence advocacy between USP, EP, and JP standards streamlines multinational pharmaceutical client formulation strategies. |
Methodological Framework
Bottom-up end-user modeling reconciled against top-down fermentation-grade capacity tracking forms the analytical core of this study. Primary interviews with nutraceutical formulation executives, veterinary compounding pharmacists, FDA regulatory affairs consultants, and urology device procurement managers were validated against secondary sources including FDA dietary supplement CGMP guidance documents, USP-NF monograph standards, EFSA Novel Food classification databases, and NMPA pharmaceutical manufacturing compliance records. Triangulation between demand-side prescription protocol adoption and supply-side crystallization facility utilization rates ensures dimensional consistency.
Historical trendline analysis of bacterial anti-adhesion therapy positioning across nutraceutical, medical food, and pharmaceutical categories informed segmentation-specific trajectory assumptions. Modeled dimensions span product type, purity grade tier, end-user regulatory sophistication, distribution channel compliance requirements, and geographic regulatory cluster. CAGRs were derived from fitted growth curves reconciled against capacity expansion announcements and patent filing patterns in urology device coating applications. Forecast inputs incorporate EFSA evidentiary threshold evolution and METI domestic fermentation capacity subsidy disbursements.
Inputs from primary fieldwork and disclosed regulatory filings were available through the study window; gaps in real-time Chinese fermentation facility utilization data introduce uncertainty bands around pharmaceutical-grade supply forecasts. Projections reflect assumptions regarding pharmacopeial harmonization progress and FDA enforcement intensity on imported raw material identity testing. A small set of named triggers—EFSA label claim rulings, Shandong facility environmental compliance actions, and PMDA drug-device combination trial approvals—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Trehalose Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Citrus Molasses Market
Sweeteners
Australia Allulose Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Erythritol Market
Sweeteners
India Cane Sugar Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Rare Sugar Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Sanding Sugar Market
Sweeteners
Natural Sweetener Blends Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
United Kingdom Food Sweetener Market