
 Dextrates Market | 2026-2036
Dextrates Market Size, Share, and Industry Trends Forecast 2026-2036
Dextrates Market Analysis
European starch derivative producers is broadening dextrate capacity to serve pharmaceutical-grade contracts. Roquette Frères leverages its Lestrem facility network to sustain multi-regional supply of purified dextrose excipients. Tate & Lyle PLC anchors North American distribution through specialized nutrition and pharma channel partnerships. Ingredion Incorporated competes on modified starch R&D intensity, positioning its portfolio for high-functionality binder applications.
Dextrates comprise enzymatically processed starch hydrolysates with dextrose equivalency values typically ranging from 4 to 20, functioning primarily as fillers, binders, and dissolution modifiers in oral dosage forms. Maltodextrin dominates volume due to its cost-efficiency across food and pharmaceutical applications, while cyclodextrin commands premium positioning in complexation technologies for poorly soluble APIs. Powder form leads pharmaceutical procurement because of flowability and compressibility advantages in direct compression tableting.
FDA excipient guidelines and EMA quality requirements shape supplier qualification protocols, forcing raw material traceability investments upstream. ISO 22000 and pharmaceutical GMP standards further filter market access for non-certified producers. Stakeholders must monitor evolving USP-NF monograph revisions and regional excipient master file submission requirements to secure long-term supply contracts.
Market Dynamics
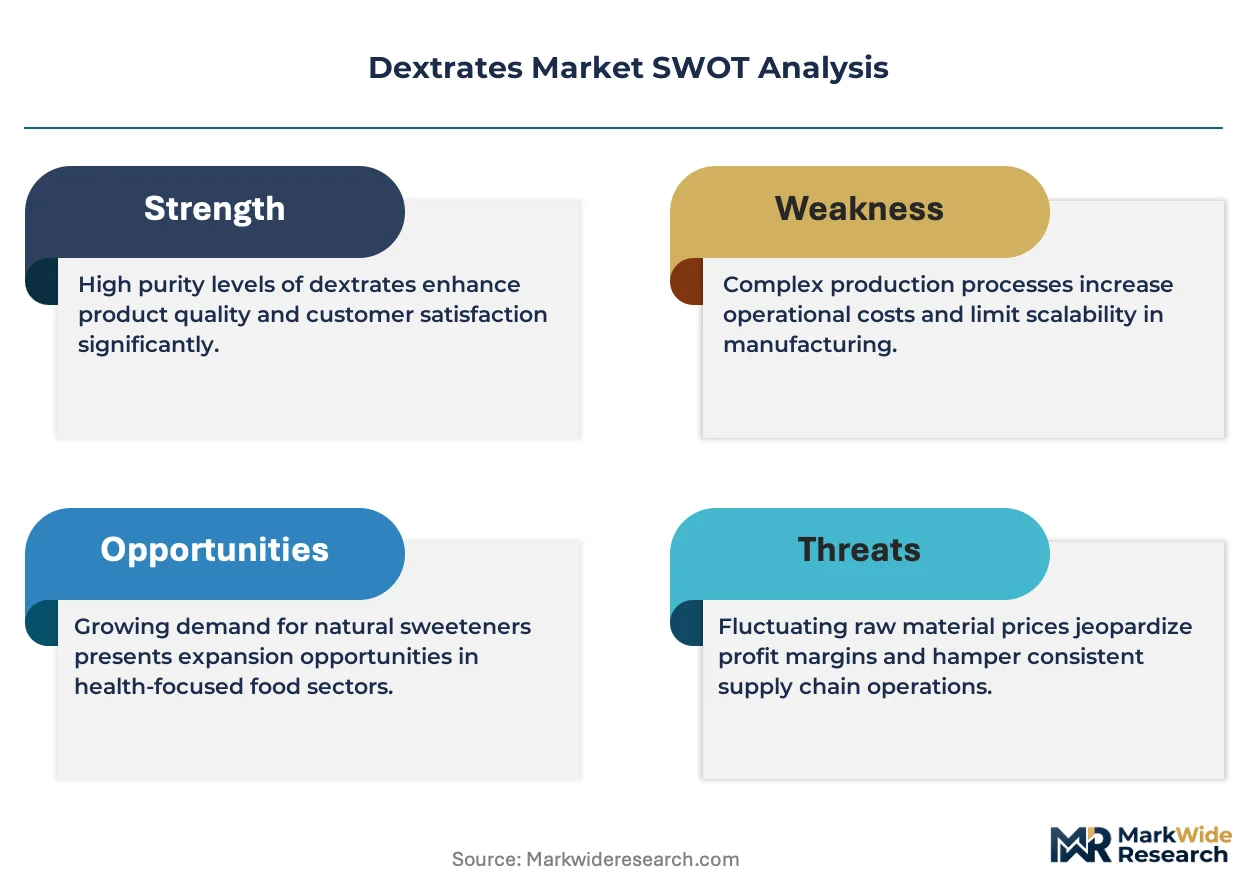
Oral solid dosage manufacturing expansion is compressing excipient qualification timelines while FDA and EMA tighten traceability mandates, forcing starch derivative suppliers to reconfigure upstream certification protocols.
Growth Catalysts
- EMA excipient master file harmonization:Streamlined submission pathways accelerate supplier onboarding for contract manufacturers across Germany, France, and Italy.
- Generic drug volume concentration:High-volume tablet production in the United States and India pulls demand for cost-optimized binder grades.
- Enzymatic hydrolysis process refinement:Improved dextrose equivalency control expands functionality in controlled-release formulations.
Market Restraints
- Corn starch feedstock volatility:Agricultural commodity price swings compress margin predictability for North American producers.
- Pharmaceutical-grade purification capex:Multi-stage filtration and ion-exchange systems require capital intensity that filters mid-scale entrants.
- Cyclodextrin substitution pressure:Complexation performance advantages in poorly soluble APIs displace standard dextrate grades in premium applications.
Strategic Opportunities
- Indian CDMO expansion:Contract development and manufacturing organization growth in Hyderabad and Ahmedabad creates unmet excipient demand.
- Continuous manufacturing compatibility:Direct compression-optimized dextrate flow properties align with FDA-promoted advanced manufacturing transitions.
- Biologics excipient diversification:Lyophilization stabilizer applications open adjacent demand beyond traditional oral dosage.
Industry Challenges
- USP-NF monograph revision lag:Pending updates to dextrate specifications create formulation uncertainty during multi-year product development cycles.
- Cross-functional talent scarcity:Combined pharmaceutical GMP and food-grade HACCP expertise remains concentrated among senior specialists at established suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dextrates Market |
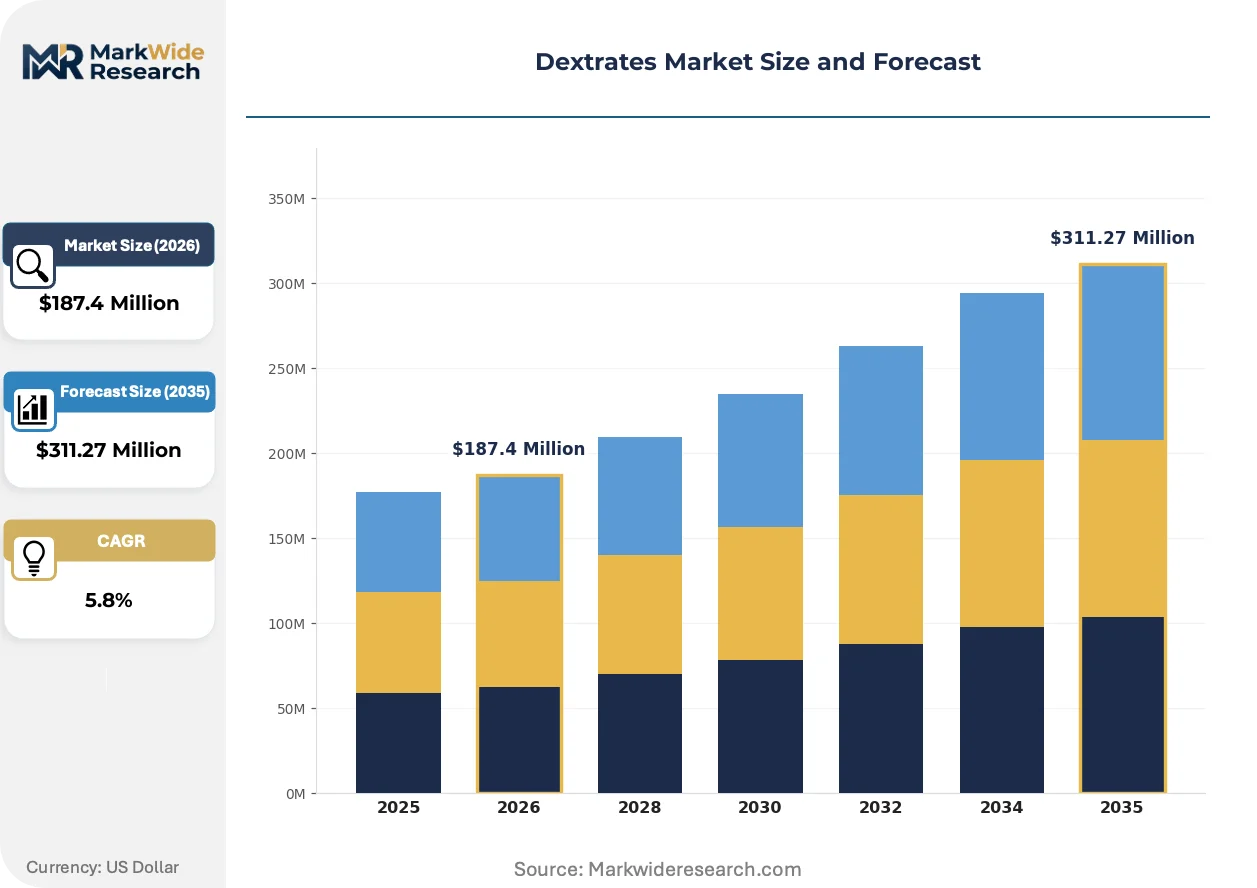
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dextrose, Maltodextrin, Cyclodextrin, Other Dextrates Application: Food & Beverages, Pharmaceuticals, Personal Care, Industrial Applications End User: Food Manufacturers, Drug Companies, Cosmetic Brands, Industrial Manufacturers Form: Powder, Liquid, Granular, Crystalline |
| Companies Covered | Roquette Frères, Tereos, Archer Daniels Midland Company, Fooding Group Limited, Gulshan Polyols Ltd, Cargill, Tate & Lyle PLC, Singsino Group Ltd, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dextrates Market Emerging Trajectories
Excipient functionality is diverging along performance-tier lines as direct compression tableting accelerates and regulatory traceability requirements harden. Three forces are restructuring supplier-buyer relationships.
Granulation-grade dextrate with enhanced compressibility is electrifying high-speed tablet press operations at North American generic manufacturers. Formulation teams at large-scale CDMOs adopt these grades to eliminate wet granulation steps. The technology is electrifying capital efficiency benchmarks across oral solid dosage lines.
REACH substance registration deadlines for starch derivatives are compressing supplier documentation investments. ECHA compliance costs filter non-EU producers from European pharmaceutical contracts. German and French formulators now require REACH-registered excipient grades for all new product filings.
Buyer consolidation among top-tier generics manufacturers is concentrating procurement leverage. Long-term supply agreements with volume-tier pricing are displacing spot-market transactions. This pattern is most visible in United States contract manufacturing, where three large CDMOs now control majority excipient procurement decisions.
Dextrates Market Segmentation
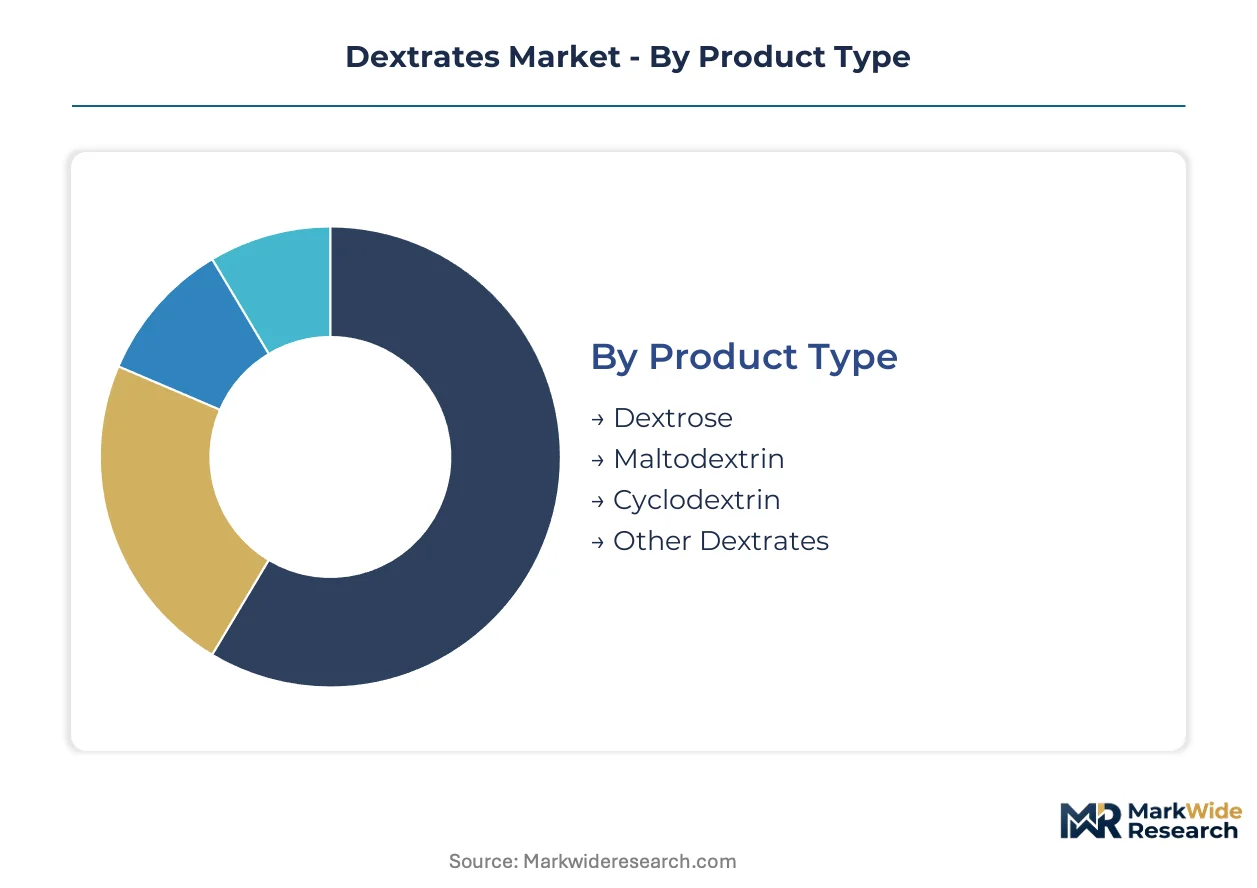
Dextrate grade selection hinges on functional requirements across formulation science, with pharmaceutical binders demanding tighter dextrose equivalency control than food-grade fillers. Procurement patterns diverge sharply by end-use certification tier, creating distinct supply channels for USP-NF monograph grades versus industrial hydrolysates.
Product Type:
Upgrade cycles in excipient functionality favor hydrolysates with refined molecular weight distribution and lower reducing sugar content.
- Maltodextrin:Enzymatically hydrolyzed starch with dextrose equivalency of 4-20 serves as the workhorse filler across high-volume oral solid dosage manufacturing. Demand concentrates in United States generic tablet production where cost-optimized binder grades compress per-unit formulation expenses.
- Cyclodextrin:Cyclic oligosaccharide structures enable molecular encapsulation of poorly soluble APIs through host-guest complexation. German and Swiss formulators lead procurement for this premium grade, driven by EMA quality requirements for bioavailability enhancement in specialty generics.
- Dextrose:Monosaccharide excipient provides rapid dissolution and sweetness masking in chewable tablet matrices.
- Other Dextrates:Specialty hydrolysates include pyrodextrins and acid-modified variants for controlled-release applications.
Volume placements concentrate in Maltodextrin; the faster expansion belongs to Cyclodextrin.
Application:
Cost tier stratification separates pharmaceutical-grade certification investments from commodity food and industrial segments.
- Pharmaceuticals:USP-NF and EP-compliant dextrates function as tablet binders, diluents, and dissolution modifiers with mandatory raw material traceability. United States contract manufacturers and Indian CDMOs in Hyderabad drive procurement scale for direct-compression compatible grades.
- Food & Beverages:Spray-dried maltodextrins serve as fat replacers, bulking agents, and encapsulation matrices in flavor systems. European starch derivative producers anchor supply through specialized nutrition channel partnerships.
- Personal Care:Dextrate film-formers and humectants appear in topical delivery systems and cosmetic powder bases.
- Industrial Applications:Non-certified hydrolysates enter adhesive formulations, paper sizing, and fermentation feedstocks.
Revenue margins peak in Pharmaceuticals; Food & Beverages sustains the highest absolute tonnage.
End User:
Customer type determines procurement leverage, with consolidated drug companies extracting volume-tier pricing unavailable to fragmented cosmetic brands.
- Drug Companies:Large-scale pharmaceutical manufacturers and CDMOs qualify dextrate suppliers through multi-year excipient master file submissions. FDA and EMA traceability mandates force upstream certification investments that filter mid-scale starch derivative producers.
- Food Manufacturers:Beverage and confectionery processors procure food-grade maltodextrin through spot-market and annual contract mechanisms. Roquette Frères and Tate & Lyle PLC sustain multi-regional supply networks for this segment.
- Cosmetic Brands:Premium skincare formulators specify low-reducing sugar dextrates for hygroscopic stability in powder products.
- Industrial Manufacturers:Adhesive and paper chemical producers absorb lower-purity hydrolysate grades with minimal certification overhead.
Contract concentration is tightest among Drug Companies; Cosmetic Brands generate the most fragmented demand pattern.
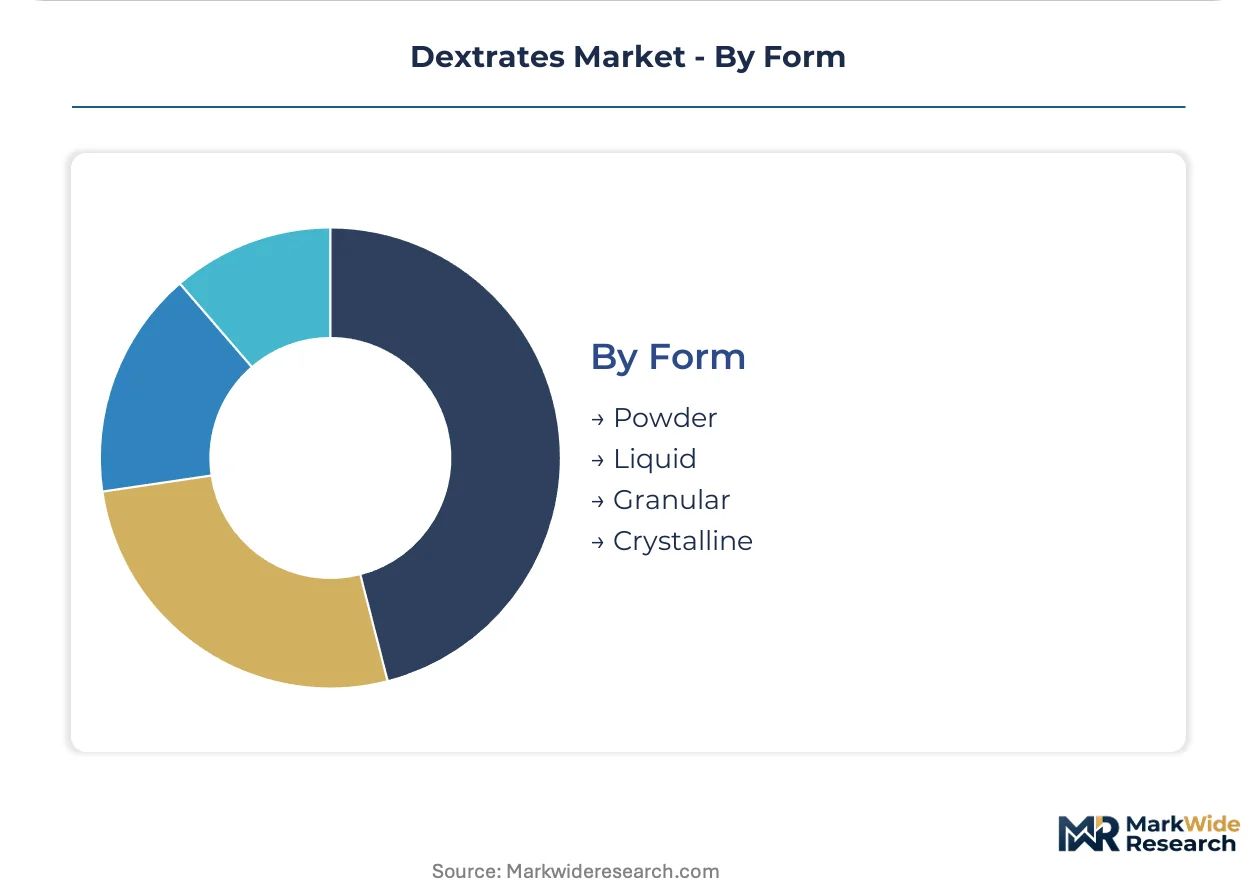
Form:
Physical state selection follows processing equipment compatibility, with powder dominance in high-speed tableting operations.
- Powder:Spray-dried and agglomerated dextrate powders deliver flowability and compressibility essential for direct compression manufacturing. United States generic manufacturers and German tablet producers standardize procurement on this form to eliminate wet granulation steps.
- Granular:Agglomerated particles reduce dust generation and improve handling in continuous manufacturing lines. Indian CDMOs expanding in Ahmedabad adopt granular grades for FDA-promoted advanced manufacturing transitions.
- Liquid:Aqueous dextrate syrups serve wet granulation processes and liquid dosage formulations.
- Crystalline:High-purity dextrose crystals target parenteral and specialty applications with stringent endotoxin limits.
Procurement volume centers on Powder; Granular forms are climbing the fastest on continuous manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn starch feedstock availability and pharmaceutical manufacturing density dictate regional demand patterns. FDA and EMA traceability mandates compress supplier qualification timelines in established markets. Emerging production clusters in India and Southeast Asia absorb technology transfer from European starch derivative specialists.
United States
Generic drug contract manufacturers in New Jersey and North Carolina drive bulk procurement of direct-compression grade maltodextrin. FDA excipient master file submission requirements filter non-certified suppliers from pharmaceutical contracts. Philadelphia-area CDMOs are expanding high-speed tableting lines that demand flowability-optimized dextrate powders.
Germany
Specialty generics formulators in Baden-Württemberg command premium cyclodextrin grades for bioavailability enhancement. EMA quality guidelines and REACH substance registration deadlines compress documentation investments for starch derivative suppliers. The Frankfurt-Rhine-Main pharmaceutical cluster sustains multi-regional distribution of pharmaceutical-grade hydrolysates.
India
Hyderabad and Ahmedabad CDMOs are scaling oral solid dosage manufacturing for export markets, pulling demand for USP-NF compliant binders. CDSCO excipient quality notifications align with FDA import alert protocols for raw material traceability. Gujarat-based starch processors are upgrading purification capacity to serve pharmaceutical-grade contracts.
China
Domestic generic manufacturers in Jiangsu and Zhejiang provinces absorb modified starch hydrolysates for tablet production. NMPA pharmaceutical excipient registration requirements tighten supplier documentation for imported dextrate grades. The Yangtze River Delta chemical cluster hosts enzymatic hydrolysis facilities serving both food and pharmaceutical channels.
Switzerland
Specialty pharmaceutical formulators around Basel procure high-purity cyclodextrin for complexation technologies. Swissmedic quality requirements exceed standard EP monographs, filtering supplier pools to established European starch derivative producers. The Lake Geneva biotech corridor sustains demand for lyophilization-grade dextrose excipients.
Dextrates Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification as a differentiation vector. The vendor base stratifies across three capability levels: multi-regional starch specialists with integrated purification assets, regional hydrolysate processors serving food-grade contracts, and niche cyclodextrin specialists commanding premium positioning. Two dominant competitive moves define current dynamics: backward integration into corn wet milling to secure feedstock cost predictability, and strategic partnerships with CDMOs to lock in multi-year excipient supply agreements.
Among European starch derivative specialists, Roquette Frères and Tate & Lyle PLC exemplify the integrated multi-regional archetype. Roquette Frères represents the vertically integrated model with captive agricultural processing and pharmaceutical-grade purification capabilities. Tate & Lyle PLC occupies a position emphasizing specialized nutrition and pharmaceutical channel partnerships over commodity food-grade volume. Ingredion Incorporated anchors the North American competitive structure as a modified starch R&D-intensive operator positioning for high-functionality binder applications.
| Leading Market Players |
|---|
| Roquette Frères |
| Tereos |
| Archer Daniels Midland Company |
| Fooding Group Limited |
| Gulshan Polyols Ltd |
| Cargill |
| Tate & Lyle PLC |
| Singsino Group Ltd |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
REACH substance registration deadlines for starch derivatives gate qualified supply and premium-tier pricing access, filtering non-EU producers from European pharmaceutical contracts while concentrating procurement leverage among REACH-registered suppliers serving German and French formulators.
Pricing Analysis
Technical documentation and excipient master file submission services are bundled into pharmaceutical-grade dextrate contracts, while food-grade maltodextrin transactions remain unbundled and spot-driven. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates USP-NF certified binders from standard hydrolysates and non-certified variants. Cost compression in food-grade tiers is intensifying because Indian and Chinese starch processors are expanding enzymatic hydrolysis capacity. Generic drug manufacturers in the United States exhibit the highest price sensitivity, while Swiss specialty formulators show minimal elasticity for cyclodextrin complexation grades.
Supply Chain Analysis
Specialized pharmaceutical GMP technicians and quality assurance specialists concentrate in Germany, Switzerland, and the United States, constraining rapid capacity scaling for purified dextrate production. Corn wet milling capacity centers on the United States and China, while enzymatic hydrolysis specialization clusters in France and Germany. Supply chains draw from corn starch, ion-exchange resins, and pharmaceutical-grade filtration membranes. Single-source vulnerability runs through European cyclodextrin purification assets. Distribution runs through long-term supply agreements with volume-tier pricing rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dextrates market is becoming a vertical-integration race as producers pursue captive corn wet milling assets to neutralize agricultural commodity volatility and secure margin predictability.
For Market Incumbents: Acquire corn wet milling facilities in the United States Corn Belt to lock in feedstock cost structures. Secure multi-year excipient master file partnerships with top-tier CDMOs in New Jersey and North Carolina before cyclodextrin substitution accelerates in poorly soluble API applications. Expand pharmaceutical-grade purification capacity at existing European sites to exploit REACH registration barriers. For New Entrants and Emerging Players: Enzymatic hydrolysis process control technology offers entry into the granular dextrate segment serving Indian CDMOs adopting continuous manufacturing. Target Hyderabad and Ahmedabad contract manufacturers with USP-NF compliant binder grades for export-market tablet production. Lead with direct compression compatibility certifications rather than commodity maltodextrin volume plays. For Investors and Strategic Acquirers: CDSCO excipient quality notification alignment with FDA import alert protocols is the leading indicator that Indian pharmaceutical-grade dextrate demand will consolidate around certified domestic suppliers. Over a multi-year horizon, vertically integrated starch processors with pharmaceutical purification assets represent the most defensible acquisition profile. Watch for NMPA registration requirement tightening in China as a signal of regional supply rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet Milling | Captive starch supply from Iowa and Illinois processing plants neutralizes commodity price volatility. |
| Pharmaceutical-Grade Purification Capacity Expansion | Multi-stage filtration and ion-exchange systems at Lestrem facilities meet EMA traceability mandates. |
| Excipient Master File Harmonization Investment | Streamlined FDA and EMA submission pathways accelerate supplier onboarding for contract manufacturers. |
| Continuous Manufacturing Compatibility Certification | Flowability-optimized granular grades align with FDA-promoted advanced manufacturing transitions. |
| Long-term Supply Agreement with CDMOs | Volume-tier pricing contracts with New Jersey and North Carolina manufacturers displace spot-market transactions. |
Methodological Framework
Multi-period observation of enzymatic hydrolysis capacity additions, excipient master file submission volumes, and CDMO procurement patterns anchored the trend analysis, supplemented by interviews with plant managers at starch derivative facilities, procurement leads at pharmaceutical contract manufacturers, regulatory affairs specialists, and distribution channel partners. Secondary validation drew from FDA excipient filings, EMA quality guideline revisions, USP-NF monograph updates, and customs trade data for starch hydrolysates. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level estimates.
Segment-weighting across product type, application tier, end-user category, and physical form dimensions structured the analytical framework. CAGRs were derived from regression analysis of historical pharmaceutical excipient demand against oral solid dosage production indices, with cross-validation against corn starch feedstock cost trajectories and regulatory compliance cost escalations. The modeling period spans the full projection horizon without year-specific anchors.
Several conditions sit outside the modeled scope, including abrupt corn commodity price shocks, sudden USP-NF monograph revision timelines, and geopolitical trade restrictions on starch derivative flows. Forecasts reflect documented assumptions about CDMO expansion rates and regulatory harmonization progress. Material deviation in FDA import alert protocols or EMA excipient master file processing timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Fructose Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
High-Fructose Corn Syrup (HFCS) Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
India Cane Sugar Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Xylitol Injection Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Maltitol Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Icing Sugar Market
Sweeteners
Sweeteners Market