
 Cassava Syrup Market | 2026-2036
Cassava Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Cassava Syrup Market Insights
Enzymatic hydrolysis efficiency is narrowing the cost gap between cassava syrup and conventional corn-based sweeteners across industrial-scale production. Cargill leverages its integrated tapioca supply chain in Southeast Asia to sustain bulk pricing advantages for beverage manufacturers. Ingredion anchors North American distribution through specialty starch expertise, while Tate & Lyle competes on formulation partnerships with confectionery clients seeking non-GMO alternatives.
Cassava syrup is a glucose-rich liquid sweetener derived from the enzymatic hydrolysis of cassava starch, typically containing 70-80% solids with dextrose equivalence ranging from 28 to 95 depending on hydrolysis depth; it functions primarily as a viscous sweetening agent, humectant, and browning facilitator in processed foods. Refined syrup dominates volume throughput due to its neutral flavor profile and compatibility with existing beverage manufacturing infrastructure, while organic syrup commands premium positioning as clean-label certification tightens across European retail channels. Bakery products represent the most mature application segment with established formulation protocols, whereas nutraceuticals emerge as the fastest-growing end-use industry as prebiotic fiber claims attach to resistant dextrin variants.
EMA food additive evaluations and REACH chemical safety registrations shape ingredient approval timelines for cassava syrup entering European food processing and personal care products. FDA GRAS self-affirmation pathways and USDA organic certification standards govern U.S. market access, with compliance costs favoring larger processors over regional importers. Stakeholders must monitor evolving EU Green Deal agricultural sourcing requirements and their potential to redirect cassava procurement toward certified sustainable cultivation zones.
Market Dynamics
Enzymatic hydrolysis efficiency gains are compressing production costs for cassava syrup manufacturers, eroding the historical price advantage held by corn-based sweeteners across beverage and bakery applications. This technological inflection is redrawing procurement patterns among industrial buyers.
Growth Catalysts
- REACH-compliant clean-label mandates:European food processors face regulatory pressure to eliminate artificial sweeteners from bakery and confectionery formulations, creating direct substitution demand for cassava-derived alternatives.
- Prebiotic fiber positioning:Resistant dextrin variants derived from cassava starch are capturing nutraceutical applications as gut health claims gain traction in functional food segments.
- Nigeria-Thailand supply corridor maturation:Dedicated processing infrastructure in these origin markets is reducing raw material transit times for European and North American importers.
Market Restraints
- Root crop price volatility:Cassava tuber costs fluctuate with Southeast Asian monsoon patterns and Nigerian agricultural labor availability, squeezing processor margins unpredictably.
- Single-origin concentration risk:Thailand dominates refined syrup export capacity; geopolitical or climate disruptions to this corridor would cascade through global beverage manufacturer supply chains.
- Enzyme cost structure:Specialized amylase and glucoamylase inputs for hydrolysis remain import-dependent for African processors, limiting local cost competitiveness.
Strategic Opportunities
- EU Green Deal agricultural sourcing requirements:Certified sustainable cultivation zones in Nigeria and Thailand stand to capture preferential procurement contracts from European food manufacturers.
- Organic certification tier:Premium positioning for certified-organic syrup remains underdeveloped relative to conventional corn and cane alternatives, offering first-mover yield potential.
- Resistant dextrin-nutraceutical convergence:Fiber-enriched syrup variants can penetrate dietary supplement channels currently served by isolated maltodextrin suppliers.
Industry Challenges
- Specialized enzyme procurement expertise:Optimizing hydrolysis depth for specific dextrose equivalence targets requires biochemical engineering talent scarce in emerging origin markets.
- USDA organic certification timelines:Three-year transition periods for conventional cassava farms impose working capital burdens on suppliers targeting North American premium segments.
- Legacy beverage formulation recalibration:Replacing high-fructose corn syrup with cassava-derived alternatives demands viscosity and browning profile adjustments that slow manufacturer adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cassava Syrup Market |
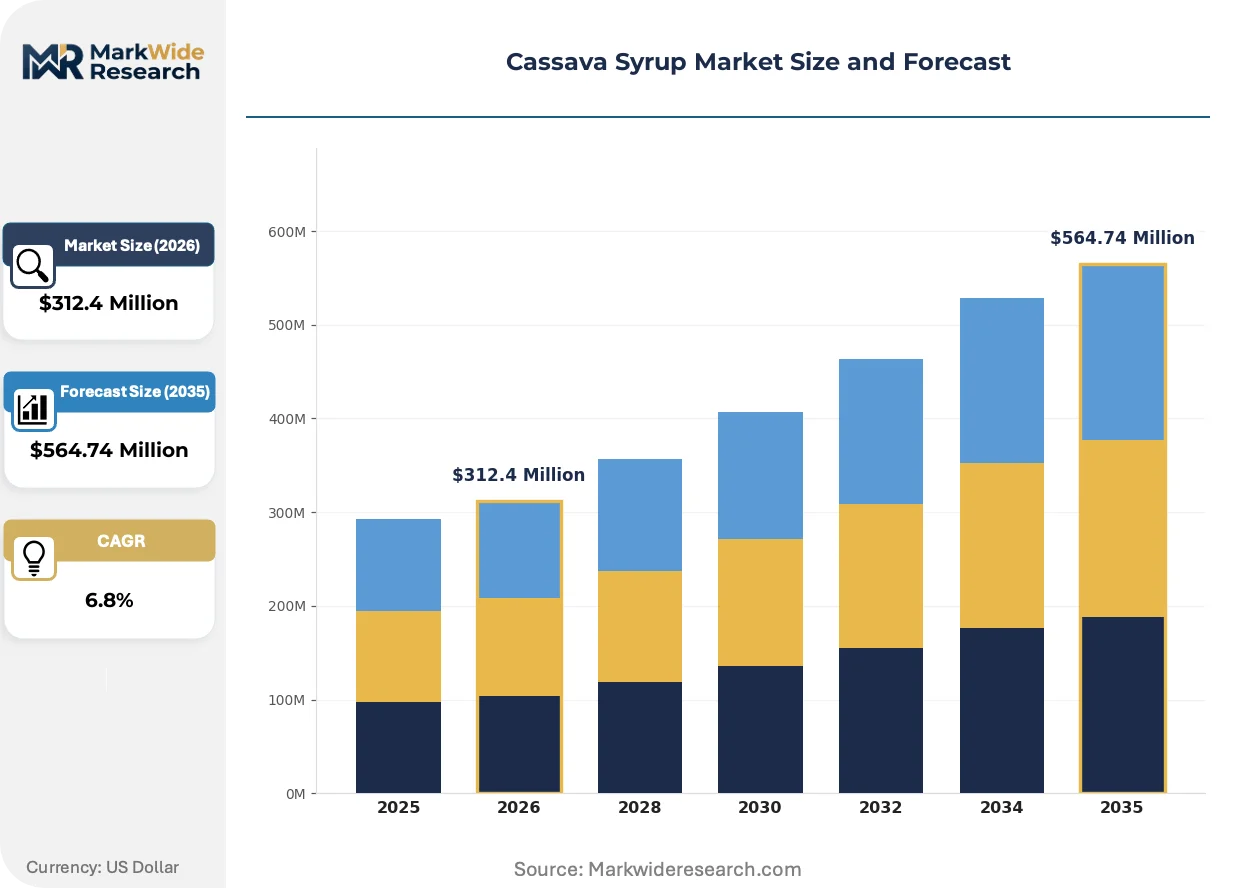
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Syrup, Organic Syrup, Flavored Syrup, Concentrated Syrup, Grade A Syrup Application: Bakery Products, Beverage Sweetener, Confectionery, Dairy Products, Snack Foods End Use Industry: Food Processing, Beverage Manufacturing, Nutraceuticals, Personal Care Products, Pharmaceuticals Packaging Type: Plastic Bottles, Glass Jars, Pouches, Tins, Bulk Containers |
| Companies Covered | Cargill, Ingredion, Tate & Lyle, Ciranda, Sweetener Products Company, Madhava Natural Sweeteners, Thai German Processing, Psaltry International, Sanstar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cassava Syrup Market Trends and Innovations
Process control technologies and regulatory compliance frameworks are converging to reshape how cassava syrup is manufactured, certified, and procured across food and nutraceutical value chains.
Sensor-integrated hydrolysis monitoring is digitizing quality consistency in Thai and Nigerian processing facilities. Beverage manufacturers adopting these systems report reduced batch-to-batch viscosity variation. This standardization is digitizing the contract terms between origin processors and multinational buyers, compressing quality dispute resolution cycles.
EMA food additive evaluations and REACH chemical safety registrations are tightening ingredient approval timelines for cassava syrup entering European personal care and pharmaceutical applications. Manufacturers must now submit toxicological dossiers earlier in product development pipelines. Bakery and confectionery segments in Germany and France are responding by pre-qualifying suppliers with existing EFSA positive opinions.
Direct-procurement relationships between food manufacturers and origin-country processors are displacing traditional trader intermediaries in bulk syrup transactions. Large bakery and beverage producers are establishing volume commitments with Thai German Processing and comparable integrated suppliers. This disintermediation is most visible in German and Dutch industrial procurement, where cost transparency and supply traceability have become contractual priorities.
Cassava Syrup Market Segmentation
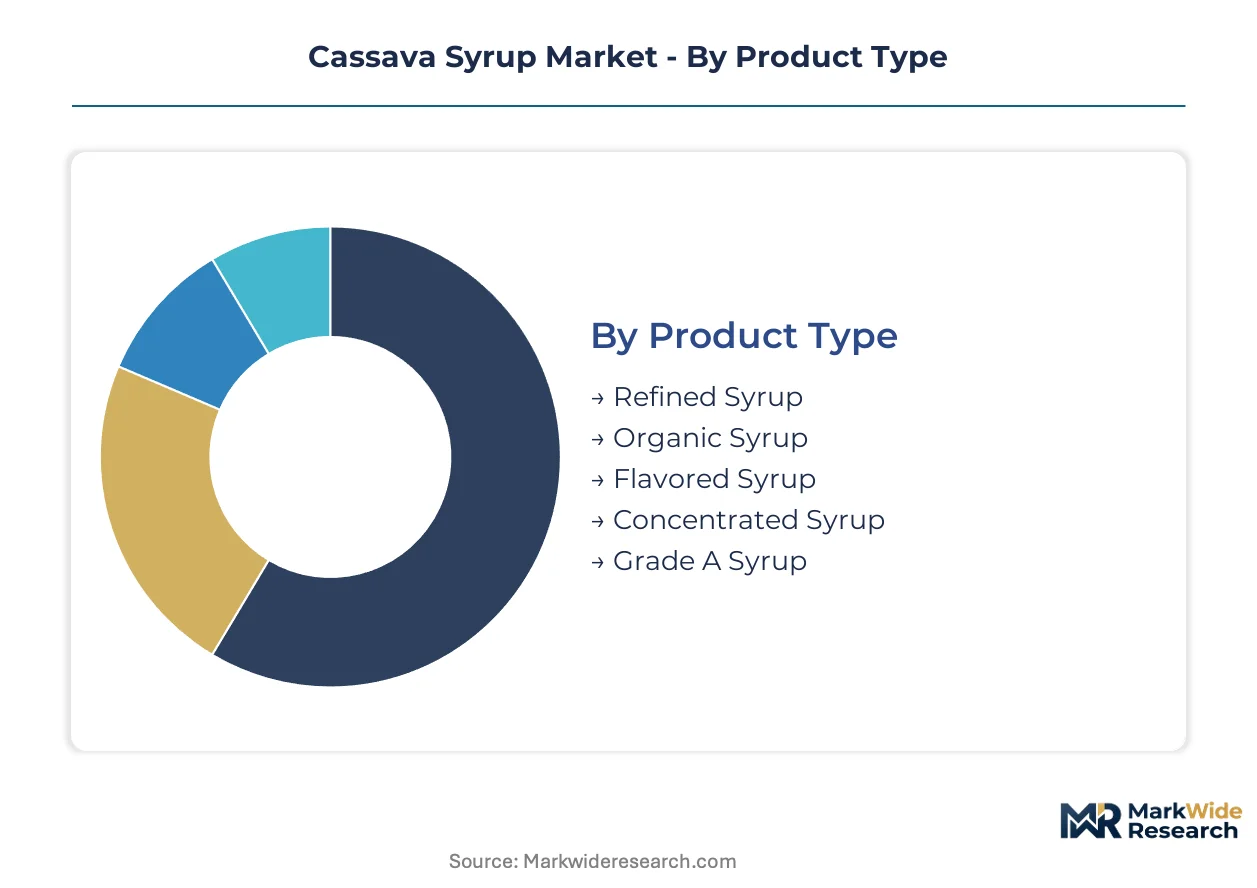
Cassava syrup segmentation reflects divergent processing depths and certification tiers that command distinct pricing premiums. Manufacturers calibrate enzymatic hydrolysis specifications to match end-use viscosity and browning requirements across food, beverage, and nutraceutical channels.
Product Type:
Mature refining infrastructure dominates industrial procurement, while emerging certification tiers capture clean-label premiums.
- Refined Syrup:Neutral-flavored glucose concentrate with 70-80% solids and dextrose equivalence ranging from 28 to 95. Beverage manufacturers in Germany and the Netherlands source this grade for high-volume formulation compatibility. REACH compliance documentation streamlines European import clearance.
- Organic Syrup:Certified cultivation with USDA organic or EU organic seals commanding 15-30% price premiums. North American retail channels and European clean-label bakery segments drive procurement concentration. Three-year farm transition timelines constrain supply elasticity.
- Flavored Syrup:Vanilla and caramel-infused variants targeting specialty coffee and dessert applications.
- Concentrated Syrup:Reduced-moisture format for long-haul export efficiency to European processors.
- Grade A Syrup:Premium clarity specification for pharmaceutical and personal care excipient applications.
Refined syrup retains volume leadership; organic syrup holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity-scale industrial sweetening from formulation-intensive specialty segments.
- Bakery Products:Humectant and browning agent functions in bread, cakes, and pastries. European manufacturers displace artificial sweeteners under EFSA-guided clean-label mandates. Established formulation protocols accelerate adoption timelines versus beverage reformulation.
- Beverage Sweetener:Viscosity-calibrated syrups for carbonated and still drinks. Thai German Processing anchors supply contracts with multinational bottlers seeking non-GMO alternatives to high-fructose corn syrup. Viscosity profile adjustments delay manufacturer switching cycles.
- Confectionery:Crystallization-controlled grades for hard candies and gummies.
- Dairy Products:Frozen dessert and yogurt sweetening with freeze-thaw stability requirements.
- Snack Foods:Coating and glaze applications in extruded and puffed products.
Bakery products anchor procurement volume; nutraceutical-adjacent confectionery applications are expanding most quickly.
End Use Industry:
Customer type fragmentation separates commodity food processors from premium-positioned nutraceutical and pharmaceutical buyers.
- Food Processing:Industrial-scale sweetening for packaged goods manufacturers. Nigerian and Thai origin processors compete on bulk pricing for European and North American importers. EMA food additive evaluations govern ingredient approval timelines.
- Nutraceuticals:Resistant dextrin variants with prebiotic fiber claims. Gut health positioning in dietary supplements drives fastest segment expansion. Formulation partnerships with functional food brands require specialized hydrolysis depth expertise.
- Beverage Manufacturing:High-volume procurement with strict batch-to-batch viscosity consistency requirements.
- Personal Care Products:Humectant applications in skincare and haircare formulations.
- Pharmaceuticals:Excipient-grade specifications for tablet binding and syrup bases.
Food processing commands absolute volume; nutraceuticals gain share fastest through functional positioning.
Packaging Type:
Volume scale determines packaging economics, with bulk formats dominating industrial procurement and retail-ready units serving specialty channels.
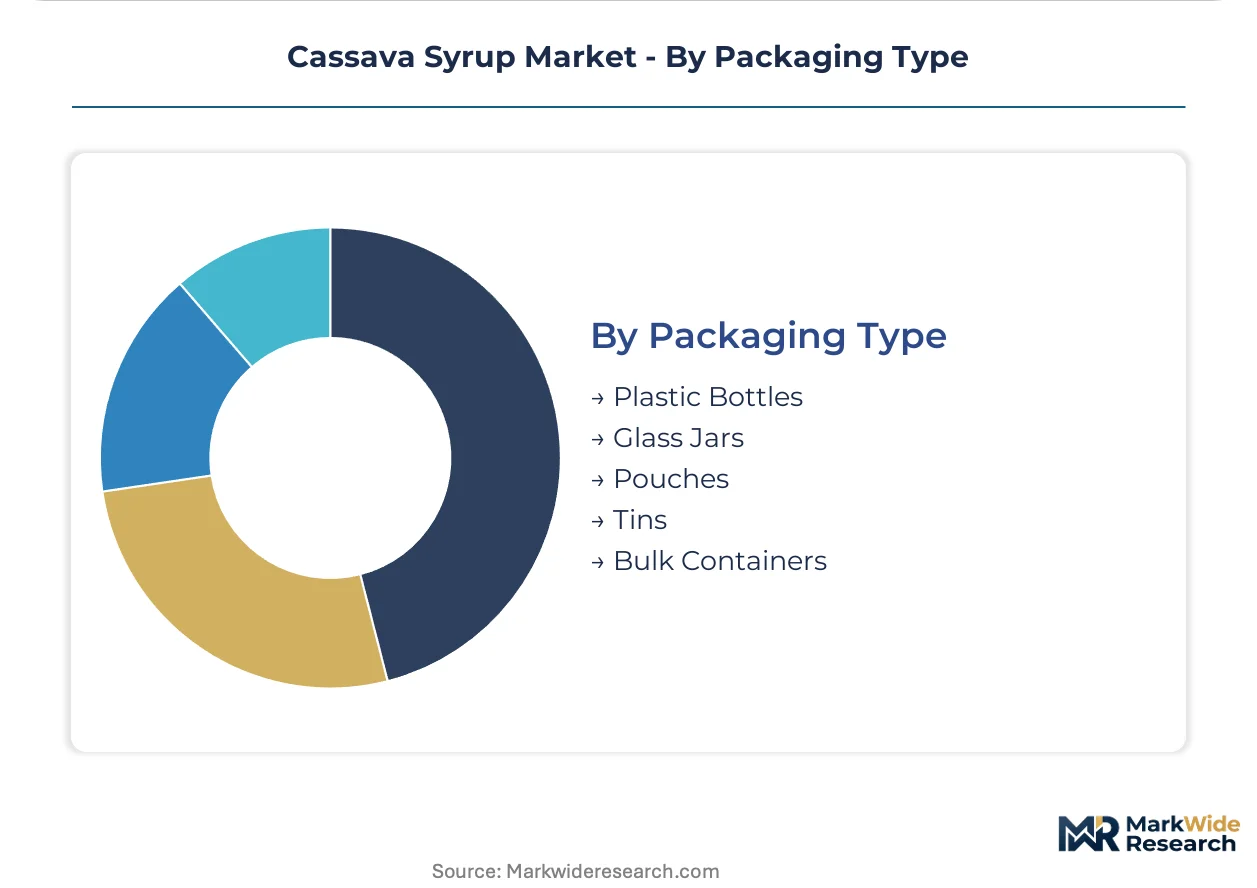
- Bulk Containers:Intermediate bulk containers and tanker shipments for beverage and bakery manufacturers. Direct-procurement relationships with Thai and Nigerian processors displace trader intermediaries. Cost transparency and supply traceability drive contractual terms.
- Plastic Bottles:Standard retail format for food service and small-scale food processors.
- Glass Jars:Premium positioning for organic and specialty syrups in European retail.
- Pouches:Flexible format for food service portion control and export efficiency.
- Tins:Traditional packaging for concentrated syrup in African domestic markets.
Bulk containers retain volume leadership; glass jars capture the steepest premium expansion in organic retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand ships refined cassava syrup to German and Dutch beverage manufacturers through direct-procurement contracts that bypass traditional trader intermediaries. Nigerian processors supply European bakery chains seeking REACH-compliant clean-label sweeteners.
Thailand
Beverage manufacturers in Bangkok and surrounding industrial zones anchor Southeast Asian export capacity for refined syrup grades. Thai German Processing maintains integrated tapioca supply chains that serve multinational bottlers under EFSA-guided formulation standards. Samut Sakhon province hosts concentrated enzymatic hydrolysis facilities where sensor-integrated monitoring reduces batch-to-batch viscosity variation for European importers.
Nigeria
Psaltry International anchors West African supply corridors targeting European bakery product manufacturers. The country's national food safety regulator enforces compliance protocols aligned with EU Green Deal agricultural sourcing requirements. Oyo State processing clusters specialize in organic certification tiers that command premium positioning across North American retail channels.
Germany
Bakery and confectionery segments in Bavaria and North Rhine-Westphalia drive substitution demand displacing artificial sweeteners. ECHA REACH registrations govern chemical safety documentation for cassava-derived ingredients entering personal care applications. Cologne industrial procurement offices negotiate direct volume commitments with Thai and Nigerian origin processors.
United States
Ingredion anchors North American distribution through specialty starch expertise serving beverage reformulation projects. FDA GRAS self-affirmation pathways and USDA organic certification standards govern market access timelines. Midwest food processing corridors in Illinois and Iowa integrate cassava syrup into packaged goods manufacturing as non-GMO alternatives to high-fructose corn syrup.
Netherlands
Rotterdam port infrastructure handles bulk container shipments from Southeast Asian processors for redistribution across European beverage manufacturers. Dutch industrial buyers prioritize supply traceability and cost transparency in contractual terms with origin-country suppliers. Amsterdam-area formulation laboratories calibrate viscosity profiles for cassava-derived alternatives entering carbonated drink production.
Cassava Syrup Market Competitive Landscape
On the supply side, the industry is consolidating around integrated processors with captive tapioca cultivation and dedicated enzymatic hydrolysis infrastructure. Large multinational ingredient suppliers compete with regional specialists on certification tiers and direct-procurement relationships. Three archetypes dominate: Southeast Asian integrated processors with backward control over root supply, North American distributors leveraging specialty starch formulation expertise, and African origin processors building organic certification capabilities. Competitive moves center on strategic partnerships with beverage manufacturers and portfolio diversification into resistant dextrin variants for nutraceutical channels.
Within the integrated processor tier, Thai German Processing and Psaltry International exemplify supply-side concentration through direct-procurement relationships with European industrial buyers. Cargill occupies a position bridging Southeast Asian origin capacity and multinational beverage manufacturer accounts through bulk pricing advantages. Among specialty distributors, Ingredion and Tate & Lyle represent formulation partnership archetypes competing on non-GMO positioning and clean-label certification support for confectionery clients.
| Leading Market Players |
|---|
| Cargill |
| Ingredion |
| Tate & Lyle |
| Ciranda |
| Sweetener Products Company |
| Madhava Natural Sweeteners |
| Thai German Processing |
| Psaltry International |
| Sanstar |
| Others |
Pricing and Supply Chain Analysis
Single-origin concentration risk in Thailand determines both the spread between refined and organic syrup tiers and the geographic shape of procurement corridors. Root crop price volatility from Southeast Asian monsoon patterns compresses processor margins unpredictably, forcing buyers toward long-term offtake contracts that bypass spot-market exposure.
Pricing Analysis
Enzymatic hydrolysis efficiency gains are compressing the technology-generation pricing gap between legacy batch-processing and sensor-integrated continuous systems. Three-tier pricing structure across premium organic, standard refined, and economy bulk grades separates certification levels and volume commitments. Pricing pressure stems from corn-based sweetener cost parity achieved through yield improvements in Thai processing facilities. Beverage manufacturers demonstrate highest price sensitivity due to formulation recalibration costs, while nutraceutical buyers absorb premiums for resistant dextrin positioning.
Supply Chain Analysis
Tariff exposure between Thailand and European Union member states dominates supply chain risk assessment for refined syrup importers. Geographic concentration centers on Thailand, Nigeria, and Vietnam for root supply and enzymatic processing capacity. Raw material dependencies include cassava tubers, specialized amylase and glucoamylase enzymes, and REACH-compliant packaging materials. Single-source vulnerability from Thai German Processing's integrated infrastructure creates cascade risk for German and Dutch beverage manufacturers. Distribution runs through Rotterdam port infrastructure for European redistribution and direct-procurement relationships with North American ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cassava syrup market is entering a cyclical recovery phase as enzymatic hydrolysis efficiency gains restore margin viability for processors previously squeezed by corn-sweetener competition.
For Market Incumbents: Insulate formulation partnerships from substitution threats by deepening captive tapioca cultivation in Oyo State and Samut Sakhon province. Secure EFSA positive opinions ahead of EMA food additive evaluation timelines to preempt supplier pre-qualification by German bakery chains. Backward integration into enzyme production reduces import-dependency exposure for African processors.
For New Entrants and Emerging Players: Build out organic certification capabilities in Nigerian supply corridors to capture the underdeveloped premium tier relative to corn and cane alternatives. Target nutraceutical-resistant dextrin applications as the fastest-expanding end-use segment with formulation partnership entry points. Establish direct-procurement relationships with Dutch industrial buyers prioritizing supply traceability.
For Investors and Strategic Acquirers: EU Green Deal agricultural sourcing requirements reshape the acquisition landscape toward certified sustainable cultivation zones in West Africa and Southeast Asia. Five-to-ten-year viability favors integrated processors with captive root supply and existing EFSA documentation. Watch for REACH compliance acceleration in German personal care applications as an inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Efficiency Investment | Sensor-integrated monitoring reduces batch-to-batch viscosity variation for European beverage manufacturers. |
| Organic Certification Tier Expansion | Three-year farm transition timelines in Nigeria capture premium positioning in North American retail channels. |
| Direct-Procurement Relationship Formation | Volume commitments with Thai and Nigerian processors displace trader intermediaries in German industrial buying. |
| Resistant Dextrin Portfolio Diversification | Prebiotic fiber claims penetrate dietary supplement channels currently served by isolated maltodextrin suppliers. |
| REACH Compliance Pre-Qualification | Early toxicological dossier submission accelerates EMA approval timelines for European personal care applications. |
Research Methodology
Initial hypotheses were tested against primary input from enzymatic hydrolysis engineers, procurement leads at European bakery manufacturers, regulatory affairs specialists, and Nigerian agricultural extension officers and refined through secondary validation. Bottom-up triangulation combined customs data from Thai and Nigerian export authorities, EFSA additive opinion databases, USDA organic certification records, and SEC filings from publicly traded ingredient distributors. Top-down constraints were applied through trade flow analysis and end-use industry consumption modeling.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product refinement depth, certification tier, end-use industry application, packaging format scale, and regional production hub concentration. CAGRs were derived from elasticity-adjusted volume projections calibrated to enzymatic yield improvement curves and substitution elasticity estimates for corn-sweetener displacement. Industry-specific inputs incorporated monsoon pattern correlation models for root crop pricing and EMA evaluation timeline probability distributions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated Thai processors or sudden enzyme cost spikes would shift outcomes. Material shifts in EU Green Deal enforcement stringency or REACH registration backlog resolution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Compressible Sugar Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Citrus Molasses Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Galactose Market
Sweeteners
Coconut Sugar Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Sugar Polyols Market
Sweeteners
Stevia Mints Market
Sweeteners
Glucose Syrup Market
Sweeteners
North America Stevia Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Tagatose Market