
 Europe Nuclear Imaging Market | 2026-2036
Europe Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nuclear Imaging Market Foresight
The EU Green Deal is decoupling nuclear imaging supply chains from carbon-intensive isotope production methods, forcing hospitals and imaging centers to evaluate low-energy cyclotron alternatives. Siemens Healthineers leverages its vertically integrated radiopharmaceutical network across German production sites. GE Healthcare anchors its European position through cyclotron manufacturing scale in Belgium and the Netherlands. Koninklijke Philips NV differentiates via digital PET detector architectures that reduce radiotracer dosage requirements.
Europe Nuclear Imaging encompasses diagnostic systems that detect gamma ray emissions from administered radiopharmaceuticals to visualize organ function, metabolic activity, and disease pathology at molecular resolution, typically operating with spatial precision below five millimeters and half-life-calibrated tracer kinetics. Positron Emission Tomography systems command the highest capital investment per unit among product categories, reflecting germanium oxyorthosilicate crystal costs and sub-nanosecond coincidence timing electronics. Hybrid Imaging technology fusions—particularly PET-MRI and PET-CT—are absorbing disproportionate R&D allocation as European health technology assessment bodies increasingly require comparative effectiveness evidence for reimbursement approval. Oncology applications generate the dominant procedure volume, though cardiology stress perfusion protocols sustain recurring radiopharmaceutical consumption.
The European Medicines Agency governs radiopharmaceutical marketing authorization through centralized procedures, while national competent authorities under the EU Medical Device Regulation enforce post-market surveillance for gamma camera and PET system hardware. REACH compliance constrains molybdenum-99 generator chemistry and lutetium-177 precursor sourcing, reshaping supplier qualification requirements for European nuclear pharmacies. Stakeholders must monitor EMA advanced therapy classification deliberations and emerging national diagnostic reference level mandates that could alter equipment utilization thresholds.
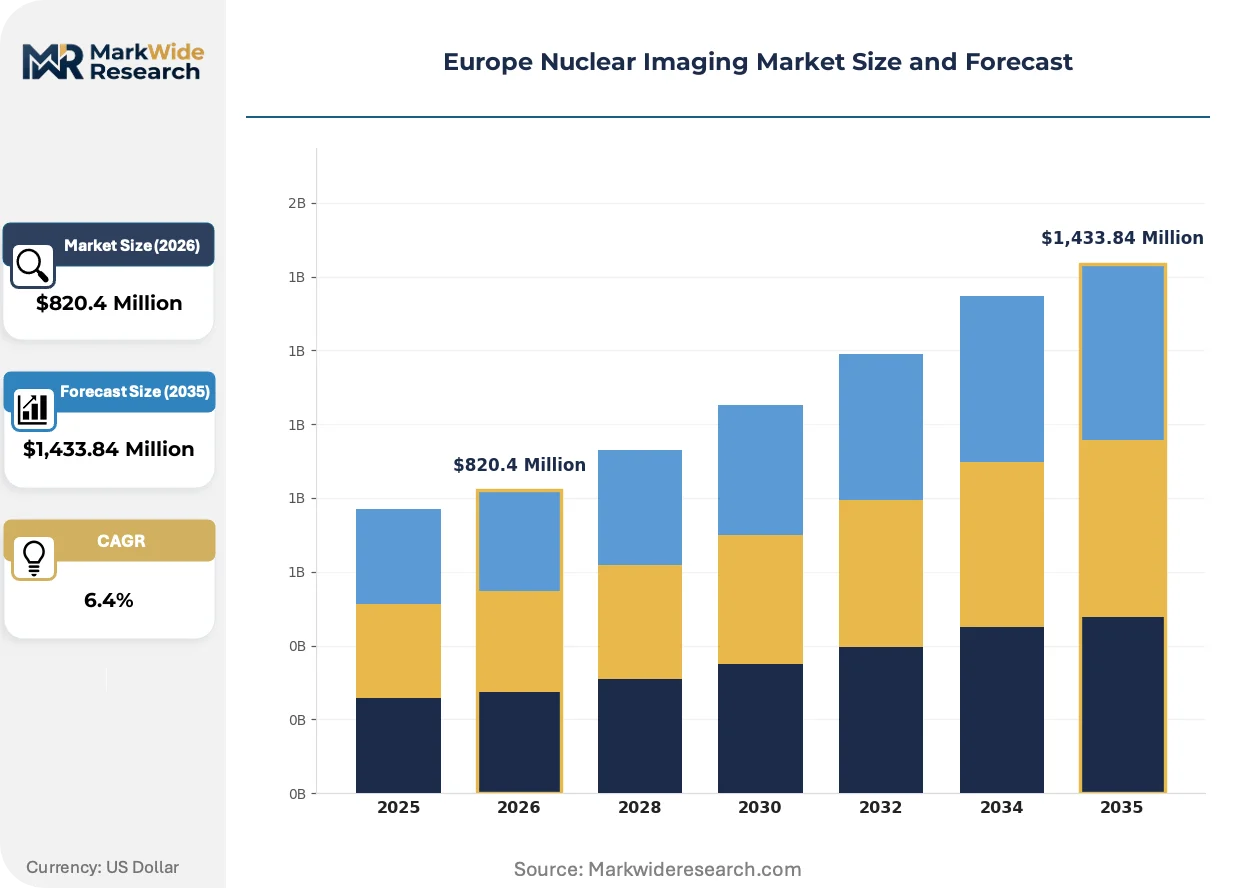
Market Dynamics
Hybrid imaging modality procurement across German, French, and British university hospitals is concentrating capital deployment toward PET-CT and PET-MRI systems, compressing standalone gamma camera replacement cycles and reshaping vendor competitive priorities.
Growth Catalysts
- EU Green Deal decarbonization mandates:Hospitals in the Netherlands and Belgium are retrofitting cyclotron facilities to reduce carbon-intensive isotope production methods, accelerating low-energy accelerator adoption.
- Oncology department expansion:European university hospitals are increasing PET-CT procurement budgets to support molecular imaging for precision oncology protocols.
- Reimbursement framework alignment:National health technology assessment bodies in Germany, France, and the United Kingdom are favoring hybrid imaging modalities in coverage decisions.
Market Restraints
- Germanium oxyorthosilicate crystal supply concentration:Detector material sourcing remains concentrated among limited specialty chemical suppliers, exposing equipment manufacturers to input cost volatility.
- EU Medical Device Regulation compliance burden:Post-market surveillance requirements for gamma camera and PET system hardware are extending certification timelines and increasing quality management system costs.
- REACH chemical restrictions:Molybdenum-99 generator chemistry and lutetium-177 precursor sourcing face constrained supplier qualification pathways, limiting radiopharmaceutical production flexibility.
Strategic Opportunities
- Digital PET detector architectures:Solid-state photon counting technology is unifying sensitivity improvements with radiotracer dosage reduction, opening premium positioning for equipment vendors.
- Underpenetrated cardiology stress perfusion:Italian and Spanish imaging centers show below-average PET myocardial perfusion imaging penetration relative to oncology procedure volumes.
- National diagnostic reference level mandates:Emerging radiation exposure thresholds in France and Germany are creating replacement demand for lower-dose imaging systems.
Industry Challenges
- Sub-nanosecond coincidence timing electronics expertise:PET system manufacturers face acute shortages of specialized signal processing engineers capable of optimizing detector calibration protocols.
- Legacy PACS integration complexity:Hybrid imaging installations require extensive middleware development to synchronize PET-CT and PET-MRI data flows with existing hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nuclear Imaging Market |
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $1,433.84 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Photon Emission Computed Tomography, Positron Emission Tomography, Gamma Camera, Radiopharmaceuticals End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Nuclear Medicine Departments Application: Oncology, Cardiology, Neurology, Functional Imaging Technology: Computed Tomography, Magnetic Resonance Imaging, Hybrid Imaging, Digital Imaging |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips NV, Bracco Imaging SpA, Cardinal Health Inc., Curium, Bayer AG, Canon Medical Systems Corporation, Mediso Medical Imaging Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nuclear Imaging Market Shifts & Advancements
Digital detector architectures, regulatory chemistry constraints, and procurement centralization are simultaneously compressing equipment replacement cycles and elevating radiopharmaceutical production standards across European nuclear imaging.
Silicon photomultiplier-based digital PET detectors are unifying photon counting sensitivity with reduced radiotracer dosage requirements. Oncology departments at university hospitals in Germany and France are prioritizing these systems for pediatric and repeat-imaging protocols. This technology is compressing the performance gap between premium-tier and mid-tier PET system configurations.
REACH compliance is reshaping molybdenum-99 generator chemistry and lutetium-177 precursor sourcing pathways for European nuclear pharmacies. The regulation forces radiopharmaceutical manufacturers to requalify chemical suppliers and document substitution hazard assessments. Belgian and Dutch cyclotron operators are absorbing disproportionate compliance costs due to concentrated precursor import dependencies.
Consolidated procurement consortia are displacing hospital-level equipment purchasing across National Health Service trusts in the United Kingdom. These centralized buying entities negotiate multi-site framework agreements that bundle PET-CT hardware, radiopharmaceutical supply contracts, and maintenance services. The model is compressing vendor margins while extending contract durations and locking out smaller equipment suppliers.
Europe Nuclear Imaging Market Segmentation
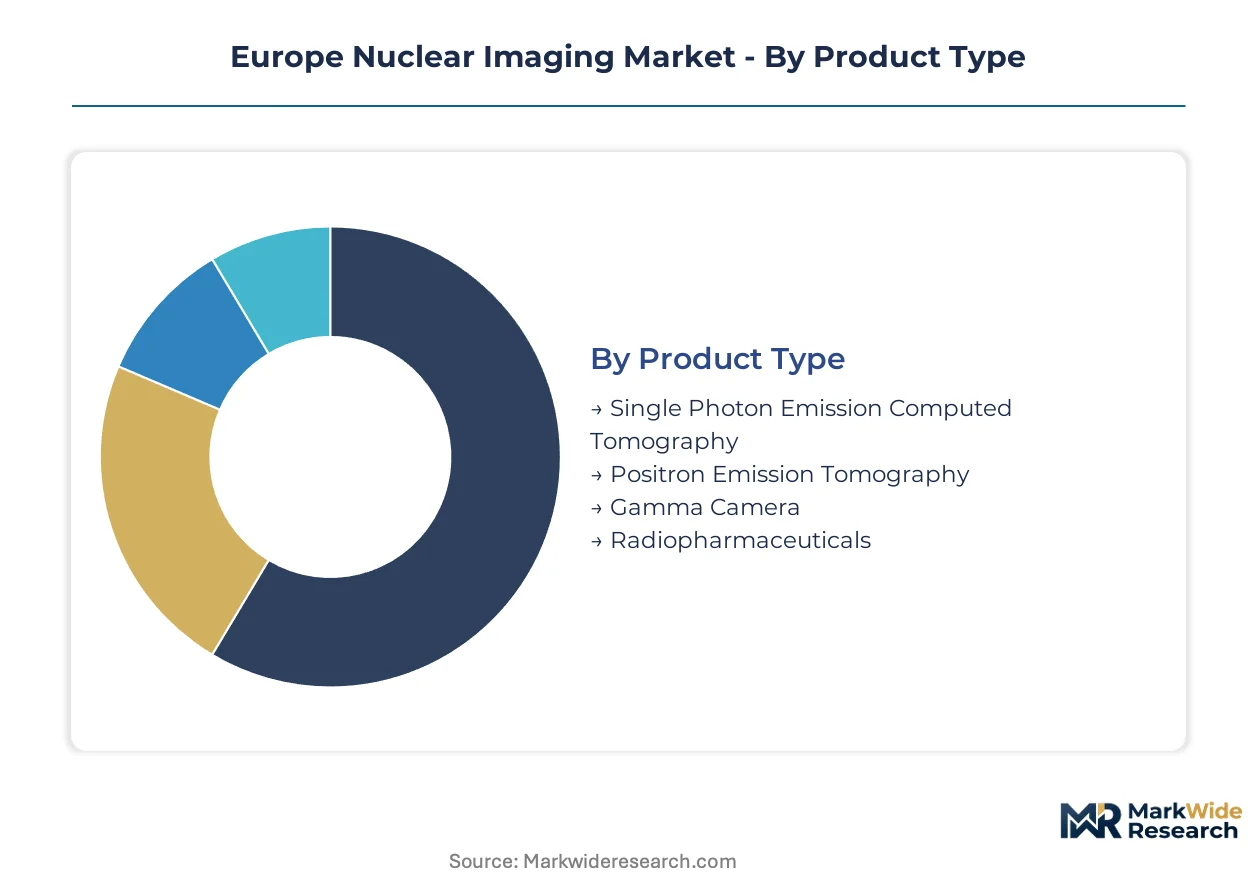
European nuclear imaging procurement concentrates capital among hybrid modalities while radiopharmaceutical sourcing faces REACH chemistry constraints. Segmentation reveals how detector material supply chains and reimbursement tiering reshape competitive positioning across product categories and end-use settings.
Product Type:
Supply concentration in germanium oxyorthosilicate crystal manufacturing and cyclotron isotope networks determines vendor competitiveness across equipment tiers.
- Positron Emission Tomography:PET systems deploy germanium oxyorthosilicate crystal arrays with sub-nanosecond coincidence timing electronics for metabolic imaging at five-millimeter spatial resolution. German university hospitals concentrate procurement of digital PET-CT configurations to support precision oncology protocols under national reimbursement frameworks.
- Hybrid Imaging:PET-CT and PET-MRI fusions command the highest capital investment per unit, integrating molecular sensitivity with anatomical precision. French and British health technology assessment bodies increasingly mandate comparative effectiveness evidence for hybrid system reimbursement approval.
- Single Photon Emission Computed Tomography:SPECT systems utilize thallium-doped sodium iodide detectors for myocardial perfusion and bone scintigraphy applications. Italian imaging centers sustain demand for SPECT-CT upgrades amid constrained PET penetration in cardiology.
- Gamma Camera:Anger camera technology supports planar scintigraphy for thyroid and renal function assessment. Replacement cycles compress as hospitals redirect capital toward hybrid modality procurement.
- Radiopharmaceuticals:Molybdenum-99 generators and fluorodeoxyglucose precursors face REACH compliance constraints on chemical sourcing pathways. Belgian and Dutch cyclotron operators absorb disproportionate supplier requalification costs.
Today's leader: Hybrid Imaging. Tomorrow's challenger: Digital PET architectures gaining mid-tier share.
End User:
Procurement centralization and reimbursement tiering concentrate demand among institutional categories with capital access and volume scale.
- Hospitals:University hospital oncology departments in Germany, France, and the United Kingdom drive PET-CT procurement expansion. National framework agreements bundle hardware, radiopharmaceutical supply, and maintenance services.
- Diagnostic Imaging Centers:Independent imaging facilities in Spain and Italy operate below-average PET myocardial perfusion penetration. Cardiology stress protocol expansion offers volume growth potential.
- Nuclear Medicine Departments:Hospital-integrated departments manage radiopharmaceutical preparation and quality control under EMA centralized marketing authorization procedures.
- Research Institutions:Academic medical centers deploy preclinical imaging systems for tracer development and theranostic protocol validation.
Procurement gravity centers on Hospitals. Diagnostic Imaging Centers show the steepest expansion trajectory as outpatient reimbursement frameworks mature.
Application:
Procedure volume distribution and tracer consumption patterns vary sharply across clinical domains.
- Oncology:Molecular imaging for tumor staging and treatment response assessment generates dominant procedure volumes. FDG-PET protocols consume the majority of European radiopharmaceutical production capacity.
- Cardiology:Stress perfusion imaging with rubidium-82 or ammonia-13 tracers sustains recurring radiopharmaceutical demand. Below-average penetration in Southern European markets indicates expansion headroom.
- Neurology:Amyloid and tau tracer applications for dementia diagnosis face emerging national diagnostic reference level mandates in France and Germany.
- Functional Imaging:Renal, thyroid, and inflammatory disease applications utilize technetium-99m labeled compounds with established reimbursement pathways.
Oncology commands current volume. Cardiology presents the largest underpenetrated opportunity.
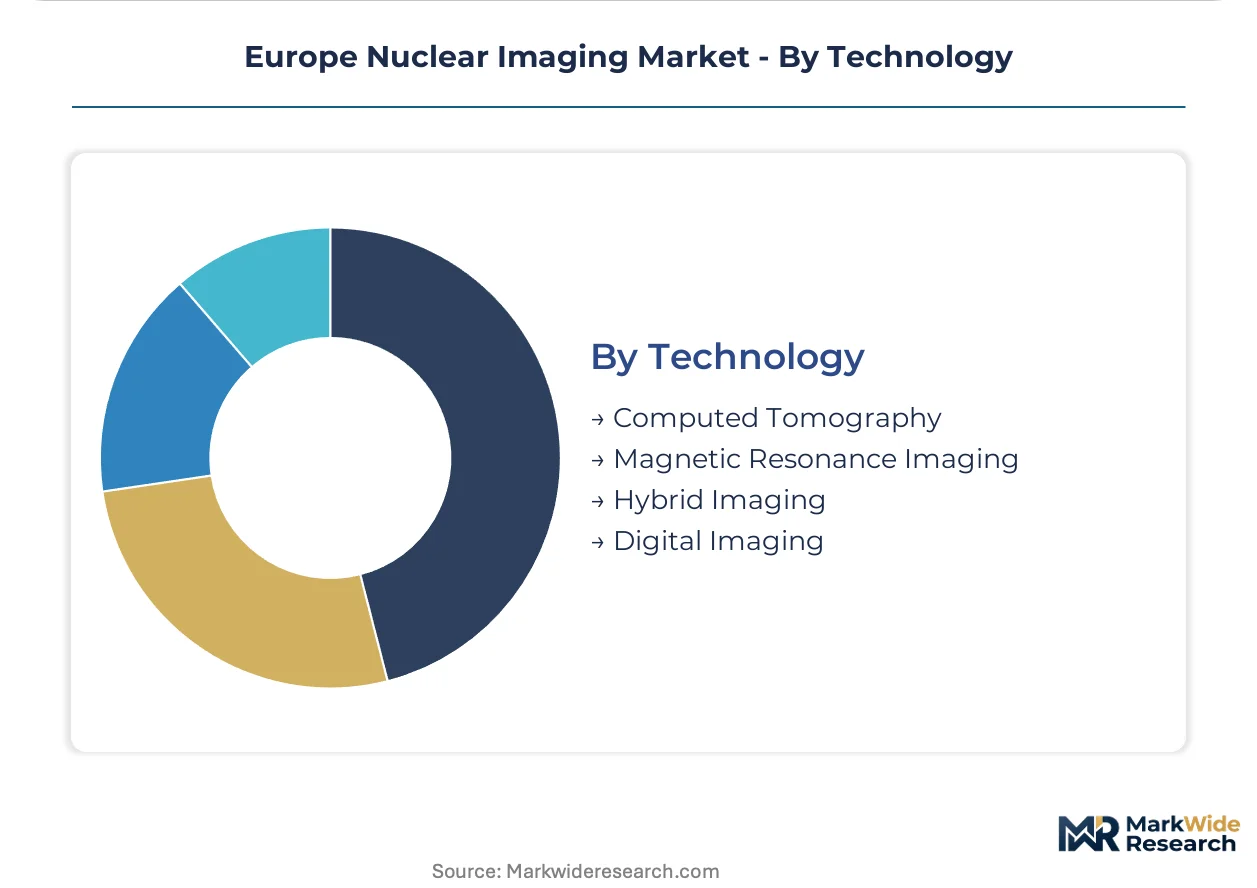
Technology:
Detector architecture evolution and data integration requirements differentiate competitive tiers.
- Hybrid Imaging:PET-CT and PET-MRI systems fuse metabolic and anatomical data streams, requiring extensive middleware development for PACS synchronization. Siemens Healthineers and GE Healthcare anchor European market presence through manufacturing scale.
- Digital Imaging:Silicon photomultiplier-based photon counting reduces radiotracer dosage requirements while improving sensitivity. Pediatric and repeat-imaging protocols at German university hospitals prioritize digital PET configurations.
- Computed Tomography:Diagnostic CT components in hybrid systems face EU Medical Device Regulation post-market surveillance requirements extending certification timelines.
- Magnetic Resonance Imaging:PET-MRI integration eliminates ionizing radiation from the anatomical component, aligning with emerging radiation exposure thresholds.
Hybrid Imaging dominates installed base. Digital Imaging is gaining share fastest as replacement cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nuclear imaging technology first achieved clinical scale in European university hospitals during the 1970s, with German and British research centers pioneering gamma camera development and tracer synthesis protocols that spread across the continent.
Germany
University hospital oncology departments in Munich and Heidelberg drive PET-CT procurement expansion for precision oncology protocols. The EU Medical Device Regulation enforces stringent post-market surveillance requirements on gamma camera and PET system hardware, extending certification timelines for domestic manufacturers. Siemens Healthineers maintains vertically integrated radiopharmaceutical production across German manufacturing sites.
France
French health technology assessment bodies mandate comparative effectiveness evidence for hybrid imaging reimbursement approval, concentrating capital deployment toward PET-MRI systems. ANSM enforces national diagnostic reference level mandates that are creating replacement demand for lower-dose imaging configurations. Parisian university hospitals anchor molecular imaging research clusters in the Île-de-France region.
United Kingdom
National Health Service trusts are consolidating procurement through multi-site framework agreements that bundle PET-CT hardware with radiopharmaceutical supply contracts. The UK Medicines and Healthcare products Regulatory Agency aligns with EMA centralized procedures for radiopharmaceutical marketing authorization. London and Manchester medical centers concentrate hybrid imaging installation volumes.
Netherlands
Dutch hospitals are retrofitting cyclotron facilities to meet EU Green Deal decarbonization mandates, accelerating low-energy accelerator adoption for isotope production. REACH compliance constrains molybdenum-99 generator chemistry sourcing pathways for nuclear pharmacies. Eindhoven and Utrecht host concentrated radiopharmaceutical manufacturing operations serving Benelux markets.
Belgium
Cyclotron operators in Belgium absorb disproportionate REACH compliance costs due to concentrated precursor import dependencies for lutetium-177 production. The European Medicines Agency governs radiopharmaceutical marketing authorization through centralized procedures that Belgian manufacturers must navigate. Brussels and Antwerp anchor radiopharmaceutical distribution networks extending into neighboring member states.
Europe Nuclear Imaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European nuclear imaging landscape, where detector crystal manufacturing and cyclotron isotope networks demand substantial fixed investment while software and detector architecture innovation requires specialized engineering talent. The market structure concentrates among diversified health technology conglomerates with captive radiopharmaceutical supply chains. Three archetypes dominate: vertically integrated system manufacturers, specialized radiopharmaceutical suppliers, and digital detector technology specialists. Competitive dynamics center on strategic partnerships for middleware development and capacity expansion in low-energy cyclotron installations.
Among diversified health technology conglomerates, Siemens Healthineers, GE Healthcare, and Koninklijke Philips NV occupy positions representing distinct strategic vectors. Siemens Healthineers exemplifies vertical integration across German production sites. GE Healthcare anchors manufacturing scale in Belgium and the Netherlands. Koninklijke Philips NV represents digital detector architecture specialization that reduces radiotracer dosage requirements.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips NV |
| Bracco Imaging SpA |
| Cardinal Health Inc. |
| Curium |
| Bayer AG |
| Canon Medical Systems Corporation |
| Mediso Medical Imaging Systems |
| Others |
Supply & Pricing Matrix
Specialized signal processing engineers concentrated in southern Germany and eastern France drive labor-cost differentials that widen pricing-tier spreads between premium digital PET configurations and mid-tier analog systems. Siemens Healthineers and GE Healthcare absorb elevated personnel expenses at Munich and Brussels manufacturing sites, translating into premium positioning for coincidence timing electronics calibration capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates vendors by detector crystal quality grade and CE-MDR certification tier. Premium digital PET-CT systems command substantial markups for silicon photomultiplier photon counting technology, while economy gamma camera tiers face acute price erosion from consolidated NHS procurement frameworks. University hospitals in Germany and France show lowest price sensitivity due to reimbursement alignment, whereas independent Italian imaging centers prioritize capital efficiency.
Supply Chain Analysis
Regional distribution centers in Belgium and the Netherlands anchor hub-and-spoke radiopharmaceutical logistics serving Benelux and northern French markets. Germanium oxyorthosilicate crystal production concentrates in Japan, Russia, and China, with European equipment manufacturers drawing from limited specialty chemical suppliers. REACH compliance restrictions on molybdenum-99 generator chemistry create single-source vulnerability for Belgian cyclotron operators. Distribution runs through hospital-integrated nuclear pharmacies and centralized radiopharmaceutical manufacturing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation compounder effect intensifies as post-market surveillance timelines extend certification cycles, forcing capital deployment toward compliant manufacturing scale. EMA centralized procedures for radiopharmaceutical marketing authorization create structural barriers that favor incumbent quality management system investments.
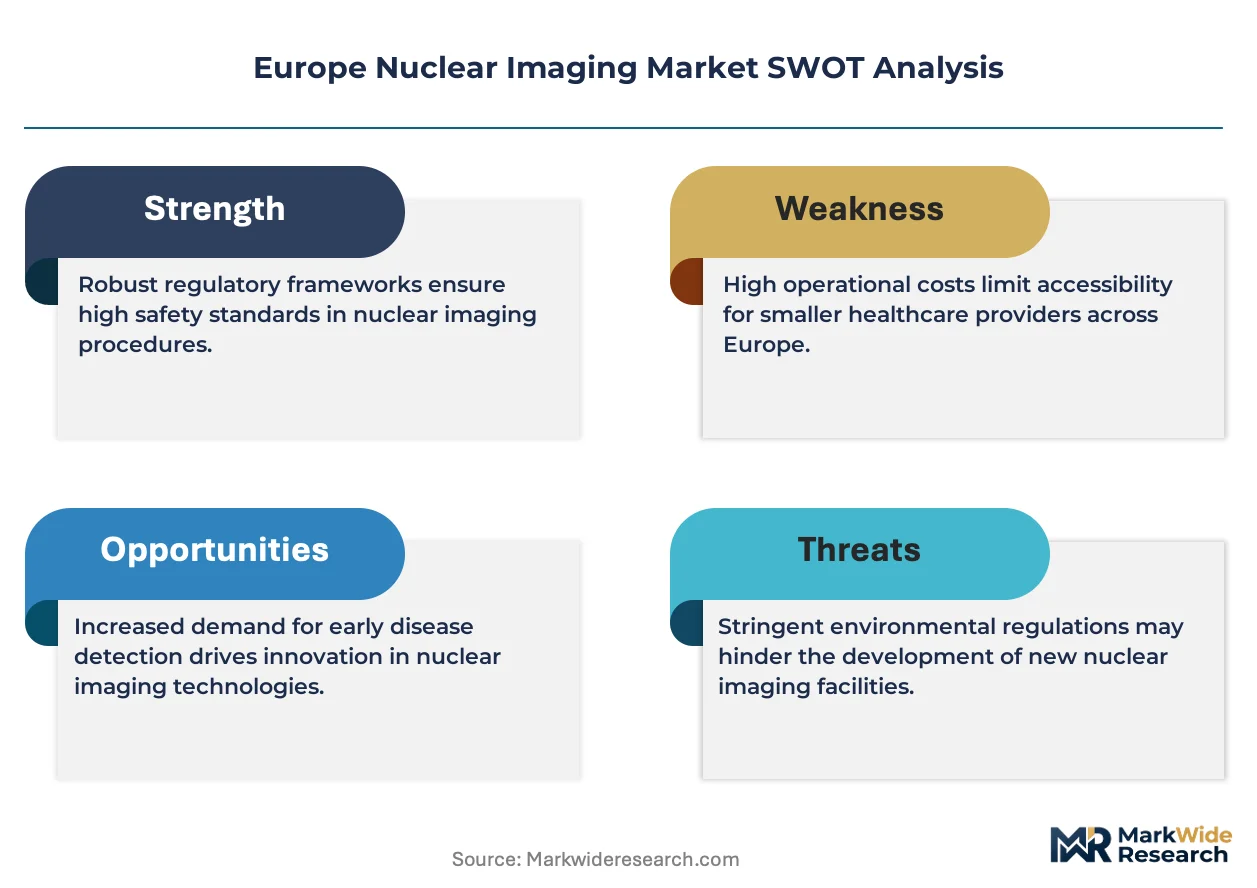
For Market Incumbents: Anticipate compressed margins from consolidated NHS procurement frameworks by deepening backward integration into cyclotron isotope networks across German and Belgian production sites. Defend positioning against digital detector specialists through captive supply chain control over lutetium-177 precursor sourcing pathways. For New Entrants and Emerging Players: Enter via underpenetrated cardiology stress perfusion segments in Italian and Spanish imaging centers where PET myocardial perfusion imaging runs below European averages. Target diagnostic imaging center partnerships with software-as-a-service middleware offerings that reduce PACS integration friction for hybrid imaging installations. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized radiopharmaceutical suppliers facing disproportionate REACH compliance cost absorption relative to diversified health technology conglomerates. Monitor EMA advanced therapy classification deliberations as the inflection signal for theranostic protocol reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance requirements extend certification timelines for gamma camera hardware. |
| Hospital System Partnership | Multi-site framework agreements bundle PET-CT procurement with radiopharmaceutical supply contracts. |
| Reimbursement Strategy | Health technology assessment bodies mandate comparative effectiveness evidence for hybrid imaging approval. |
| Software Companion Development | Middleware synchronization resolves legacy PACS integration complexity for PET-CT data flows. |
| Backward Integration | Captive cyclotron networks secure isotope supply against REACH-constrained precursor sourcing. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down cyclotron manufacturing capacity tracking forms the analytical core. Primary interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and radiopharmaceutical manufacturing executives combined with secondary validation against EMA centralized procedure filings, EU MDR post-market surveillance databases, hospital procurement registries, and REACH compliance documentation. Top-down and bottom-up triangulation cross-validates equipment installation volumes against isotope production capacity.
Historical trendline analysis of PET-CT procurement cycles and radiopharmaceutical consumption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end-user category, application, and technology architecture alongside regional regulatory cluster differentiation. CAGRs derived from equipment replacement cycle compression rates and radiopharmaceutical volume growth trajectories. Forecast inputs incorporated EU Green Deal decarbonization mandate compliance timelines and national diagnostic reference level implementation schedules.
The model holds under stable reimbursement framework conditions and REACH enforcement continuity; deviation in EMA advanced therapy reclassification or abrupt MDR certification timeline shifts would revise trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
China Mammography Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Digital X Ray Market