
 Global Positron Emission Tomography [PET] Scanners Market | 2026-2036
Global Positron Emission Tomography [PET] Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Positron Emission Tomography [PET] Scanners Market Intelligence
The buyer landscape for PET scanners is consolidating as large hospital networks and multi-site imaging center chains increase their procurement power. Siemens Healthineers leverages its extensive diagnostic imaging portfolio to serve these large accounts. GE Healthcare competes through its focus on integrated digital solutions and service contracts. Koninklijke Philips N.V. differentiates with its specialized systems for complex neurological and cardiac applications.
Positron Emission Tomography (PET) scanners are medical imaging devices that create three-dimensional images of metabolic processes within the body. The technology works by detecting pairs of gamma rays emitted indirectly by a positron-emitting radiotracer, providing functional insights unavailable from other modalities. The combined PET/CT systems represent the largest product segment due to their ability to fuse functional PET data with anatomical CT scans. Cancer diagnosis remains the principal application, driving procurement primarily within the hospital end-user segment.
Market access is governed by stringent regulatory approvals, including 510(k) clearance or Premarket Approval (PMA) from the US FDA and CE marking under the Medical Device Regulation (MDR) in Europe. In China, the National Medical Products Administration (NMPA) sets the standards for device registration and quality. Future investment decisions for providers will hinge on evolving reimbursement policies for advanced applications and the clinical utility of emerging PET/MRI systems.
Market Dynamics
The consolidation of healthcare providers into large hospital networks and multi-site imaging chains represents the central structural force shaping the market. This buyer concentration creates significant procurement leverage, forcing PET scanner manufacturers to compete not just on technology but on enterprise-wide service, software integration, and total cost of ownership.
Growth Catalysts
- Expanding Clinical Applications:The growing use of PET imaging in neurology for Alzheimer's and Parkinson's diagnosis, alongside its established role in oncology, is widening the addressable patient population and stimulating demand from specialized clinical departments.
- Government Healthcare Investment:National initiatives to upgrade healthcare infrastructure, particularly in countries like China and India, are funneling significant capital into advanced diagnostic imaging technology, including PET systems, to improve public health outcomes.
- Time-of-Flight Technology:The continued advancement and adoption of TOF technology enhances image quality and signal-to-noise ratio. This allows for faster scans or reduced radiotracer doses, improving patient throughput and safety in hospital settings.
Market Restraints
- High Capital Costs:The substantial initial investment required for PET/CT and especially PET/MRI systems acts as a significant barrier for smaller hospitals and imaging centers, limiting market penetration outside of well-funded institutions.
- Radiotracer Logistics:The reliance on positron-emitting radiotracers with extremely short half-lives necessitates proximity to a cyclotron, creating complex and costly logistical challenges that constrain geographic accessibility for imaging centers.
- Stringent Regulatory Hurdles:Navigating the rigorous and lengthy device approval pathways, such as Premarket Approval (PMA) from the US FDA or CE marking under the EU's MDR, delays product launches and increases development costs.
Strategic Opportunities
- Integrated PET/MRI Systems:The development of hybrid PET/MRI scanners offers a unique opportunity by combining molecular data with superior soft-tissue contrast, opening new avenues in neurological, musculoskeletal, and pediatric imaging research and diagnostics.
- Drug Development and Trials:Pharmaceutical companies are increasingly using PET imaging as a quantitative biomarker in clinical trials to assess drug efficacy and patient response, creating a new and growing customer segment for scanner manufacturers.
- Emerging Market Expansion:Healthcare infrastructure development in Brazil, Mexico, and Southeast Asian nations presents a significant opportunity for market entry and expansion as these regions seek to modernize their diagnostic imaging capabilities.
Industry Challenges
- Specialized Personnel Shortage:A global shortage of trained nuclear medicine physicians, radiologists, and technologists qualified to operate PET scanners and interpret the complex functional images creates a bottleneck for operational capacity.
- Data Integration Complexity:Ensuring seamless integration of PET systems with existing hospital information systems (HIS) and Picture Archiving and Communication Systems (PACS) remains a persistent technical and operational challenge for healthcare providers.
- Reimbursement Policy Fluctuation:Evolving and inconsistent reimbursement policies for advanced PET procedures across different countries and healthcare systems create uncertainty for providers, influencing their investment decisions and adoption rates for new technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Positron Emission Tomography [PET] Scanners Market |
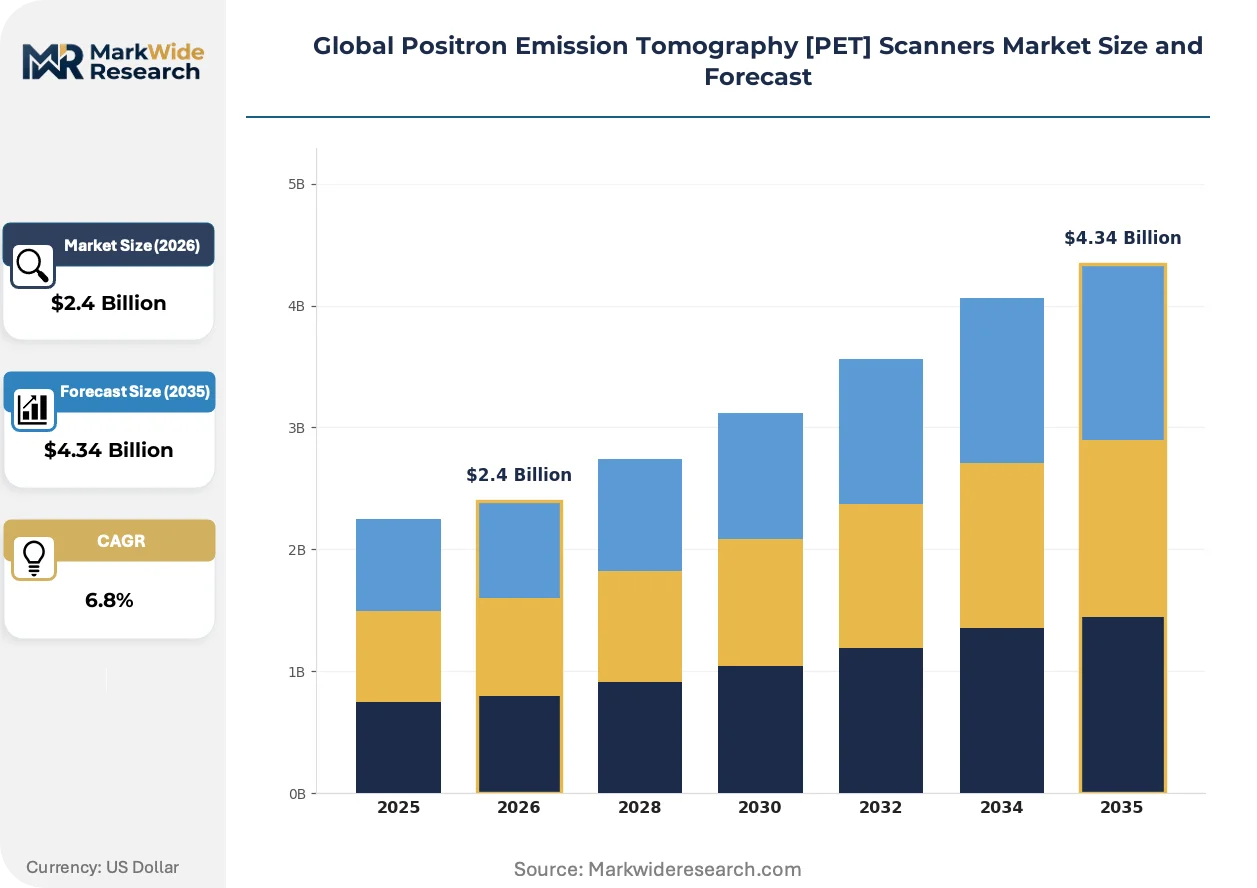
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Body PET, PET/CT, PET/MRI, Portable PET Technology: Time-of-Flight, Digital, Analog, Hybrid End User: Hospitals, Imaging Centers, Research Institutions, Laboratories Application: Cancer Diagnosis, Neurology, Cardiology, Infectious Disease |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems, Hitachi Ltd., United Imaging Healthcare, Mediso Ltd., Shimadzu Corporation, Positron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Positron Emission Tomography [PET] Scanners Market Strategic Shifts & Innovations
The pursuit of higher quantitative accuracy and improved patient experience is driving innovation. A focus on reducing scan times and radiation exposure through superior detector technology and advanced software algorithms defines the current product development cycle, responding directly to clinical and operational demands from healthcare providers.
Digital PET detectors based on Silicon Photomultipliers (SiPM) provide superior timing resolution and photon detection efficiency. Large academic medical centers and dedicated oncology clinics are the primary adopters of this next-generation hardware. The enhanced performance of digital systems, which enables faster scans and lower radiotracer doses, is overtaking the capabilities of legacy analog photomultiplier tube (PMT) technology.
In Europe, the Medical Device Regulation (MDR) intensifies the requirements for clinical evidence and post-market surveillance. This regulation directly impacts manufacturers by increasing the cost and time associated with bringing new PET systems to market. The diagnostic imaging segment is most affected, forcing vendors to generate more robust clinical data to obtain or maintain CE marking for their devices.
A notable behavioral shift is occurring in equipment acquisition, moving from one-time capital purchases to long-term, value-based partnerships. Large hospital systems are increasingly favoring managed equipment service contracts that bundle the scanner with maintenance, software upgrades, and technology refresh options. This trend is most prominent in North America and Western Europe, where providers prioritize predictable operational costs and access to current technology.
Global Positron Emission Tomography [PET] Scanners Market Segmentation
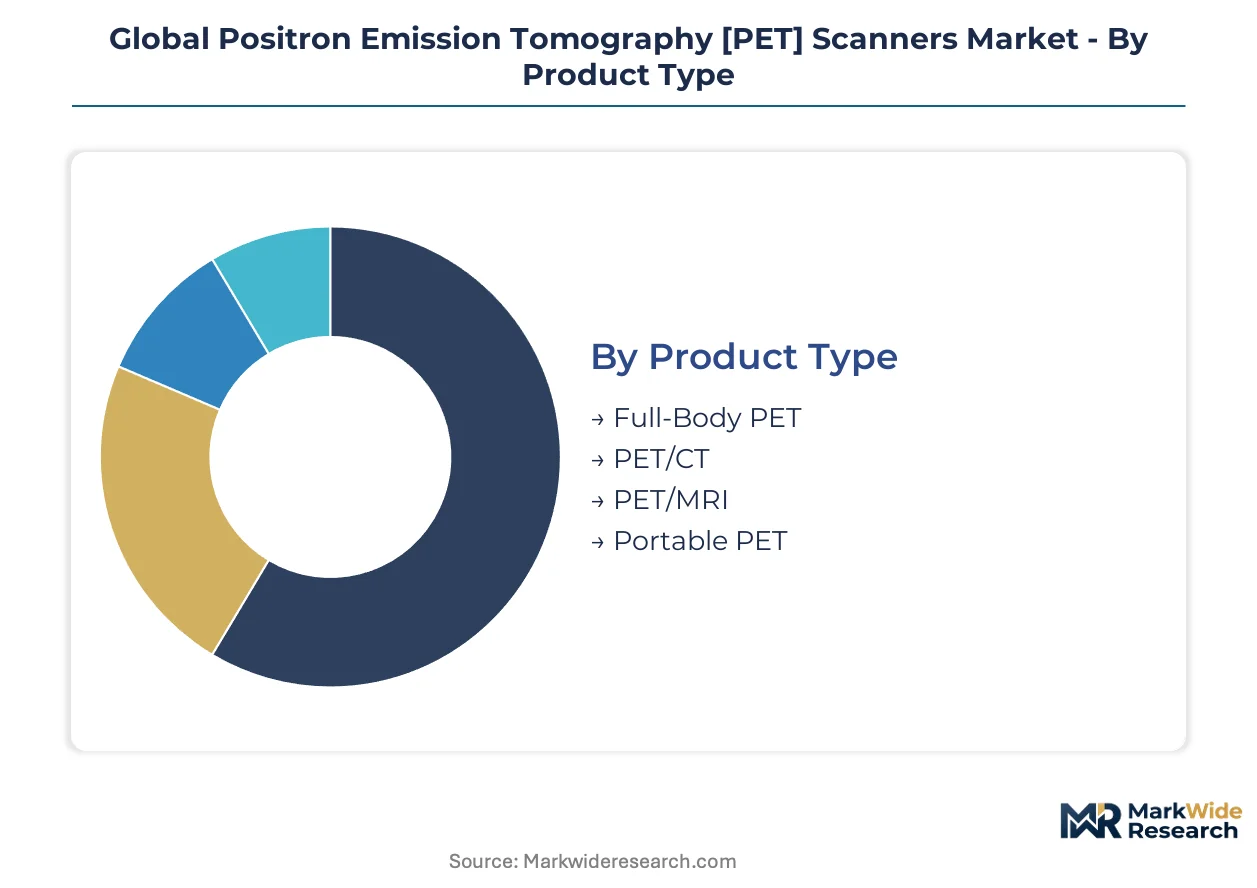
The PET scanners market is segmented to reflect the diverse technological capabilities, clinical applications, and end-user requirements that shape procurement decisions. Understanding these distinct segments provides clarity on where investment is directed and how technological innovation translates into clinical utility across different healthcare settings.
Product Type:
The market for PET scanners categorizes devices by their core functional integration and design specifications.
- Full-Body PET:These standalone systems are designed for comprehensive metabolic imaging across the entire body, primarily used in oncology for staging and monitoring cancer. Demand for these systems remains consistent in specialized cancer treatment centers globally.
- PET/CT:This integrated system combines the functional imaging of PET with the anatomical detail of CT, offering superior diagnostic accuracy by fusing metabolic and structural information. PET/CT systems represent the largest product segment, driving procurement within hospital networks and large imaging centers due to their versatility and established clinical utility.
- PET/MRI:Hybrid PET/MRI scanners merge the molecular insights of PET with the excellent soft-tissue contrast of MRI, providing advanced diagnostic capabilities, particularly in neurology and pediatric imaging. These systems are gaining traction in academic medical centers and research institutions for complex cases and clinical trials.
- Portable PET:Compact and often mobile PET systems offer flexibility for point-of-care imaging or situations where patient transport to a fixed scanner is challenging. These systems are exploring niches in emergency medicine and remote diagnostic settings.
PET/CT systems lead on scale; PET/MRI systems lead on momentum.
Technology:
Technological advancements define the performance tiers and capabilities across the PET scanner market.
- Time-of-Flight:TOF technology measures the arrival time difference of gamma rays with high precision, significantly improving image quality, signal-to-noise ratio, and lesion detectability. This technology is a primary driver for new scanner purchases in well-funded institutions and large hospital networks seeking enhanced diagnostic confidence.
- Digital:Digital PET detectors, often based on Silicon Photomultipliers (SiPM), offer superior timing resolution and photon detection efficiency compared to traditional analog systems. These systems enable faster scans, lower radiotracer doses, and improved quantitative accuracy, influencing adoption in academic medical centers and dedicated oncology clinics.
- Analog:Analog PET systems utilize Photomultiplier Tubes (PMT) for photon detection, representing the established and widely installed base of older generation scanners. These systems remain operational in numerous facilities, particularly in regions with budget constraints.
- Hybrid:Hybrid technology refers to combined imaging modalities like PET/CT and PET/MRI, integrating different imaging principles into a single device for comprehensive diagnostic information. These systems are preferred for their ability to provide functional and anatomical data simultaneously.
Time-of-Flight technology drives current adoption, while digital systems represent the fastest-growing segment.
End User:
Customer type and operational scale dictate the specific PET scanner configurations procured.
- Hospitals:Hospitals, particularly large university hospitals and specialized cancer centers, constitute the primary end-user segment for PET scanners. These institutions require advanced imaging capabilities for patient diagnosis, treatment planning, and monitoring across various departments.
- Imaging Centers:Standalone or multi-site imaging centers represent a significant end-user category, often focusing on outpatient diagnostic services. These centers invest in PET/CT systems to offer specialized imaging services and expand their diagnostic portfolios.
- Research Institutions:Academic and private research institutions utilize PET scanners for clinical research, drug development, and understanding disease mechanisms. Their demand often includes specialized systems like PET/MRI for advanced scientific investigations.
- Laboratories:Pharmaceutical and biotechnology laboratories increasingly use PET imaging as a quantitative biomarker in preclinical and clinical trials. These facilities acquire PET scanners to assess drug efficacy and patient response.
Hospitals represent the primary investment source, with imaging centers expanding their installed base.
Application:
The clinical utility of PET imaging spans several critical medical applications, each driving specific demand patterns.
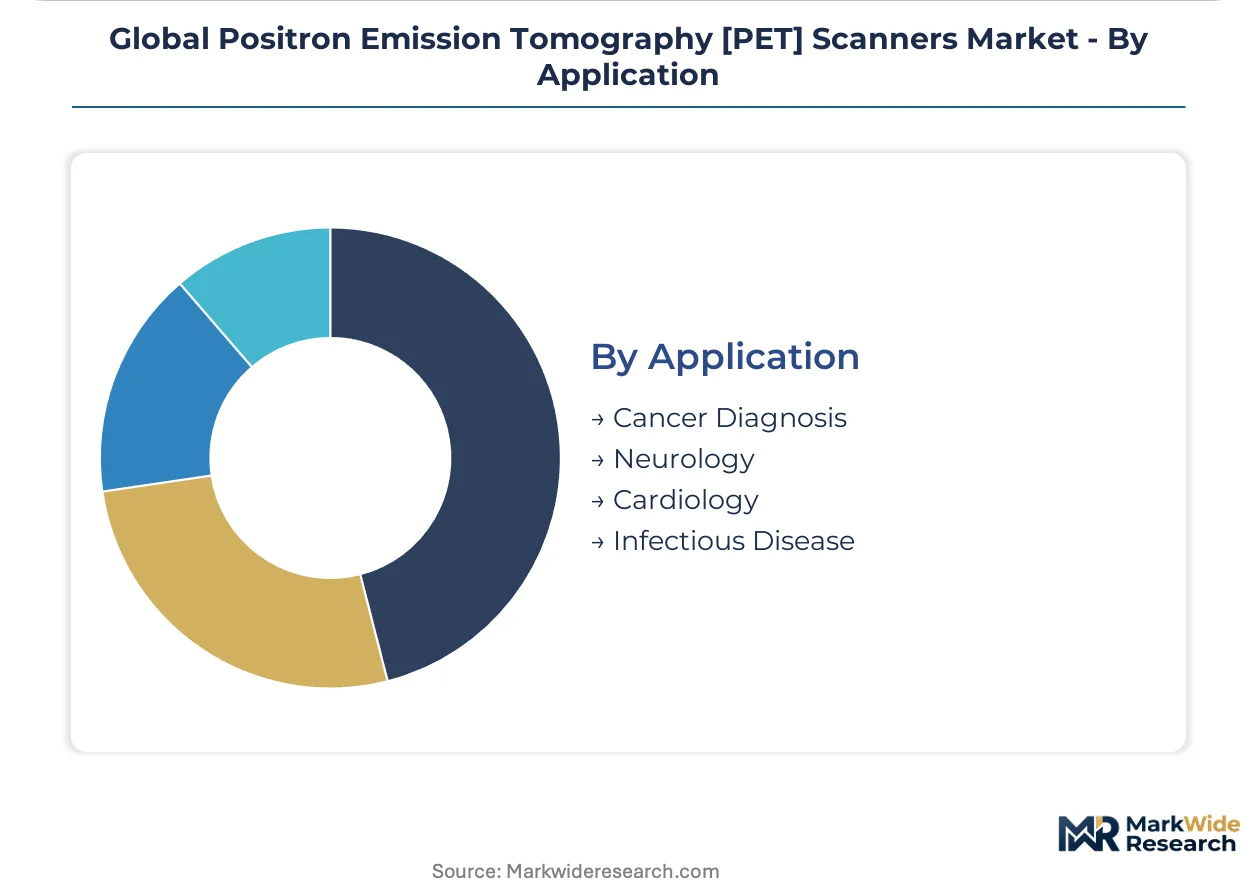
- Cancer Diagnosis:Oncology remains the principal application for PET scanners, providing essential information for cancer detection, staging, treatment response assessment, and recurrence monitoring. This application drives substantial procurement within hospitals and specialized cancer clinics globally.
- Neurology:PET imaging plays an expanding role in neurology for the diagnosis and differentiation of neurodegenerative diseases like Alzheimer's and Parkinson's, as well as for epilepsy localization. This application stimulates demand from specialized neurological departments and research centers.
- Cardiology:PET offers unique insights into myocardial perfusion and viability, aiding in the diagnosis of coronary artery disease and assessing heart function. Cardiovascular PET is a specialized application, often found in advanced cardiac imaging centers.
- Infectious Disease:PET imaging helps in localizing and assessing the extent of infections and inflammatory processes, particularly in cases of fever of unknown origin or osteomyelitis. This application is gaining recognition in infectious disease management.
Cancer diagnosis remains the most significant clinical application, with neurology gaining considerable importance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical professionals and researchers globally drive demand for advanced diagnostic imaging technologies. This need anchors the market for PET scanners, particularly in regions with established healthcare infrastructure and those undergoing significant modernization. Key countries are prioritizing investment in diagnostic capabilities to improve patient outcomes and support clinical research initiatives.
United States
Demand for PET scanners in the United States stems from expanding applications in oncology and neurology. The US FDA's stringent 510(k) clearance process ensures device safety and efficacy before market entry. Major academic medical centers and biopharmaceutical clusters in Boston and California continue to lead in PET research and early adoption of new systems.
China
China's substantial investment in healthcare infrastructure fuels the procurement of advanced diagnostic technologies like PET scanners. The National Medical Products Administration (NMPA) sets the standards for device registration and quality in the country. Large public hospitals and specialized cancer centers in the Yangtze River Delta region are rapidly expanding their PET imaging capabilities.
Germany
German academic medical centers and research institutions drive demand for high-end PET systems, particularly those with advanced digital and Time-of-Flight technologies. CE marking under the Medical Device Regulation (MDR) governs market access for PET scanners in Europe. Bavaria and North Rhine-Westphalia host significant medical technology clusters, fostering innovation and adoption.
Japan
Japan's aging population and focus on early disease detection contribute to consistent demand for PET imaging, especially in oncology and neurodegenerative diseases. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees the approval and regulation of medical devices. The Kanto region, including Tokyo, concentrates major hospitals and research facilities that utilize advanced PET systems.
India
Growing urban healthcare infrastructure and an increasing burden of chronic diseases stimulate demand for advanced diagnostic tools in India. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices and approvals within the country. Major metropolitan areas like Delhi-NCR and Mumbai are witnessing significant investment in new hospital facilities equipped with PET scanners.
Global Positron Emission Tomography [PET] Scanners Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the PET scanners market. The market structure is tiered, with global medical imaging giants dominating the high-end segments. Specialized manufacturers often target niche applications or specific technological advancements. Dominant competitive moves include strategic partnerships for technology co-development and targeted acquisitions to expand portfolio capabilities.
Global imaging giants like Siemens Healthineers and GE Healthcare exemplify the comprehensive portfolio approach, offering integrated diagnostic solutions across multiple modalities. These companies leverage their extensive sales and service networks to reach large hospital systems and multi-site imaging chains. Koninklijke Philips N.V. also occupies a significant position, often differentiating with specialized systems for complex neurological and cardiac applications.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| Hitachi Ltd. |
| United Imaging Healthcare |
| Mediso Ltd. |
| Shimadzu Corporation |
| Positron Corporation |
| Others |
Cost & Logistics Intelligence
Diversified conglomerates, which dominate the PET scanner market, shape both supply chain resilience and pricing strategies through their integrated manufacturing and extensive distribution networks. Their financial strength allows for significant R&D investments and long-term service contract offerings.
Pricing Analysis
Bundled service contracts, encompassing hardware, software, and maintenance, define the primary pricing model for PET scanners. Price differentiation stems from advanced features like Time-of-Flight technology and integration with existing hospital information systems. Pricing softness affects analog systems due to technological obsolescence and lower performance. Smaller hospitals and imaging centers exhibit higher price sensitivity compared to large academic medical centers, which prioritize advanced capabilities.
Supply Chain Analysis
PET scanner manufacturing relies heavily on specialized electronic components and advanced detector materials, often sourced from Germany, Japan, and the United States. The supply of radiotracers, with their short half-lives, creates a logistical chokepoint due to cyclotron proximity requirements. Single-source vulnerability for critical detector components poses a structural risk for manufacturers. Distribution runs through direct sales forces and established medical equipment distributors, particularly to large hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET scanners market operates as a stable compounder, driven by the expanding clinical applications in oncology and neurology. Consistent investment in healthcare infrastructure globally further underpins this steady growth trajectory.
For Market Incumbents: Anticipate continued consolidation of large hospital networks, necessitating enterprise-wide service contracts and integrated digital solutions. Incumbents should invest in PET/MRI system R&D to counter emerging specialized entrants and maintain technological leadership. Expanding clinical evidence for advanced applications will reinforce market position against substitute imaging modalities. Deepening partnerships with pharmaceutical companies for drug development trials also offers a strong defensive move.
For New Entrants and Emerging Players: Digital-channel partnerships with smaller imaging centers offer a viable route for new entrants to target underpenetrated regional markets. Focus on portable PET systems for emergency medicine or remote diagnostics represents a white-space opportunity. A go-to-market angle emphasizing lower total cost of ownership through efficient logistics and modular designs could attract budget-conscious buyers. Developing AI-powered image analysis software as a complementary offering also provides differentiation.
For Investors and Strategic Acquirers: Valuations sit cheapest among legacy analog system manufacturers with limited R&D pipelines, presenting potential turnaround opportunities. Long-term viability is strong for firms specializing in digital PET detectors or advanced radiotracer production. Acquisition targets should include companies with niche expertise in neurological PET applications or those developing next-generation detector materials. A key signal to watch is the pace of reimbursement policy expansion for emerging PET/MRI procedures.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Detector R&D | Drives superior image quality, faster scans, and lower radiation exposure for patients. |
| PET/MRI System Development | Integrates molecular and anatomical data, opening new diagnostic avenues in neurology. |
| Hospital System Partnership | Secures long-term procurement agreements and provides extensive service contract opportunities. |
| CE Marking Pathway | Ensures market access and regulatory compliance for PET systems across European Union countries. |
| Radiotracer Logistics Optimization | Addresses short half-life challenges, improving geographic accessibility for imaging centers. |
Research Approach
Multiple input streams — primary interviews, regulatory filings, and academic literature — were reconciled to build a comprehensive market understanding. Interviews included clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Secondary validation utilized FDA filings, NMPA registration data, and medical device association reports. This involved bottom-up data aggregation and top-down market sizing triangulation.
Data-stream reconciliation established the analytical framework for market projections across the analysis window. Segmentation dimensions modeled included product type, technology, end-user, and application, alongside regional regulatory nuances. Compound annual growth rates were derived from historical data trends and projected adoption rates for new technologies. Healthcare infrastructure investment and evolving reimbursement policies served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for digital PET systems would alter the outlook. Forecasts reflect assumptions regarding regulatory approvals and radiotracer supply chain stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Dental Imaging Market
Medical Imaging
Teleradiology Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
China Mammography Market
Medical Imaging
Next Generation Ultrasound Systems Market
Medical Imaging
Echocardiography Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market