
 Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market | 2026-2036
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market Analytics
The EU Green Deal's medical equipment energy-efficiency directives is repositioning procurement criteria across Irish and Northern Irish health systems. Siemens Healthineers Ireland leverages its installed base of magnet technology to sustain service contracts across the HSE's hospital network. Alliance Medical anchors mobile MRI deployment in Northern Ireland's rural health zones where fixed infrastructure remains sparse. Affidea Ireland differentiates through multi-site accreditation that competes directly with public hospital radiology departments for NHS and HSE referral volumes.
MRI and CT scan radiology services encompass diagnostic imaging modalities utilizing magnetic resonance and computed tomography technologies to generate cross-sectional anatomical visualizations, with MRI systems typically operating at 1.5T or 3.0T field strengths and CT scanners employing multi-slice detector arrays from 64 to 320 slices for sub-millimeter spatial resolution. These services enable non-invasive detection, staging, and monitoring of neoplastic, neurological, and musculoskeletal pathologies across acute and ambulatory care settings. MRI services lead the service type category due to superior soft-tissue contrast for neurological and oncological indications, while AI Integration within the technology dimension represents the fastest-expanding segment as automated lesion detection and workflow triage reduce radiologist interpretation burden. Oncology applications within the application segment command concentrated margin pools given the complexity of multi-parametric imaging protocols and the requirement for serial treatment-response monitoring.
HIQA's statutory licensing framework for designated diagnostic centers shapes market access through mandatory equipment calibration, staff credentialing, and quality-assurance protocols that filter subscale operators. The UK's Medicines and Healthcare products Regulatory Agency (MHRA) governs Northern Ireland's medical device conformity assessment under retained EU law, while the Health and Safety Executive for Northern Ireland enforces ionizing radiation regulations for CT scanner installations. Stakeholders must monitor the divergence trajectory between post-Brexit UK medical device regulations and continuing EU MDR alignment in the Republic of Ireland, as dual compliance obligations will determine cross-border service configuration economics.
Market Dynamics
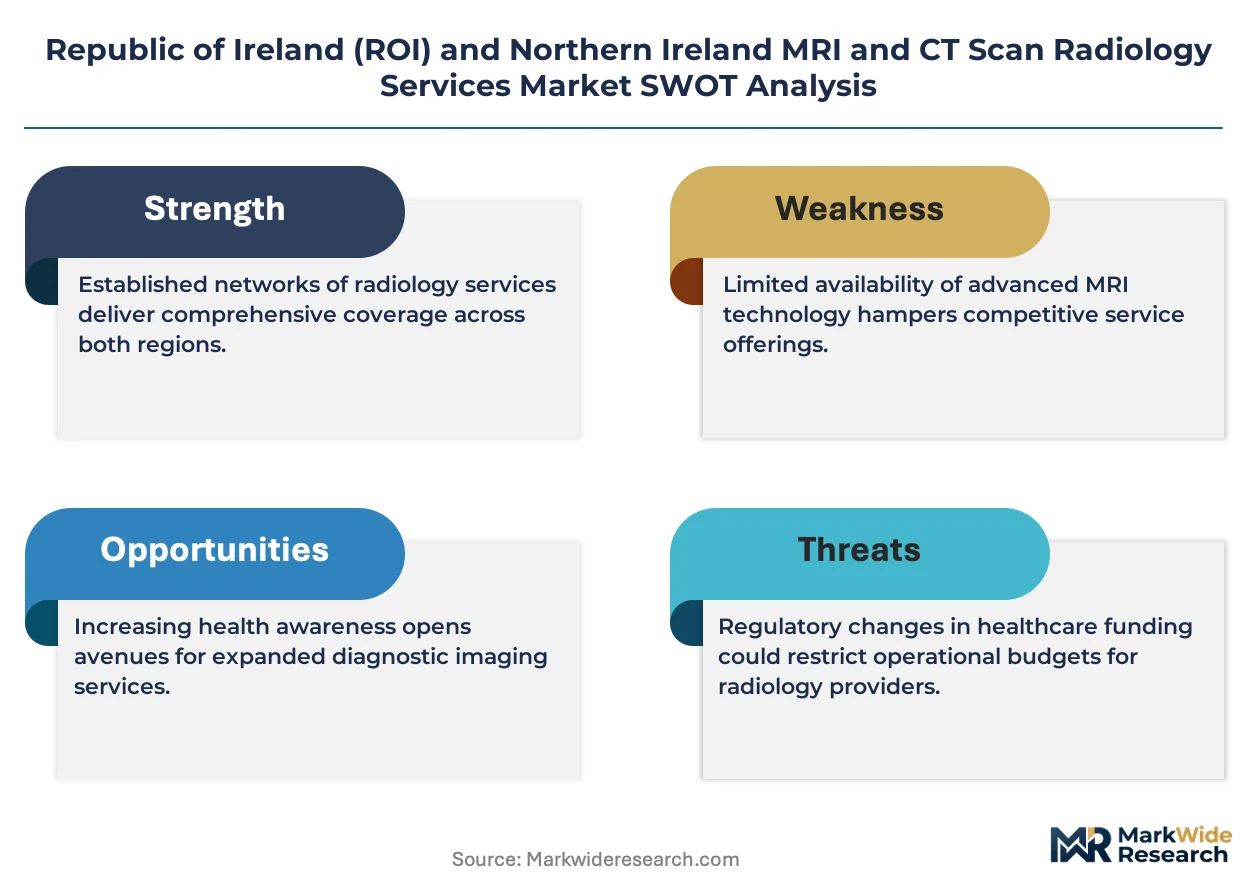
Public hospital networks across Dublin and Belfast are accelerating diagnostic capacity expansion to clear outpatient waiting lists, while HIQA licensing standards and retained EU medical device regulations in Northern Ireland create dual compliance obligations that reshape capital deployment decisions for imaging infrastructure.
Growth Catalysts
- Oncology Imaging Protocols:Complex multi-parametric MRI sequences for cancer staging and treatment-response monitoring drive repeat scan volumes across major teaching hospitals in both jurisdictions.
- EU Green Deal Directives:Energy-efficiency mandates for medical equipment procurement reposition tender criteria toward low-field MRI systems and CT scanners with reduced helium dependency.
- AI-Assisted Workflow Triage:Automated lesion detection algorithms reduce radiologist interpretation burden and expand throughput capacity without proportional staffing increases.
Market Restraints
- Helium Supply Concentration:MRI magnet cooling depends on concentrated global helium production, exposing service operators to price volatility and supply interruption risks.
- Post-Brexit Regulatory Divergence:Northern Ireland's retained EU law under MHRA governance creates compliance friction against Republic of Ireland's continuing EU MDR alignment, complicating cross-border service configuration.
- Fixed Infrastructure Economics:Rural zones in Northern Ireland lack population density to support fixed-site MRI installations, limiting service accessibility outside mobile deployment corridors.
Strategic Opportunities
- Mobile MRI Deployment:Northern Ireland's rural health zones present white-space demand for itinerant imaging services where permanent scanner installation remains economically unviable.
- Multi-Site Accreditation:Private diagnostic chains can capture HSE and NHS referral volumes by achieving HIQA and Care Quality Commission dual accreditation standards that compete with public hospital radiology departments.
- AI-Radiologist Convergence:Integration of automated detection algorithms with PACS workflow creates premium service tiers for complex neurological and oncological indications requiring subspecialist interpretation.
Industry Challenges
- Radiologist Workforce Scarcity:Subspecialty-trained neuroradiologists and oncologic imagers remain concentrated in Dublin and Belfast teaching hospitals, constraining service expansion in peripheral regions.
- Dual Compliance Timelines:Service operators spanning both jurisdictions must maintain parallel quality-assurance protocols under HIQA statutory licensing and UK retained EU law, extending certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market |
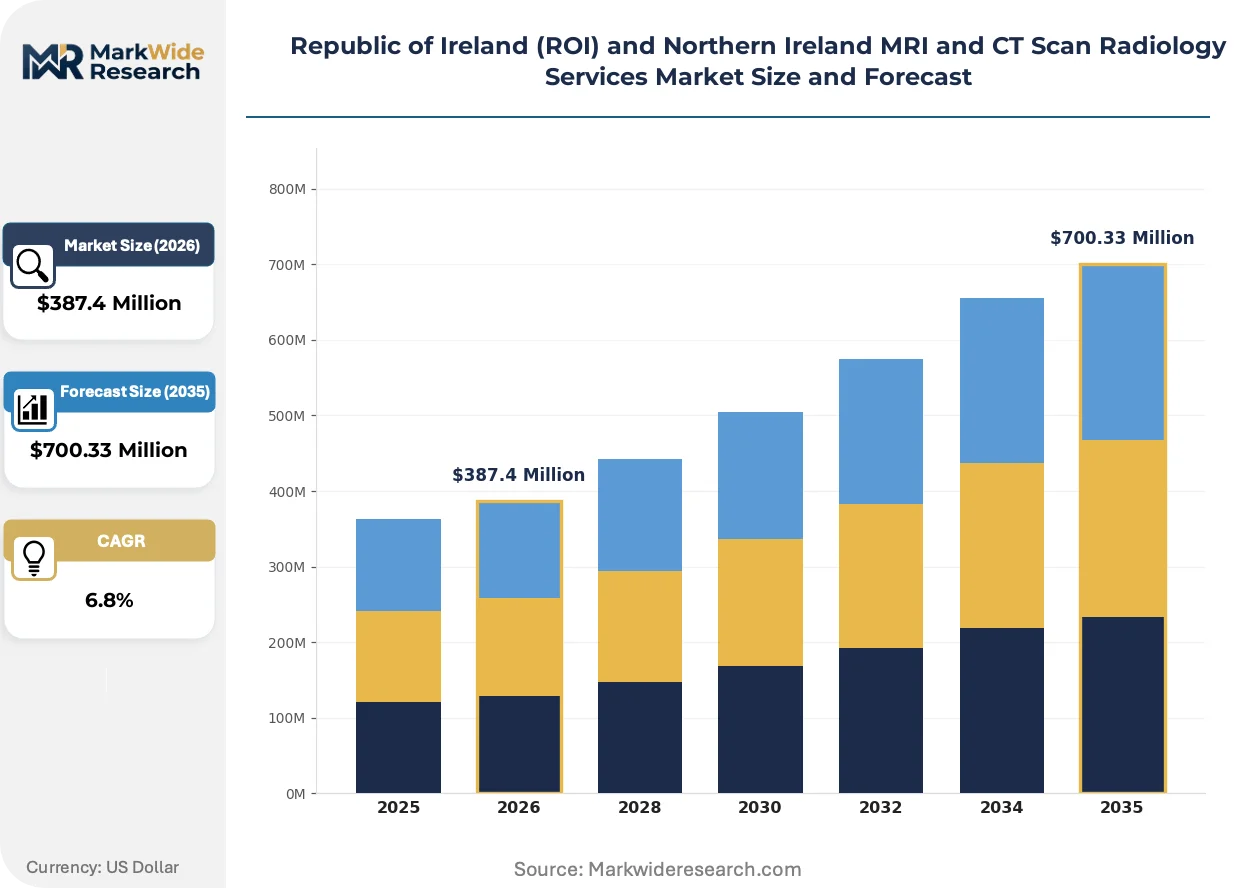
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: MRI, CT Scan, Ultrasound, X-Ray End User: Hospitals, Imaging Centers, Clinics, Research Facilities Technology: Digital Imaging, 3D Imaging, AI Integration, Hybrid Systems Application: Oncology, Neurology, Orthopedics, Cardiology |
| Companies Covered | Siemens Healthineers Ireland, Alliance Medical, Affidea Ireland, GE Healthcare, Philips Healthcare, Johnson & Johnson Ireland Limited, Mater Private Network, Global Diagnostics Ireland, Boston Scientific Ireland Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market Evolving Landscape
Artificial intelligence is restructuring radiology service economics by compressing interpretation timelines and enabling throughput expansion without proportional specialist hiring. Three developments are reshaping competitive positioning.
Deep learning algorithms for automated lesion detection and volumetric tumor assessment are converging with radiologist workflow through PACS integration layers. Major teaching hospitals in Dublin and Belfast are piloting these tools for lung nodule and brain metastasis screening. The technology is converging with teleradiology platforms to enable centralized subspecialist interpretation across distributed scanner networks.
EU MDR retention in Northern Ireland alongside continuing EU alignment in the Republic of Ireland creates a bifurcated conformity assessment environment. Medical device manufacturers must maintain dual technical documentation for CT and MRI systems serving both markets. Imaging service operators face divergent incident reporting obligations that complicate cross-border equipment deployment strategies.
Hospital procurement teams are consolidating radiology service contracts under framework agreements that bundle equipment, maintenance, and interpretation services. This displaces fragmented point-solution purchasing across individual departments. The Republic of Ireland's HSE and Northern Ireland's Department of Health are both centralizing diagnostic imaging procurement to achieve volume leverage.
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market Segmentation
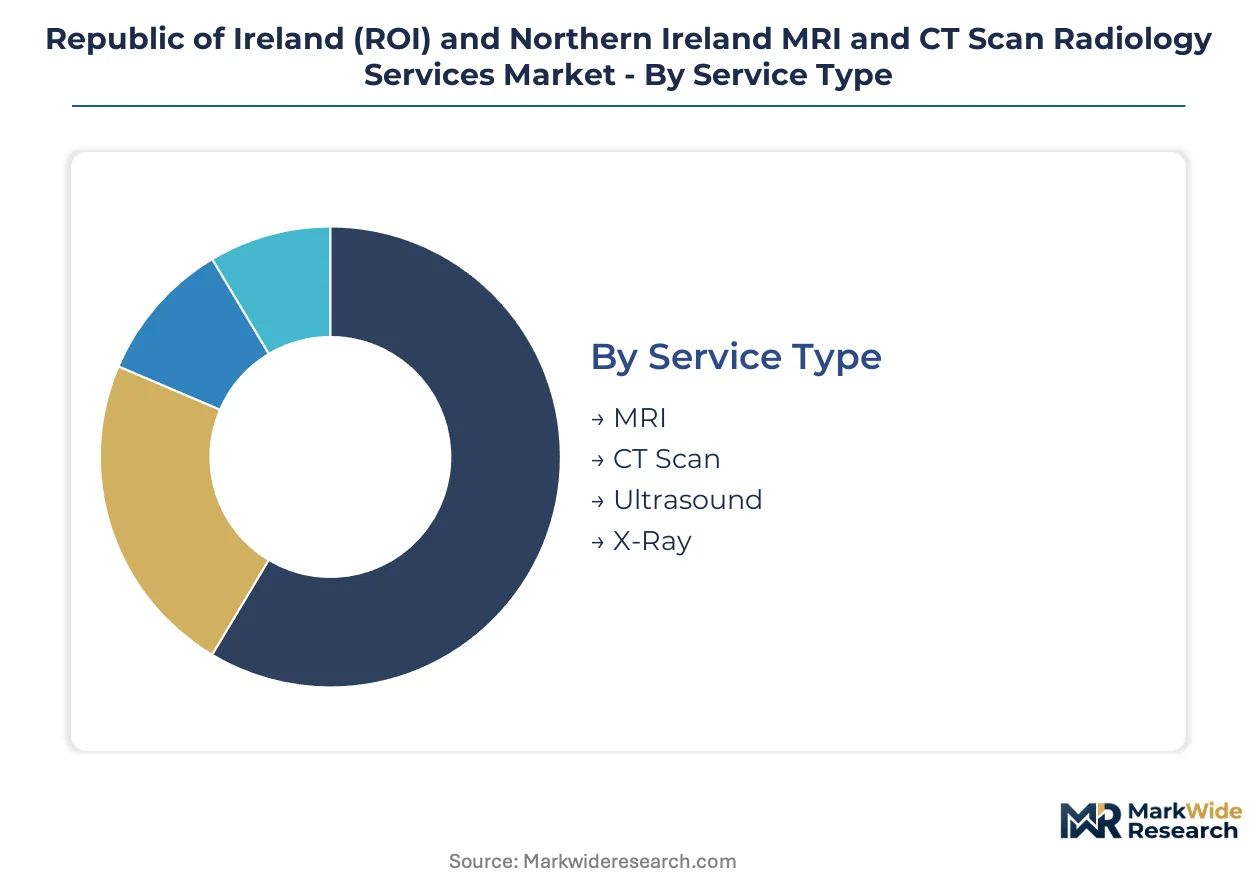
Segmentation across the Republic of Ireland and Northern Ireland MRI and CT scan radiology services market reveals how regulatory frameworks, clinical applications, and technology tiers concentrate procurement decisions. Understanding these divisions exposes where HIQA licensing and MHRA retained EU law impose distinct compliance burdens on service operators.
Service Type:
HIQA statutory licensing applies differential calibration and quality-assurance protocols across modalities, with MRI systems facing the most stringent helium-handling and magnet-maintenance requirements under Ireland's Safety, Health and Welfare at Work Act.
- MRI:Systems operating at 1.5T and 3.0T field strengths generate superior soft-tissue contrast for neurological and oncological staging. Demand concentrates in Dublin's teaching hospitals and Belfast's Royal Victoria Hospital complex, driven by complex multi-parametric imaging protocols for cancer treatment-response monitoring that require serial repeat scans.
- CT Scan:Multi-slice detector arrays from 64 to 320 slices deliver sub-millimeter spatial resolution for trauma and emergency pathways. Deployment concentrates in HSE public hospital networks and Northern Ireland's acute trusts, where rapid throughput requirements for emergency departments override soft-tissue differentiation needs.
- Ultrasound:Portable systems with Doppler capability serve point-of-care diagnostics in rural clinics across Donegal and County Londonderry where fixed scanner infrastructure remains sparse.
- X-Ray:Digital radiography systems anchor screening programs and orthopedic trauma assessment in peripheral HSE hospitals and Northern Ireland's community health centers.
Leading the category by volume: CT Scan. Growing fastest: MRI.
End User:
Procurement authority and reimbursement pathways diverge sharply across customer types, with public hospital networks commanding framework agreements that bundle equipment, maintenance, and interpretation services under centralized HSE and Department of Health contracting.
- Hospitals:Major teaching hospitals in Dublin (St. James's, Mater, Beaumont) and Belfast (Royal Victoria, Belfast City) anchor diagnostic capacity expansion. These institutions drive demand for AI-integrated workflow systems and subspecialist neuroradiologist interpretation for complex neurological indications.
- Imaging Centers:Private diagnostic chains such as Affidea Ireland achieve HIQA and Care Quality Commission dual accreditation to compete directly with public radiology departments for HSE and NHS referral volumes, particularly in Dublin's competitive outpatient market.
- Clinics:General practice and specialist clinics in Galway, Cork, and Derry access teleradiology platforms for centralized interpretation of routine scans, extending subspecialist reach without permanent staffing.
- Research Facilities:Trinity College Dublin and Queen's University Belfast imaging research units pilot novel MRI sequences and AI detection algorithms, generating technology transfer opportunities for clinical deployment.
Volume concentrates in Hospitals. Steepest expansion trajectory: Imaging Centers.
Technology:
Capital deployment decisions increasingly weight energy-efficiency criteria under EU Green Deal procurement directives, repositioning tender evaluations toward low-field MRI systems and CT scanners with reduced helium dependency.
- Digital Imaging:PACS-integrated systems with DICOM compliance form the backbone of radiology workflow across both jurisdictions, enabling image archiving and retrieval that satisfies HIQA data governance requirements.
- 3D Imaging:Volumetric reconstruction capabilities support surgical planning and interventional guidance in cardiac and orthopedic applications, with adoption concentrated in Dublin's private imaging centers and Belfast's cardiac units.
- AI Integration:Automated lesion detection algorithms and workflow triage tools reduce radiologist interpretation burden, expanding throughput capacity without proportional specialist hiring. Pilots for lung nodule and brain metastasis screening are active in major teaching hospitals.
- Hybrid Systems:PET-MRI and PET-CT configurations serve oncology staging and treatment monitoring in specialized centers, limited to Mater Private Dublin and Belfast City Hospital due to capital intensity and radiopharmaceutical supply requirements.
Highest installed base: Digital Imaging. Gaining share fastest: AI Integration.
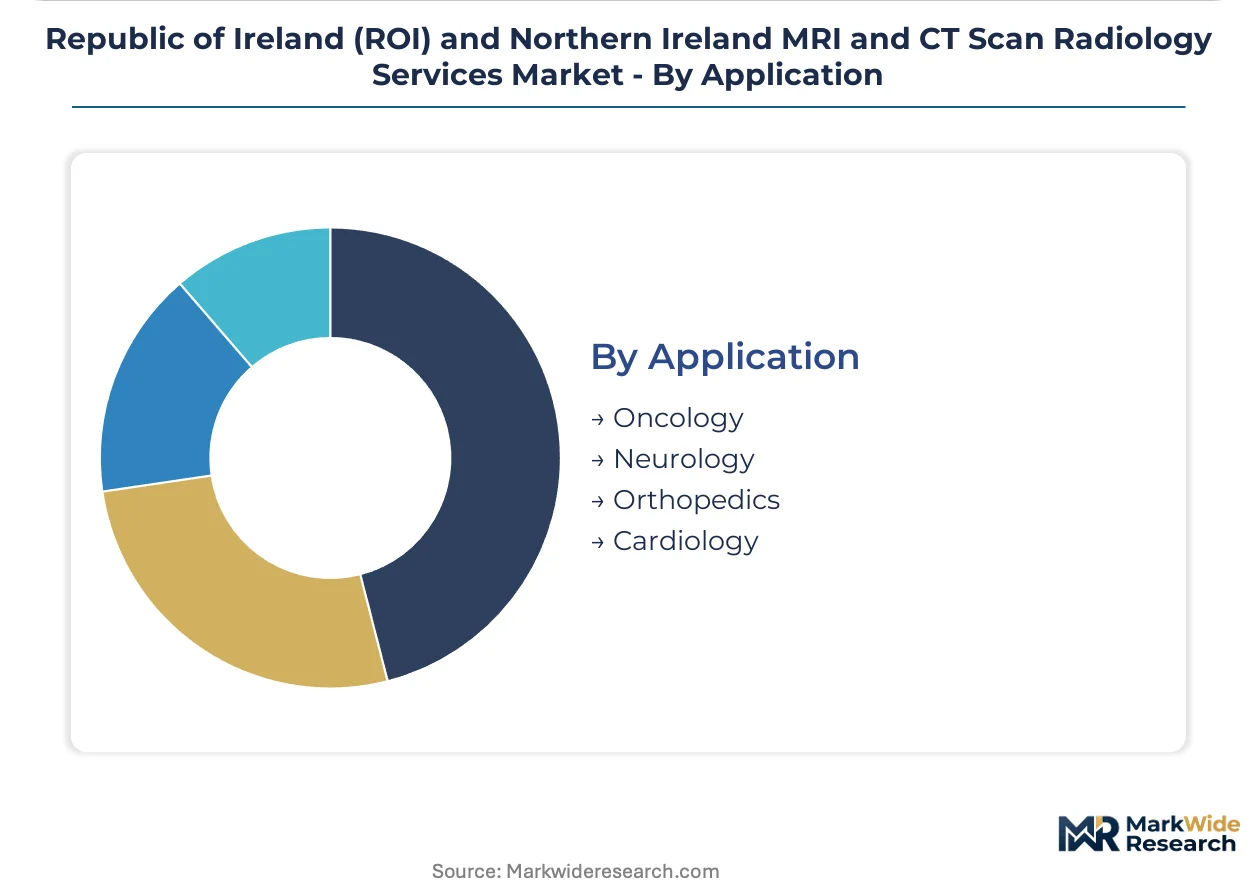
Application:
Margin pools concentrate in oncology and neurology where multi-parametric imaging protocols demand subspecialist interpretation and serial monitoring generates repeat scan volumes.
- Oncology:Complex staging protocols and treatment-response assessment drive premium pricing for multi-parametric MRI sequences. Demand concentrates in Dublin's St. James's Hospital and Belfast's Northern Ireland Cancer Centre, where multidisciplinary tumor boards mandate standardized imaging pathways.
- Neurology:Brain metastasis screening, multiple sclerosis monitoring, and stroke protocol imaging require subspecialist neuroradiologist interpretation. Workforce scarcity in peripheral regions limits service expansion outside Dublin and Belfast teaching hospital networks.
- Orthopedics:MRI dominates soft-tissue and joint assessment for sports medicine and trauma, with high throughput in Cork's private imaging centers and Northern Ireland's elective orthopedic hubs.
- Cardiology:CT coronary angiography and cardiac MRI for viability assessment serve growing demand in Dublin's Mater Private and Belfast's cardiac institutes, though reimbursement pathways remain less established than in oncology.
Revenue concentration: Oncology. Expanding most quickly: Neurology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dublin anchors diagnostic imaging demand across the island, with St. James's Hospital and the Mater complex driving complex MRI protocol volumes for oncology and neurology staging.
Dublin and Eastern Region
The HSE's hospital network concentrates multi-parametric MRI capacity for cancer treatment monitoring, with St. James's Hospital and Beaumont Hospital handling complex neurological referrals. HIQA licensing standards filter subscale operators from designated center status. Private imaging chains compete directly with public radiology departments for outpatient referrals in this dense metropolitan corridor.
Cork and Southern Region
Cork University Hospital anchors CT throughput for emergency and trauma pathways across Munster, while private orthopedic imaging centers capture sports medicine demand. Ireland's Safety, Health and Welfare at Work Act governs ionizing radiation protocols for scanner installations. The city's imaging research collaboration with University College Cork pilots novel MRI sequences for clinical translation.
Galway and Western Region
University Hospital Galway manages regional neurology referrals with limited subspecialist neuroradiologist coverage, creating teleradiology dependency for complex interpretations. HSE procurement frameworks bundle equipment and maintenance contracts to achieve volume leverage. Rural clinics across Mayo and Donegal rely on mobile ultrasound deployment where fixed CT infrastructure remains sparse.
Belfast and Northern Region
The Royal Victoria Hospital and Belfast City Hospital complex concentrate Northern Ireland's diagnostic capacity for oncology staging and cardiac imaging. MHRA retained EU law governs medical device conformity assessment alongside Health and Safety Executive for Northern Ireland radiation enforcement. The Northern Ireland Cancer Centre mandates standardized imaging pathways for multidisciplinary tumor boards.
Derry and Western Northern Ireland
Altnagelvin Area Hospital serves as the western anchor for acute imaging, with mobile MRI units filling gaps in County Londonderry and Tyrone where permanent scanner economics fail. NHS commissioning frameworks prioritize reducing outpatient waiting lists through capacity expansion. Alliance Medical's mobile deployment corridor extends services to these peripheral zones.
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market Competitive Landscape
The competitive structure tilts toward equipment manufacturers with established service networks and private diagnostic chains with multi-site accreditation. Siemens Healthineers Ireland leverages its installed magnet base to sustain long-term maintenance contracts across HSE facilities. Two strategic archetypes dominate: integrated equipment-service providers and accredited private imaging networks. Competitive moves center on framework contract consolidation and AI-integrated workflow partnerships.
Within the equipment-service tier, Siemens Healthineers Ireland and GE Healthcare anchor manufacturer presence through magnet technology and imaging system deployment. Alliance Medical exemplifies the mobile imaging archetype, while Affidea Ireland represents multi-site private diagnostic accreditation competing for HSE and NHS referral volumes. These three occupy positions spanning equipment supply, itinerant service delivery, and fixed-site private diagnostics.
| Leading Market Players |
|---|
| Siemens Healthineers Ireland |
| Alliance Medical |
| Affidea Ireland |
| GE Healthcare |
| Philips Healthcare |
| Johnson & Johnson Ireland Limited |
| Mater Private Network |
| Global Diagnostics Ireland |
| Boston Scientific Ireland Ltd |
| Others |
Value Network & Pricing Analysis
EU Green Deal medical equipment energy-efficiency directives gate qualified supply access and premium-tier pricing for imaging service operators across Irish health systems. These procurement criteria favor low-field MRI systems and reduced-helium CT configurations, compressing margins for legacy high-field installations while rewarding compliant equipment with framework contract eligibility.
Pricing Analysis
Value-based pricing anchored to scan throughput and diagnostic yield dominates HSE and NHS framework agreements. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated subspecialist interpretation from routine teleradiology reads and bulk emergency CT throughput. Cost compression in standard-tier services is intensifying because radiologist workforce scarcity forces competitive compensation bidding. General practice clinics accessing teleradiology platforms exhibit highest price sensitivity; major teaching hospitals with mandated oncology pathways show lowest sensitivity due to clinical outcome imperatives.
Supply Chain Analysis
Domestic-content mandates under Ireland's Safety, Health and Welfare at Work Act reshape sourcing toward EU-registered equipment service providers with local calibration certification. MRI magnet manufacturing concentrates in Germany, the Netherlands, and the United States; helium supply draws from Qatar, the United States, and Algeria. Single-source vulnerability in superconducting wire and liquid helium creates procurement risk for 3.0T system operators. Distribution runs through manufacturer-direct service contracts with HSE procurement frameworks, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as AI-assisted workflow triage replaces legacy radiologist-intensive interpretation models. Automated lesion detection algorithms are compressing turnaround timelines and enabling throughput expansion without proportional specialist hiring.
For Market Incumbents: Extend AI-integrated service contracts across the HSE hospital network to lock out emerging teleradiology platforms. Deepen magnet technology service relationships at St. James's Hospital and Beaumont Hospital to defend against Alliance Medical's mobile deployment expansion. Invest in dual HIQA-CQC accreditation to capture cross-border NHS referral volumes before regulatory divergence hardens.
For New Entrants and Emerging Players: Begin with mobile MRI deployment corridors in County Londonderry and Tyrone where fixed infrastructure economics fail and Alliance Medical has limited coverage. Target teleradiology partnerships with University Hospital Galway and peripheral HSE clinics facing neuroradiologist scarcity. Pursue outcome-based contracting with NHS Northern Ireland to differentiate from incumbent equipment vendors.
For Investors and Strategic Acquirers: First major NHS Northern Ireland framework award to a private imaging chain is the leading indicator that public procurement is shifting toward accredited private operators. Five-to-ten-year viability favors multi-site diagnostic networks with dual-jurisdiction compliance infrastructure over pure equipment manufacturers. Monitor HIQA licensing backlog clearance rates as the signal for market access timing.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Radiologist Workflow Integration | PACS-embedded lesion detection algorithms at Mater Private reduce interpretation burden without specialist expansion. |
| Mobile MRI Deployment Expansion | Itinerant imaging units in Northern Ireland's rural zones capture demand outside fixed-site economic viability. |
| Dual Accreditation Investment | HIQA and CQC certification enables Affidea Ireland to compete directly for HSE and NHS referral volumes. |
| Low-Field MRI Procurement Pivot | EU Green Deal compliance positions operators for HSE framework eligibility amid helium supply volatility. |
| Teleradiology Platform Development | Centralized subspecialist interpretation extends neuroradiologist reach to Galway and Cork peripheral clinics. |
Research Methodology
Multi-period observation of scanner installation rates, HIQA licensing approvals, and NHS commissioning awards anchored the trend analysis, supplemented by interviews with hospital procurement managers, biomedical engineers, neuroradiologists, and GPO contracts managers. Secondary validation drew from HSE capital expenditure disclosures, NHS Northern Ireland service specifications, MHRA medical device registration databases, and EU MDR technical documentation requirements. Bottom-up modeling of individual hospital network capacity expansion triangulated against top-down health system budget allocation analysis.
Input-output matrix framing connected modality-specific demand drivers to installed base depreciation schedules and replacement cycles across the projection horizon. Segmentation dimensions modeled include service type, end-user category, technology tier, and clinical application, with cross-cutting analysis of public-versus-private procurement pathway splits. CAGRs were derived from weighted least-squares trend fitting to historical capacity data, adjusted for regulatory approval timelines and framework contract award patterns.
Underlying measurement precision varies by segment; oncology and neurology application forecasts carry tighter precision than orthopedic and cardiology projections due to standardized imaging pathway mandates. Forecasts reflect assumptions regarding helium supply stability, radiologist workforce pipeline recovery, and post-Brexit regulatory alignment maintenance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Open System MRI Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Australia Magnetic Resonance Imaging Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
United Kingdom Nuclear Imaging Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
Global Technetium-99M Market