
 Global Mammography Systems Market | 2026-2036
Global Mammography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mammography Systems Market Foresight
Digital breast tomosynthesis is fragmenting the traditional two-dimensional mammography installed base as healthcare systems recalibrate capital allocation toward volumetric imaging platforms. Hologic Inc. anchors the North American market through deep manufacturing scale in 3D-enabled systems. Siemens Healthineers AG competes on integrated workflow solutions that span detection through biopsy guidance. GE HealthCare leverages its imaging informatics backbone to sustain service contract renewals across hospital networks.
Mammography systems are X-ray-based diagnostic platforms engineered to detect breast tissue anomalies, with modern units operating at 25-35 kVp tube voltage and incorporating solid-state detectors capable of resolving microcalcifications below 100 microns. Their primary purpose is population-scale breast cancer screening and diagnostic workup in clinical settings. Full field digital technology leads installed capacity but 3D tomosynthesis captures the fastest expansion as reimbursement codes in multiple countries now cover supplemental screening. Portable mammography occupies a niche serving mobile screening units and rural access programs where fixed-room infrastructure remains uneconomical.
FDA premarket notification requirements and EU MDR technical documentation obligations are extending product launch timelines and elevating quality management investments for manufacturers seeking multi-regional market access. Japan's PMDA enforces JIS-aligned radiation safety standards that shape detector calibration protocols for systems deployed in that market. Stakeholders must monitor evolving screening age recommendations from national oncology bodies and corresponding reimbursement adjustments that directly influence hospital procurement cycles.
Market Dynamics
Digital breast tomosynthesis is virtualizing the installed base of two-dimensional mammography systems as healthcare systems redirect capital toward volumetric imaging platforms capable of resolving microcalcifications below 100 microns.
Growth Catalysts
- Population screening mandates:National oncology bodies in Japan, Germany, and the United States sustain replacement cycles through age-based screening recommendations and reimbursement coverage for supplemental 3D imaging.
- FDA premarket pathways:Streamlined 510(k) clearance processes for iterative detector improvements accelerate product refresh timelines for manufacturers with established quality management systems.
- Solid-state detector advances:Amorphous selenium and cesium iodide technologies enable single-exposure tomosynthesis acquisition, reducing radiation dose while maintaining spatial resolution for dense breast tissue.
Market Restraints
- Capital intensity of 3D systems:Full-field digital mammography with tomosynthesis capability requires room renovation, HVAC upgrades, and shielding compliance that strain rural hospital budgets.
- EU MDR technical documentation:Extended conformity assessment timelines for Class IIb devices delay multi-regional product launches and elevate post-market surveillance obligations.
- Supply concentration in detector substrates:Thin-film transistor manufacturing concentrates in East Asian foundries, creating single-source vulnerability for flat-panel detector assembly.
Strategic Opportunities
- Mobile screening units:Portable mammography systems address access gaps in rural India and sub-Saharan Africa where fixed-room infrastructure remains uneconomical and technician density is low.
- Artificial intelligence integration:Computer-aided detection algorithms paired with tomosynthesis datasets reduce radiologist reading time and enable centralized teleradiology services.
- Japan PMDA radiation safety alignment:JIS-standard detector calibration protocols create first-mover advantage for manufacturers certifying to the country's dose optimization requirements.
Industry Challenges
- Specialized service engineering scarcity:Field technicians capable of solid-state detector calibration and tube head alignment are concentrated in urban medical device hubs, limiting rural deployment velocity.
- Legacy PACS integration complexity:Hospital networks with decade-old picture archiving systems face middleware costs and workflow disruption when connecting to modern DICOM-structured tomosynthesis datasets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mammography Systems Market |
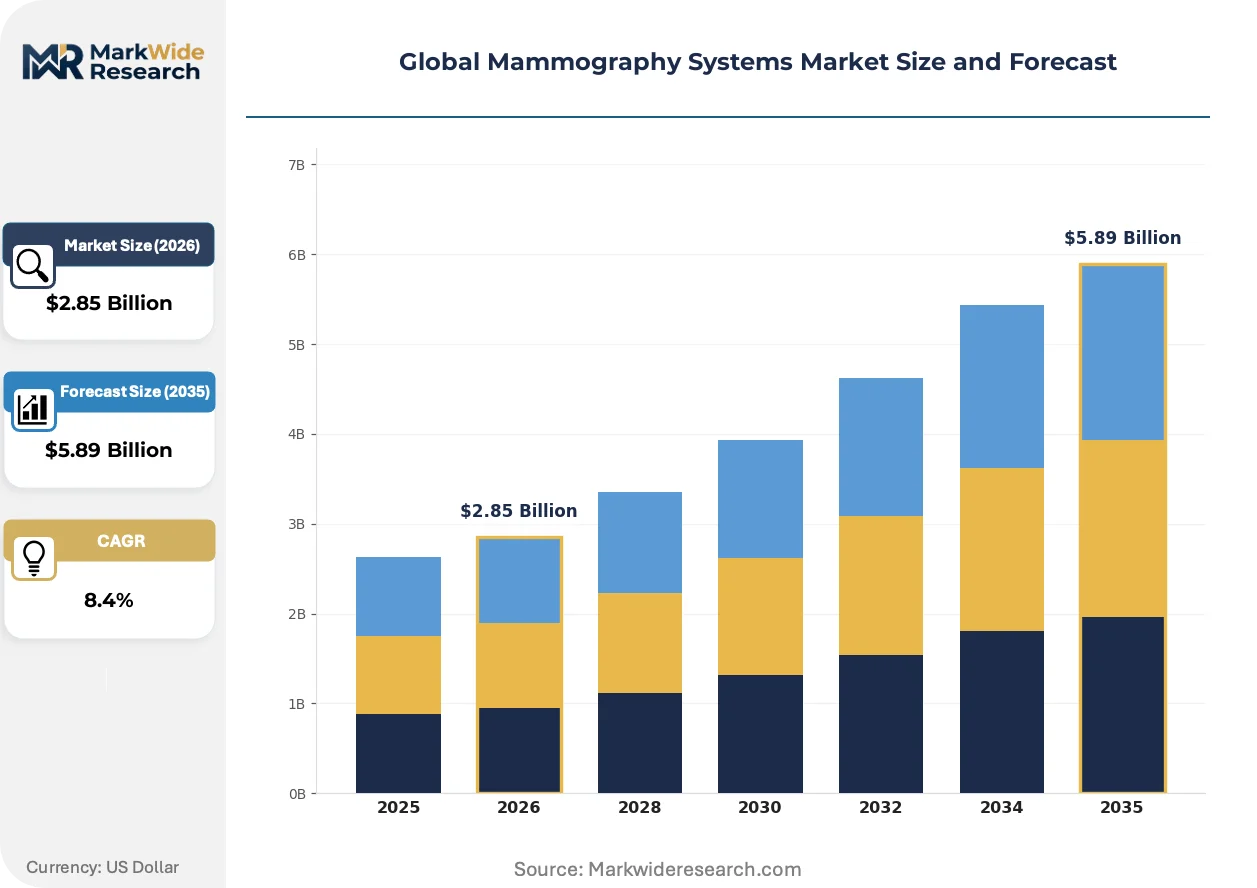
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography, Analog Mammography, 3D Tomosynthesis, Computer-Aided Detection, Portable Mammography Technology: Full Field Digital, Film Screen, Contrast-Enhanced, Ultrasound-Assisted, Automated Breast Ultrasound Application: Breast Cancer Screening, Diagnostic Imaging, Risk Assessment, Treatment Monitoring, Research End User: Diagnostic Centers, Imaging Clinics, Research Institutions, Mobile Screening Units, Specialty Hospitals |
| Companies Covered | Hologic Inc., GE HealthCare, Siemens Healthineers AG, FUJIFILM Corporation, Koninklijke Philips NV, Planmed OY, Canon Medical Systems Corporation, Metaltronica S.p.A., Analogic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mammography Systems Market Shifts & Advancements
Three concurrent developments are compressing product lifecycles and redistributing value capture across the mammography value chain: detector virtualization, regulatory harmonization friction, and procurement model atomization.
Photon-counting detector technology is virtualizing the signal-to-noise performance of conventional energy-integrating systems. Academic medical centers in the United States and university hospitals in Germany are piloting cadmium-zinc-telluride direct-conversion panels that eliminate electronic noise from scintillator layers. This architecture is virtualizing the dose-resolution tradeoff that has constrained screening intervals for dense breast populations.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for legacy system manufacturers. Notified bodies now mandate clinical evidence packages for software-driven image reconstruction algorithms that previously qualified as substantial equivalents. European hospital procurement committees are delaying replacement decisions until manufacturers secure renewed CE certificates, compressing near-term sales visibility.
After-sales service contracts are unbundling from hardware purchase agreements as third-party ISO-certified service organizations enter detector calibration and tube replacement markets. Independent service organizations in the United States are capturing preventive maintenance revenue from hospital networks seeking to reduce OEM dependency. This disintermediation is most visible in multi-site health systems with centralized biomedical engineering departments capable of performing solid-state detector quality assurance protocols in-house.
Global Mammography Systems Market Segmentation
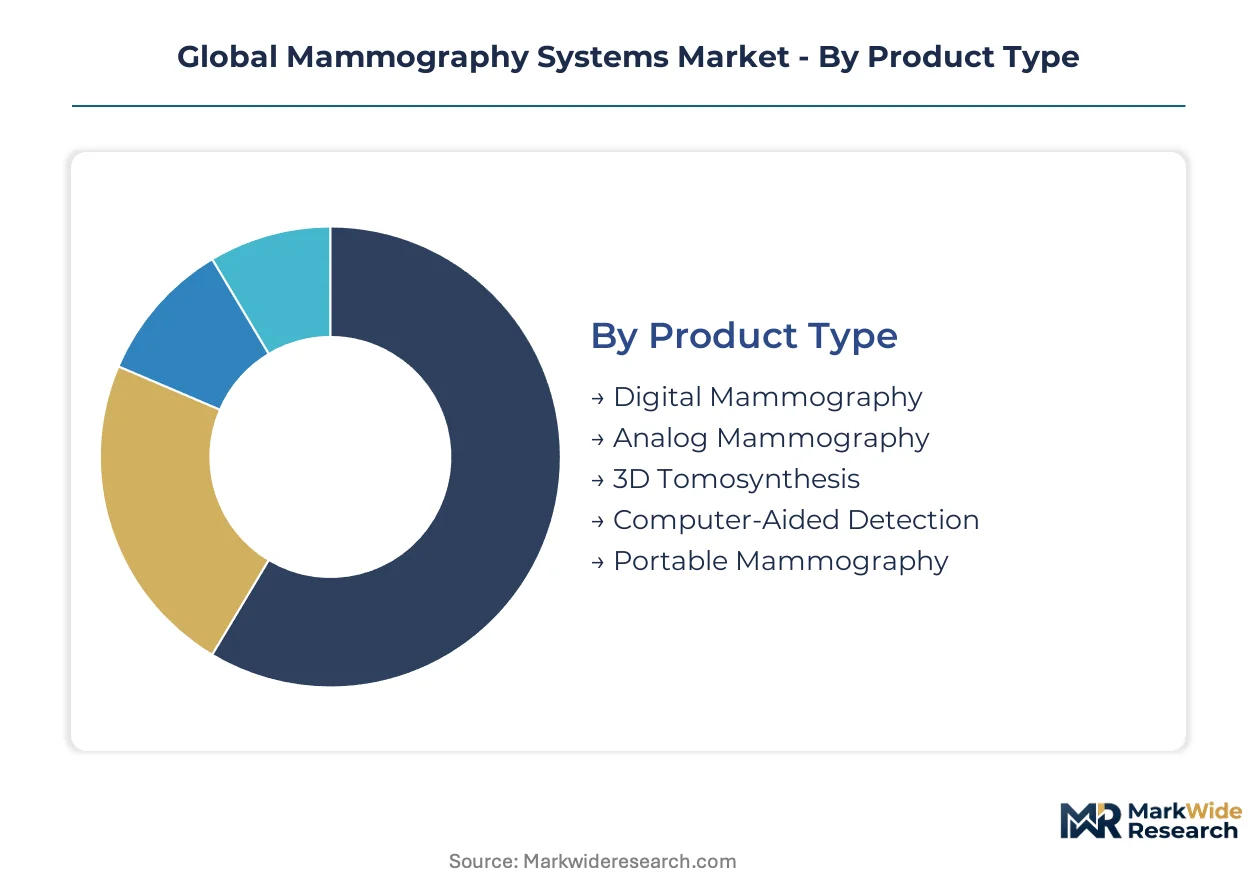
Procurement patterns in mammography systems diverge sharply across product architectures and care settings. Service contract structures, detector replacement cycles, and regulatory compliance burdens vary by segment, reshaping vendor-customer relationships and lifetime value calculations.
Product Type:
After-sales-service intensity climbs steeply with detector complexity and software dependency, concentrating margin capture in 3D tomosynthesis and digital platforms while analog systems commoditize.
- 3D Tomosynthesis:Volumetric acquisition systems with iterative reconstruction algorithms demand specialized field engineers for detector calibration and tube alignment. Hospital networks in the United States and Germany prioritize these units for dense breast populations, though capital requirements and room renovation costs constrain rural deployment.
- Digital Mammography:Full-field systems with amorphous selenium or cesium iodide detectors dominate installed capacity. Replacement demand concentrates in Japan and the United States where aging first-generation digital units require detector refresh cycles and software upgrades to maintain DICOM compliance.
- Analog Mammography:Film-screen systems persist in price-sensitive markets with limited infrastructure, requiring minimal service intervention beyond mechanical maintenance.
- Computer-Aided Detection:Software modules for lesion flagging and workflow triage integrate with primary imaging platforms, generating recurring license revenue rather than hardware service contracts.
- Portable Mammography:Compact units with battery-powered operation and wireless DICOM transmission serve mobile screening programs in India and sub-Saharan Africa, where field service networks remain sparse and remote diagnostics drive maintenance complexity.
By volume, Digital Mammography leads. By growth pace, 3D Tomosynthesis is ahead.
Technology:
Cost tier stratification separates premium direct-conversion detectors from economy scintillator-based systems, with price spreads exceeding 40% between photon-counting pilots and conventional energy-integrating panels.
- Full Field Digital:Amorphous silicon TFT arrays with cesium iodide scintillators constitute the volume baseline. Academic medical centers in Germany and the United States are piloting cadmium-zinc-telluride direct-conversion panels that eliminate electronic noise, though unit economics currently restrict adoption to research budgets.
- Automated Breast Ultrasound:Mechanical sweep systems for dense breast supplemental screening capture growing share in Japan, where PMDA radiation dose guidelines incentivize non-ionizing alternatives for younger screening cohorts.
- Film Screen:Analog capture technology with chemical processing persists in resource-constrained settings where electricity reliability and digital infrastructure remain inadequate.
- Contrast-Enhanced:Iodinated contrast protocols for lesion characterization occupy a narrow diagnostic niche, requiring pharmacy integration and adverse event preparedness that elevate operational overhead.
- Ultrasound-Assisted:Hand-held adjunctive systems for targeted diagnostic workup complement primary mammography without replacing screening workflows.
Full Field Digital holds the largest installed base. Automated Breast Ultrasound is climbing the fastest as dense breast protocols expand.
Application:
Customer type fragmentation splits procurement between centralized screening programs with government reimbursement contracts and decentralized diagnostic centers with private payor negotiations.
- Breast Cancer Screening:Population-scale programs with age-based eligibility criteria drive volume procurement in Japan, Germany, and the United States. National oncology body recommendations directly influence replacement cycles and technology upgrade timing.
- Diagnostic Imaging:Symptomatic workup and callback evaluation require higher-resolution capabilities and biopsy guidance integration, concentrating demand in specialty hospitals and comprehensive cancer centers.
- Risk Assessment:Genetic counseling and high-risk surveillance protocols for BRCA-positive populations utilize supplemental MRI and ultrasound, with mammography serving as a baseline modality rather than primary tool.
- Treatment Monitoring:Neoadjuvant therapy response evaluation and post-surgical surveillance generate recurring imaging demand with standardized protocols.
- Research:Clinical trial imaging cores and academic biobanks require specialized phantoms, dose calibration documentation, and regulatory submission support that extend vendor engagement beyond equipment sale.
Breast Cancer Screening dominates procedure volume. Diagnostic Imaging is gaining share fastest as callback rates from 3D tomosynthesis expand downstream workup demand.
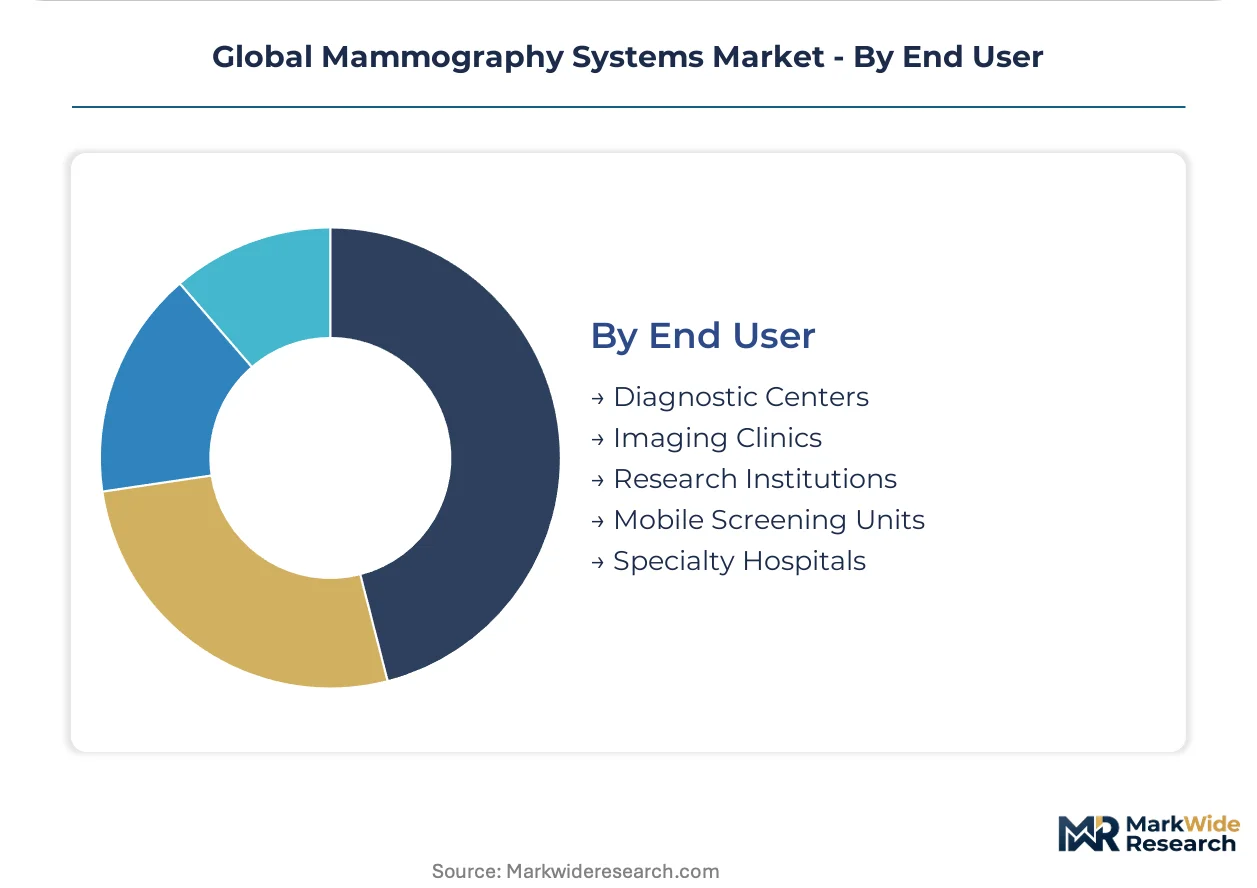
End User:
Geography of demand clusters in urban corridors with radiologist density, while supply concentration in detector manufacturing creates fulfillment bottlenecks for remote deployments.
- Diagnostic Centers:Dedicated breast imaging facilities with MQSA certification in the United States and equivalent accreditation in Germany achieve higher throughput and faster amortization of 3D systems through centralized screening contracts.
- Imaging Clinics:Multi-modality outpatient centers balance mammography with MRI and CT, requiring PACS integration and workflow optimization that favor vendors with informatics portfolios.
- Mobile Screening Units:Trailer-based and van-deployed systems address access gaps in rural India and sub-Saharan Africa, where technician density is low and preventive maintenance schedules must accommodate irregular power supply and road vibration stress.
- Specialty Hospitals:Comprehensive cancer centers with on-site biopsy and surgical oncology integration prioritize tomosynthesis-guided stereotactic capability.
- Research Institutions:Academic medical centers with NIH or EU Horizon funding drive pilot adoption of photon-counting detectors and AI validation studies, though commercial scale remains distant.
Diagnostic Centers lead by installed base. Mobile Screening Units are expanding most quickly as national health systems prioritize access equity in underserved regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export digital mammography systems to hospital networks across the United States and Japan, while Japanese detector substrate suppliers feed assembly lines in South Korea and Taiwan.
United States
Hospital-based breast cancer screening programs and MQSA-certified diagnostic centers drive procurement of 3D tomosynthesis units. FDA 510(k) premarket notification pathways govern iterative detector improvements and software upgrades. The Boston-Cambridge medical device cluster anchors manufacturing scale for solid-state detector calibration protocols serving dense breast populations.
Germany
Comprehensive cancer centers and university hospitals prioritize integrated workflow solutions spanning detection through biopsy guidance. EU MDR Article 10 technical documentation requirements extend conformity assessment timelines for Class IIb devices. The Erlangen-Munich corridor concentrates Siemens Healthineers AG manufacturing and service engineering capabilities for volumetric imaging platforms.
Japan
Aging demographics and national screening mandates sustain replacement cycles for full-field digital systems. PMDA enforces JIS-aligned radiation safety standards shaping detector calibration protocols. The Tokyo-Osaka metropolitan corridor hosts academic medical centers piloting photon-counting detector technology and AI validation studies.
India
Mobile screening units and rural access programs generate demand for portable mammography systems where fixed-room infrastructure remains uneconomical. CDSCO medical device registration requirements govern import and distribution of imaging equipment. The Mumbai-Pune and Bengaluru-Chennai corridors concentrate diagnostic center networks and third-party service organizations performing preventive maintenance.
China
Provincial hospital networks expand procurement of digital systems as breast cancer screening coverage broadens. NMPA premarket approval pathways and GB standards for radiation safety shape product entry requirements. The Yangtze River Delta and Pearl River Delta clusters concentrate flat-panel detector manufacturing and thin-film transistor foundry capacity.
Global Mammography Systems Market Competitive Landscape
On the supply side, the industry is consolidated around a handful of integrated imaging conglomerates with deep manufacturing scale in detector substrates and tube head assembly. Tiered competitive positioning separates premium-tier vendors with full informatics portfolios from mid-scale specialists in portable configurations and economy-tier assemblers of analog systems. Dominant competitive moves include strategic partnerships for AI algorithm integration and geographic expansion through localized service networks in emerging markets.
Within the integrated imaging conglomerate tier, Hologic Inc. and GE HealthCare represent archetypal North American anchors with established hospital network relationships, while Siemens Healthineers AG exemplifies the European workflow-integrated model. These three occupy positions defined by manufacturing depth in 3D-enabled systems, service contract renewal velocity, and imaging informatics backbone capabilities rather than discrete product differentiation.
| Leading Market Players |
|---|
| Hologic Inc. |
| GE HealthCare |
| Siemens Healthineers AG |
| FUJIFILM Corporation |
| Koninklijke Philips NV |
| Planmed OY |
| Canon Medical Systems Corporation |
| Metaltronica S.p.A. |
| Analogic Corporation |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta freight corridor channels thin-film transistor substrates from East Asian foundries to detector assembly plants, with logistics cost volatility amplifying pricing power for consolidated upstream suppliers while forcing tiered equipment pricing downstream. This corridor's throughput constraints intersect with FDA and EU MDR compliance timelines to stretch working capital cycles for manufacturers caught between extended certification periods and fixed-price hospital procurement contracts.
Pricing Analysis
Three-generation pricing stratification separates photon-counting pilots at premium levels, energy-integrating 3D tomosynthesis at standard tiers, and refurbished digital systems at economy entry points. Three-tier pricing structure across premium, standard, and economy levels reflects detector substrate grade, FDA 510(k) versus PMA certification pathway, and bundled service contract duration. Cost compression in the economy tier intensifies as independent service organizations capture preventive maintenance revenue previously retained by OEMs. Rural hospital networks exhibit highest price sensitivity due to capital budget constraints, while academic medical centers with NIH funding demonstrate lowest sensitivity for pilot-generation photon-counting systems.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now characterize supplier-finance arrangements for amorphous selenium and cesium iodide detector substrate procurement. Manufacturing concentrates in China, South Korea, and Taiwan for thin-film transistor arrays, with Japan supplying precision tube head components and Germany contributing iterative reconstruction software modules. Raw material dependencies center on high-purity selenium, iodine crystal substrates, and rare-earth phosphors. Single-source vulnerability in East Asian foundry capacity for TFT backplanes creates fulfillment risk for flat-panel detector assembly. Distribution runs through hospital GPO contracts in the United States, regional equipment distributors in Germany, and government tender processes in Japan and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as AI algorithm marketplaces and teleradiology networks transform mammography from discrete hardware sales to interoperable imaging ecosystems. DICOM-structured tomosynthesis datasets now serve as the interoperability layer connecting detector hardware, computer-aided detection software, and centralized reading services.
For Market Incumbents: Harden service contract renewal velocity through embedded detector calibration telemetry that raises switching costs for hospital networks. Deepen backward integration into amorphous selenium substrate production to offset East Asian foundry concentration risk. Lock in MQSA-certified diagnostic centers with multi-year tomosynthesis upgrade schedules before third-party ISO-certified service organizations capture preventive maintenance share.
For New Entrants and Emerging Players: Portable mammography systems for mobile screening units in rural India and sub-Saharan Africa represent the most penetrable entry point, with battery-powered operation and wireless DICOM transmission addressing infrastructure gaps. AI-powered computer-aided detection modules for lesion flagging offer software-only market entry without capital-intensive detector manufacturing. Partner with established teleradiology networks for distribution rather than building direct hospital sales forces.
For Investors and Strategic Acquirers: Independent service organizations with ISO-certified detector calibration capabilities and multi-site health system contracts present the most attractive acquisition archetype for platform consolidation. Long-term viability hinges on transition from hardware-centric revenue to recurring software and service income streams. Watch FDA premarket approval pathway streamlining for iterative AI algorithms as the signal indicating accelerated value capture shift toward software-enabled incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI Algorithm | Accelerates computer-aided detection market entry through streamlined premarket notification. |
| CE Marking Pathway Under EU MDR | Extends conformity assessment timelines but secures multi-regional hospital procurement eligibility. |
| Hospital System Partnership for Screening Programs | Locks in replacement cycle timing through centralized GPO contract structures. |
| Software Companion Development for Tomosynthesis | Captures recurring license revenue beyond one-time hardware sales. |
| Reimbursement Strategy for 3D Supplemental Screening | Aligns procurement decisions with national oncology body coverage recommendations. |
Research Methodology
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and radiology department heads converged on the working assumptions driving segmentation models and replacement cycle timing. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR notified body guidance documents, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up unit economics for detector replacement cycles and top-down screening program budget allocations were triangulated to anchor volume projections.
Demand-supply balance framing shaped the analytical approach, with hospital capital expenditure cycles and national screening mandate expansions on the demand side matched against thin-film transistor foundry capacity and tube head manufacturing output on the supply side. Segmentation dimensions modeled include product architecture, detector technology generation, application purpose, and end-user facility type across the projection horizon. CAGRs were derived from fitted growth curves applied to replacement cycle data and reimbursement code expansion schedules, with photon-counting detector pilot adoption and AI algorithm integration velocity serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in hospital capital budget availability, medical device tariff structures, or radiation safety standard revisions would shift the trajectory. Forecasts reflect documented assumptions about screening age recommendation stability and reimbursement code permanence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Nuclear Imaging Devices Market
Medical Imaging
France Mammography Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Global MRI Scanner Market