
 Middle East and Africa Magnetic Resonance Imaging (MRI) Market | 2026-2036
Middle East and Africa Magnetic Resonance Imaging (MRI) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Magnetic Resonance Imaging (MRI) Market Foresight
Software-defined service contracts for remote diagnostics and predictive maintenance is consolidating vendor revenue streams across the Middle East and Africa MRI landscape. Siemens Healthineers leverages its regional service infrastructure to anchor long-term hospital partnerships in the Gulf. Canon Medical Systems Corporation competes through specialized extremity MRI configurations tailored to outpatient clinic networks. Koninklijke Philips N.V. extends its position via integrated workflow software that connects radiology departments across multi-site health systems.
Magnetic Resonance Imaging employs superconducting magnets generating field strengths from 1.5 to 7.0 Tesla to excite hydrogen nuclei and reconstruct tomographic images of soft tissues, organs, and neural structures without ionizing radiation. Closed MRI systems dominate installed base volumes due to superior signal-to-noise ratios required for neurovascular and abdominal diagnostics. High-Field MRI technology leads replacement cycles as Gulf health systems prioritize faster scan times and higher resolution for oncology staging protocols. Research institutions across South Africa and Egypt are adopting Ultra-High-Field MRI for advanced neuroimaging studies, though infrastructure requirements limit widespread deployment.
Saudi Arabia's SFDA, South Africa's SAHPRA, and the UAE's Ministry of Health and Prevention enforce divergent medical device registration pathways that shape import timelines and aftermarket service obligations for multinational suppliers. The EU Medical Device Regulation's extraterritorial influence persists as Gulf regulators reference CE marking benchmarks for clinical evidence requirements. Stakeholders must monitor harmonization efforts between national regulatory frameworks and assess localized manufacturing partnerships that could compress approval timelines for next-generation gradient coil technologies.
Market Dynamics
Hospital procurement departments across the Gulf Cooperation Council are consolidating imaging equipment purchasing into centralized tender frameworks, compressing vendor negotiation cycles and elevating service-level agreements above upfront capital costs in vendor selection criteria.
Growth Catalysts
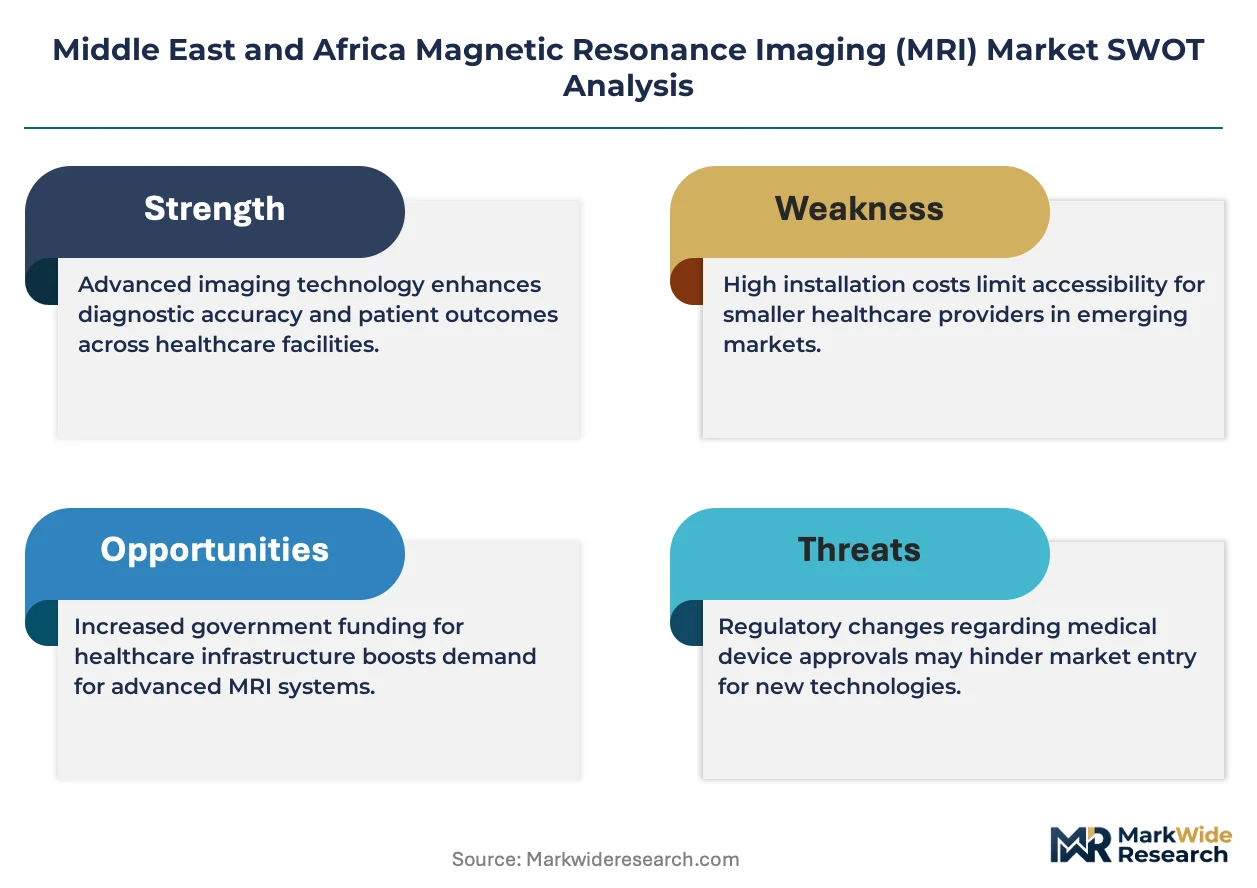
- SFDA Registration Harmonization:Saudi Arabia's streamlined medical device approval pathways are reducing import lead times for advanced gradient coil systems, accelerating hospital fleet modernization timelines.
- Outpatient Clinic Networks:Specialized extremity MRI configurations are penetrating diagnostic chains across the United Arab Emirates, extending imaging access beyond tertiary hospital campuses.
- Ultra-High-Field Research Adoption:Neuroscience institutes in Egypt and South Africa are deploying 7.0 Tesla systems for advanced brain mapping studies, creating institutional demand anchors.
Market Restraints
- Liquid Helium Supply Concentration:Superconducting magnet cooling depends on helium imports from concentrated North African and Middle Eastern gas processing facilities, exposing operators to input cost volatility.
- CE Marking Dependency:Gulf regulators reference EU Medical Device Regulation clinical evidence benchmarks, forcing manufacturers to duplicate documentation for divergent national approval pathways.
- Power Infrastructure Gaps:Rural hospital networks in sub-Saharan Africa lack stable electrical grids required for cryogen maintenance, limiting closed-system MRI deployment outside urban centers.
Strategic Opportunities
- Nigeria Diagnostic Gap:Underpenetrated radiology infrastructure in West Africa's largest economy creates first-mover positioning for mobile MRI service providers.
- Artificial Intelligence Integration:Convergence of deep learning reconstruction algorithms with existing 1.5 Tesla hardware is extending equipment useful life and deferring replacement capital.
- MOHAP Public-Private Partnerships:UAE Ministry of Health and Prevention tender frameworks are opening multi-site radiology department integration contracts to workflow software vendors.
Industry Challenges
- Gradient Coil Engineering Talent:Specialized electromagnetic design expertise concentrates in Western European and North American supplier engineering centers, constraining local technical support depth.
- Multi-Site Integration Complexity:Hospital networks pursuing centralized image archiving face interoperability friction between legacy PACS architectures and cloud-native radiology platforms.
- SAHPRA Compliance Timelines:South Africa's Health Products Regulatory Authority extended review periods for software-as-medical-device classifications are delaying AI-enabled diagnostic tool rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Magnetic Resonance Imaging (MRI) Market |
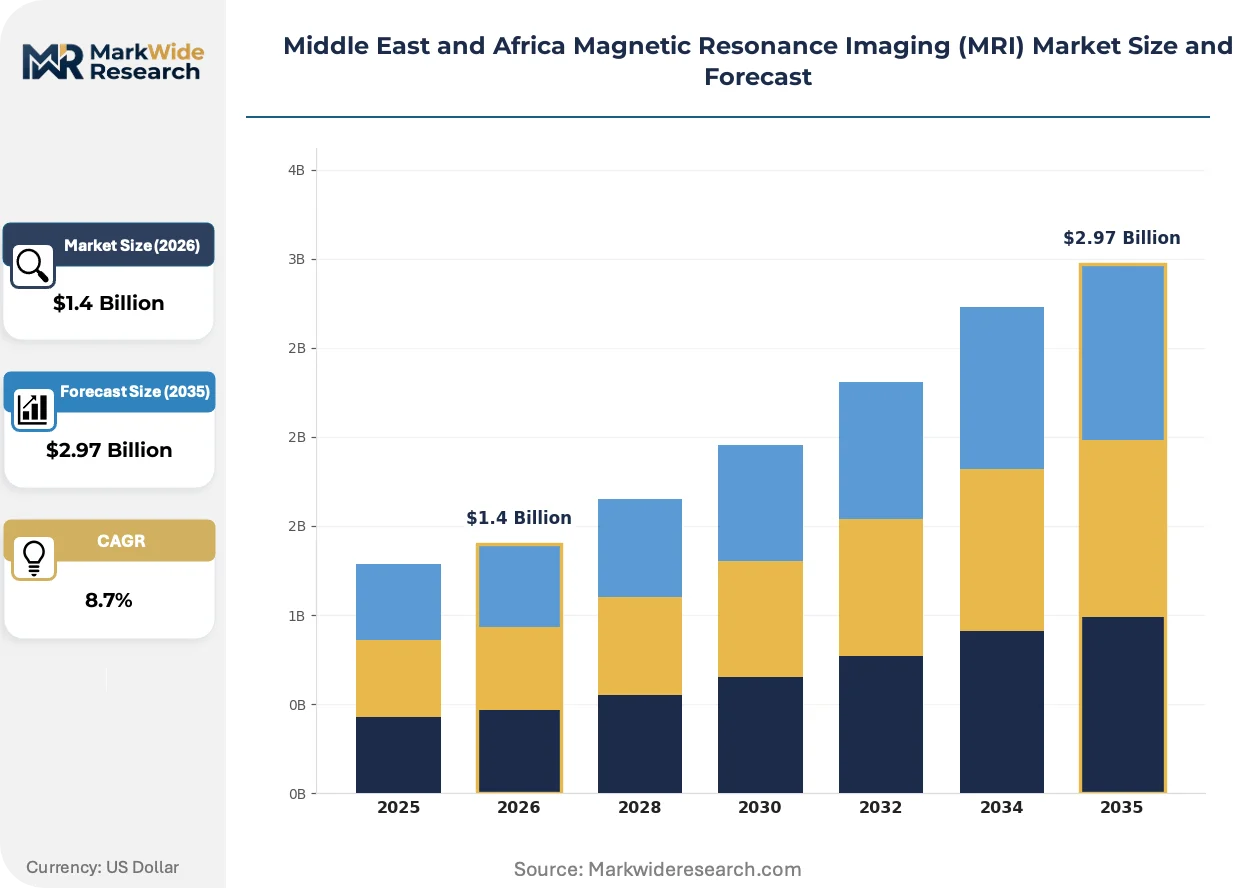
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Imaging Centers, Research Institutions, Clinics Technology: High-Field MRI, Low-Field MRI, Ultra-High-Field MRI, Hybrid Imaging Application: Neurology, Oncology, Musculoskeletal, Cardiology |
| Companies Covered | Canon Medical Systems Corporation, Koninklijke Philips N.V, General Electric Company (GE Healthcare), Siemens Healthineers, FUJIFILM Corporation, Hitachi Ltd., Esaote SpA, United Imaging Healthcare, Shimadzu Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Magnetic Resonance Imaging (MRI) Market Shifts & Advancements
Artificial intelligence reconstruction algorithms and helium-free magnet technologies are simultaneously reshaping equipment economics and operational requirements across Middle East and Africa imaging departments.
Compressed sensing reconstruction software is integrating with conventional 1.5 Tesla hardware to deliver scan time reductions of forty to sixty percent without magnet replacement. Radiology departments in Saudi Arabia and the UAE are adopting these upgrades to increase patient throughput during peak screening periods. The technology is integrating predictive maintenance protocols that flag gradient amplifier degradation before clinical downtime occurs.
EU Medical Device Regulation extraterritorial influence persists as Gulf Cooperation Council regulators reference CE marking clinical evidence requirements for imported imaging equipment. Manufacturers must now submit expanded post-market surveillance documentation to Saudi SFDA and UAE MOHAP alongside traditional technical files. High-field MRI replacement cycles face elongated approval timelines as authorities scrutinize software validation for AI-enabled diagnostic protocols.
Software-defined service contracts are displacing traditional capital purchase models across Gulf hospital networks. Procurement departments now prioritize remote diagnostics capabilities and guaranteed uptime clauses over equipment ownership. This shift concentrates vendor relationships around Siemens Healthineers, Philips, and Canon Medical Systems service infrastructures, compressing opportunities for independent maintenance providers.
Middle East and Africa Magnetic Resonance Imaging (MRI) Market Segmentation
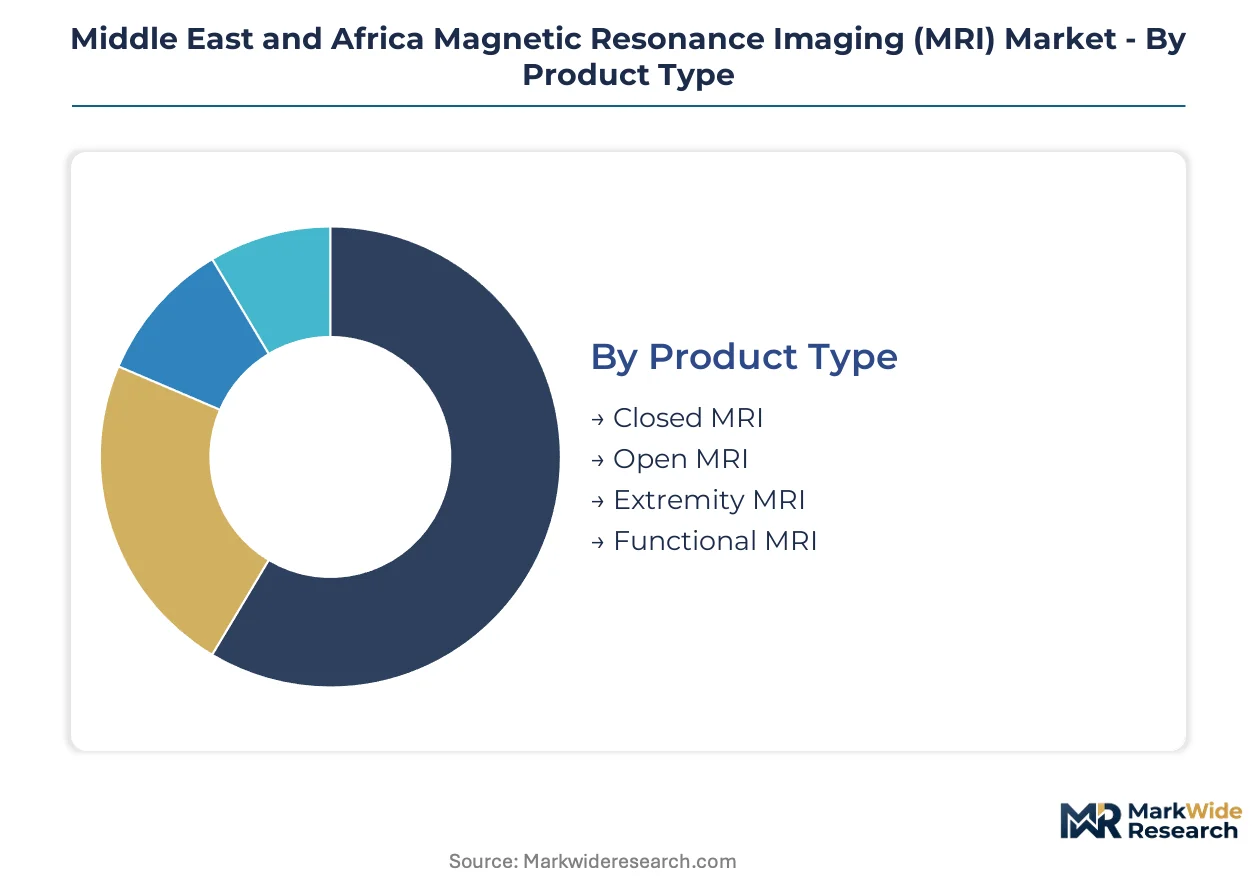
Segmentation in the Middle East and Africa MRI market reveals how procurement priorities diverge between tertiary hospital networks and emerging outpatient diagnostic chains. Equipment specifications, field strength requirements, and service infrastructure needs vary sharply across these divisions, shaping vendor go-to-market strategies and regulatory compliance burdens.
Product Type:
Customization intensity spans from standardized closed-bore platforms to highly specialized extremity configurations, with procurement patterns tracking the shift from hospital-centric to distributed diagnostic networks.
- Closed MRI:Superconducting cylindrical bore systems generate field strengths of 1.5 to 3.0 Tesla, delivering superior signal-to-noise ratios for neurovascular and abdominal protocols. Saudi Arabia's Ministry of Health and tertiary hospital networks in the UAE concentrate replacement demand here, driven by oncology staging requirements and SFDA-mandated screening program expansions.
- Open MRI:C-shaped or double-doughnut magnet architectures accommodate claustrophobic patients and larger body habitus, sacrificing field homogeneity for accessibility. South Africa's public hospital upgrades and Egypt's provincial health initiatives are expanding installed base, constrained by power infrastructure limitations outside Johannesburg and Cairo metropolitan zones.
- Extremity MRI:Compact dedicated systems image peripheral joints without full-body enclosure, penetrating UAE outpatient clinic chains and Saudi sports medicine facilities.
- Functional MRI:Blood-oxygen-level-dependent sequencing enables real-time brain activity mapping, adopted by neuroscience institutes in Egypt and South Africa for cognitive research protocols.
Most installed capacity flows through Closed MRI. Expansion is steepest in Extremity MRI configurations.
End User:
Customer-type concentration shapes pricing power and service contract structures, with centralized Gulf procurement departments extracting multi-year uptime guarantees.
- Hospitals:Tertiary and secondary acute care facilities anchor equipment demand across Saudi Arabia, the UAE, and South Africa, consolidating purchasing through Gulf Cooperation Council tender frameworks that elevate service-level agreements above capital expenditure.
- Imaging Centers:Independent diagnostic chains and hospital-affiliated outpatient radiology units in Dubai, Riyadh, and Johannesburg prioritize throughput optimization and AI reconstruction software integration.
- Research Institutions:Universities and dedicated neuroscience institutes in Cairo, Cape Town, and selected Gulf cities deploy Ultra-High-Field systems for advanced neuroimaging studies.
- Clinics:Primary care and specialist physician practices across Nigeria and Kenya represent nascent demand for compact low-field systems, constrained by helium supply logistics and electrical grid reliability.
Procurement volume concentrates in Hospitals. Imaging Centers are gaining share fastest as outpatient networks proliferate.
Technology:
Field strength tiers stratify by clinical application intensity and infrastructure investment capacity, with replacement cycles accelerating at the high-field boundary.
- High-Field MRI:Systems operating at 1.5 to 3.0 Tesla dominate neuro-oncology and musculoskeletal diagnostics, with Saudi SFDA and UAE MOHAP procurement frameworks prioritizing these platforms for national screening programs.
- Ultra-High-Field MRI:7.0 Tesla research-grade installations concentrate in South African and Egyptian academic medical centers, limited by specialized siting requirements and liquid helium consumption.
- Low-Field MRI:Permanent magnet or resistive systems below 0.5 Tesla serve cost-constrained settings and mobile deployment scenarios across sub-Saharan Africa.
- Hybrid Imaging:PET-MRI and SPECT-MRI fusion platforms enable simultaneous functional and anatomical assessment, penetrating Saudi Arabia's specialized oncology centers.
Technology deployment concentrates in High-Field MRI. Ultra-High-Field MRI is climbing the fastest among research institutions.
Application:
Clinical use-case segmentation tracks disease burden shifts across the region, with non-communicable disease protocols reshaping equipment specification requirements.
- Neurology:Brain and spinal cord imaging protocols demand high-field homogeneity and advanced diffusion tensor capabilities, with Gulf health systems prioritizing stroke and neurodegenerative disease diagnostics.
- Oncology:Tumor staging and treatment response monitoring drives 3.0 Tesla adoption across Saudi Arabia's specialized cancer centers and South Africa's academic hospital networks.
- Musculoskeletal:Joint, spine, and soft tissue imaging represents high-volume routine diagnostic work across UAE sports medicine facilities and occupational health programs.
- Cardiology:Cardiac MRI for perfusion and viability assessment remains underpenetrated, constrained by specialized technologist training gaps and longer scan protocols.
Application demand concentrates in Neurology. Oncology is gaining share fastest as screening protocols intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment procurement across the Middle East and Africa, as Gulf health systems leverage streamlined approval pathways to compress import lead times while sub-Saharan markets face elongated compliance timelines that deter vendor entry.
Saudi Arabia
Oncology screening protocols and neurovascular diagnostic expansion are driving 3.0 Tesla system procurement across Riyadh and Jeddah hospital networks. The Saudi Food and Drug Authority has harmonized medical device registration with EU Medical Device Regulation benchmarks, reducing documentation duplication for CE-marked equipment. King Faisal Specialist Hospital anchors high-field MRI deployment in the Riyadh cluster, with specialized cancer centers commissioning hybrid PET-MRI platforms for precision staging protocols.
United Arab Emirates
Outpatient diagnostic chains and sports medicine facilities are penetrating Dubai and Abu Dhabi with extremity MRI configurations. The Ministry of Health and Prevention enforces tender frameworks that elevate multi-year service-level agreements above upfront capital expenditure in vendor selection. Dubai Healthcare City concentrates private imaging center proliferation, where workflow software integration connects radiology departments across multi-site health systems.
South Africa
Academic medical centers in Cape Town and Johannesburg are deploying Ultra-High-Field 7.0 Tesla systems for advanced neuroimaging research. The South African Health Products Regulatory Authority has extended review periods for software-as-medical-device classifications, delaying AI-enabled diagnostic tool rollouts. Groote Schuur Hospital anchors public sector high-field replacement cycles, constrained by power infrastructure reliability gaps outside metropolitan zones.
Egypt
Provincial health initiatives and neuroscience institute expansion are stimulating open MRI and functional MRI adoption across Cairo and Alexandria. The country's national pharmaceutical regulator maintains divergent clinical evidence requirements from Gulf frameworks, fragmenting import documentation for multinational suppliers. Cairo University neuroscience institutes concentrate research-grade system deployment, with 7.0 Tesla installations limited by specialized siting requirements and liquid helium logistics.
Nigeria
Underpenetrated radiology infrastructure and mobile diagnostic service gaps are creating first-mover positioning opportunities for low-field and portable MRI providers. The national medical device regulator lacks harmonized pathways with CE marking or FDA benchmarks, elongating approval timelines for advanced gradient coil technologies. Lagos and Abuja metropolitan clusters concentrate nascent private imaging center development, constrained by electrical grid instability and helium supply chain fragmentation.
Middle East and Africa Magnetic Resonance Imaging (MRI) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system vendors anchoring hospital procurement through integrated service infrastructures while component suppliers penetrate price-sensitive markets through localized assembly partnerships. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with regional service networks, specialized imaging equipment manufacturers with workflow software integration capabilities, and emerging Asia-Pacific suppliers competing on capital cost compression. Dominant competitive moves include software-defined service contract expansion that displaces traditional equipment ownership models, and strategic partnerships with Gulf hospital networks to secure multi-site maintenance agreements.
Within the diversified conglomerate tier, Siemens Healthineers and Koninklijke Philips N.V. occupy positions anchored by regional service infrastructures and integrated workflow platforms. Canon Medical Systems Corporation exemplifies the specialized imaging archetype, with configurations tailored to outpatient clinic networks. Among Asia-Pacific-based suppliers, United Imaging Healthcare represents cost-competitive positioning for markets prioritizing capital expenditure reduction over proprietary service ecosystems.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Koninklijke Philips N.V |
| General Electric Company (GE Healthcare) |
| Siemens Healthineers |
| FUJIFILM Corporation |
| Hitachi Ltd. |
| Esaote SpA |
| United Imaging Healthcare |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
Centralized Gulf Cooperation Council tender frameworks are compressing vendor negotiation cycles and elevating multi-year service-level agreements above upfront capital expenditure, forcing manufacturers to absorb financing costs and anchor pricing around guaranteed uptime clauses rather than equipment margins.
Pricing Analysis
Distributor margins on imported gradient coil assemblies and superconducting magnet subsystems typically range between fifteen and twenty-five percent before hospital procurement departments extract volume discounts through consolidated purchasing frameworks. Three-tier pricing structure across premium 3.0 Tesla configurations, standard 1.5 Tesla platforms, and economy-oriented low-field systems stratifies by field strength performance and AI reconstruction software bundling. Pricing pressure stems from software-defined service contracts displacing traditional capital purchase models, with Gulf health systems prioritizing remote diagnostics capabilities over equipment ownership. Public hospital networks across South Africa and Egypt exhibit highest price sensitivity due to constrained national health budgets, while Saudi Arabia's specialized oncology centers demonstrate lowest sensitivity given screening protocol mandates.
Supply Chain Analysis
CE marking and FDA 510(k) clearance serve as qualification gates that Gulf regulators reference for clinical evidence requirements, elongating documentation preparation for manufacturers lacking established Western regulatory footprints. Superconducting magnet manufacturing concentrates in Germany, the Netherlands, and Japan, with gradient coil production anchored in the United States and China. Liquid helium supply draws from concentrated North African and Middle Eastern gas processing facilities, while niobium-titanium superconductor wire sourcing rests on Japanese and European metallurgical specialists. Single-source vulnerability in helium logistics exposes operators to input cost volatility, particularly for Ultra-High-Field 7.0 Tesla systems with elevated cryogen consumption. Distribution runs through authorized regional service infrastructures operated by Siemens Healthineers, Philips, and Canon Medical Systems, compressing opportunities for independent maintenance providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on helium-free magnet technology adoption compressing operational cost structures for end-users, alongside premium-tier shift toward AI-integrated 3.0 Tesla platforms commanding service-contract premiums.
For Market Incumbents: Deepen vertical integration into gradient coil engineering capabilities to reduce dependency on Western European and North American supplier engineering centers, while expanding regional service infrastructure density to defend against Asia-Pacific cost competitors. Threat substitution from United Imaging Healthcare and other capital-cost-focused entrants pressures proprietary service ecosystem margins. Capacity addition in Saudi Arabia and UAE service hubs anchors long-term hospital partnerships against tender-framework consolidation. For New Entrants and Emerging Players: The price-point gap between premium 3.0 Tesla configurations and economy low-field systems creates positioning room for mid-tier 1.5 Tesla platforms with compressed sensing reconstruction software. Nigeria's underpenetrated radiology infrastructure and mobile diagnostic service gaps represent the most penetrable geography, constrained only by electrical grid instability and helium supply chain fragmentation. Go-to-market execution should prioritize public-private partnership frameworks with UAE Ministry of Health and Prevention tender structures to bypass capital-purchase barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with workflow software vendors capable of multi-site radiology department integration across Gulf hospital networks, given procurement prioritization of guaranteed uptime over equipment ownership. Long-term viability favors service-contract revenue streams with recurring characteristics over capital-equipment cyclicality. Signal to watch: harmonization progress between Saudi SFDA, UAE MOHAP, and South Africa SAHPRA registration pathways as indicator of vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Magnet Technology Deployment | Eliminates liquid helium supply vulnerability for Nigerian and Kenyan rural hospital networks. |
| AI Reconstruction Software Integration | Extends 1.5 Tesla hardware useful life for Saudi Arabia's SFDA-mandated screening expansions. |
| Regional Service Infrastructure Expansion | Secures multi-year maintenance agreements under Gulf Cooperation Council tender frameworks. |
| CE Marking Harmonization Investment | Compresses Saudi SFDA and UAE MOHAP approval timelines for next-generation gradient coils. |
| Mobile MRI Service Platform Launch | Addresses Nigeria's diagnostic gap without requiring stable electrical grid infrastructure. |
Research Methodology
Multiple input streams — primary interviews with hospital procurement committees, biomedical engineers, and GPO contracts managers, alongside secondary validation through hospital procurement databases, GPO contracts, and CMS Medicare data — were reconciled through bottom-up and top-down triangulation. Saudi SFDA registration filings, UAE MOHAP tender documentation, and South Africa SAHPRA approval records provided regulatory pathway intelligence. Field intelligence from radiology department heads and medical device distribution channel partners in Riyadh, Dubai, Johannesburg, and Cairo anchored demand-side assessment.
Data-stream reconciliation across equipment shipment records, installed base surveys, and replacement cycle modeling informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include product type, field strength tier, end-user category, and application intensity. CAGRs were derived from replacement cycle velocity, screening protocol expansion timelines, and research institution adoption curves. Helium supply logistics, power infrastructure reliability indices, and regulatory harmonization progress served as industry-specific forecast inputs.
Caveats apply where liquid helium supply disruption, electrical grid instability in sub-Saharan Africa, or divergent national regulatory pathway fragmentation could materially shift the outlook. Forecasts reflect assumptions around software-defined service contract penetration rates and AI reconstruction algorithm adoption timelines. A model refresh is warranted upon material change in Gulf Cooperation Council tender framework standardization or helium-free magnet technology cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
Echocardiography Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Global Portable Magnetic Resonance Imaging Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
X-Ray Film Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
Cephalometric X-Ray System Market
Medical Imaging
Global Spectral Computed Tomography (CT) Market