
 Asia Pacific Diabetes Pen Market | 2026-2036
Asia Pacific Diabetes Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Diabetes Pen Market Outlook
Aftermarket service revenue for connected pen platforms is rewriting how device economics work across the region. Novo Nordisk A/S leverages its deep insulin portfolio to bundle pen devices with long-term patient monitoring programs. Ypsomed AG anchors its position through precision injection mechanisms that reduce dosing errors in home settings. Biocon Ltd. competes aggressively on cost-engineered disposable pens tailored for price-sensitive markets in South and Southeast Asia.
An Asia Pacific diabetes pen is a handheld, spring-activated or electronic drug delivery instrument designed for subcutaneous insulin administration, typically featuring dose-adjustment windows accurate to one-unit increments and needle shielding mechanisms for patient safety. Its primary commercial purpose is to enable precise, repeatable self-injection by diabetic patients outside clinical supervision. Reusable pens still command the largest installed base across mature markets like Japan and Australia, though smart pens with Bluetooth-enabled dose logging represent the fastest-expanding margin pool as digital therapeutics gain reimbursement traction. Homecare distribution through retail pharmacies dominates volume, while hospital pharmacies retain higher per-unit pricing power due to institutional procurement standards.
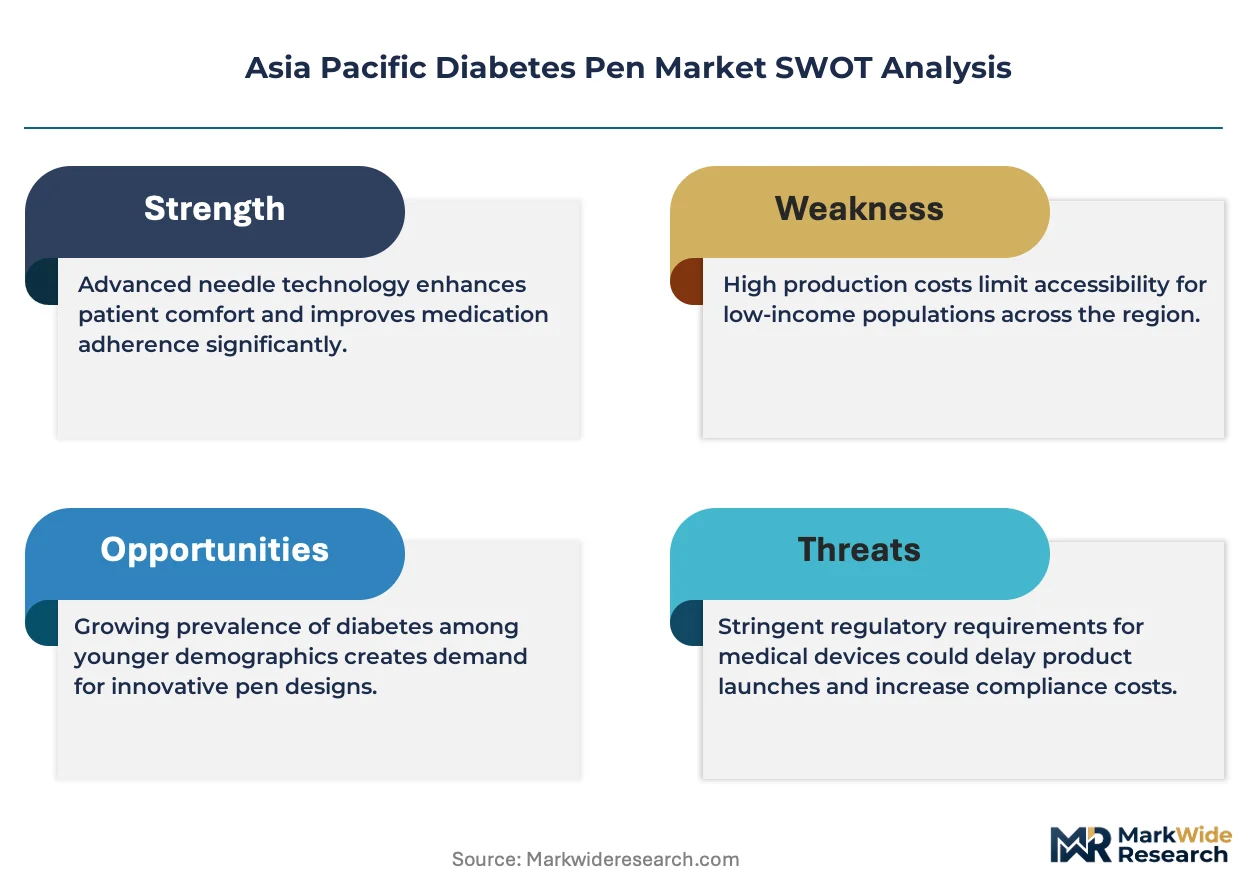
India's CDSCO and the country's BIS certification requirements for medical devices are tightening quality benchmarks for imported and locally manufactured pens alike. Japan's PMDA maintains stringent electromagnetic compatibility standards for connected devices, effectively filtering which Bluetooth-enabled products reach that market. China's NMPA has accelerated review pathways for innovative drug-device combinations, reshaping how multinational firms sequence their regional launch strategies. Stakeholders must track how divergent data-localization rules across these three jurisdictions will affect cloud-connected pen architectures and subsequent service monetization models.
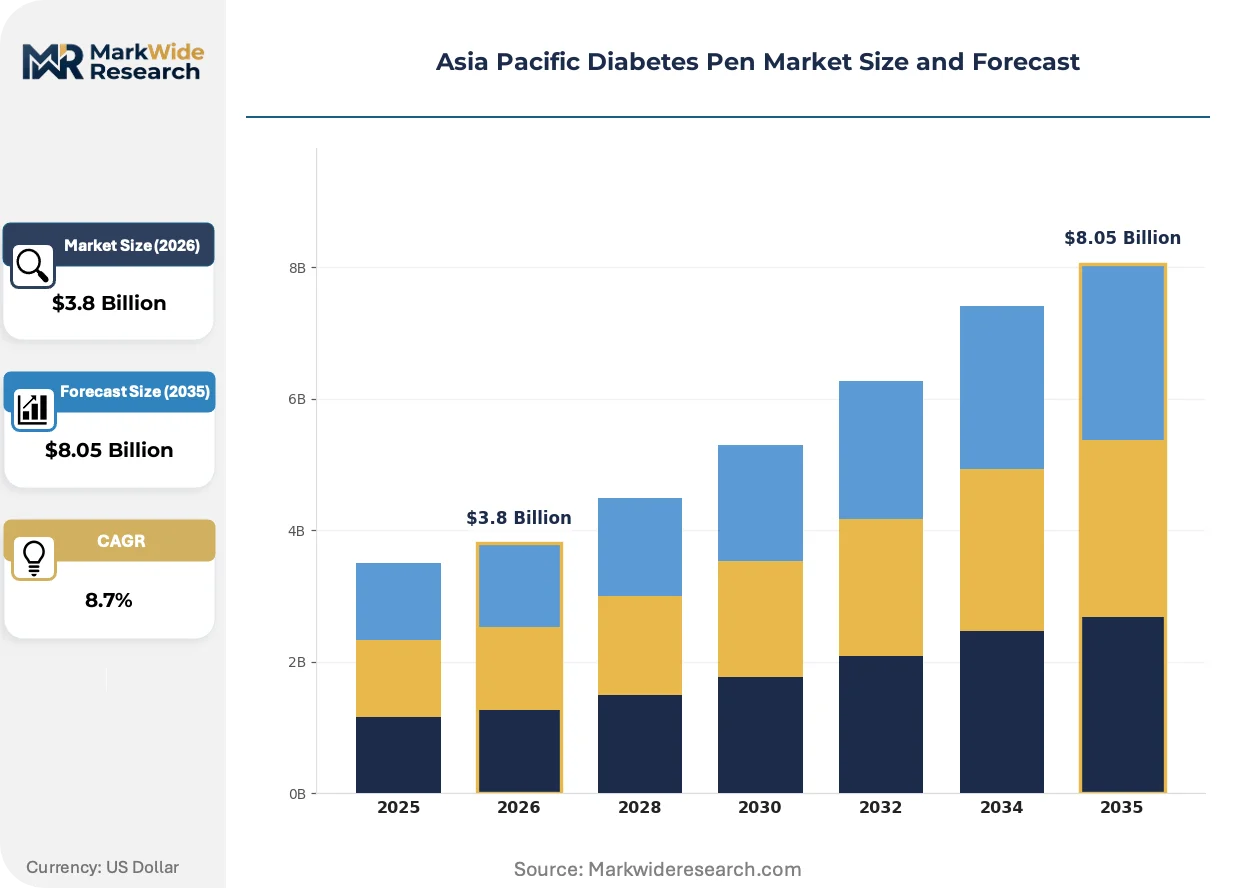
Market Dynamics
Connected pen platforms are digitizing patient adherence monitoring across the Asia Pacific, forcing manufacturers to restructure revenue models around recurring service fees rather than one-time device sales. This shift compresses hardware margins while expanding lifetime value capture through cloud-based dose analytics and remote clinician integration.
Growth Catalysts
- China's NMPA accelerated review pathways:Drug-device combination approvals now move through streamlined queues, pulling multinational launch timelines forward by 12-18 months for Bluetooth-enabled pens.
- Homecare self-administration:Patients across India and Southeast Asia bypass hospital pharmacy queues for retail-channel pens, expanding addressable volume through pharmacy network density.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting component suppliers for pen injectors, reducing import dependency for spring mechanisms and dose-adjustment assemblies.
Market Restraints
- Japan's PMDA electromagnetic compatibility standards:Stringent Bluetooth certification requirements filter which connected devices reach the market, creating a two-tier product landscape where only large manufacturers absorb compliance costs.
- Stainless steel needle supply concentration:Three Japanese and German suppliers control precision cannula production, exposing pen assemblers to input cost volatility and allocation risk during demand surges.
- Reusable pen installed base lock-in:Mature markets like Australia and Japan exhibit slow switching cycles from cartridge-based systems to disposable formats, constraining volume growth for next-generation platforms.
Strategic Opportunities
- Indonesia's underpenetrated diabetes management infrastructure:Dispensing pharmacy networks in second-tier cities lack connected device access, creating first-mover terrain for dose-logging platforms paired with local language apps.
- Cloud-localization requirements:Divergent data-residency rules across China, India, and Japan are forcing modular pen architectures that can be reconfigured for jurisdiction-specific servers, opening consulting and integration service revenue.
- Reimbursement digitization:South Korea's HIRA and Australia's PBS are piloting remote monitoring codes for dose-adherent patients, creating policy tailwinds for pen platforms with built-in connectivity.
Industry Challenges
- Cross-jurisdiction certification timelines:CDSCO, PMDA, and NMPA maintain non-harmonized biocompatibility testing protocols, forcing manufacturers to rerun studies rather than leverage mutual recognition.
- Legacy ERP integration with connected pen backends:Hospital pharmacy inventory systems in Thailand and Vietnam lack API standards for real-time dose data ingestion, complicating enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Diabetes Pen Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Pens, Disposable Pens, Smart Pens, Insulin Delivery Systems End User: Hospitals, Clinics, Homecare, Pharmacies Technology: Auto-Injectors, Manual Injectors, Bluetooth-enabled Devices, Connected Devices Distribution Channel: Online Stores, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Novo Nordisk A/S, AstraZeneca plc., Medtronic PLC, Eli Lilly and Company, Biocon Ltd., Ypsomed AG, Sanofi S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Diabetes Pen Market Strategic Shifts
Bluetooth-enabled dose logging is restructuring how adherence data flows between patients and payers across the Asia Pacific. Three developments are compressing product refresh cycles and redrawing competitive boundaries.
Smart pen ecosystems are digitizing the insulin administration workflow through automatic timestamp capture and glycemic correlation algorithms. Endocrinology clinics in Singapore and South Korea are piloting these platforms for type 1 cohorts, with adoption accelerating where reimbursement covers remote monitoring. The technology is digitizing patient-pharmacist interactions by replacing manual logbooks with server-validated adherence records that influence refill authorization.
China's NMPA has carved out priority review tracks for drug-device combinations that demonstrate real-world evidence generation capabilities. This regulatory architecture favors submissions where the pen platform includes built-in clinical trial infrastructure, tilting competitive advantage toward manufacturers with integrated digital health divisions. Multinational firms are responding by sequencing China-first launches for connected formats while delaying them in jurisdictions with slower approval timelines.
Retail pharmacy chains are consolidating procurement authority for homecare pens across Malaysia and the Philippines, displacing fragmented wholesaler networks. Guardian Pharmacy and Watsons are negotiating direct manufacturer contracts with volume commitments tied to exclusive shelf placement. This concentration is most visible in urban corridors where pharmacy density supports same-day delivery promises for insulin refills.
Asia Pacific Diabetes Pen Market Segmentation
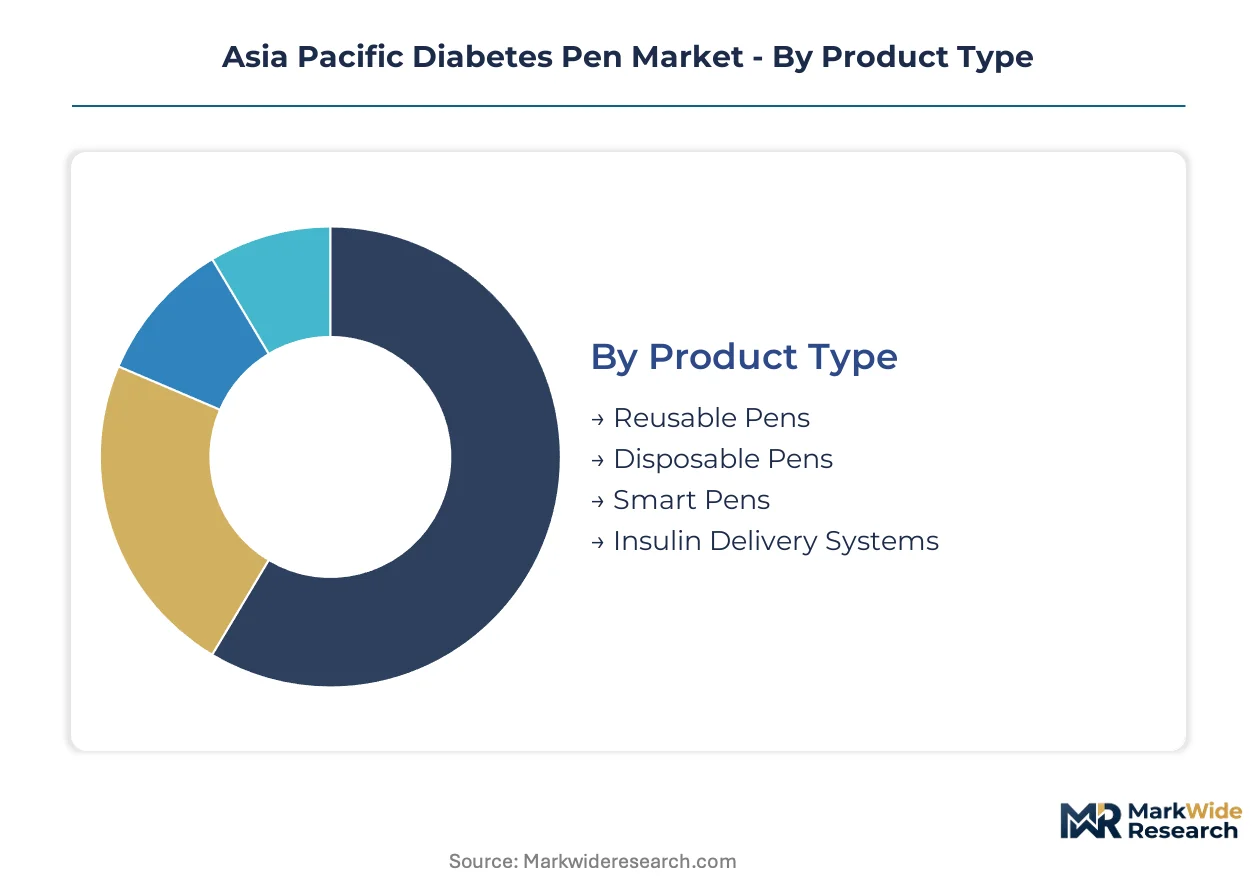
Segmentation in the Asia Pacific diabetes pen market reveals how device economics split across patient self-administration patterns, reimbursement pathways, and digital maturity. Each dimension exposes different margin structures and competitive entry points for manufacturers.
Product Type:
Product architecture determines both manufacturing complexity and patient lifecycle value, with cartridge compatibility and connectivity features driving divergent pricing power across patient segments.
- Reusable Pens:Metal-bodied devices with replaceable insulin cartridges and adjustable dose windows dominate installed bases in Japan and Australia. Hospital procurement contracts in these markets favor durable metal construction over disposability, though patient switching cycles extend beyond typical product refresh timelines.
- Smart Pens:Bluetooth-enabled dose logging with timestamp capture and glycemic correlation algorithms command premium positioning where South Korea's HIRA and Australia's PBS pilot remote monitoring reimbursement codes. These devices expand lifetime value through recurring cloud service fees rather than one-time hardware margins.
- Disposable Pens:Pre-filled, single-use plastic devices with integrated needles target price-sensitive markets in India and Southeast Asia where pharmacy retail networks prioritize low unit cost over durability.
- Insulin Delivery Systems:Pump-integrated or patch-based alternatives to traditional pen formats serve type 1 cohorts in Singapore and South Korean endocrinology clinics with intensive insulin regimens.
The dominant share belongs to reusable pens, while smart pens are closing the gap fastest.
End User:
Patient location at point of injection shapes device specification requirements, training burden, and data capture infrastructure.
- Homecare:Self-administration outside clinical supervision demands intuitive dose adjustment, needle shielding, and patient-friendly instruction sets. India's retail pharmacy density and Indonesia's expanding urban dispensing networks are channeling volume growth through this segment.
- Hospitals:Institutional procurement in China and Thailand mandates batch traceability, electromagnetic compatibility certification, and integration with electronic health record systems. Per-unit pricing power remains strongest here due to tender-based purchasing standards.
- Clinics:Outpatient endocrinology settings in Malaysia and the Philippines balance device cost with staff training efficiency, often favoring familiar reusable formats over novel connected platforms.
- Pharmacies:Dispensing counter recommendations influence patient device selection in markets where physician prescribing authority does not extend to delivery mechanism specification.
Homecare settings now generate the steepest volume expansion trajectory, though hospitals retain superior per-unit economics.
Technology:
Injection mechanism sophistication spans mechanical simplicity to digital ecosystem integration, with regulatory clearance requirements scaling accordingly.
- Bluetooth-enabled Devices:Wireless dose transmission to smartphone applications enables adherence logging and clinician remote monitoring. Japan's PMDA electromagnetic compatibility standards filter market entry, creating compliance cost barriers that favor established manufacturers with dedicated certification resources.
- Manual Injectors:Spring-activated mechanical dose delivery without electronic components dominates cost-engineered segments across India and Vietnam where price sensitivity constrains technology adoption.
- Auto-Injectors:Motorized or high-spring-force mechanisms reduce dexterity requirements for elderly patients in Australia's aging diabetic population.
- Connected Devices:Full ecosystem integration with cloud analytics, API-accessible dose data, and pharmacy system interoperability represents the frontier segment where China's NMPA priority review tracks accelerate approval timelines.
Manual injectors still command volume leadership, yet Bluetooth-enabled devices are gaining share fastest as reimbursement digitization spreads.
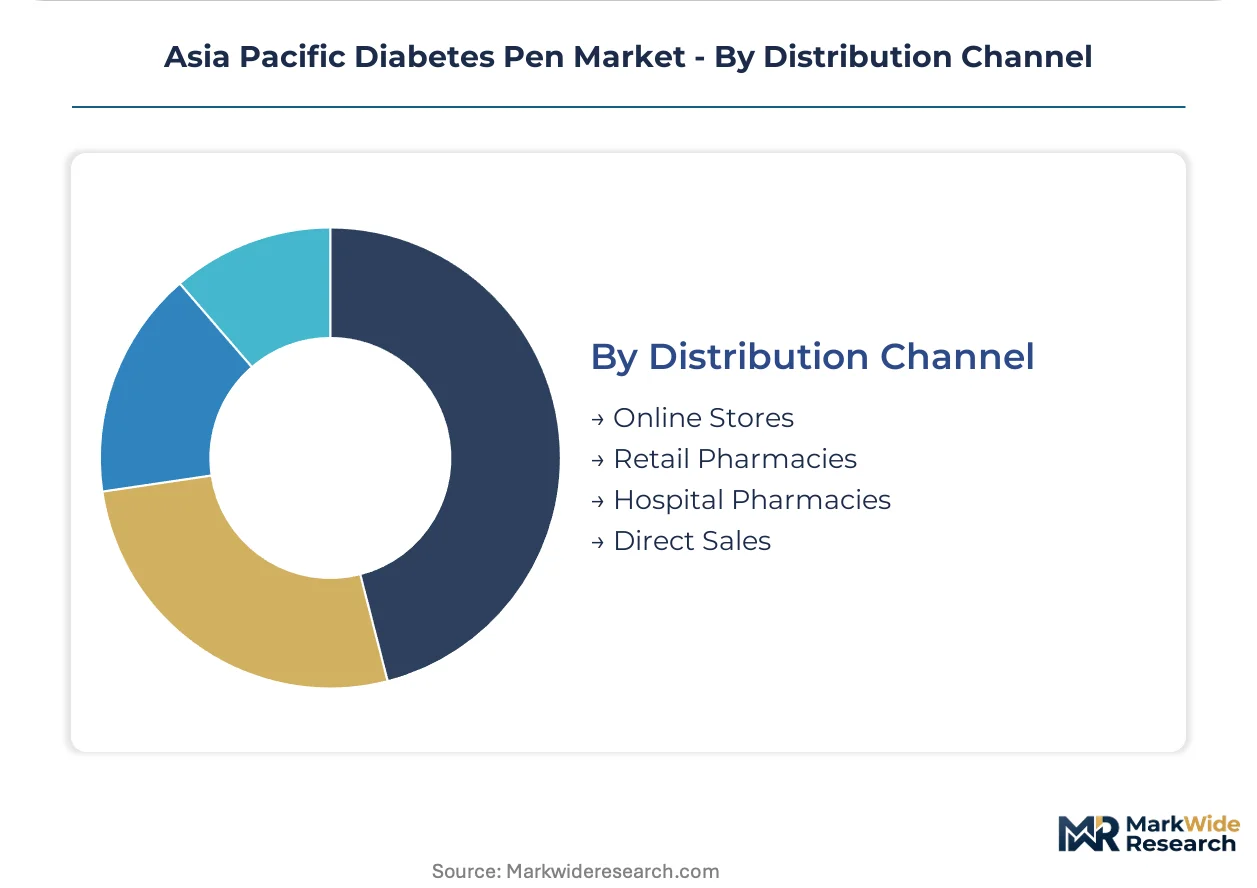
Distribution Channel:
Channel structure determines patient access speed, inventory carrying cost, and manufacturer pricing control.
- Retail Pharmacies:Guardian Pharmacy and Watsons chains across Malaysia and the Philippines are consolidating procurement authority through direct manufacturer contracts with volume commitments tied to exclusive shelf placement. Same-day delivery promises in urban corridors reinforce channel concentration.
- Hospital Pharmacies:Institutional tender processes in China and Thailand maintain higher per-unit pricing through procurement standards that prioritize traceability and batch documentation over cost minimization.
- Online Stores:E-commerce penetration for insulin pens remains constrained by cold-chain logistics requirements and prescription verification protocols across most Asia Pacific jurisdictions.
- Direct Sales:Manufacturer-to-patient subscription models for smart pen platforms are emerging in South Korea and Australia where remote monitoring reimbursement creates recurring revenue feasibility.
Retail pharmacies hold the dominant position, while direct sales channels are expanding most quickly through connected device subscription pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia Pacific diverge sharply by healthcare infrastructure maturity and reimbursement digitization. Japan and Australia favor durable reusable formats with institutional procurement standards, while India and Southeast Asia channel volume through cost-optimized disposable pens distributed via retail pharmacy density.
China
China's diabetic population expansion and healthcare infrastructure investments drive concentrated demand for connected pen platforms. NMPA accelerated review pathways for drug-device combinations compress multinational launch timelines by 12-18 months. Manufacturing clusters in the Yangtze River Delta are scaling precision injection component capacity to serve both domestic and export markets.
India
India's retail pharmacy networks enable patient bypass of hospital queues for self-administration devices, expanding addressable volume through dispensing density. CDSCO and BIS certification requirements tighten quality benchmarks for imported and locally manufactured pens alike. The PLI scheme for medical devices is attracting component suppliers for pen injectors to industrial corridors in Maharashtra and Gujarat.
Japan
Japan's aging diabetic population sustains installed base loyalty to metal-bodied reusable pens with hospital procurement contracts. PMDA electromagnetic compatibility standards filter which Bluetooth-enabled products reach the market, creating compliance cost barriers. Manufacturing concentration in the Kansai region maintains precision engineering capabilities for dose-adjustment mechanisms.
South Korea
South Korea's HIRA reimbursement digitization pilots remote monitoring codes for dose-adherent patients, creating policy tailwinds for connected platforms. Endocrinology clinics in Seoul pilot smart pen ecosystems for type 1 cohorts where connectivity influences refill authorization. The Seoul Capital Area anchors domestic distribution infrastructure for pharmacy network penetration.
Australia
Australia's PBS pilot programs for remote monitoring create reimbursement pathways for Bluetooth-enabled dose logging devices. Slow switching cycles from cartridge-based systems constrain volume growth for disposable formats despite digital health adoption. Hospital procurement standards in New South Wales and Victoria maintain higher per-unit pricing through batch traceability requirements.
Asia Pacific Diabetes Pen Market Competitive Environment
Capability concentration sits with precision engineering specialists; scale advantage sits with integrated pharmaceutical-device bundlers. The market structures around three tiers: multinational drug-device combinations, European precision injection specialists, and cost-engineered Asian manufacturers. Dominant competitive moves include cloud service monetization restructuring and direct retail pharmacy contracting to displace wholesaler networks.
Within the multinational integrated tier, Novo Nordisk A/S and Eli Lilly and Company anchor positions through insulin portfolio bundling with patient monitoring programs. Ypsomed AG exemplifies the European precision specialist archetype, occupying a position defined by injection mechanism accuracy for home settings. Biocon Ltd. represents the cost-engineered Asian manufacturer archetype, sitting within competitive terrain shaped by price-sensitive market access across South and Southeast Asia.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Novo Nordisk A/S |
| AstraZeneca plc. |
| Medtronic PLC |
| Eli Lilly and Company |
| Biocon Ltd. |
| Ypsomed AG |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing clusters anchor precision injection component capacity, translating concentrated spring mechanism and dose-adjustment assembly production into asymmetric pricing power for device integrators serving hospital procurement channels across China and Southeast Asia.
Pricing Analysis
Long-term offtake contracts dominate hospital pharmacy procurement in China and Thailand, securing batch traceability and electromagnetic compatibility certification tiers that command premium positioning over retail pharmacy spot purchases. Three-tier pricing structure across connected platforms, standard reusable formats, and economy disposable pens reflects divergence in software service bundling and cartridge compatibility depth. Pricing pressure stems from India's PLI scheme attracting domestic component suppliers that erode import dependency premiums. Retail pharmacy networks in Indonesia and Vietnam exhibit highest price sensitivity, while South Korean endocrinology clinics show lowest sensitivity where HIRA reimbursement digitization covers remote monitoring.
Supply Chain Analysis
Extended payment terms from Japanese and German precision cannula suppliers expose pen assemblers to working capital strain during demand surges, amplifying cost volatility for stainless steel needle inputs. Component sourcing concentrates in China, Japan, and Germany for dose-adjustment mechanisms, spring assemblies, and electromagnetic modules. Raw material dependencies span medical-grade stainless steel, engineering plastics, and Bluetooth chipsets. Single-source vulnerability concentrates in precision cannula production controlled by three suppliers. Distribution runs through retail pharmacy chains consolidating procurement authority across Malaysia and the Philippines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled dose logging platforms are disrupting device economics across Asia Pacific, with China's NMPA accelerated review pathways compressing multinational launch timelines and forcing revenue model restructuring around recurring cloud service fees.
For Market Incumbents: Build ecosystem lock-in moats through API-accessible dose data architectures that tether hospital pharmacy inventory systems to proprietary cloud backends, defending against emerging direct-to-patient subscription models from connected device specialists. Deepen backward integration into precision cannula production to offset allocation risk from Japanese and German suppliers. Prioritize CDSCO certification investment ahead of India's PLI scheme maturation to capture domestic manufacturing incentives. For New Entrants and Emerging Players: Pursue Indonesia's underpenetrated second-tier city dispensing networks where pharmacy density lacks connected device access, positioning dose-logging platforms with Bahasa Indonesia language interfaces as first-mover offerings. Target Vietnam's clinic segment where legacy ERP integration gaps complicate enterprise sales for incumbents. Lead with direct retail pharmacy contracting to displace fragmented wholesaler networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision injection mechanism specialists with modular cloud architectures that can be reconfigured for jurisdiction-specific data residency requirements across China, India, and Japan. Long-term viability hinges on recurring service revenue capture rather than hardware margin extraction. Watch South Korea's HIRA and Australia's PBS reimbursement digitization pilots as inflection indicators for connected platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Localization Architecture | Modular server configurations address divergent data-residency rules across NMPA, CDSCO, and PMDA jurisdictions. |
| Direct Pharmacy Contracting | Volume commitments with Guardian Pharmacy and Watsons displace wholesaler networks in Malaysia and Philippines. |
| Precision Component Backward Integration | In-house spring mechanism production reduces dependency on Yangtze River Delta supplier concentration. |
| Reimbursement Strategy Development | HIRA and PBS remote monitoring code alignment accelerates connected pen platform patient access. |
| Software Companion Development | Glycemic correlation algorithms and timestamp capture differentiate smart pen ecosystems in Seoul clinics. |
Study Parameters
The analysis maps reusable pen, smart pen, disposable pen, and insulin delivery system sub-sectors, each validated through hospital purchasing committee interviews, biomedical engineer consultations, GPO contracts managers, and regulatory affairs specialists at multinational device manufacturers. Primary fieldwork combined with secondary validation from NMPA filings, CDSCO device registrations, PMDA electromagnetic compatibility standards, hospital procurement databases, and GPO contract repositories. Bottom-up patient population modeling triangulated against top-down pharmaceutical-device bundling revenue analysis.
Assumptions held fixed include current reimbursement digitization pilot scope across South Korea and Australia, while NMPA review pathway velocity and PLI scheme participation rates were varied across sensitivity scenarios. Segmentation dimensions modeled span product architecture, end-user setting, connectivity technology, and distribution channel structure. CAGRs derived from patient population growth trajectories, device replacement cycle analysis, and cloud service adoption curves. Forecast inputs incorporated diabetes prevalence projections and healthcare infrastructure investment flows across the analysis window.
Sensitivities concentrate around NMPA regulatory timeline compression, PLI scheme domestic manufacturing incentive maturation, and Bluetooth chipset supply availability. Forecasts reflect documented assumptions on connected platform reimbursement expansion and precision component supplier concentration stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
Saudi Arabia Diabetes Care Devices Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market