
 India Diabetes Devices Market | 2026-2036
India Diabetes Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Diabetes Devices Market Foresight
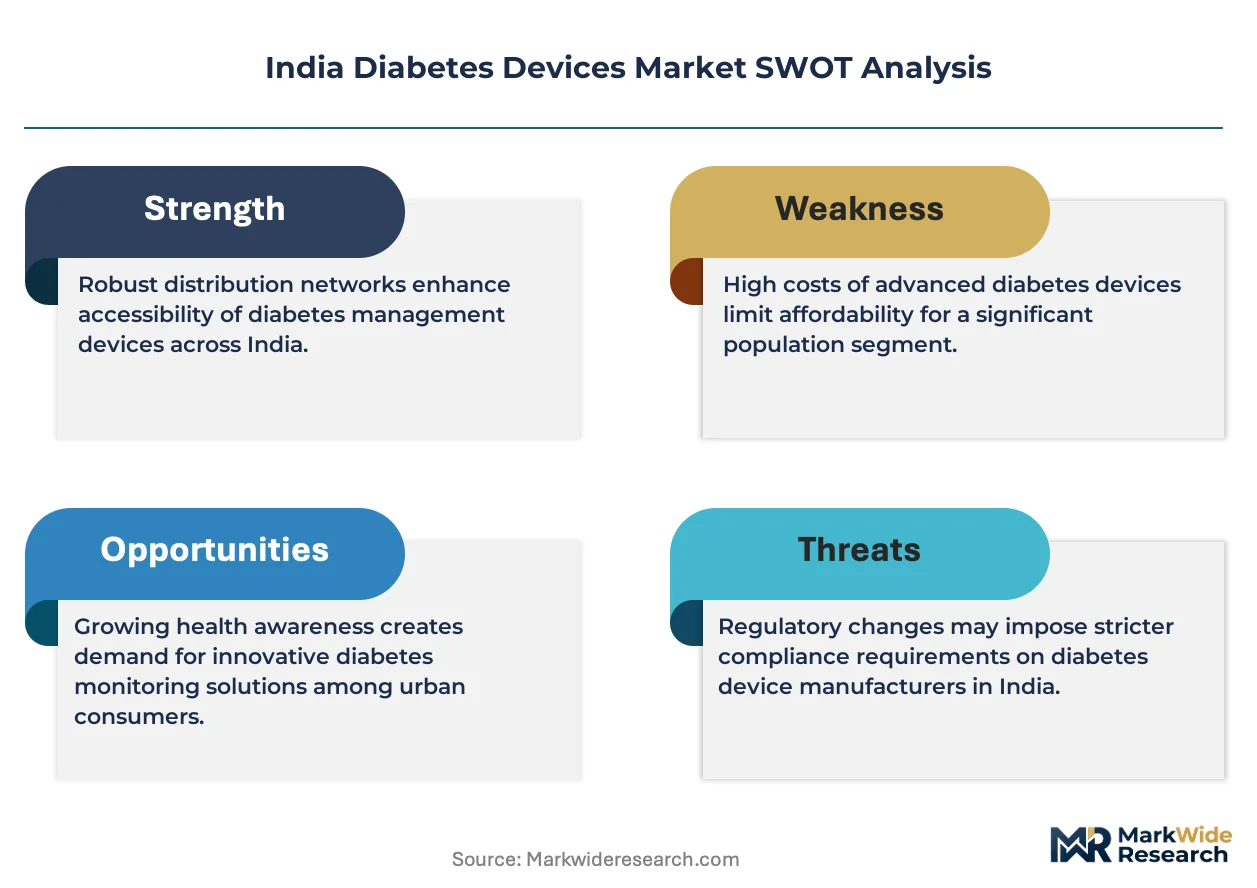
Hospital procurement channels in India is tilting toward direct manufacturer partnerships as states consolidate tender volumes. Abbott leverages its FreeStyle Libre manufacturing presence in Kerala to sustain cost competitiveness in government tenders. Roche anchors its position through diagnostic lab integration, while Medtronic competes via specialized insulin pump training programs for endocrinologists.
India diabetes devices encompass instruments for glucose measurement, insulin delivery, and metabolic monitoring, typically operating through electrochemical enzymatic reactions with measurement precision within 15% of laboratory reference values, serving chronic disease management across outpatient and domiciliary settings. Continuous glucose monitors capture expanding margin pools as wearable sensor technology extends replacement cycles and reduces calibration frequency. Insulin pumps occupy a narrower but higher-value niche where patient self-management capability intersects with reimbursement readiness. Home care delivery mode leads volume absorption as telemedicine infrastructure builds last-mile connectivity into semi-urban catchments.
CDSCO regulates device safety and efficacy under the Medical Device Rules, while BIS enforces electrical safety and electromagnetic compatibility standards for powered equipment, and the PLI scheme incentivizes domestic manufacturing of high-value medtech components. These frameworks compress import dependency timelines while elevating quality benchmarks for market entry. Stakeholders must track state-level tender consolidation patterns and evolving Ayushman Bharat reimbursement eligibility for continuous monitoring technologies.
Market Dynamics
CDSCO's streamlined approval pathway for Class C and D devices is compressing time-to-market for continuous glucose monitors while Maharashtra and Gujarat drive home care adoption among Type 2 diabetes patients.
Growth Catalysts
- PLI scheme incentives:Domestic manufacturing of high-value medtech components receives production-linked incentives, reducing import dependency for sensor assemblies and pump mechanisms.
- Ayushman Bharat expansion:Reimbursement eligibility for continuous monitoring technologies is extending into tier-2 cities where private insurance penetration lags.
- Telemedicine infrastructure:Last-mile connectivity builds into semi-urban catchments across Kerala and Tamil Nadu, enabling remote glucose monitoring and insulin titration support.
Market Restraints
- Sensor import concentration:Enzymatic glucose oxidase membranes and platinum electrode substrates remain concentrated among East Asian suppliers, exposing margins to currency volatility.
- BIS electrical safety certification:Powered insulin pumps face extended electromagnetic compatibility testing timelines that delay commercial launch by six to nine months.
- Calibration frequency limitations:Factory-calibrated sensors reduce user burden but constrain accuracy in hematocrit-variant populations prevalent in northern plains.
Strategic Opportunities
- Tier-2 city penetration:Endocrinology infrastructure gaps in Madhya Pradesh and Rajasthan create first-mover advantages for hub-and-spoke diagnostic networks.
- CGM-insulin pump convergence:Closed-loop algorithm integration between wearable sensors and patch pumps addresses unmet needs among pediatric Type 1 cohorts.
- State tender consolidation:Direct manufacturer partnerships with Maharashtra and Karnataka bypass distributor markups while securing multi-year volume commitments.
Industry Challenges
- Endocrinologist training bandwidth:Specialized insulin pump certification programs require twelve to eighteen months, constraining patient onboarding velocity in high-growth districts.
- Legacy glucometer data silos:Proprietary data formats from incumbent devices impede seamless migration to continuous monitoring platforms without manual entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Diabetes Devices Market |
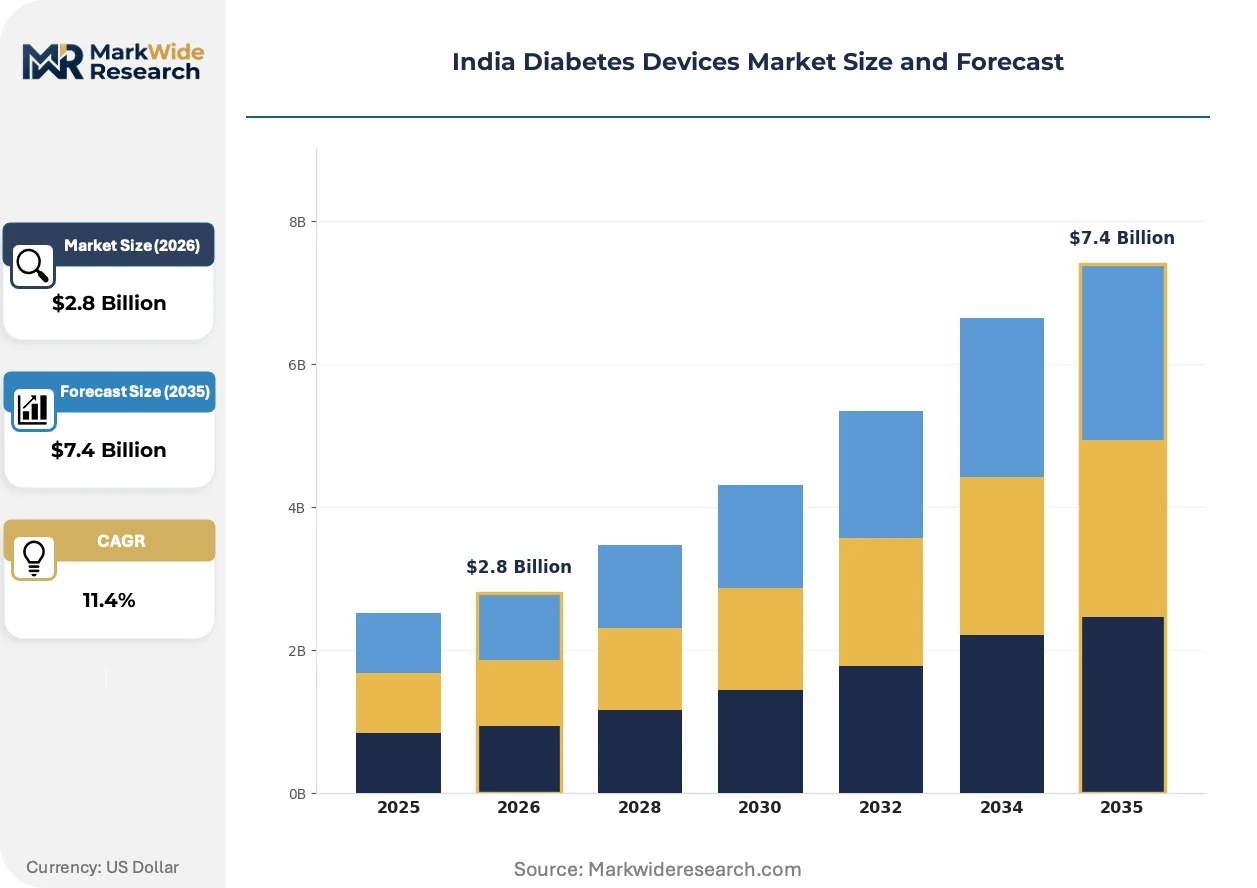
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
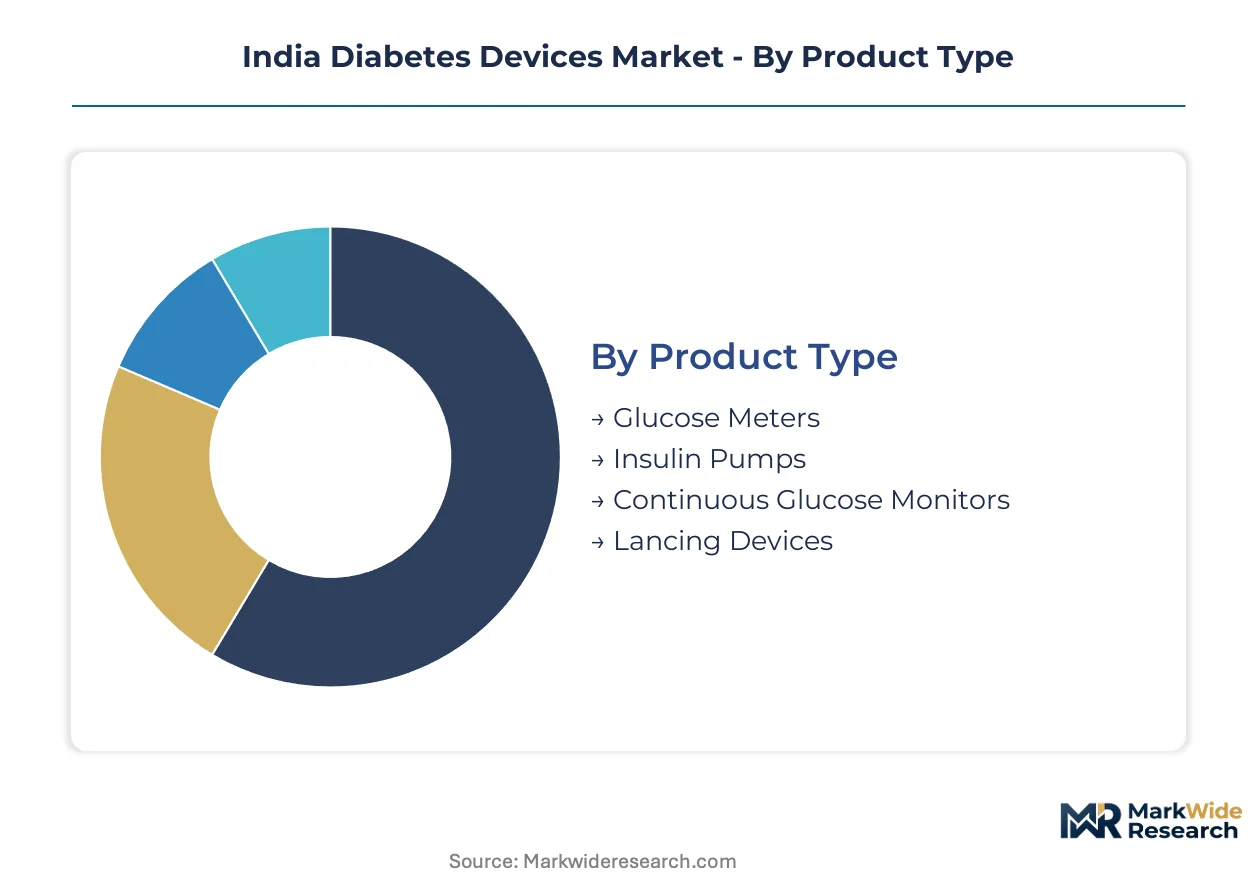
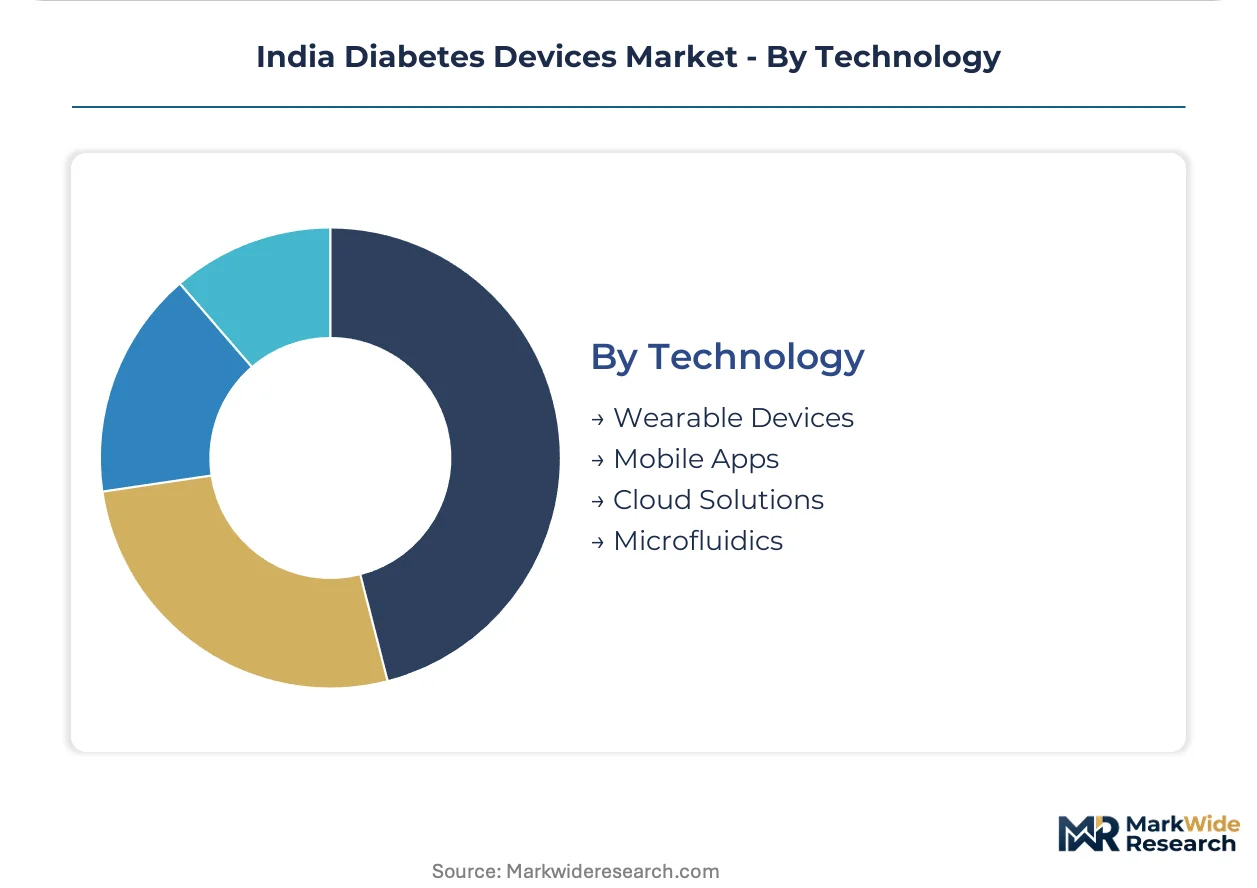
| Segmentation | Product Type: Glucose Meters, Insulin Pumps, Continuous Glucose Monitors, Lancing Devices Delivery Mode: Home Care, Hospital Care, Telemedicine, Remote Monitoring Customer Type: Patients, Healthcare Professionals, Caregivers, Insurance Providers Technology: Wearable Devices, Mobile Apps, Cloud Solutions, Microfluidics |
| Companies Covered | Abbott, Roche, Medtronic, Dexcom, Becton Dickinson, Novo Nordisk, Sanofi, Eli Lilly and Company, Insulet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Diabetes Devices Market Shifts & Advancements
Sensor miniaturization and algorithmic glucose prediction are converging to extend wearable replacement cycles while reducing patient calibration burden across outpatient and domiciliary settings.
Continuous glucose monitoring is migrating from physician-prescribed hospital procurement to direct-to-consumer pharmacy channels. Urban Type 2 patients in Mumbai and Delhi bypass endocrinology referrals for over-the-counter sensor purchases. This shift compresses margin capture for traditional distribution intermediaries while expanding addressable patient populations beyond diagnosed cohorts.
CDSCO's risk-based classification framework for Software as Medical Device is accelerating algorithm-enabled glucose prediction approvals. Manufacturers submit pre-market dossiers with real-world performance data from Indian cohorts. This regulatory evolution favors domestic clinical trial infrastructure investments and compresses validation timelines for AI-augmented monitoring systems.
Hospital procurement committees in tier-1 cities now bundle continuous monitoring with insulin delivery systems under single-vendor contracts. Maharashtra's consolidated tender volumes favor suppliers offering integrated training and remote patient monitoring support. This concentration pattern disadvantages standalone glucometer manufacturers lacking pump or sensor portfolio breadth.
India Diabetes Devices Market Segmentation
Device segmentation in India reveals how reimbursement pathways, patient self-management capability, and infrastructure maturity create divergent commercial trajectories across product categories. Understanding these fault lines enables targeted resource allocation where margin pools and volume expansion overlap.
Product Type:
Glucose measurement, insulin delivery, and metabolic monitoring instruments serve distinct patient cohorts across outpatient and domiciliary settings in Maharashtra, Gujarat, and Kerala.
- Glucose Meters:Electrochemical enzymatic systems with measurement precision within 15% of laboratory reference values dominate government tender volumes across tier-1 cities. Procurement committees in Maharashtra and Karnataka favor bundled contracts with consumable supply commitments, compressing standalone device margins.
- Continuous Glucose Monitors:Wearable sensor technology with extended replacement cycles and reduced calibration frequency captures expanding margin pools among Type 1 pediatric cohorts in Mumbai and Delhi. CDSCO's streamlined Class C and D approval pathway accelerates time-to-market for factory-calibrated systems.
- Insulin Pumps:Specialized devices serving narrow but higher-value niches where patient self-management capability intersects with private insurance penetration in tier-1 hospital networks.
- Lancing Devices:Peripheral consumables integrated into glucose meter ecosystem strategies, with cost pressure from state tender consolidation limiting standalone pricing power.
The dominant share belongs to glucose meters, while continuous glucose monitors are closing the gap fastest.
Delivery Mode:
Channel configuration tracks infrastructure maturity and reimbursement evolution across urban and semi-urban catchments.
- Home Care:Direct-to-consumer pharmacy channel expansion in Mumbai and Delhi enables over-the-counter sensor purchases without endocrinology referrals. This shift compresses traditional distribution markups while extending addressable populations beyond diagnosed cohorts in Maharashtra and Gujarat.
- Telemedicine:Last-mile connectivity builds into semi-urban catchments across Kerala and Tamil Nadu, enabling remote glucose monitoring and insulin titration support for Type 2 patients lacking local endocrinology access.
- Hospital Care:Consolidated tender volumes in tier-1 cities favor suppliers offering integrated training and remote patient monitoring support under single-vendor contracts.
- Remote Monitoring:Hub-and-spoke diagnostic networks address endocrinology infrastructure gaps in Madhya Pradesh and Rajasthan through centralized specialist oversight of distributed glucose data.
Home care commands the largest volume absorption, though telemedicine is gaining share fastest as infrastructure penetrates tier-2 cities.
Customer Type:
Purchasing authority fragments across self-pay patients, institutional procurement, and emerging reimbursement intermediaries.
- Patients:Urban Type 2 cohorts in Delhi and Mumbai drive direct-to-consumer pharmacy purchases of continuous monitoring systems, bypassing traditional referral pathways and expanding addressable demand beyond clinically diagnosed populations.
- Healthcare Professionals:Endocrinologists in tier-1 cities prescribe integrated pump-sensor systems, with twelve-to-eighteen-month certification timelines constraining patient onboarding velocity in high-growth districts.
- Caregivers:Pediatric Type 1 diabetes management in Kerala and Tamil Nadu relies on caregiver-operated closed-loop systems, creating demand for simplified algorithm interfaces and remote monitoring dashboards.
- Insurance Providers:Ayushman Bharat eligibility extension into tier-2 cities creates reimbursement readiness gaps where private insurance penetration lags, requiring hybrid payment models for continuous monitoring adoption.
Patients generate the highest transaction frequency, while insurance providers are scaling fastest through Ayushman Bharat expansion.
Technology:
Digital and hardware technology stacks determine calibration burden, data interoperability, and algorithmic prediction accuracy across Indian patient populations.
- Wearable Devices:Sensor miniaturization extends replacement cycles while reducing patient calibration burden, though factory-calibrated systems face accuracy constraints in hematocrit-variant populations prevalent in northern plains.
- Mobile Apps:CDSCO's Software as Medical Device risk-based classification framework accelerates algorithm-enabled glucose prediction approvals, favoring domestic clinical trial infrastructure investments.
- Cloud Solutions:Proprietary data formats from legacy glucometer incumbents impede seamless migration to continuous monitoring platforms without manual entry, creating switching friction.
- Microfluidics:Emerging electrochemical architectures for enzymatic glucose oxidase membranes face import concentration risk among East Asian suppliers, exposing margins to currency volatility.
Wearable devices hold the installed base lead, while mobile apps are climbing the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands pricing premiums through consolidated tender volumes while Madhya Pradesh absorbs cost-sensitive procurement, creating a 40% price differential across state boundaries that manufacturers must navigate through differentiated product tiers.
Maharashtra
Mumbai and Pune drive continuous glucose monitor adoption through direct-to-consumer pharmacy channels bypassing traditional referrals. CDSCO's streamlined Class C and D device approvals accelerate time-to-market for factory-calibrated systems in this cluster. Hospital procurement committees in Mumbai bundle monitoring with insulin delivery under single-vendor contracts favoring integrated suppliers.
Gujarat
Ahmedabad and Surat anchor home care expansion among Type 2 diabetes patients with rising private insurance penetration. The state's tender consolidation patterns favor direct manufacturer partnerships reducing distributor markups. Abbott leverages its FreeStyle Libre manufacturing presence in Kerala to sustain cost competitiveness in Gujarat government tenders.
Karnataka
Bengaluru's telemedicine infrastructure builds last-mile connectivity into semi-urban catchments enabling remote glucose monitoring. BIS electrical safety certification timelines for powered insulin pumps extend commercial launch windows by six to nine months here. Endocrinology training programs at Manipal and Narayana Health networks constrain patient onboarding velocity despite device availability.
Tamil Nadu
Chennai and Coimbatore pediatric Type 1 cohorts drive demand for caregiver-operated closed-loop systems with simplified algorithm interfaces. PLI scheme incentives for domestic sensor assembly reduce import dependency for enzymatic glucose oxidase membranes. Hub-and-spoke diagnostic networks address specialist access gaps in Madurai and Tiruchirappalli through centralized oversight.
Delhi-NCR
The capital region concentrates Ayushman Bharat reimbursement eligibility expansion for continuous monitoring technologies into tier-2 satellite cities. Factory-calibrated sensors face accuracy constraints in hematocrit-variant populations prevalent across northern plains catchments. Diagnostic lab integration by Roche anchors institutional procurement relationships with Max and Apollo hospital networks.
India Diabetes Devices Market Competitive Landscape
Multinational device conglomerates and specialized insulin delivery specialists split the market between integrated monitoring-pump ecosystems and standalone glucose measurement platforms. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with manufacturing presence in southern India, pure-play continuous monitoring specialists leveraging CDSCO regulatory tailwinds, and pharmaceutical-insulin manufacturers extending into delivery hardware. Dominant competitive moves include state tender consolidation partnerships and backward integration into sensor component manufacturing.
Among diversified conglomerates, Abbott and Roche exemplify the integrated diagnostics-to-delivery archetype through manufacturing presence and lab network anchoring. Medtronic occupies the specialized insulin pump training position where twelve-to-eighteen-month endocrinologist certification programs create competitive moats. Dexcom represents the pure-play continuous monitoring vector capitalizing on direct-to-consumer channel migration in Mumbai and Delhi pharmacy networks.
| Leading Market Players |
|---|
| Abbott |
| Roche |
| Medtronic |
| Dexcom |
| Becton Dickinson |
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Insulet |
| Others |
Supply & Pricing Matrix
Enzymatic glucose oxidase membrane import concentration among East Asian suppliers compresses margin buffers while simultaneously dictating tiered pricing spreads between factory-calibrated and physician-configured continuous monitoring systems. This single-source dependency for platinum electrode substrates forces manufacturers to absorb currency volatility through premium tier markups or surrender standard tier margins.
Pricing Analysis
The customization-premium spread separates factory-calibrated continuous glucose monitors from physician-configured systems requiring endocrinologist intervention. Pricing stratifies across premium, standard, and economy tiers based on calibration automation level and CDSCO Class C/D certification grade. Cost compression in the economy tier intensifies as state tender consolidation in Maharashtra and Karnataka demands bundled consumable commitments. Government procurement committees exhibit highest price sensitivity, while private hospital networks in Mumbai and Delhi tolerate premium positioning for integrated pump-sensor ecosystems.
Supply Chain Analysis
Upstream feedstock for enzymatic sensors draws from South Korea, Japan, and Taiwan for platinum electrode substrates and glucose oxidase membrane chemistry. Raw material dependencies center on rare earth catalysts, medical-grade polymers, and precision electrochemical substrates. Single-source vulnerability concentrates in East Asian membrane suppliers, exposing landed costs to tariff volatility and shipping chokepoints. Distribution runs through direct manufacturer partnerships with state procurement bodies, bypassing traditional distributor markups in consolidated tender markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's diabetes device market sits at a platform-economics inflection where closed-loop algorithm integration between sensors and pumps is displacing standalone glucometer ecosystems. Interoperability standards and data format unification will determine which vendor architectures capture the next patient cohort.
For Market Incumbents: Entrench through backward integration into sensor component manufacturing and captive supply of enzymatic membranes to offset East Asian import dependency. Secure multi-year direct partnerships with Maharashtra and Karnataka state tender bodies before emerging pure-play monitoring specialists achieve CDSCO Class C scale. Prioritize certification bandwidth expansion for endocrinologist training programs to constrain competitor patient onboarding velocity. For New Entrants and Emerging Players: Pursue tier-2 city hub-and-spoke diagnostic networks in Madhya Pradesh and Rajasthan where endocrinology infrastructure gaps create first-mover windows. Target caregiver-operated closed-loop pediatric systems in Tamil Nadu and Kerala through simplified algorithm interfaces. Anchor go-to-market strategy through telemedicine platform partnerships rather than hospital procurement committee penetration. For Investors and Strategic Acquirers: Software-as-Medical-Device specialists with CDSCO pre-market dossier experience and domestic clinical trial infrastructure represent the highest-conviction acquisition archetype. Long-term viability hinges on algorithmic prediction accuracy validated against Indian hematocrit-variant populations. Watch for Ayushman Bharat reimbursement eligibility expansion into tier-2 cities as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C/D Approval Pathway | Accelerates time-to-market for factory-calibrated continuous monitoring systems in Maharashtra. |
| State Tender Consolidation Partnership | Secures multi-year volume commitments with Karnataka and Maharashtra procurement committees. |
| Backward Integration into Sensor Assembly | Captures PLI scheme incentives while reducing East Asian membrane import dependency. |
| Endocrinologist Certification Program | Creates twelve-to-eighteen-month competitive moats around insulin pump patient onboarding. |
| Telemedicine Platform Integration | Enables last-mile connectivity into Kerala and Tamil Nadu semi-urban catchments. |
Research Methodology
Operator-level perspectives from hospital procurement managers, biomedical engineers, endocrinology department heads, and GPO contracts specialists anchored the qualitative base. Primary interviews combined with secondary validation from CDSCO medical device registration databases, Ayushman Bharat reimbursement eligibility filings, and state tender consolidation records. Bottom-up patient cohort sizing and top-down device shipment triangulation converged on segment-level estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around PLI scheme uptake rates and reimbursement expansion timing. Segmentation dimensions modeled include device type, delivery mode, customer purchasing authority, and technology stack. CAGRs derived from installed base evolution, replacement cycle extension, and patient population growth trajectories. Forecast inputs incorporated CDSCO approval pipeline velocity and state-level tender consolidation patterns.
Sensitivities concentrate around East Asian currency volatility, BIS electromagnetic compatibility certification delays, and Ayushman Bharat tier-2 eligibility timing. Forecasts reflect documented assumptions on sensor replacement cycle extension and algorithm accuracy improvement curves. Cross-checking against hospital procurement database benchmarks and GPO contract award records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Smart Implants Market
Medical Devices
Surgical Devices Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
US C-Arms Market
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Appendage Management Market
Medical Devices
Clear Aligners Market
Medical Devices
Ocular Implants Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Gum Grafting Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Europe Ventilator Market