
 Medical Polyetheretherketone Market | 2026-2036
Medical Polyetheretherketone Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Polyetheretherketone Market Intelligence
ISO 10993 biocompatibility certification is rotating toward stricter cytotoxicity and sensitization testing tiers, filtering which compounders qualify for long-term implant supply. Victrex plc leverages its Lancashire manufacturing base to sustain captive resin-to-implant supply chains. Invibio Ltd. anchors the dental and spine segments through proprietary PEEK-OPTIMA grades. Solvay competes via differentiated sulfone-PEEK blends for instruments requiring repeated sterilization.
Medical polyetheretherketone is a semi-crystalline aromatic polymer with a glass transition temperature near 143°C and elastic modulus comparable to human cortical bone, produced through nucleophilic aromatic substitution of 4,4'-difluorobenzophenone with hydroquinone. Its primary purpose is to replace metal in permanent and semi-permanent implants where radiolucency, chemical inertness, and reduced stress shielding improve patient outcomes. The implants category leads value generation due to multi-year regulatory validation cycles and premium pricing for spinal and trauma applications, while orthopedics dominates volume through knee and hip bearing trials expanding PEEK-on-ceramic articulation. Dentistry represents the fastest-climbing application as CAD/CAM milled PEEK frameworks displace cobalt-chrome for removable partial dentures.
FDA 510(k) and EU MDR frameworks require implant-grade PEEK suppliers to maintain batch-level biocompatibility documentation, elevating compliance costs for smaller compounders. Japan's PMDA and China's NMPA have synchronized their polymer master file requirements with ISO 10993-18 chemical characterization standards, creating parallel but convergent approval tracks. Stakeholders must monitor whether recycled-content mandates from the EU Green Deal extend to medical polymers, as this would force requalification of established resin streams.
Market Dynamics
FDA 510(k) clearance pathways and EU MDR conformity requirements are tightening material traceability standards, forcing compounders to invest in batch-level biocompatibility documentation systems. This regulatory compression is reshaping which suppliers qualify for long-term implant contracts.
Growth Catalysts
- ISO 10993-18 Chemical Characterization:Synchronized adoption by Japan's PMDA and China's NMPA creates parallel approval tracks, reducing redundant testing burdens for multinational device manufacturers.
- Spinal Interbody Fusion Cages:PEEK's elastic modulus matching human cortical bone drives substitution of titanium in lumbar fusion procedures, particularly in German orthopedic clusters around Stuttgart.
- CAD/CAM Milled Frameworks:Dental laboratories are displacing cobalt-chrome with PEEK for removable partial dentures, accelerating demand from prosthetic milling centers.
Market Restraints
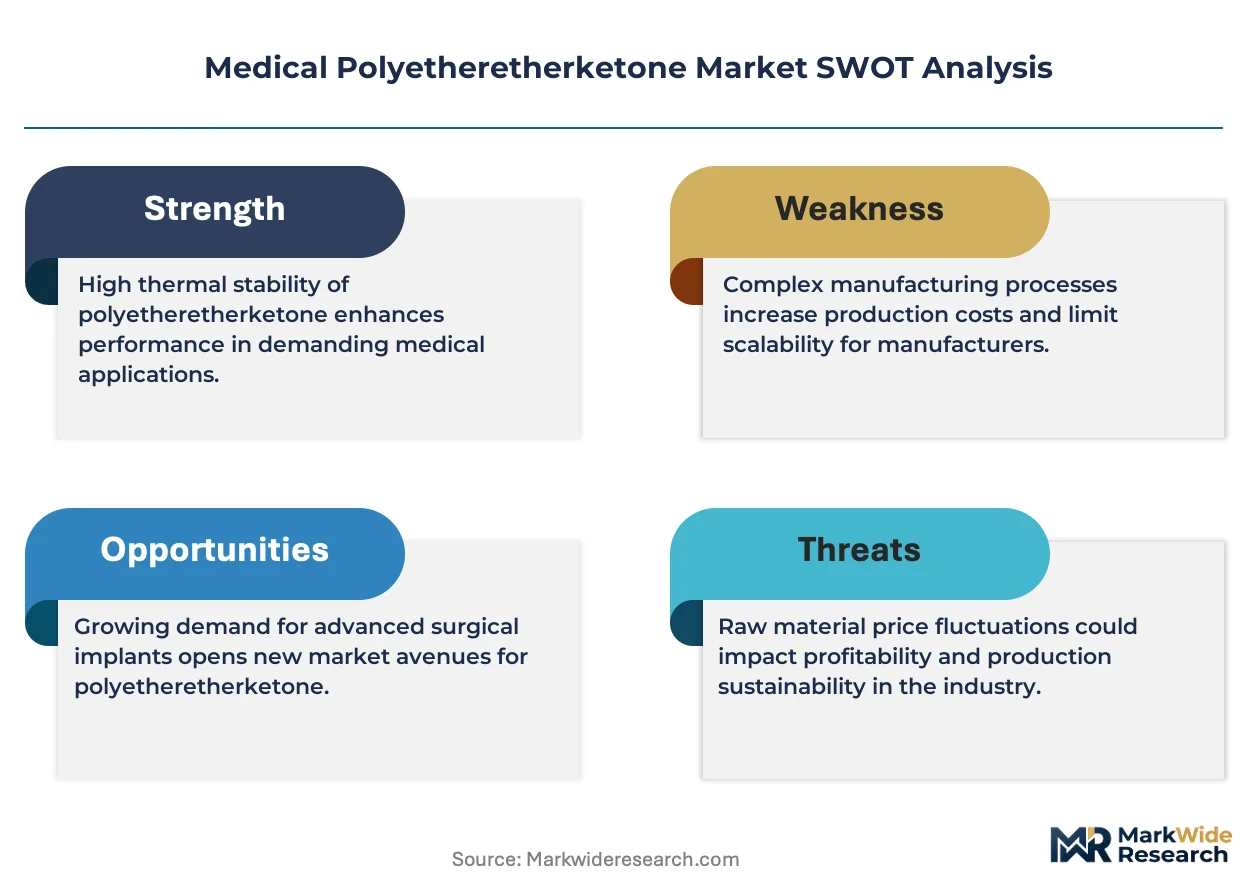
- Fluorobenzophenone Feedstock Volatility:Nucleophilic aromatic substitution requires 4,4'-difluorobenzophenone, whose pricing tracks benzene and fluorine chemical cycles with limited supplier diversification.
- Lancashire Supply Concentration:Captive resin-to-implant supply chains concentrate high-grade PEEK production in northwest England, creating geographic single-point-of-failure exposure.
- Titanium Substitution Persistence:Metal implants retain preference in load-bearing trauma applications where radiolucency offers no clinical advantage, limiting PEEK addressable market.
Strategic Opportunities
- EU Green Deal Recycled Content Mandates:Potential extension to medical polymers would force requalification of established resin streams, creating first-mover advantage for compounders with validated recycling pathways.
- PEEK-on-Ceramic Articulation:Knee and hip bearing trials are expanding PEEK use in orthopedics, opening volume markets beyond spine and dental applications.
- Sulfone-PEEK Blend Instruments:Repeated sterilization requirements in surgical tool sets favor hybrid polymers combining PEEK's mechanical properties with polysulfone thermal resistance.
Industry Challenges
- Biocompatibility Testing Talent Scarcity:ISO 10993 cytotoxicity and sensitization testing tiers require specialized toxicologists, with qualification bottlenecks extending regulatory timelines.
- Master File Maintenance Burden:Polymer master files for PMDA, NMPA, and FDA require parallel documentation systems, multiplying compliance headcount for mid-tier compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Polyetheretherketone Market |
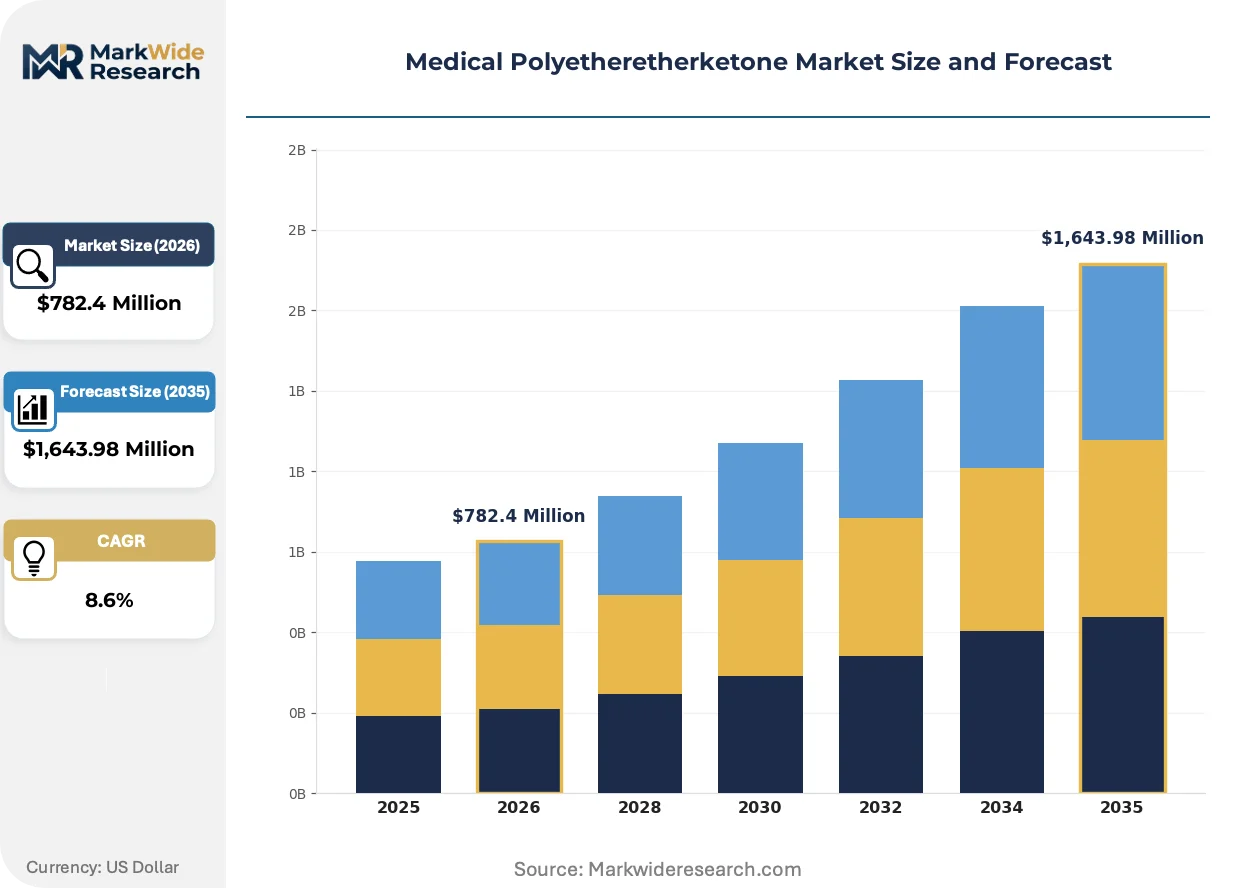
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,643.98 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Devices, Implants, Surgical Instruments, Prosthetics Application: Orthopedics, Dentistry, Cardiology, Neurology End User: Hospitals, Clinics, Research Laboratories, Rehabilitation Centers Delivery Mode: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Solvay, Medtronic, Invibio Ltd., Ensinger GmbH, Celanese Corporation, Victrex plc, Superior Polymers, Semadeni AG, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Polyetheretherketone Market Strategic Shifts & Innovations
Medical PEEK formulation strategies are diverging as end-use specifications harden, with spinal, dental, and instrument applications demanding increasingly specialized compound properties. This specification fragmentation is forcing compounders to choose between breadth and depth.
Reinforced PEEK composites containing carbon fiber or barium sulfate are fragmenting the traditional homogeneous polymer market. Spinal implant manufacturers in Germany specify radiopaque grades for post-operative imaging visibility, while trauma plate producers favor carbon-reinforced variants for modulus tuning. The technology is fragmenting compounder portfolios into application-specific product lines with non-overlapping qualification requirements.
EU MDR Article 10 technical documentation requirements now mandate supply chain disclosure for implant-grade polymers. Device manufacturers must demonstrate economic operator accountability through raw material sourcing records. German notified bodies are enforcing this most stringently, delaying market entry for compounders lacking established quality management systems.
Hospital procurement departments are consolidating polymer sourcing through approved supplier lists, displacing traditional distributor relationships. Academic medical centers in the United States now require direct manufacturer contracts with batch traceability guarantees. This concentration is most visible in integrated delivery networks controlling multiple implant categories across spine, trauma, and dental service lines.
Medical Polyetheretherketone Market Segmentation
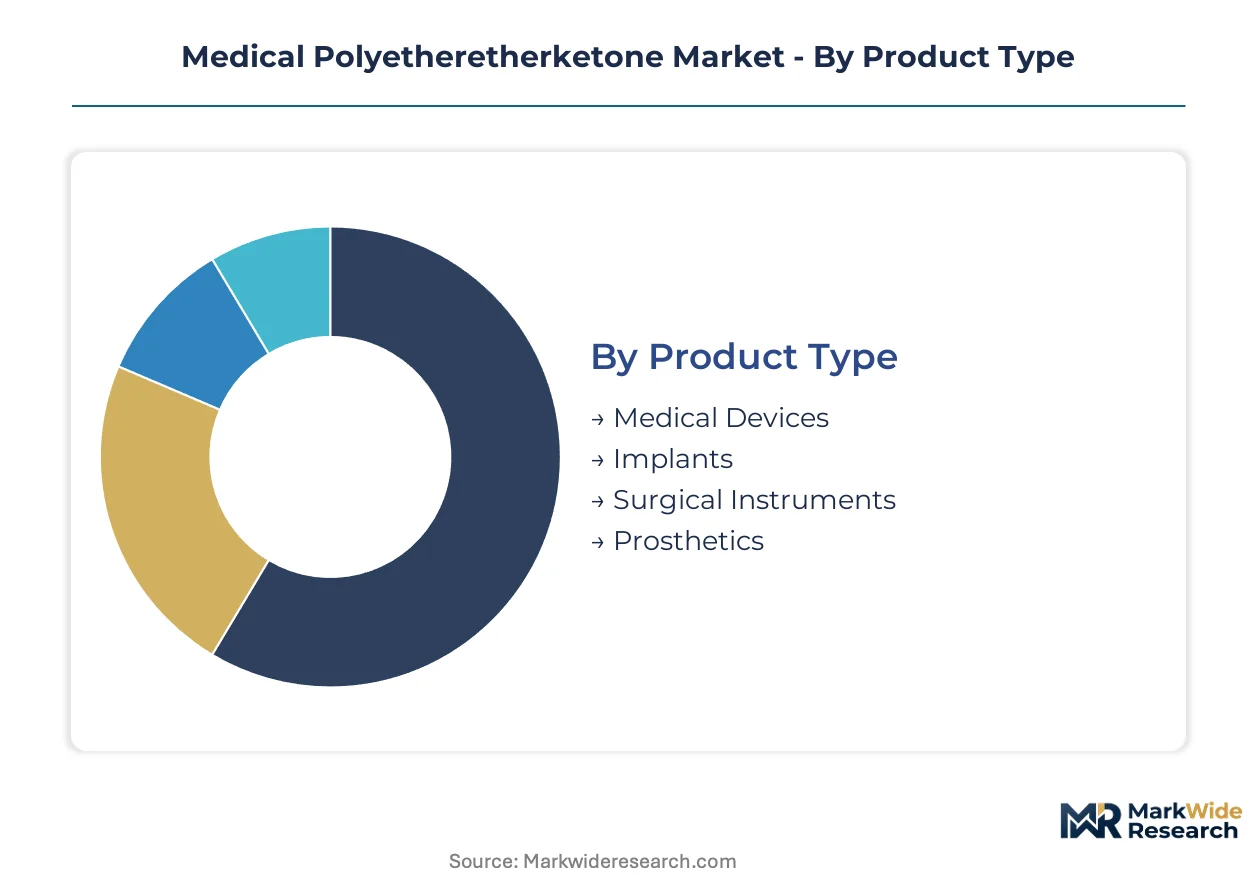
Medical PEEK segmentation reflects diverging specification requirements across implant durability, device sterilization cycles, and prosthetic customization. Each category carries distinct regulatory validation burdens and substitution pressures from titanium, cobalt-chrome, and emerging ceramic alternatives.
Product Type:
Implants face the most acute substitution pressure from titanium in load-bearing trauma applications, while surgical instruments compete against reusable metal tool sets on cost-per-use metrics.
- Implants:Spinal interbody fusion cages and trauma plates demand radiopaque grades with barium sulfate loading for post-operative imaging visibility. German orthopedic clusters around Stuttgart specify these grades for lumbar fusion procedures where modulus matching cortical bone drives clinical preference.
- Medical Devices:PEEK components in diagnostic and therapeutic equipment require repeated autoclave compatibility. Solvay's sulfone-PEEK blends address this thermal stress, capturing procurement contracts from academic medical centers requiring direct manufacturer traceability.
- Surgical Instruments:Reusable tool handles and retractors favor carbon-reinforced PEEK for stiffness-to-weight ratios. Procurement departments increasingly require batch-level biocompatibility documentation under EU MDR Article 10.
- Prosthetics:CAD/CAM milled frameworks for removable partial dentures displace cobalt-chrome in dental laboratories. Prosthetic milling centers in Germany and the United States drive volume demand for unfilled PEEK-OPTIMA grades.
Implants anchor the volume base while prosthetics gains share at the steepest rate.
Application:
Cost tier differentiation separates premium implant-grade formulations from standard industrial PEEK, with cardiology and neurology commanding the highest purity premiums due to permanent implant exposure.
- Orthopedics:Knee and hip bearing trials are expanding PEEK-on-ceramic articulation beyond traditional spine applications. Carbon fiber reinforcement enables modulus tuning for trauma plates, though titanium retains preference in high-load fracture fixation.
- Dentistry:CAD/CAM milled frameworks for removable partial dentures represent the fastest-climbing application. Dental laboratories in Germany and Japan are displacing cobalt-chrome with PEEK for biocompatibility and patient comfort.
- Cardiology:Pacemaker headers and implantable device housings require ultra-high purity grades with minimal extractables. FDA 510(k) clearance pathways demand extensive cytotoxicity testing for permanent blood-contacting applications.
- Neurology:Cranial plates and dura mater substitutes utilize unfilled PEEK for radiolucency during post-operative MRI monitoring. Japan's PMDA maintains stringent polymer master file requirements for neurosurgical implants.
Orthopedics captures the largest revenue pool while dentistry expands most quickly.
End User:
Customer type determines procurement complexity, with hospitals consolidating through approved supplier lists while research laboratories tolerate longer qualification timelines for experimental grades.
- Hospitals:Integrated delivery networks in the United States now require direct manufacturer contracts with batch traceability guarantees. Academic medical centers enforce this concentration across spine, trauma, and dental service lines.
- Clinics:Outpatient surgical centers favor standardized implant kits with pre-qualified PEEK components. Distributor relationships dominate procurement, though EU MDR economic operator accountability requirements are forcing direct manufacturer engagement.
- Research Laboratories:Experimental PEEK formulations for next-generation composites and surface modifications flow through specialized compounders. ISO 10993-18 chemical characterization standards apply even to pre-clinical material evaluation.
- Rehabilitation Centers:Prosthetic fitting and customization services drive demand for CAD/CAM milling blanks. German rehabilitation networks coordinate with Stuttgart-area orthopedic device clusters for rapid turnaround.
Hospitals dominate procurement volume while research laboratories show the steepest growth in specialized grade demand.
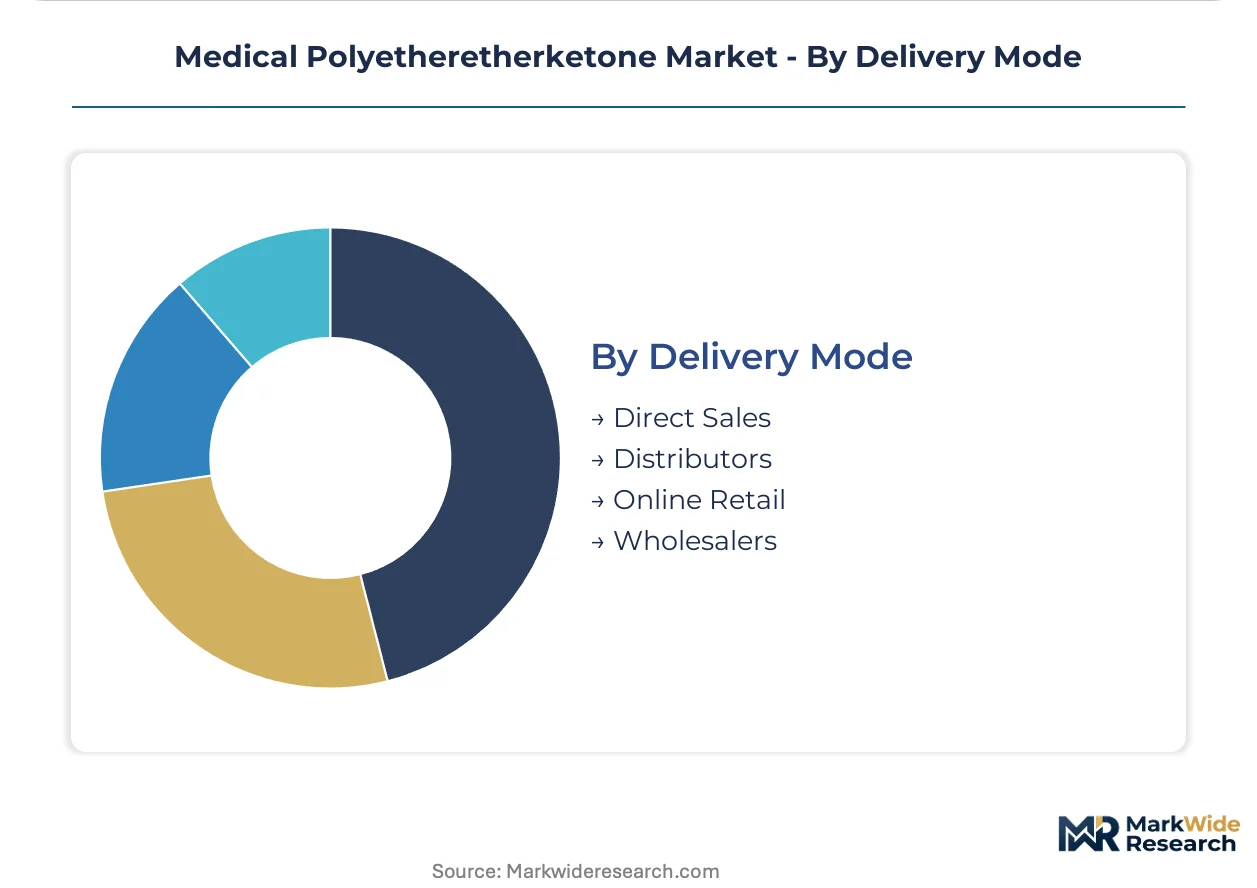
Delivery Mode:
Supply concentration in northwest England shapes distribution economics, with direct sales capturing premium implant contracts while distributors retain relevance in fragmented dental and instrument markets.
- Direct Sales:Spinal implant manufacturers and major orthopedic device firms contract directly with Victrex and Invibio for captive resin-to-implant supply chains. FDA and EU MDR batch traceability requirements favor this channel for implant-grade material.
- Distributors:Dental laboratories and smaller device manufacturers rely on regional distributors for PEEK milling blanks and semi-finished stock. German notified bodies are enforcing supply chain disclosure most stringently, pressuring distributor transparency.
- Online Retail:Standard industrial PEEK grades for research and prototyping flow through specialized polymer e-commerce platforms. Medical-grade material remains restricted to qualified buyers with device manufacturer credentials.
- Wholesalers:Surgical instrument manufacturers source sulfone-PEEK blends through chemical industry wholesalers with established logistics networks. Repeated sterilization requirements favor hybrid polymers with documented thermal resistance.
Direct sales commands the premium tier while distributor channels face margin compression from regulatory documentation burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and EU MDR conformity requirements are tightening material traceability standards, forcing compounders to invest in batch-level biocompatibility documentation systems across major medical device manufacturing jurisdictions.
Germany
Orthopedic device clusters around Stuttgart and Frankfurt drive specialized PEEK compound consumption for spinal interbody fusion cages. EU MDR Article 10 technical documentation requirements mandate supply chain disclosure for implant-grade polymers, with German notified bodies enforcing economic operator accountability most stringently. Stuttgart-area manufacturers specify radiopaque grades with barium sulfate loading for post-operative imaging visibility in lumbar fusion procedures.
United States
Academic medical centers and integrated delivery networks consolidate polymer sourcing through approved supplier lists with direct manufacturer contracts. FDA batch traceability requirements favor captive resin-to-implant supply chains for spinal implant manufacturers. Hospital procurement departments across major metropolitan areas now require batch-level biocompatibility documentation guarantees across spine, trauma, and dental service lines.
Japan
PMDA polymer master file requirements for neurosurgical implants maintain stringent qualification standards for cranial plates and dura mater substitutes. METI coordinates with domestic device manufacturers to synchronize ISO 10993-18 chemical characterization standards with national approval tracks. Kanto-region medical device clusters source unfilled PEEK grades for radiolucency during post-operative MRI monitoring.
China
NMPA has synchronized polymer master file requirements with ISO 10993-18 standards, creating parallel but convergent approval tracks for multinational device manufacturers. MIIT oversees domestic compounder qualification for implant-grade PEEK as knee and hip bearing trials expand. Yangtze River Delta medical device manufacturing zones drive demand for carbon fiber-reinforced variants in trauma plate applications.
Switzerland
Swissmedic maintains premium-tier regulatory validation for ultra-high purity grades with minimal extractables in permanent blood-contacting applications. The country's precision manufacturing base supports specialized compounders serving cardiology device segments. Basel-area chemical industry clusters provide fluorobenzophenone feedstock expertise for nucleophilic aromatic substitution production pathways.
Medical Polyetheretherketone Market Key Industry Players
Listed leaders compete with private specialists across regulatory qualification depth, with public compounders leveraging capital market access for ISO 10993 certification investments while private firms retain flexibility in niche formulation development. The vendor base organizes around three strategic archetypes: integrated resin-to-implant suppliers, specialized medical-grade compounders, and diversified chemical conglomerates with healthcare divisions. Competitive moves concentrate on backward integration into fluorobenzophenone feedstock security and geographic expansion into German orthopedic clusters.
Within the integrated supplier tier, Victrex plc and Invibio Ltd. exemplify archetypes of captive manufacturing control. Solvay occupies a position among diversified chemical conglomerates leveraging sulfone blend expertise. Ensinger GmbH represents the specialized compounder archetype with European manufacturing concentration.
| Leading Market Players |
|---|
| Solvay |
| Medtronic |
| Invibio Ltd. |
| Ensinger GmbH |
| Celanese Corporation |
| Victrex plc |
| Superior Polymers |
| Semadeni AG |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Captive resin-to-implant manufacturing at scale creates durable cost advantages for compounders with Lancashire production bases, simultaneously elevating price floors for mid-tier entrants lacking ISO 10993 certification depth and batch-level documentation systems. This scale-certification nexus concentrates pricing power among established suppliers while forcing smaller competitors toward distributor-dependent margin structures.
Pricing Analysis
Certification level creates the primary spread across implant-grade PEEK tiers, with FDA 510(k)-cleared and EU MDR-conforming material commanding substantial premiums over industrial grades. Three-tier pricing structure across premium implant-grade, standard medical-device, and economy industrial levels reflects differentiation by biocompatibility testing depth and master file maintenance burden. Cost compression in mid-tier dental milling blanks is intensifying because German prosthetic centers consolidate procurement through approved supplier lists. Research laboratories exhibit highest price sensitivity due to experimental volume unpredictability, while spinal implant manufacturers demonstrate lowest sensitivity given multi-year regulatory validation cycles.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes compound lead time uncertainty for fluorobenzophenone feedstock shipments from Chinese chemical manufacturers. High-grade PEEK production concentrates in the United Kingdom, Germany, and Switzerland, drawing from difluorobenzophenone, hydroquinone, and specialized catalyst inputs. Single-source vulnerability pervades nucleophilic aromatic substitution chemistry due to limited qualified suppliers of pharmaceutical-grade fluorobenzophenone. Distribution runs through direct manufacturer contracts for implant-grade material, with regional distributors retaining relevance in fragmented dental and instrument segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs formidable defensive moats in medical PEEK, as polymer master file maintenance and ISO 10993 certification timelines create switching costs that lock device manufacturers into established supplier relationships.
For Market Incumbents: Fortify backward integration into fluorobenzophenone feedstock security to offset benzene cycle volatility, while expanding carbon fiber compounding capacity in Stuttgart-area orthopedic clusters. Emerging sulfone-PEEK blend competitors from diversified chemical conglomerates threaten instrument segment margins, necessitating preemptive capacity addition in thermal-resistant hybrid polymer grades. For New Entrants and Emerging Players: ISO 10993-18 chemical characterization fast-track alignment with Japan's PMDA and China's NMPA offers parallel approval pathway efficiency for multinational device manufacturer qualification. Dental CAD/CAM milling centers in Germany and the United States represent the most penetrable white-space target, with prosthetic laboratory direct contracting as the viable go-to-market angle bypassing hospital procurement consolidation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized compounders with established EU MDR Article 10 quality management systems and radiopaque grade formulation libraries. Long-term viability hinges on regulatory qualification asset durability rather than volume scale, with acquisition targets centering on European notified body relationships and Stuttgart-area customer density. EU Green Deal recycled-content mandate extension to medical polymers serves as the critical inflection signal for first-mover recycling pathway validation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 10 Compliance Investment | Batch-level biocompatibility documentation secures German notified body approval for implant contracts. |
| Backward Integration into Fluorobenzophenone | Captive feedstock supply insulates compounders from benzene and fluorine chemical cycle volatility. |
| Radiopaque Grade Formulation Expansion | Barium sulfate-loaded PEEK captures Stuttgart spinal interbody fusion cage specifications. |
| PEEK-on-Ceramic Articulation R&D Partnership | Knee and hip bearing trials open orthopedic volume markets beyond traditional spine applications. |
| Recycling Pathway Validation Program | EU Green Deal first-mover positioning prepares for potential medical polymer recycled-content mandates. |
Research Approach
The analysis maps spinal implant, dental prosthetic, surgical instrument, and cardiology device sub-sectors, each validated through biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs leads at compounders. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, polymer master file registries, and customs trade data establish demand-supply calibration. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across application categories.
Consistency checks against external benchmarks validated analytical outputs across the projection horizon. The framework models grade tier, end-use application, sterilization compatibility requirement, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from implant procedure volume trajectories, dental laboratory CAD/CAM adoption curves, and instrument replacement cycle analysis, with fluorobenzophenone feedstock pricing and EU MDR enforcement intensity as key sensitivity inputs.
Underlying assumptions cover stable benzene-fluorine chemical feedstock pricing, sustained EU MDR notified body capacity, and continued PEEK-on-ceramic articulation trial expansion, with deviation risk concentrated in recycled-content mandate timing and Lancashire supply concentration disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
Bilirubin Meters Market
Medical Devices
Human Enhancement Market