
 Global Gauze Swabs Market | 2026-2036
Global Gauze Swabs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gauze Swabs Market Foresight
Skilled textile workers capable of maintaining ISO-certified cleanroom environments is bifurcating competitive capacity between premium and commodity gauze producers. Medline Industries leverages its North American manufacturing footprint to sustain just-in-time hospital contracts. Cardinal Health anchors its position through extensive distribution control across integrated delivery networks. BSN Medical specializes in European woven gauze traditions that differentiate its surgical-grade offerings.
Gauze swabs are absorbent medical textiles, typically composed of woven or non-woven cotton or cotton-blend fibers in ply counts ranging from 4 to 16 layers, manufactured through carding, weaving, or needle-punch processes and sterilized via gamma irradiation or ethylene oxide for clinical use. Their primary purpose is wound exudate management, surgical site preparation, and protective barrier application across acute and chronic care settings. Sterile gauze commands the dominant revenue share in hospital procurement, while non-woven gauze represents the fastest-expanding category due to superior fluid retention and reduced linting in laparoscopic environments. Wound care applications absorb the largest volume flows, though surgical procedures concentrate the highest margin pools through kit bundling and private-label contracts.
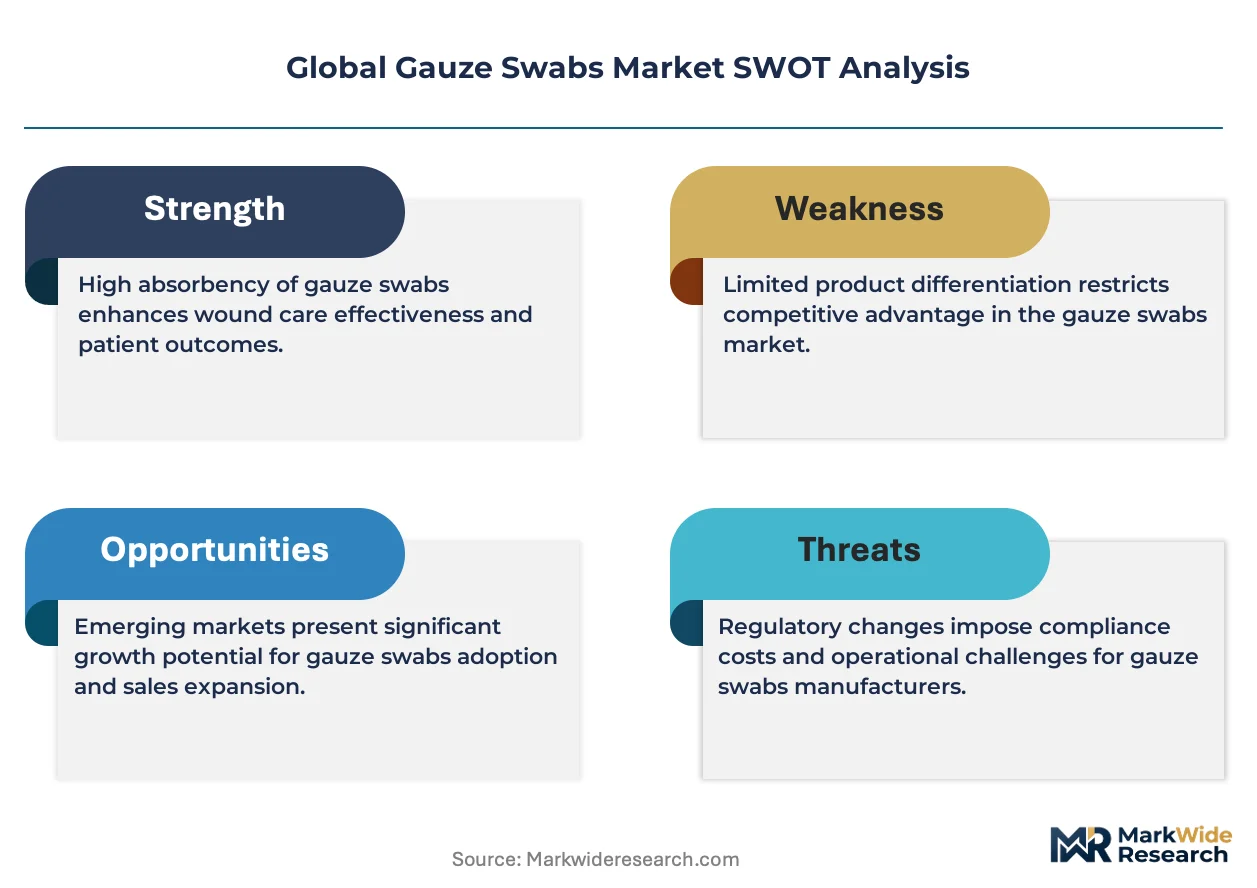
The FDA enforces Quality System Regulation and sterilization validation requirements that elevate barrier costs for new gauze entrants, while the EU MDR imposes strengthened clinical evidence standards on absorbent wound care devices sold in Europe. India's CDSCO aligns with ISO 13485 for domestic medical textile licensing, creating compliance overlap for exporters targeting both regulated and emerging markets. Stakeholders must monitor evolving sterilization modality restrictions, as ethylene oxide phase-down discussions in multiple jurisdictions could force capital-intensive conversion to alternative technologies.
Market Dynamics
Sterilization modality restrictions are bifurcating manufacturer capital allocation between ethylene oxide conversion costs and gamma irradiation infrastructure, forcing gauze producers to absorb compliance investments or cede hospital contracts to certified competitors.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volumes in United States ASCs are accelerating sterile gauze kit consumption through bundled procurement contracts.
- ISO 13485 alignment:India's CDSCO harmonization with international quality management standards is streamlining export pathways for domestic medical textile manufacturers.
- Laparoscopic environment requirements:Reduced-linting non-woven gauze formats are capturing preference in minimally invasive surgical suites.
Market Restraints
- Raw cotton price volatility:Input cost swings in agricultural commodity markets compress margin stability for woven gauze producers dependent on natural fiber supply chains.
- Sterilization technology concentration:Limited commercial gamma irradiation facility availability in emerging markets creates bottleneck risk for sterile product distribution.
- Synthetic dressing substitution:Hydrocolloid and foam wound care alternatives are eroding volume share in chronic wound management applications.
Strategic Opportunities
- India hospital infrastructure buildout:Public and private bed expansion in tier-2 and tier-3 cities is generating localized demand for cost-optimized sterile gauze procurement.
- EU MDR clinical evidence pathways:Strengthened documentation requirements for absorbent wound care devices create first-mover advantage for manufacturers with existing technical files.
- E-commerce direct distribution:Hospital purchasing cooperatives and group purchasing organizations are piloting digital procurement platforms for consumable medical textiles.
Industry Challenges
- Cleanroom textile technician scarcity:ISO-certified manufacturing environments require skilled operators capable of maintaining particulate control standards, limiting production scale-up velocity.
- Ethylene oxide phase-down compliance timelines:Multi-jurisdictional regulatory transitions are forcing simultaneous dual-technology sterilization validation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gauze Swabs Market |
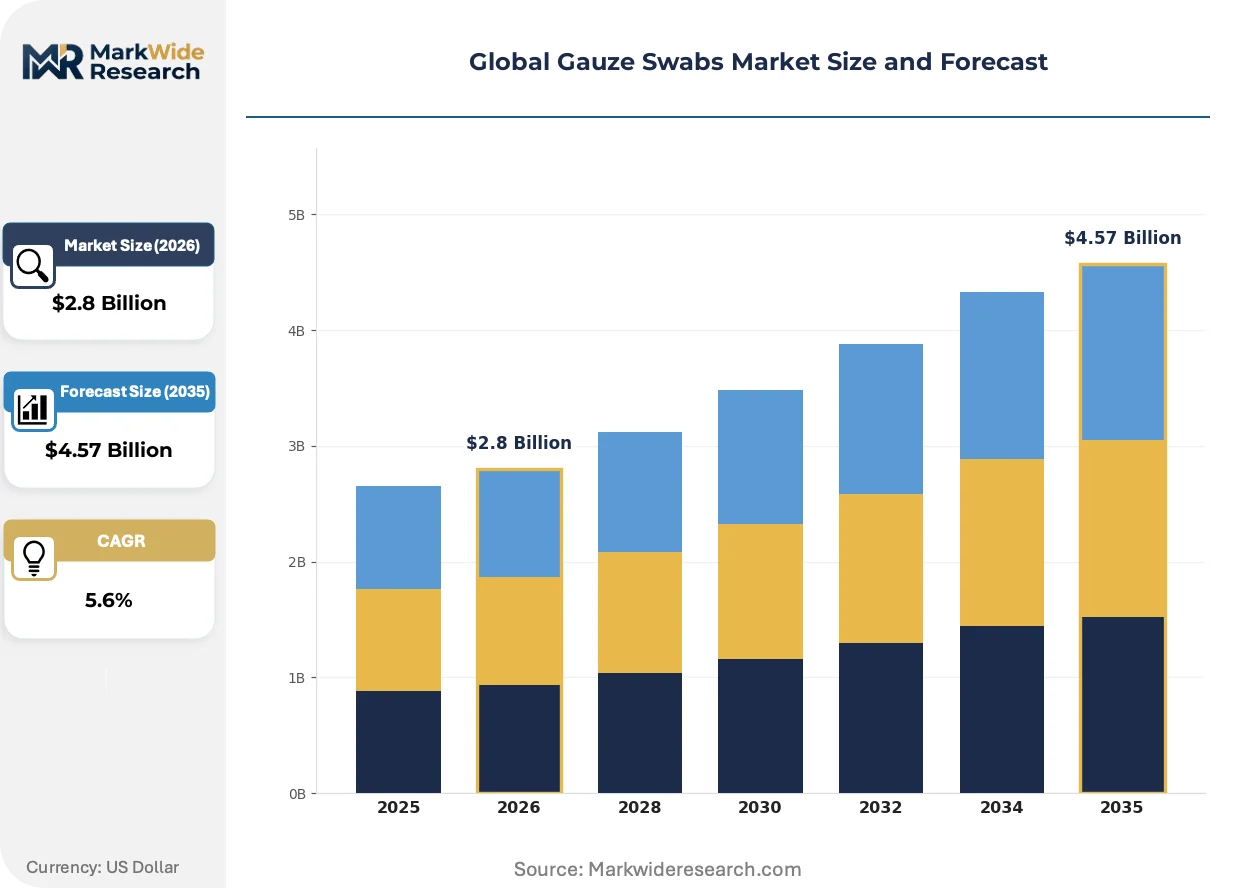
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterile Gauze, Non-Sterile Gauze, Impregnated Gauze, Woven Gauze, Non-Woven Gauze Application: Wound Care, Surgical Procedures, First Aid, Dental Care, Veterinary Use End User: Hospitals, Ambulatory Surgical Centers, Clinics, Emergency Care Units, Home Healthcare Packaging Type: Individual Packets, Bulk Packs, Sterile Pouches, Plastic Containers, Paper Wraps |
| Companies Covered | Medline Industries, BSN Medical, Cardinal Health, Baxter International, Aero Healthcare, 3M, Winner Medical Group, AdvaCare Pharma, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gauze Swabs Market Shifts & Advancements
Material science advances and sterilization technology transitions are compressing traditional competitive advantages in woven gauze manufacturing while elevating barrier requirements for market participation.
Antimicrobial-impregnated gauze substrates containing silver or polyhexamethylene biguanide are displacing standard cotton formats in surgical site infection prevention protocols. Academic medical centers in Germany and the United States are piloting these enhanced textiles in orthopedic and cardiovascular procedures. The shift is compressing commodity gauze margins while creating premium pricing tiers tied to clinical outcome data.
EU MDR strengthened clinical evidence requirements for absorbent wound care devices are extending time-to-market for new gauze product registrations. Manufacturers must now submit biocompatibility testing and performance validation data previously exempt under the Medical Devices Directive. Surgical-grade woven gauze producers with legacy technical documentation are accelerating dossier updates to maintain CE marking continuity.
Hospital value analysis committees are consolidating supplier rosters for standardized consumables, compressing vendor counts from multiple regional distributors to single-source national contracts. Integrated delivery networks in the United States are unbundling gauze from procedure kits to capture direct sourcing savings. The concentration is most visible in multi-hospital systems pursuing supply chain rationalization across affiliated ambulatory and acute care facilities.
Global Gauze Swabs Market Segmentation
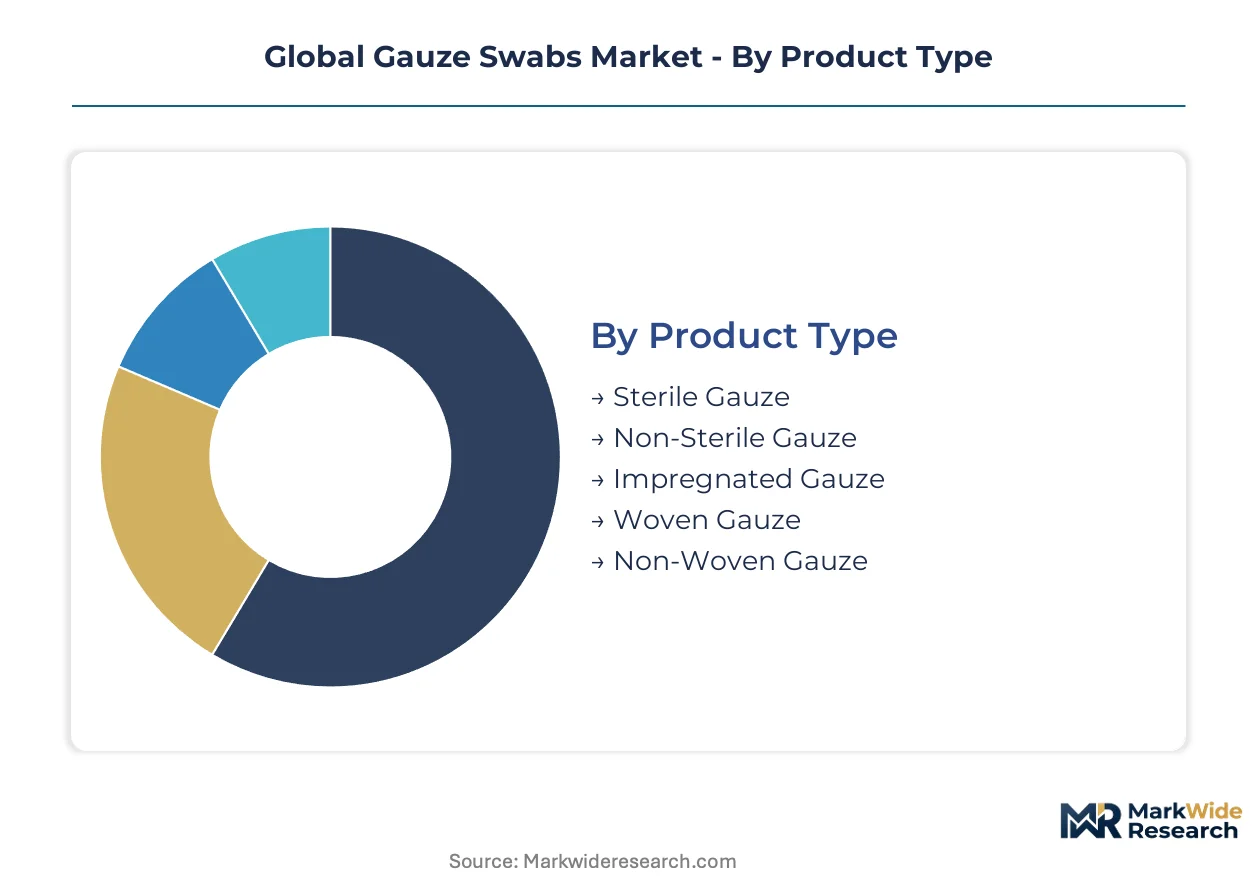
Gauze swabs exhibit distinct demand profiles across product formats and clinical settings. Segmentation reveals how sterilization standards, procedural environments, and procurement channels reshape competitive positioning.
Product Type:
Sterile formats face divergent compliance pathways under FDA Quality System Regulation versus EU MDR clinical evidence requirements.
- Sterile Gauze:Gamma-irradiated or ethylene-oxide-treated formats meeting ISO 11135 and ISO 11137 standards. Hospital procurement in the United States concentrates here due to joint commission infection control mandates.
- Non-Sterile Gauze:Lower-cost formats for non-invasive applications. Demand clusters in India's tier-2 city clinics where CDSCO licensing aligns with cost-optimized public health procurement.
- Impregnated Gauze:Silver or PHMB-embedded substrates for surgical site infection prevention. German academic medical centers pilot these in orthopedic protocols.
- Woven Gauze:Traditional cotton constructions with 12-16 ply counts. European manufacturers leverage heritage textile capabilities for surgical-grade certification.
- Non-Woven Gauze:Needle-punched synthetic blends with superior fluid retention. Laparoscopic suites in Japan's metropolitan hospitals drive preference for reduced-linting performance.
Sterile Gauze handles the majority of throughput; Non-Woven Gauze is the fastest mover on share.
Application:
Margin structures vary sharply between acute intervention and chronic management settings.
- Wound Care:Chronic exudate management absorbs volume flows across home healthcare and long-term care facilities. Hydrocolloid substitution pressures commodity gauze margins here.
- Surgical Procedures:Highest margin pool through kit bundling and private-label contracts. ASC expansion in the United States accelerates sterile format consumption.
- First Aid:Consumer and occupational health segments. Retail pharmacy chains in Brazil stock bulk formats under ANVISA registration requirements.
- Dental Care:Hemostatic and moisture control in oral surgery. South Korean dental clinics specify non-woven formats under MFDS device classification.
- Veterinary Use:Companion animal and livestock applications. Australia's TGA-aligned veterinary supply chains source cost-optimized woven grades.
Surgical Procedures commands premium pricing; Wound Care expands most quickly in absolute volume terms.
End User:
Procurement authority concentration determines supplier access and contract structure.
- Hospitals:Integrated delivery networks consolidate vendor rosters. Value analysis committees in United States multi-hospital systems unbundle gauze from procedure kits.
- Ambulatory Surgical Centers:Bundled procurement contracts accelerate sterile kit consumption. Outpatient volume growth in Germany's Kliniken drives format standardization.
- Clinics:Dispersed purchasing across independent practices. India's CDSCO streamlined licensing supports domestic manufacturer penetration here.
- Emergency Care Units:Rapid-turn inventory requirements favor pre-sterilized individual packets. Japan's pre-hospital care protocols specify gamma-irradiated formats.
- Home Healthcare:Direct-to-patient distribution channels. E-commerce platforms pilot digital procurement for consumable medical textiles.
Hospitals anchor revenue concentration; Ambulatory Surgical Centers are gaining share fastest.
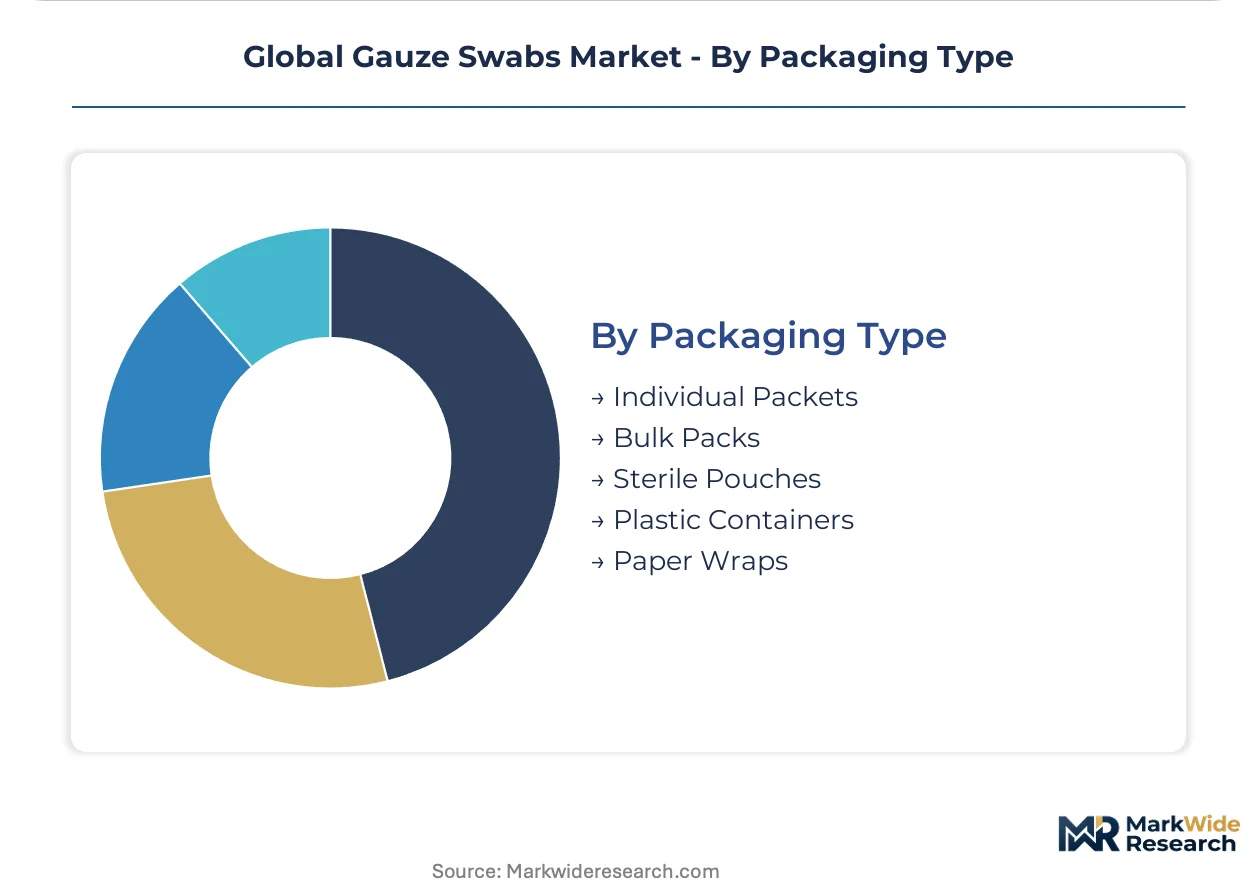
Packaging Type:
Packaging configuration directly ties to sterilization modality and point-of-use workflow efficiency.
- Individual Packets:Single-use sterile units for operating room environments. FDA-validated ethylene oxide or gamma irradiation barrier integrity is mandatory.
- Bulk Packs:Cost-optimized formats for high-volume clinical settings. India's hospital infrastructure buildout in tier-3 cities sources these for ward-level inventory.
- Sterile Pouches:Peel-open designs for aseptic technique compliance. EU MDR technical documentation requirements extend time-to-market for new pouch configurations.
- Plastic Containers:Reclosable systems for multi-use clinical environments. German dental practices specify these for moisture-resistant storage.
- Paper Wraps:Sustainable packaging alternatives under environmental procurement policies. Australia's healthcare sector pilots these under TGA sterilization validation guidance.
Bulk Packs handles the majority of throughput; Sterile Pouches is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns in Germany favor woven surgical-grade formats, while India's cost-optimized public health systems drive bulk non-sterile consumption. Japan's metropolitan surgical suites demand reduced-linting non-woven specifications distinct from commodity markets.
United States
Ambulatory surgical center expansion accelerates sterile gauze kit consumption through bundled procurement contracts. FDA Quality System Regulation enforces sterilization validation requirements that elevate compliance costs for new entrants. Greater Boston's academic medical centers pilot antimicrobial-impregnated gauze substrates in orthopedic infection prevention protocols.
Germany
Kliniken outpatient volume growth drives format standardization across integrated delivery networks. EU MDR strengthened clinical evidence requirements extend time-to-market for new absorbent wound care device registrations. Bavaria's textile manufacturing clusters leverage heritage woven gauze capabilities for surgical-grade certification.
India
Public and private bed expansion in tier-2 and tier-3 cities generates localized demand for cost-optimized sterile gauze procurement. CDSCO harmonization with ISO 13485 quality management standards streamlines export pathways for domestic medical textile manufacturers. Gujarat's industrial corridors concentrate spinning and weaving capacity serving both regulated and emerging markets.
Japan
Metropolitan hospital laparoscopic suites specify reduced-linting non-woven gauze formats for minimally invasive environments. PMDA device classification frameworks govern moisture control textile approvals in dental and surgical applications. Osaka's medical supply distribution networks channel gamma-irradiated sterile packets to pre-hospital care protocols.
Australia
TGA-aligned veterinary supply chains source cost-optimized woven grades for companion animal and livestock applications. Healthcare sector procurement pilots sustainable paper wrap packaging alternatives under sterilization validation guidance. New South Wales hospital infrastructure expansion absorbs bulk pack formats for ward-level inventory management.
Global Gauze Swabs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in gauze swab supply. Hospital purchasing cooperatives and group purchasing organizations consolidate vendor rosters from multiple regional distributors toward single-source national contracts. Three archetypes dominate: North American just-in-time contract holders, European heritage textile specialists, and Asian cost-optimized scale producers. Competitive moves concentrate on M&A for distribution control and dual-technology sterilization validation investments.
Among North American integrated distributors, Medline Industries and Cardinal Health anchor the contract-holding tier through extensive hospital network relationships. BSN Medical exemplifies the European heritage specialist archetype, occupying a position tied to woven gauze traditions and surgical-grade certification capabilities. Winner Medical Group represents the Asian scale-oriented segment, sitting within cost-optimized production structures serving emerging market expansion.
| Leading Market Players |
|---|
| Medline Industries |
| BSN Medical |
| Cardinal Health |
| Baxter International |
| Aero Healthcare |
| 3M |
| Winner Medical Group |
| AdvaCare Pharma |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
FDA Quality System Regulation and EU MDR sterilization validation requirements gate both supplier qualification and price differentiation simultaneously, compressing commodity margins while elevating premium tiers for certified manufacturers. Contract structures bifurcate between long-term hospital system agreements and spot procurement for emerging market clinics, with sterilization modality investments acting as the primary price floor determinant.
Pricing Analysis
Long-term offtake contracts dominate hospital integrated delivery networks, locking in volume commitments against sterilization-capacity guarantees. Three-tier pricing structure across premium, standard, and economy levels separates gamma-irradiated surgical grades from ethylene-oxide hospital formats and non-sterile clinic bulk packs. Pricing pressure stems from synthetic dressing substitution in chronic wound management, eroding volume share at the economy tier. Ambulatory surgical centers exhibit least price sensitivity due to bundled kit procurement, while India's tier-3 public health clinics anchor the most cost-optimized demand segment.
Supply Chain Analysis
Just-in-time inventory strategies prevail in United States hospital networks, while strategic stockpiling characterizes Indian and Brazilian procurement for supply security. Manufacturing concentrates in India, Germany, and the United States, with Gujarat's textile corridors feeding both regulated and emerging markets. Raw cotton draws from agricultural commodity exchanges, gamma irradiation capacity rests on limited commercial facility networks, and ethylene oxide feedstock hinges on petrochemical supply chains. Single-source vulnerability in sterilization infrastructure creates bottleneck risk. Distribution runs through integrated delivery networks and group purchasing organizations in developed markets, with regional distributors anchoring emerging market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global gauze swabs sit in early-cycle expansion as ambulatory surgical center buildout accelerates sterile format penetration beyond traditional hospital settings. India's hospital infrastructure expansion and antimicrobial-impregnated substrate adoption represent dual tailwinds reshaping competitive positioning.
For Market Incumbents: Secure dual-technology sterilization validation investments ahead of ethylene oxide phase-down timelines to defend hospital contract renewals. Deepen backward integration into gamma irradiation partnerships or captive capacity to control supply security. Anchor position through GPO contract consolidation as value analysis committees compress vendor rosters from regional distributors to single-source national agreements. For New Entrants and Emerging Players: Differentiate on antimicrobial-impregnated substrates for surgical site infection prevention, targeting German and United States academic medical center pilot programs. Penetrate India's tier-2 and tier-3 city hospital buildout with CDSCO-aligned cost-optimized sterile formats. Pursue direct e-commerce distribution to hospital purchasing cooperatives as digital procurement platforms displace traditional distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European heritage textile specialists possessing legacy woven gauze technical documentation for EU MDR dossier updates. Five-to-ten year viability favors manufacturers with dual-sterilization certification and established GPO contract relationships. Monitor ethylene oxide regulatory phase-down acceleration as the primary inflection signal for sterilization technology conversion capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Sterilization Technology Validation | Gamma irradiation and ethylene oxide certification secures hospital contract continuity across regulatory transition timelines. |
| Antimicrobial Substrate Development | Silver and PHMB-impregnated gauze captures premium pricing tiers in orthopedic and cardiovascular surgical protocols. |
| India Manufacturing Scale-Up | Gujarat textile corridor expansion serves tier-2 and tier-3 city hospital infrastructure buildout with cost-optimized sterile formats. |
| GPO Contract Consolidation | Single-source national agreements with integrated delivery networks compress regional distributor intermediaries. |
| EU MDR Technical File Acceleration | Legacy documentation updates maintain CE marking continuity for absorbent wound care device registrations. |
Research Methodology
Cross-validation between hospital procurement database analysis and sterilization facility capacity audits anchors the qualitative findings. Primary interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee members, and CDSCO regulatory affairs leads combine with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital supply chain disclosures, and customs trade records. Bottom-up gauze format consumption modeling and top-down medical textile market sizing triangulate volume estimates.
Sensitivity analysis across sterilization modality conversion timelines and raw cotton price volatility bands stress-tests projection robustness. Segmentation dimensions span sterile versus non-sterile formats, woven versus non-woven constructions, wound care versus surgical application settings, and hospital versus ambulatory end-user channels. CAGRs derive from procedure volume growth correlations and kit bundling penetration curves across the analysis window. Antimicrobial substrate adoption rates and India hospital bed expansion trajectories feed scenario-weighted outputs.
Material uncertainties — ethylene oxide regulatory phase-down acceleration, synthetic dressing substitution velocity, and cleanroom textile technician availability — sit outside the modeled envelope. Forecasts reflect assumptions about sterilization technology transition costs and hospital procurement consolidation trajectories. Revision becomes warranted when antimicrobial substrate clinical outcome data crosses threshold adoption rates in academic medical center protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Surgical Snare Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Italy General Surgical Devices Market