
 Disposable Laparoscopic Instruments Market | 2026-2036
Disposable Laparoscopic Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Laparoscopic Instruments Market Analysis
Modular procedure kits bundling graspers, scissors, and trocars into single-use configurations is repositioning hospital procurement toward disposable ecosystems over standalone reusable instrument contracts. Medtronic leverages its integrated surgical platform to anchor bundled contracts across integrated delivery networks. Ethicon differentiates through polymer-based jaw technologies that compete with traditional stainless steel reusable alternatives. B. Braun Melsungen specializes in electrosurgical disposables that dominate European hospital tenders.
Disposable laparoscopic instruments are single-use surgical tools manufactured from medical-grade polymers and stainless steel alloys, designed for insertion through trocar ports to manipulate tissue during minimally invasive abdominal procedures. These devices incorporate insulated handles, articulating jaws, and ratchet-locking mechanisms to enable precise grasping, cutting, and coagulation while eliminating sterilization cycles between cases. Scissors and graspers lead procedure volume due to their ubiquity across cholecystectomy and appendectomy workflows, though robotic-assisted technology segments command premium positioning as hospital systems adopt da Vinci-compatible disposable attachments. Electrosurgical instruments sustain higher margin pools than manual alternatives because RF-energy integration requires specialized insulation and tip metallurgy that commands differentiated pricing.
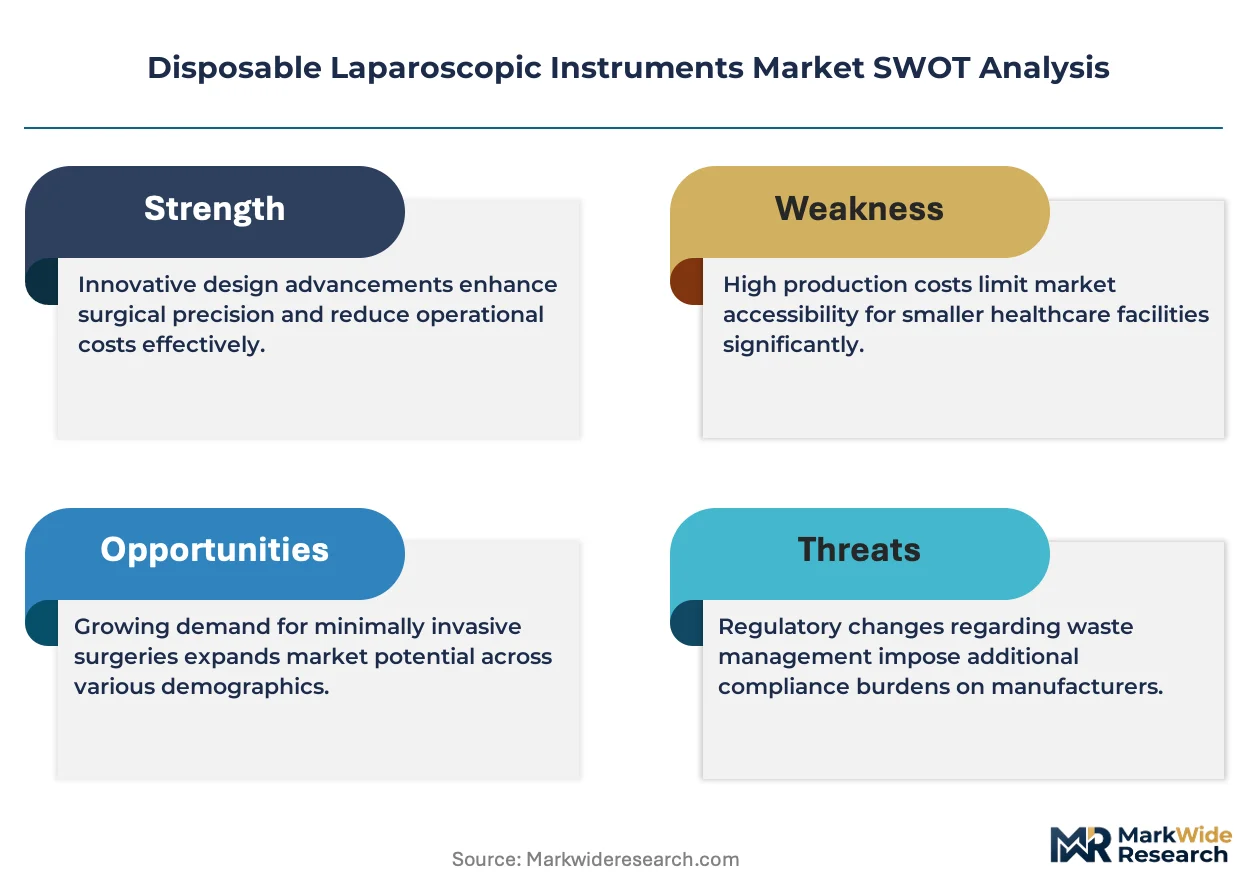
FDA 510(k) clearance pathways and EU MDR Class IIa device requirements shape product development timelines and clinical validation burdens for disposable laparoscopic instrument manufacturers. ISO 13485 quality management standards and REACH polymer compliance obligations further constrain material selection and supplier qualification processes across the value chain. Stakeholders must monitor how FDA guidance on reprocessed single-use device enforcement evolves relative to original disposable manufacturer claims, as this regulatory tension will determine competitive positioning between pure-disposable and reprocessing-service business models.
Market Dynamics
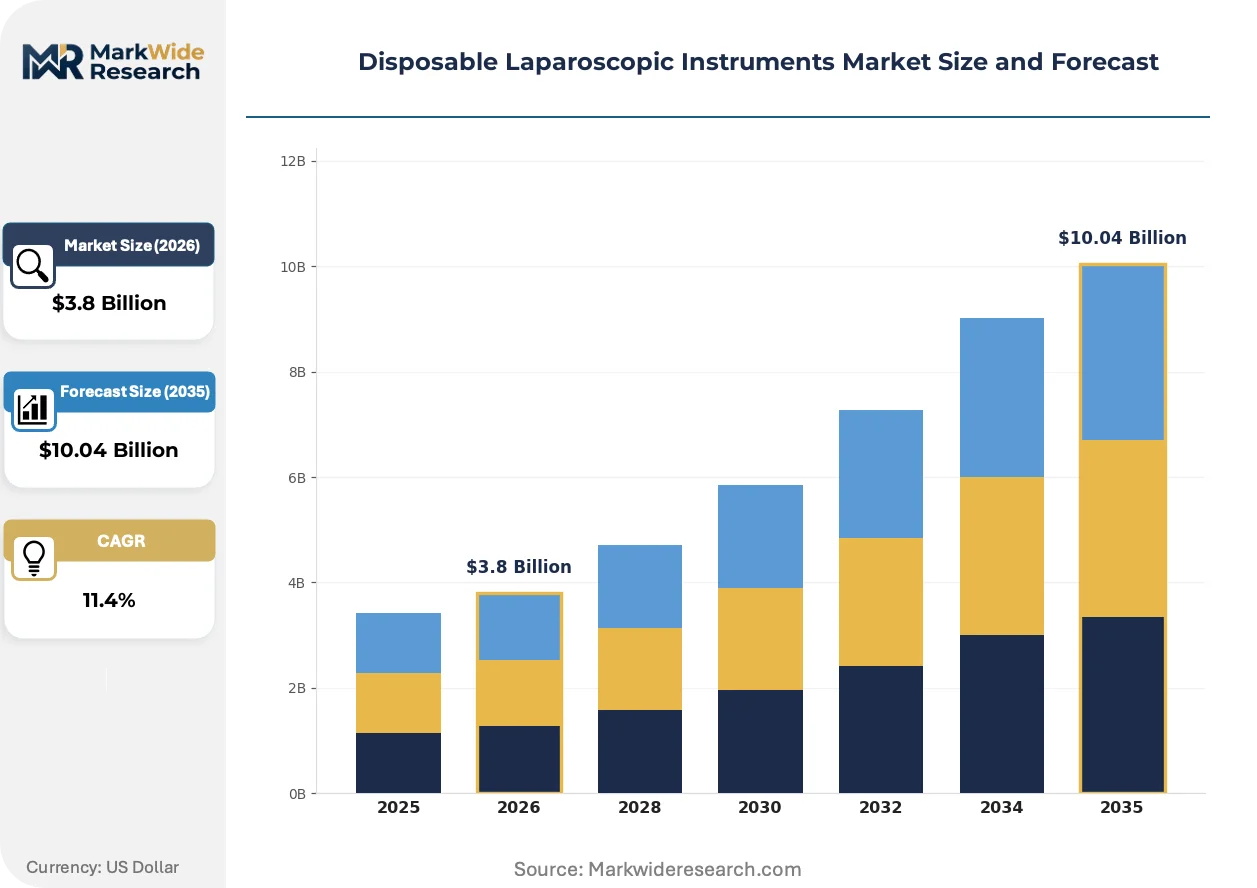
Modular single-use procedure kits are compressing hospital procurement cycles and displacing standalone reusable instrument contracts across integrated delivery networks. This kit-centric purchasing model restructures supplier relationships toward bundled ecosystem vendors.
Growth Catalysts
- EU MDR sterilization validation:The EU MDR's enhanced clinical evidence requirements for reusable device reprocessing are accelerating hospital transitions toward pre-sterilized disposable formats that bypass validation burdens entirely.
- Ambulatory surgical center expansion:ASCs in the United States are procuring single-use laparoscopic sets to eliminate cross-contamination risk and same-day turnover sterilization bottlenecks.
- Polymer metallurgy advances:Medical-grade polymer jaw technologies now achieve tensile parity with stainless steel alternatives, enabling functional equivalence without reprocessing infrastructure.
Market Restraints
- Medical-grade resin cost volatility:Specialized polymer feedstocks for insulated handles and jaw housings face petrochemical price swings that compress manufacturer margin pools.
- Electrosurgical tip supply concentration:RF-energy conductive metallurgy for cautery instruments depends on a narrow supplier base concentrated in German precision metalworking clusters.
- FDA reprocessed SUD enforcement ambiguity:Uncertainty around FDA guidance on single-use device reprocessing creates pricing tension between pure-disposable and third-party reprocessing service models.
Strategic Opportunities
- Japan's aging surgical workforce:Demographic pressure on Japanese operating room staff is creating demand for pre-configured disposable kits that reduce instrument assembly time and training requirements.
- Robotic-assisted surgery convergence:da Vinci-compatible disposable attachments represent unpenetrated white space as hospital systems expand robotic program volumes.
- IRA domestic manufacturing incentives:United States hospital procurement is tilting toward domestically manufactured disposables eligible for federal healthcare facility preference programs.
Industry Challenges
- ISO 13485 auditor capacity constraints:Quality management system certification backlogs are extending product launch timelines for manufacturers seeking European market access.
- REACH polymer compliance complexity:Substance of very high concern screening for medical-grade polymers requires specialized regulatory affairs talent that commands premium compensation.
- Legacy sterilization infrastructure stranded assets:Hospitals with recent capital investment in reusable instrument reprocessing suites face internal resistance to full disposable conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Laparoscopic Instruments Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissors, Forceps, Graspers, Needle Holders End User: Hospitals, Surgical Centers, Clinics, Research Facilities Technology: Electrosurgical, Robotic-assisted, Manual, Hybrid Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Wholesalers |
| Companies Covered | Medtronic, Ethicon (Johnson & Johnson), B. Braun Melsungen, Stryker Corporation, Karl Storz SE & Co. KG, Olympus Corporation, ConMed, Teleflex, Péters Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Laparoscopic Instruments Market Emerging Trajectories
Smart instrument connectivity and polymer metallurgy convergence are redefining performance benchmarks for single-use laparoscopic tools. These developments compress the functional gap with reusable alternatives while embedding traceability and workflow optimization.
Articulating polymer jaw mechanisms with embedded force-feedback sensors are integrating haptic data transmission into disposable graspers and scissors. Academic medical centers in Germany and the United States are piloting these instruments to reduce tissue trauma rates during cholecystectomy procedures. The technology is integrating real-time pressure telemetry that was previously exclusive to capital-intensive reusable robotic platforms.
EU MDR Class IIa device requirements are mandating expanded clinical evidence packages for electrosurgical disposables with active energy delivery. Manufacturers must now submit post-market surveillance data and biocompatibility testing that exceeds previous Medical Device Directive thresholds. European hospital tenders are increasingly specifying MDR-certified instruments exclusively, filtering out legacy product registrations.
Subscription-based instrument provisioning is replacing capital purchase models for high-volume ASC networks. Third-party logistics providers are warehousing sterile disposable sets and replenishing inventory based on procedure scheduling data. This pattern is most visible in United States multi-site surgical groups where working capital constraints favor operational expenditure structures over instrument ownership.
Disposable Laparoscopic Instruments Market Segmentation
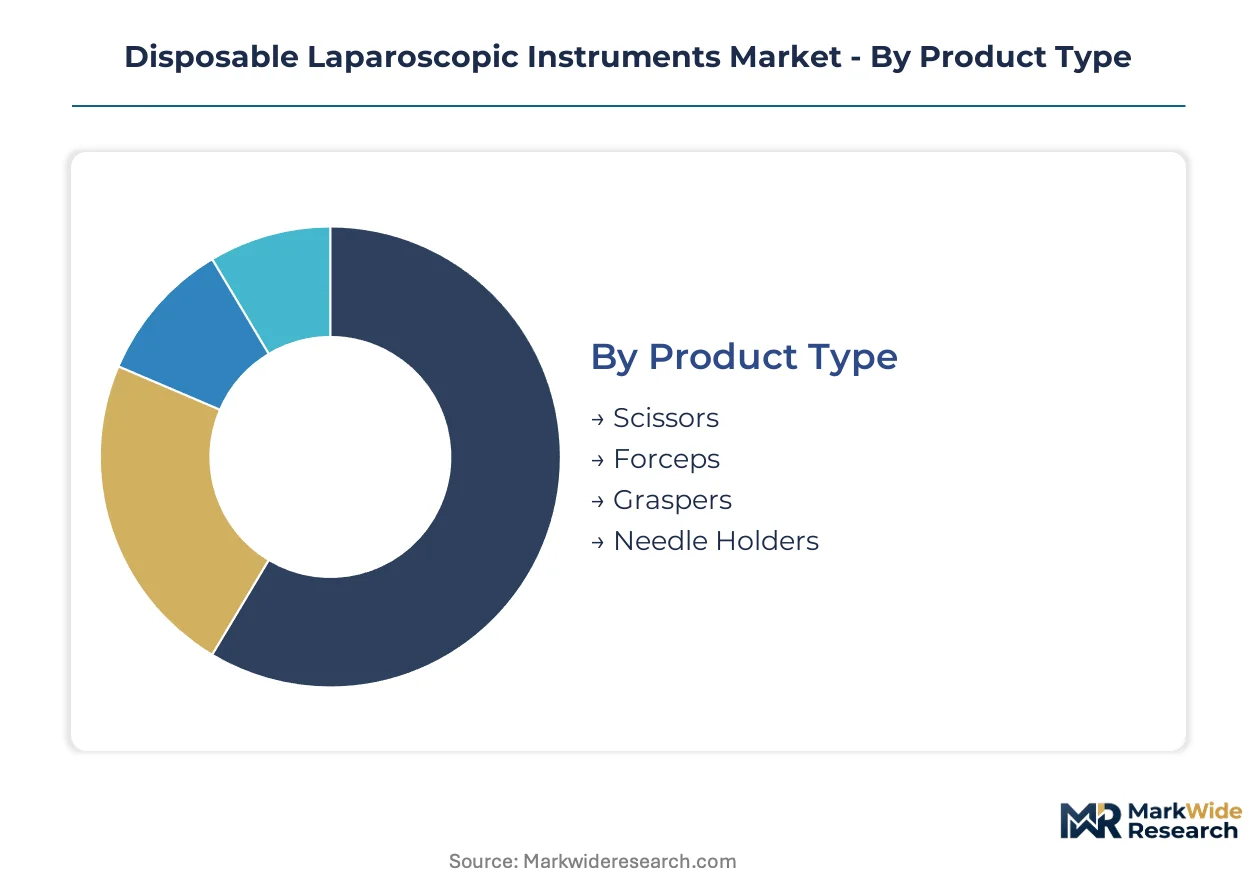
Disposable laparoscopic instruments fragment across four structural dimensions that determine procurement economics and margin architecture. Each segmentation layer reveals distinct capital requirements, regulatory burdens, and customer concentration patterns that shape vendor positioning strategies.
Product Type:
Graspers and scissors demand the heaviest upfront tooling investment for polymer jaw metallurgy and articulation mechanisms, while needle holders require precision machining infrastructure for suture security features.
- Scissors:Single-use shears incorporate high-carbon stainless steel cutting edges laminated onto polymer handles with insulated RF-safety coatings. Demand clusters in United States ambulatory surgical centers performing high-volume cholecystectomy workflows where same-day sterilization capacity is constrained.
- Forceps:Tissue manipulation forceps utilize medical-grade polypropylene housings with titanium-alloy tip inserts for thermal conductivity control. German hospital tenders specify these instruments for appendectomy procedures where reusable forceps reprocessing validation costs exceed disposable unit economics.
- Graspers:Ratchet-lock graspers dominate trocar-port insertion volumes across manual laparoscopic suites.
- Needle Holders:Suture-driving instruments with diamond-dust jaw patterns serve specialized gynecologic and urologic procedures.
Scissors absorb the bulk of installed capacity; robotic-compatible graspers are expanding most quickly.
End User:
Customer type determines contract structure, with hospitals demanding bundled ecosystem pricing and surgical centers prioritizing working capital flexibility through subscription provisioning.
- Hospitals:Integrated delivery networks negotiate multi-year disposable instrument contracts tied to electronic health record procurement platforms. United States health systems with recent sterilization infrastructure investments face internal capital-stranding resistance to full disposable conversion.
- Surgical Centers:Freestanding ASCs procure pre-configured single-use kits through third-party logistics providers eliminating on-site sterilization suites. Japanese multi-site surgical groups favor operational expenditure models that reduce instrument assembly training burdens for aging nursing staff.
- Clinics:Office-based procedure rooms purchase low-volume disposable sets through medical distributor networks.
- Research Facilities:Academic medical centers pilot smart instrument connectivity with embedded force-feedback sensors for tissue trauma reduction studies.
Hospitals command the deepest contract penetration; surgical centers are gaining share fastest.
Technology:
Energy integration intensity separates margin tiers, with electrosurgical platforms requiring specialized RF-insulation engineering and robotic attachments demanding da Vinci interface certification.
- Electrosurgical:RF-energy instruments with active electrode monitoring and ceramic insulation layers sustain premium pricing pools. EU MDR Class IIa device requirements mandate expanded clinical evidence packages for active energy delivery systems that exceed prior Medical Device Directive thresholds.
- Robotic-assisted:da Vinci-compatible disposable attachments represent unpenetrated white space as hospital systems expand robotic program volumes. German precision metalworking clusters supply concentrated RF-conductive metallurgy for cautery instrument tips.
- Manual:Non-powered graspers and scissors serve cost-sensitive procurement segments.
- Hybrid:Instruments combining mechanical and limited electrosurgical functionality target mid-tier hospital tenders.
Electrosurgical platforms capture the highest margin concentration; robotic-assisted configurations are climbing the fastest.
Distribution Channel:
Channel selection reflects customer scale and geographic concentration, with direct sales anchoring integrated delivery network relationships and distributors serving fragmented clinic markets.
- Direct Sales:Manufacturer field organizations negotiate bundled contracts across United States integrated delivery networks. Medtronic leverages its integrated surgical platform to anchor ecosystem procurement commitments through dedicated account teams.
- Medical Distributors:Regional wholesalers warehouse sterile inventory for same-day replenishment of high-volume surgical centers. B. Braun Melsungen dominates European hospital tenders through distributor relationships with electrosurgical disposable specialization.
- Online Retail:E-procurement platforms serve low-volume clinic customers with standardized SKU catalogs.
- Wholesalers:Bulk purchasing intermediaries aggregate demand from independent surgical practices.
Direct sales secure the largest contract values; medical distributors are broadening geographic coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of disposable laparoscopic instruments concentrates in German precision metalworking clusters and United States polymer processing hubs, while consumption gravitates toward health systems with the highest minimally invasive surgery volumes in the United States, Germany, and Japan.
United States
Ambulatory surgical centers in Florida, Texas, and Arizona are expanding procurement of single-use laparoscopic sets to eliminate same-day turnover sterilization bottlenecks. FDA 510(k) clearance pathways shape product development timelines for manufacturers seeking market access. Boston and Minneapolis medical device clusters anchor domestic production of polymer-based jaw technologies.
Germany
Hospital tenders in Bavaria and North Rhine-Westphalia increasingly specify EU MDR Class IIa-certified electrosurgical disposables exclusively. REACH polymer compliance obligations constrain material selection for insulated handle manufacturers. Tuttlingen precision metalworking clusters supply concentrated RF-conductive metallurgy for cautery instrument tips serving European hospital networks.
Japan
Demographic pressure on aging operating room staff in Tokyo and Osaka is creating demand for pre-configured disposable kits that reduce instrument assembly time. PMDA regulatory frameworks govern medical device market authorization timelines. Nagoya medical device manufacturers are piloting smart instrument connectivity with embedded force-feedback sensors for tissue trauma reduction studies.
United Kingdom
NHS procurement frameworks are tilting toward bundled disposable instrument contracts that compress standalone reusable instrument agreements. MHRA post-Brexit regulatory alignment with EU MDR requirements extends clinical validation burdens for manufacturers. London and Cambridge academic medical centers are evaluating subscription-based instrument provisioning models for high-volume surgical groups.
China
NMPA medical device registration requirements are extending product launch timelines for foreign manufacturers seeking domestic market access. Yangtze River Delta manufacturing hubs are expanding polymer processing capacity for insulated handle production. Shanghai and Suzhou health systems are adopting single-use laparoscopic sets to reduce cross-contamination risk in high-volume abdominal surgery workflows.
Disposable Laparoscopic Instruments Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated integrated delivery network contracts favor ecosystem vendors with bundled surgical platform offerings, while fragmented ambulatory surgical center procurement enables mid-tier specialists to capture share through distributor relationships. Three archetypes dominate: diversified surgical platform conglomerates, electrosurgical disposable specialists, and robotic-compatible attachment innovators. Competitive moves center on strategic partnerships with third-party logistics providers and portfolio diversification into smart instrument connectivity.
Within the diversified conglomerate tier, Medtronic and Ethicon exemplify ecosystem anchoring strategies through integrated surgical platform bundling. Among European electrosurgical specialists, B. Braun Melsungen occupies a position exemplifying distributor-dominated hospital tender capture. These three entities represent the archetype spectrum from capital-intensive platform integration to focused disposable specialization.
| Leading Market Players |
|---|
| Medtronic |
| Ethicon (Johnson & Johnson) |
| B. Braun Melsungen |
| Stryker Corporation |
| Karl Storz SE & Co. KG |
| Olympus Corporation |
| ConMed |
| Teleflex |
| Péters Surgical |
| Others |
Supply Flow & Price Mechanics
Electrosurgical-manual instrument bifurcation creates distinct margin architectures that propagate differently through procurement channels. Premium RF-energy platforms command differentiated pricing anchored in German precision metallurgy and specialized ceramic insulation engineering, while commodity polymer graspers face compression from resin cost volatility and ASC volume contracting.
Pricing Analysis
Margin tightening in electrosurgical tiers reflects ceramic insulation feedstock concentration and EU MDR Class IIa certification burdens that filter out legacy competitors. Three-tier pricing structure across premium electrosurgical, standard manual, and economy polymer-only levels stratifies hospital procurement, with integrated delivery networks least sensitive due to bundled ecosystem contracts and freestanding ASCs most responsive to per-unit differentials. Cost-down pressure on manual instruments accelerates because medical-grade polypropylene faces petrochemical price swings that manufacturers cannot fully pass through.
Supply Chain Analysis
Single-source vulnerability sits with German Tuttlingen precision metalworking clusters supplying RF-conductive metallurgy for cautery tips. Manufacturing draws from United States polymer processing hubs for insulated handles, German metalworking centers for electrosurgical components, and Chinese Yangtze River Delta facilities for commodity polymer housings. Tariff exposure on Chinese polymer imports threatens margin stability for mid-tier manufacturers. Distribution runs through third-party logistics providers warehousing sterile inventory for same-day ASC replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer metallurgy R&D capacity constraints prop pricing power for manufacturers with captive materials science capabilities, as medical-grade jaw engineering talent pools remain shallow relative to demand expansion.
For Market Incumbents: To counter third-party reprocessing service encroachment, anchor hospital contracts through integrated surgical platform bundling that embeds disposable instrument provisioning within electronic health record procurement workflows. Deepen backward integration into medical-grade polymer compounding to insulate margin pools from petrochemical volatility. For New Entrants and Emerging Players: Distributor partnerships with regional ASC logistics providers offer the most penetrable channel wedge, as multi-site surgical groups favor operational expenditure models over capital instrument ownership. Target da Vinci-compatible disposable attachments where hospital robotic program expansion outpaces incumbent certification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with electrosurgical disposable specialists given EU MDR Class IIa certification barriers that consolidate tender capture among validated manufacturers. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Watch FDA reprocessed SUD enforcement clarity as the inflection signal determining competitive positioning between pure-disposable and reprocessing-service models.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Investment | Filters hospital tenders toward validated manufacturers with expanded clinical evidence packages. |
| Polymer Metallurgy R&D Partnership | Enables functional parity with stainless steel alternatives without reprocessing infrastructure. |
| Third-Party Logistics Integration | Captures ASC procurement through subscription-based sterile inventory replenishment models. |
| Robotic-Compatible Attachment Development | Accesses unpenetrated white space as da Vinci program volumes expand in hospital systems. |
| Domestic Manufacturing Footprint | Qualifies for United States federal healthcare facility preference programs under IRA incentives. |
Methodological Framework
Independent corroboration across hospital purchasing committee interviews, biomedical engineer consultations, and GPO contracts manager discussions underwrites the qualitative findings. Primary fieldwork engaged sterilization department heads, ambulatory surgical center administrators, and regulatory affairs specialists at polymer processing manufacturers. Secondary validation drew from FDA 510(k) filing databases, EU MDR notified body certification registries, hospital procurement contract repositories, and CMS Medicare utilization statistics. Bottom-up instrument volume modeling and top-down healthcare expenditure triangulation anchored market size estimation.
Comparable-period anchoring to historical minimally invasive surgery volume trends established the forecast baseline across the projection horizon. Segmentation modeling dissected product type, end user archetype, energy integration technology, and distribution channel dimensions. CAGRs derived from procedure volume elasticity to demographic surgical demand, regulatory transition timelines, and capital equipment replacement cycles. Electrosurgical penetration rates and robotic-assisted surgery adoption curves served as primary forecast inputs.
Caveats apply where FDA reprocessed SUD enforcement shifts or EU MDR auditor capacity constraints could materially shift the outlook. Forecasts reflect assumptions regarding sterilization infrastructure retirement timelines and polymer feedstock price normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Equine Surgical Equipment Market
Surgical Instruments
Global Hysteroscopy Instruments Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Operating Room Smoke Aspirators Market