
 Surgical Dental Loupes and Camera Market | 2026-2036
Surgical Dental Loupes and Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Dental Loupes and Camera Market Outlook
Academic dental surgery is hardening as the dominant procurement channel for premium loupes and camera systems. Carl Zeiss Meditec AG leverages its optical heritage to dominate high-end surgical microscopy in university hospital settings. Designs for Vision, Inc. anchors its position through specialized ergonomic configurations for extended operative procedures. SurgiTel competes aggressively on customizable working-distance options that reduce clinician neck strain.
Surgical dental loupes and cameras comprise magnification optics paired with integrated illumination and digital capture modules, typically offering 2.5x to 6.0x magnification with LED or fiber-optic light delivery for real-time procedural documentation. Flip-up loupes retain the largest installed base among practicing dentists due to their versatility between magnified and unmagnified vision. Wireless connectivity is displacing tethered camera systems in oral surgery applications, while digital imaging now captures margin pools previously held by analog documentation equipment. LED lights sustain technology leadership across all end-user tiers given their color-rendering fidelity and thermal efficiency.
The FDA's 510(k) framework governs device clearance, while ISO 13485 quality management standards constrain manufacturing scale-up for new entrants. CE marking under the EU MDR extends compliance burdens for European market access, particularly for digital imaging subsystems. Stakeholders must monitor evolving cybersecurity guidance for wireless-enabled surgical cameras as connectivity becomes standard rather than optional.
Market Dynamics
Wireless-enabled surgical cameras are consolidating market share from tethered documentation systems as ambulatory surgical centers prioritize intraoperative mobility and reduced cable contamination risks.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's Class II medical device clearance framework accelerates product entry timelines for LED-illuminated loupes with integrated digital capture modules.
- Ambulatory surgical center infrastructure upgrades:United States outpatient facilities are replacing aging operative microscopy equipment with high-magnification visualization systems.
- Academic medical center procurement expansion:Dental surgery departments in university hospital settings are hardening as the dominant channel for premium loupes and camera systems.
Market Restraints
- ISO 13485 compliance burden:Quality management certification requirements constrain manufacturing scale-up for new entrants seeking to enter the surgical visualization device market.
- EU MDR CE marking complexity:Extended conformity assessment timelines for digital imaging subsystems delay European market access for wireless camera manufacturers.
- Optical component supply concentration:Precision lens manufacturing clusters in Germany and Japan create geographic concentration risk for high-magnification loupe producers.
Strategic Opportunities
- Underpenetrated Latin American markets:Brazil's ANVISA regulatory framework presents whitespace for ergonomic flip-up loupes in private dental clinic chains.
- Cybersecurity guidance tailwinds:Evolving FDA guidance on wireless-enabled medical devices creates compliance-driven preference shifts toward hardened camera systems.
- Convergence of AR visualization with traditional optics:Augmented reality overlay technology paired with standard loupes opens new procedural documentation workflows in oral surgery.
Industry Challenges
- Specialized optical engineering talent scarcity:Precision lens design expertise required for 4.0x to 6.0x magnification systems remains concentrated among legacy optics firms.
- Legacy analog documentation integration friction:Dental practices with existing film-based record systems face capital-intensive transitions to fully digital imaging workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Dental Loupes and Camera Market |
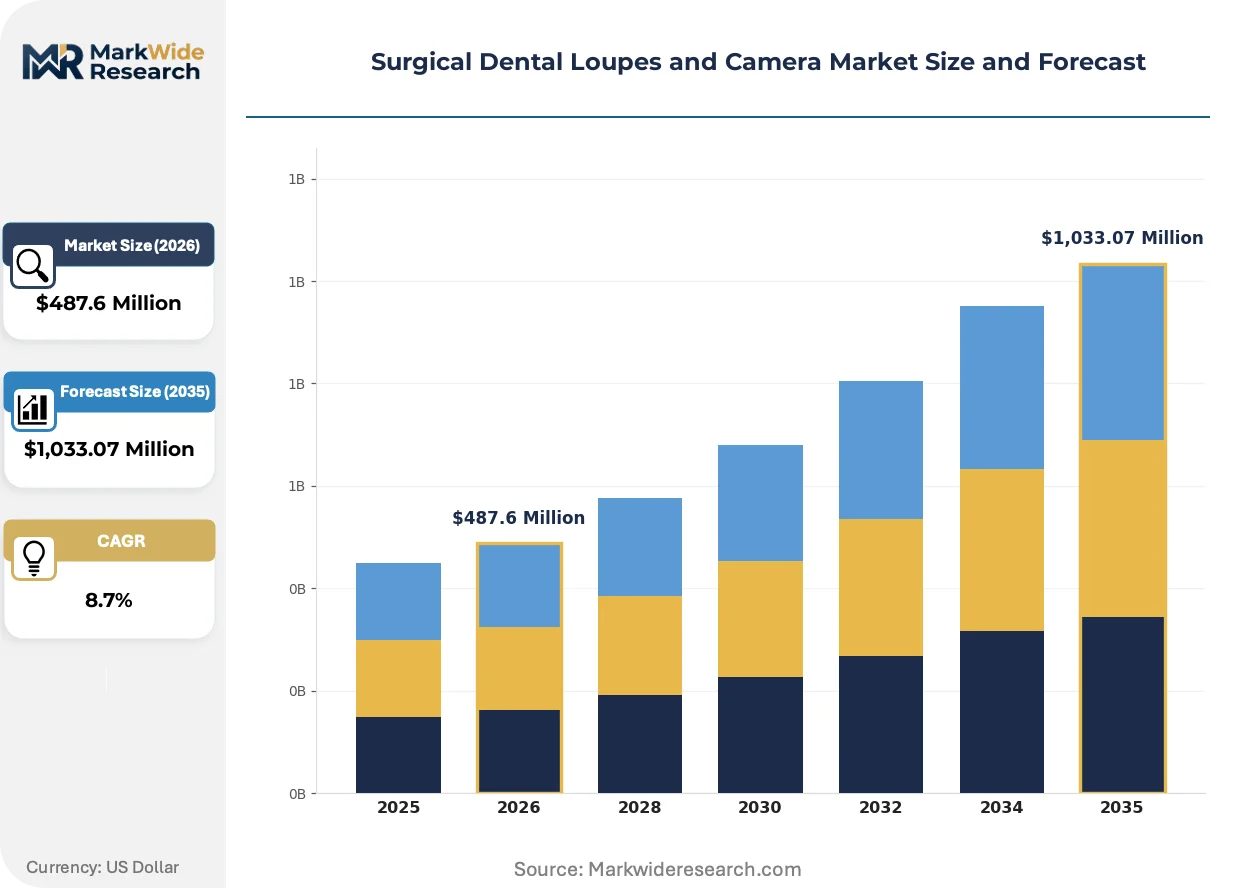
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
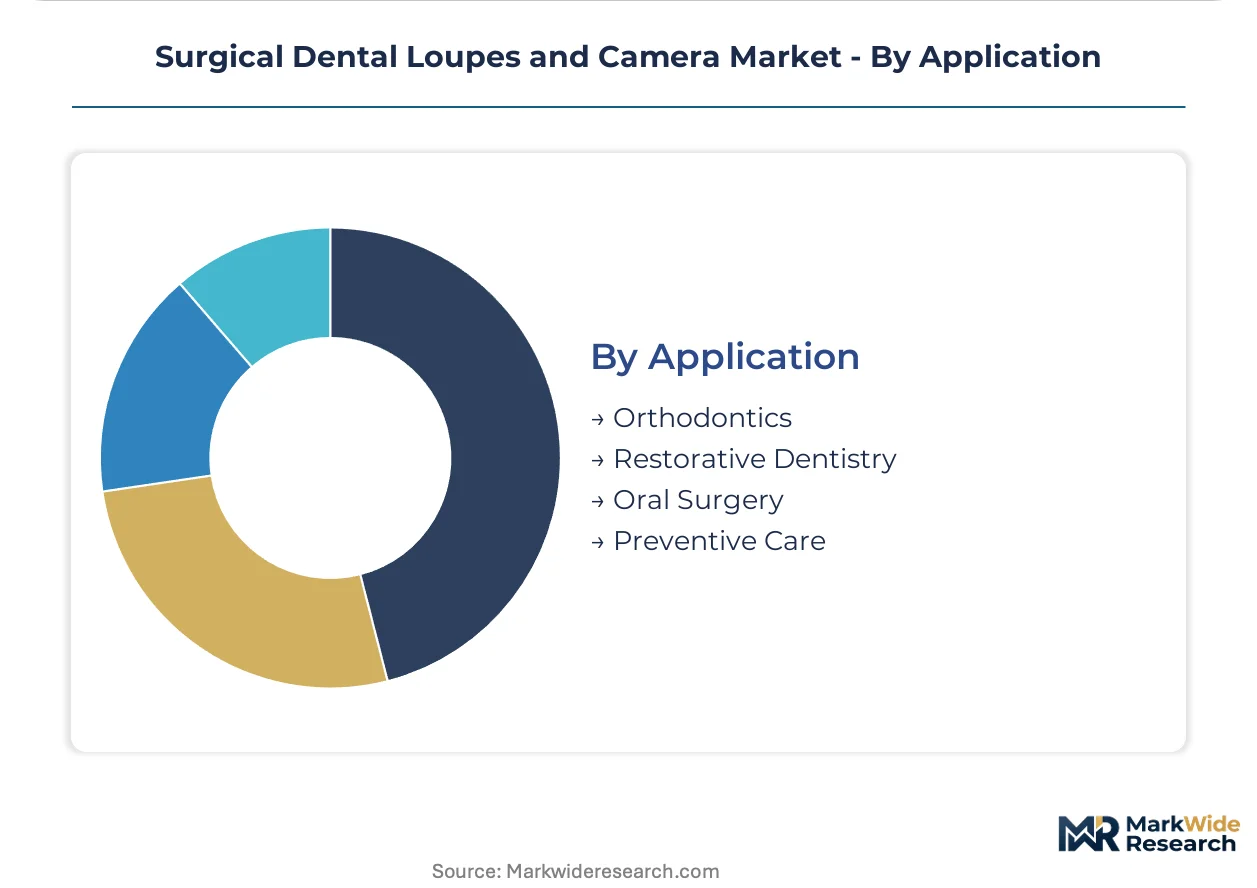
| Segmentation | Product Type: Flip-Up Loupes, Telescopic Loupes, Retina Cameras, Handheld Cameras Technology: LED Lights, Fiber Optic, Digital Imaging, Wireless Connectivity End User: Dentists, Dental Surgeons, Dental Assistants, Dental Students Application: Orthodontics, Restorative Dentistry, Oral Surgery, Preventive Care |
| Companies Covered | Carl Zeiss Meditec AG, Designs for Vision, Inc., Orascoptic, SurgiTel, HEINE Optotechnik GmbH & Co. KG, Enova Illumination, ErgonoptiX, Den-Mat Holdings, LLC, Rose Micro Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Dental Loupes and Camera Market Strategic Shifts
Digital capture modules paired with LED illumination are reshaping how procedural documentation integrates directly into surgical workflows. Three distinct vectors are accelerating market evolution.
Wireless connectivity is consolidating the tethered camera segment as oral surgeons abandon cable-dependent systems for Bluetooth and Wi-Fi-enabled documentation devices. Academic medical centers in the United States are deploying these systems at the fastest adoption rates. The shift is compressing aftermarket service revenue for legacy cable manufacturers while expanding recurring software subscription pools.
EU MDR cybersecurity annexes are mandating encrypted data transmission for wireless surgical cameras with patient-facing imaging capabilities. Manufacturers must now embed hardware security modules and conduct penetration testing prior to CE marking. German and Swiss dental device producers are responding fastest, integrating ISO 27001-aligned information security management into quality systems.
Academic procurement committees are centralizing vendor selection authority away from individual surgeon preferences toward institutional standardization. University hospital systems are consolidating supplier rosters to three to four approved loupe and camera vendors. This concentration is most visible in the northeastern United States, where massive health systems are negotiating enterprise pricing for visualization equipment.
Surgical Dental Loupes and Camera Market Segmentation
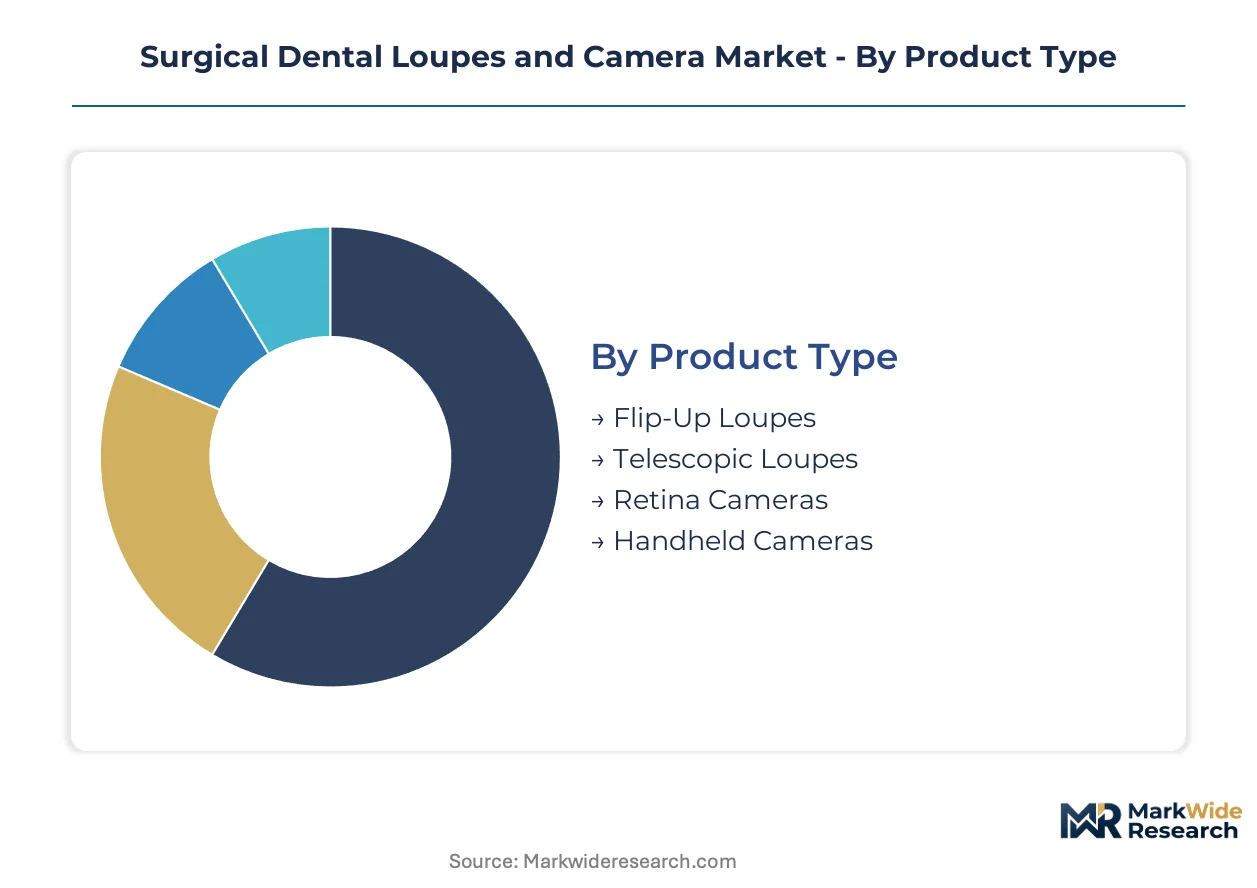
Segmentation in surgical dental visualization reveals how optical specifications, connectivity architecture, and procedural specialization dictate procurement patterns. Each axis shapes distinct margin structures and vendor competitive dynamics across the value chain.
Product Type:
Magnification mechanics and mounting architecture define the primary product taxonomy, with ergonomic considerations driving differential adoption across practice settings.
- Flip-Up Loupes:Hinged optical assemblies pivot away from the line of sight, enabling rapid transitions between magnified operative fields and standard vision. Academic medical centers in the United States deploy these most heavily in training environments where instructors must alternate between student supervision and direct visualization. Their versatility sustains the largest installed base among practicing clinicians despite weight penalties versus fixed-through-the-lens designs.
- Telescopic Loupes:Galilean or Keplerian optical systems deliver higher magnification ranges with superior edge-to-edge clarity for microsurgical procedures. Demand concentrates among oral surgeons performing endodontic microsurgery and periodontal regenerative procedures where 4.0x to 6.0x magnification is clinically necessary. German and Japanese optical heritage firms dominate this premium tier through proprietary lens coating technologies.
- Retina Cameras:Specialized fundus imaging systems adapted for dental applications capture high-resolution posterior segment documentation.
- Handheld Cameras:Portable digital capture devices enable intraoral photography without loupe integration for auxiliary staff.
Flip-Up Loupes leads on scale; Telescopic Loupes leads on momentum.
Technology:
Illumination source and data transmission protocols constitute the critical technology differentiators, with convergence between lighting and imaging accelerating replacement cycles.
- LED Lights:Solid-state emitters deliver color temperatures optimized for tissue differentiation with minimal thermal loading. Ambulatory surgical centers prioritize these for their 50,000-hour operational lifespans and reduced maintenance burden versus legacy halogen systems. The FDA's 510(k) pathway has streamlined clearance for LED-integrated loupes, compressing time-to-market for manufacturers.
- Fiber Optic:Light transmission through flexible glass bundles enables coaxial illumination without electromagnetic interference near sensitive instrumentation. Academic medical centers maintain these in hybrid operating suites where MRI compatibility is required. Supply concentration in German precision glass drawing facilities creates procurement vulnerability for North American device assemblers.
- Digital Imaging:CMOS and CCD sensor modules enable immediate procedural documentation with DICOM-compliant storage integration.
- Wireless Connectivity:Bluetooth and Wi-Fi protocols eliminate cable contamination risks while enabling real-time streaming to auxiliary displays.
LED Lights dominates current procurement volumes; Wireless Connectivity is climbing the fastest as infection control protocols tighten.
End User:
Credential level and procedural authority determine feature requirements, with training status and surgical volume driving divergent price elasticities.
- Dentists:General practitioners constitute the volume foundation, typically selecting 2.5x to 3.5x magnification for routine restorative and diagnostic procedures. Private practice owners in the United States exhibit strong preference for customizable working-distance configurations to accommodate ergonomic variation across clinical teams.
- Dental Surgeons:Board-certified specialists command the premium tier, requiring 4.0x to 6.0x systems with integrated camera modules for medicolegal documentation. University hospital employment contracts increasingly specify visualization equipment allowances, hardening institutional procurement channels.
- Dental Assistants:Auxiliary personnel utilize lower-magnification loupes for chairside support and instrument passing precision.
- Dental Students:Training programs represent price-sensitive volume with high replacement frequency as graduates transition to practice.
Dentists anchors absolute volume; Dental Surgeons commands margin expansion.
Application:
Procedural invasiveness and visualization precision requirements segment demand by clinical specialty, with reimbursement dynamics influencing capital allocation.
- Orthodontics:Fixed appliance placement and occlusal analysis utilize moderate magnification with emphasis on photographic documentation for treatment planning. Private orthodontic group practices in the United States are consolidating vendor relationships to capture enterprise pricing on visualization equipment across multi-site networks.
- Restorative Dentistry:Crown and bridge preparations, composite resin placement, and margin evaluation demand consistent 2.5x to 4.0x magnification with color-accurate illumination. The shift toward CAD/CAM same-day restorations is elevating documentation requirements as digital impressions replace physical models.
- Oral Surgery:Implant placement, bone grafting, and soft tissue procedures require the highest optical specifications with integrated video capture for informed consent documentation.
- Preventive Care:Caries detection and periodontal screening employ entry-level magnification for hygiene team deployment.
Restorative Dentistry leads on scale; Oral Surgery leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek jurisdictions with streamlined quality certification pathways and lower compliance overhead for precision optical assemblies.
United States
Ambulatory surgical centers in Texas and Florida are driving capital expenditure on LED-illuminated visualization systems with integrated digital capture. The FDA's 510(k) clearance pathway for Class II medical devices accelerates market entry timelines for domestic assemblers. Rochester, New York retains concentration in precision optics manufacturing, though final device assembly increasingly migrates to lower-cost southern states.
Germany
University hospital procurement committees in Bavaria and Baden-Württemberg are consolidating supplier rosters for high-magnification surgical microscopy. CE marking under the EU MDR extends conformity assessment timelines, favoring established domestic producers with dedicated regulatory affairs infrastructure. The precision glass drawing cluster in Jena supplies critical fiber-optic components to North American device manufacturers.
Japan
Oral surgery departments in Tokyo and Osaka are deploying wireless-enabled camera systems with hardened cybersecurity modules aligned to PMDA guidance. METI industrial standards for medical device software validation create compliance barriers for imported equipment. The Nagoya manufacturing corridor concentrates CMOS sensor fabrication for dental imaging subsystems.
Brazil
Private dental clinic chains in São Paulo and Rio de Janeiro are expanding procurement of ergonomic flip-up loupes for restorative procedures. ANVISA regulatory frameworks for Class II medical devices present whitespace opportunities for manufacturers with established ISO 13485 quality systems. Local distributors in Minas Gerais are building technical service capabilities to support imported visualization equipment.
Switzerland
Swissmedic certification requirements for wireless surgical cameras are mandating embedded hardware security modules prior to market authorization. Dental surgery training programs in Geneva and Zurich are standardizing on institutional procurement contracts rather than individual surgeon equipment allowances. The Basel region concentrates precision lens coating expertise serving German and Austrian device producers.
Surgical Dental Loupes and Camera Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbent optical specialists expand from surgical microscopy into integrated camera-documentation systems. The vendor base separates into three distinct tiers: heritage optics conglomerates with university hospital relationships, mid-scale specialists in ergonomic configurations, and regional assemblers competing on customizable working-distance options. Strategic archetypes include precision optical heritage players, ergonomic-focused configurators, and connectivity-first newcomers. M&A activity and technology licensing agreements represent the dominant competitive vectors as firms seek to fill capability gaps in wireless transmission and cybersecurity compliance.
Within the heritage optics tier, Carl Zeiss Meditec AG exemplifies the university hospital procurement channel anchor, while Designs for Vision, Inc. occupies a position among ergonomic configuration specialists. SurgiTel represents the customizable working-distance segment, competing on clinician-specific fit parameters that reduce operative fatigue.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Designs for Vision, Inc. |
| Orascoptic |
| SurgiTel |
| HEINE Optotechnik GmbH & Co. KG |
| Enova Illumination |
| ErgonoptiX |
| Den-Mat Holdings, LLC |
| Rose Micro Solutions |
| Others |
Value Chain & Pricing Dynamics
Wireless camera module miniaturization is compressing bill-of-materials costs while simultaneously concentrating CMOS sensor sourcing among Japanese and South Korean fabricators. This dual effect reshapes margin pools across the value chain as LED-illuminated loupes with integrated capture capabilities displace standalone documentation systems.
Pricing Analysis
Distributor margins on surgical visualization equipment typically absorb 25-35 percent of final device cost before hospital procurement committees negotiate enterprise pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by magnification range and camera integration depth, with telescopic systems commanding substantial premiums over flip-up configurations. Cost compression in entry-level LED-illuminated loupes is intensifying because regional assemblers in southern United States states are bypassing traditional distribution layers. Dental students and training programs exhibit the highest price sensitivity, while university hospital systems demonstrate the lowest due to bundled service contracts and visualization equipment allowances embedded in employment agreements.
Supply Chain Analysis
Refurbishment flows for precision optical assemblies create secondary market circulation that tempers new-unit demand among cost-conscious private practices. Manufacturing concentration clusters in Germany, Japan, and the United States, with Jena's precision glass drawing facilities feeding fiber-optic components to North American device assemblers. CMOS sensors, LED emitters, and proprietary lens coatings constitute critical input dependencies. Single-source vulnerability around German precision optics creates procurement exposure for manufacturers lacking dual-qualified suppliers. Distribution runs through specialized dental equipment distributors with technical service capabilities, though direct-to-hospital contracting is displacing this channel for large health system accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in surgical dental visualization rests on LED efficiency gains and the premium-tier shift toward wireless-integrated systems with recurring software revenue streams.
For Market Incumbents: Hedge against connectivity-first newcomers by embedding hardware security modules ahead of evolving FDA cybersecurity guidance for wireless-enabled devices. Deepen backward integration into precision lens coating capabilities to defend against German and Japanese optical heritage firms. Channel control through exclusive hospital system partnerships represents the priority defensive lever as procurement committees consolidate approved vendor rosters. For New Entrants and Emerging Players: Direct-to-clinic digital sales platforms offer the lowest customer acquisition cost route for ergonomic flip-up loupes targeting private dental group practices. Brazil's ANVISA regulatory whitespace and Latin American private clinic chain expansion present the most penetrable geographic opportunity. A software-subscription bundling angle bypasses capital-intensive upfront pricing resistance among price-sensitive training programs. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale ergonomic configurators lacking wireless connectivity capabilities but possessing established ISO 13485 quality systems and dental school relationships. The five-to-ten year viability window favors targets with regulatory affairs infrastructure spanning FDA 510(k) and EU MDR CE marking pathways. Watch for cybersecurity guidance finalization as the inflection signal that will accelerate consolidation toward hardened camera system producers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined Class II clearance accelerates product entry for LED-integrated loupes with digital capture modules. |
| CE Marking Pathway | EU MDR conformity assessment timelines favor established producers with dedicated regulatory infrastructure in Germany. |
| Hospital System Partnership | Enterprise pricing negotiations with northeastern United States health systems consolidate procurement authority away from individual surgeons. |
| Software Companion Development | Recurring subscription revenue from wireless camera streaming platforms compresses reliance on hardware margins. |
| Reimbursement Strategy | Medicolegal documentation requirements in oral surgery drive informed consent video capture into standard-of-care protocols. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procurement volume patterns and purchasing committee decision dynamics. Primary engagement spanned dental surgeons, hospital biomedical engineers, GPO contracts managers, and ambulatory surgical center administrators. Secondary validation drew from FDA 510(k) clearance databases, hospital procurement records, ISO 13485 certification registries, and dental school equipment allowance disclosures. Bottom-up vendor shipment tracking and top-down health system capital expenditure analysis were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon through documented replacement cycles for operative microscopy equipment and analog-to-digital documentation transitions. The analytical framework modeled magnification tier, connectivity architecture, illumination source, end-user credential level, and procedural application specialization across the modeling period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated academic medical center procurement expansion rates and wireless camera adoption curves in oral surgery settings.
The model assumes a particular technology adoption path; alternative pathways for augmented reality overlay integration with traditional optics would alter the outlook for premium telescopic loupes. Forecasts reflect assumptions around regulatory timeline stability and optical component supply continuity. Practitioners should monitor FDA cybersecurity guidance publication and EU MDR annex updates for early signals of compliance-driven vendor selection shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Healing Caps Market
Dental Devices
Dental Restoration Market
Dental Devices
Dental Implants Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Global Dental Burs Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Dental Handpieces Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
Global Dental Labs Market
Dental Devices
Dental Floss Market
Dental Devices
Glenoid Fossa Prosthesis Market