
 Demolition Vessels Market | 2026-2036
Demolition Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Demolition Vessels Market Analysis
Remote-operated demolition arms integrated with real-time structural monitoring is rewriting vessel capability requirements for precision dismantling of subsea assets. Heerema Marine Contractors leverages its heavy-lift vessel fleet to anchor large-scale platform removal contracts in the North Sea. Damen Shipyards Group competes through modular vessel designs that extend operational flexibility across varying water depths and debris profiles.
Demolition vessels are purpose-built or retrofitted marine craft engineered to dismantle offshore platforms, bridges, and coastal industrial structures, typically featuring crane capacities exceeding 500 tonnes and reinforced hulls to absorb impact stresses from falling debris. Floating crane vessels dominate contract value for platform topside removal, while excavator barges lead unit volume in nearshore and harbor demolition where draft limitations apply. Hydraulic demolition technology captures the largest installed base, though controlled demolition methods are gaining share in environmentally sensitive marine zones where debris containment is mandatory.
The International Maritime Organization's ship recycling conventions and the EU Ship Recycling Regulation are tightening material traceability and hazardous substance documentation requirements for vessels engaged in demolition work. The Netherlands Human Environment and Transport Inspectorate and the UK Maritime and Coastguard Agency enforce vessel-specific safety certifications that shape fleet upgrade cycles and barrier-to-entry dynamics. Stakeholders must weigh capital allocation between newbuild specialized units and retrofit programs as regulatory thresholds for emissions and worker safety tighten without grandfathering existing tonnage.
Market Dynamics
Remote-operated demolition arms integrated with real-time structural monitoring are compressing project timelines and forcing fleet-wide capability upgrades across the North Sea decommissioning sector.
Growth Catalysts
- EU Green Deal vessel upgrade mandates:The European Commission's marine environmental directives are accelerating capital flows toward lower-emission demolition methods and hybrid propulsion retrofits.
- North Sea platform retirement wave:Aging oil and gas infrastructure across United Kingdom and Norwegian waters is generating sustained contract pipelines for heavy-lift removal services.
- Controlled demolition methods:Hydraulic containment systems for environmentally sensitive marine zones are expanding addressable project scopes where debris management was previously prohibitive.
Market Restraints
- Specialized steel alloy supply concentration:Reinforced hull plating and crane boom materials face sourcing bottlenecks from limited European mill capacity.
- IMO ship recycling documentation burdens:The International Maritime Organization's material traceability requirements extend project onboarding timelines and compliance overhead.
- Excavator barge substitution in nearshore zones:Lower-draft alternatives capture harbor and coastal demolition volumes where full-specification vessels face operational constraints.
Strategic Opportunities
- Subsea cable decommissioning expansion:Offshore wind farm end-of-life cycles in the United Kingdom are creating new demand profiles for precision seabed clearing operations.
- UK Maritime and Coastguard Agency certification harmonization:Streamlined safety approval pathways reduce barrier-to-entry for specialized newbuild tonnage entering the North Sea.
- Digital twin integration with demolition planning:Convergence of structural modeling software and real-time sensor feeds is enabling predictive dismantling sequences that minimize secondary damage.
Industry Challenges
- ROV pilot and demolition engineer talent scarcity:The specialized skill intersection of underwater robotics operation and structural engineering constrains crew scaling for concurrent projects.
- Dual certification timelines:Vessel operators must sequence EU Ship Recycling Regulation compliance with national flag-state approvals, extending drydock periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demolition Vessels Market |
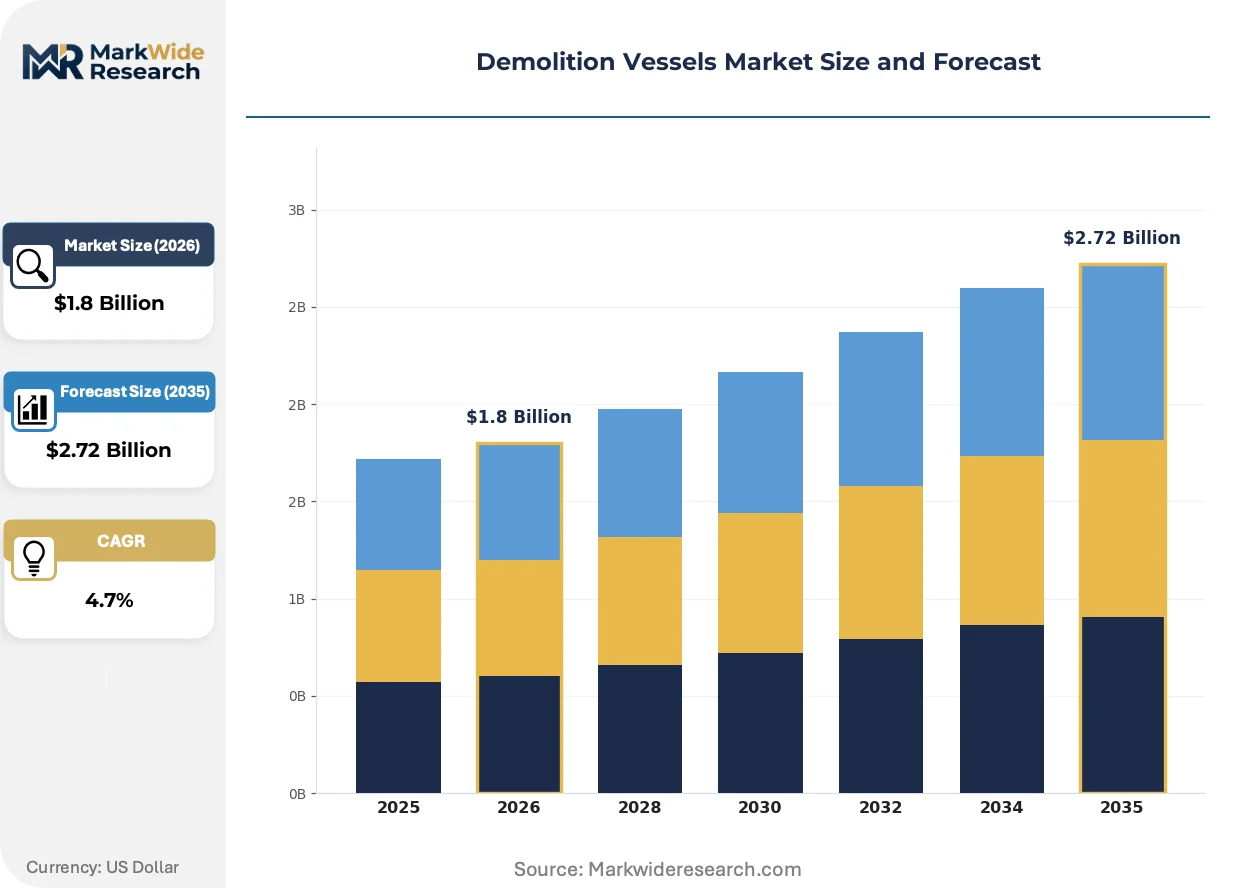
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Excavator Barge, Floating Crane, Dredger, Demolition Tug Application: Industrial Sites, Urban Redevelopment, Marine Structures, Bridge Removal Technology: Hydraulic Demolition, Mechanical Demolition, Controlled Demolition, Implosion Technology End User: Construction Firms, Government Agencies, Environmental Consultants, Marine Contractors |
| Companies Covered | Van Oord, Heerema Marine Contractors, Damen Shipyards Group, McDermott International, Subsea 7, Boskalis Westminster, Jan De Nul Group, Wirana Shipping Company, Saipem S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demolition Vessels Market Emerging Trajectories
Digital integration is compressing the gap between structural assessment and physical dismantling, while regulatory pressure on emissions and worker safety is accelerating equipment refresh cycles across the fleet.
Teleoperation suites with haptic feedback interfaces are virtualizing the demolition command chain, allowing shore-based engineers to direct subsea cutting operations with millimeter precision. North Sea platform operators are deploying these systems for first-cut sequences in hazardous zones. The technology is virtualizing traditional dive-team dependencies and reducing personnel exposure in high-risk demolition phases.
The EU Ship Recycling Regulation's hazardous substance documentation requirements are reshaping vessel procurement specifications across European waters. Shipyards must now embed material passporting systems into newbuild designs to satisfy downstream traceability audits. Norwegian-flagged demolition fleets are responding with integrated RFID tagging of structural components from fabrication through retirement.
Asset owners are unbundling engineering-procurement-construction contracts into discrete demolition service agreements with outcome-based liability structures. This disintermediates traditional integrated contractors and places direct performance risk on specialized vessel operators. The United Kingdom's mature decommissioning market exhibits the most advanced contract fragmentation, with separate awards for topside removal, jacket severance, and debris clearance.
Demolition Vessels Market Segmentation
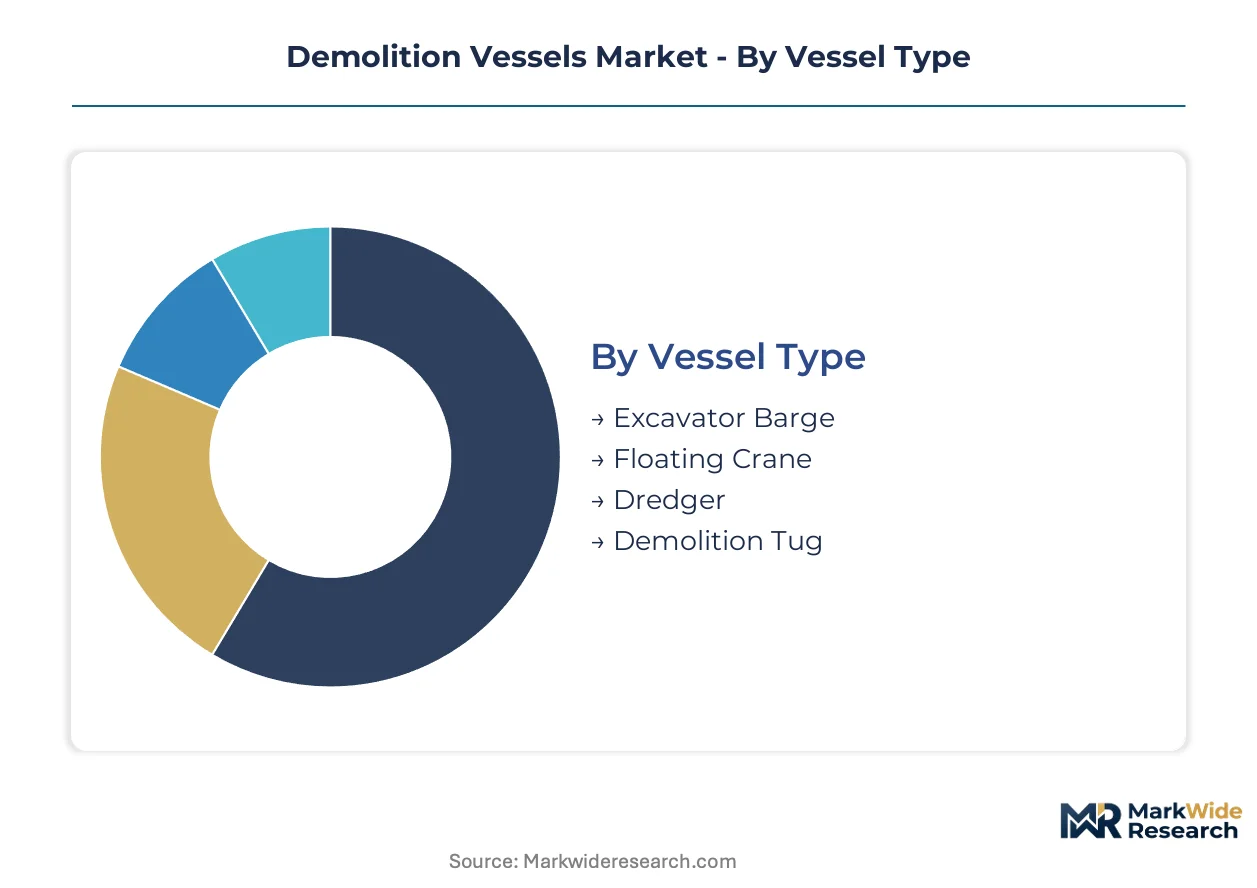
Demolition vessel procurement decisions hinge on water depth constraints, debris containment mandates, and structural load requirements. Each segmentation dimension reveals distinct capability trade-offs between capital intensity and operational flexibility across decommissioning project portfolios.
Vessel Type:
Mature configurations dominate contract value in deepwater North Sea decommissioning, while emerging designs capture nearshore and harbor applications where draft limitations apply.
- Floating Crane:Heavy-lift platforms with crane capacities exceeding 500 tonnes anchor large-scale platform topside removal contracts. United Kingdom and Norwegian waters concentrate demand as aging oil infrastructure retirement accelerates, though reinforced hull steel sourcing bottlenecks constrain fleet expansion timelines.
- Excavator Barge:Modular flat-deck vessels with mounted hydraulic arms lead unit volume in coastal zones and confined waterways. Damen Shipyards Group competes through adaptable designs spanning varying water depths, while lower capital thresholds attract regional operators serving harbor maintenance contracts.
- Dredger:Integrated suction and cutting systems handle seabed preparation and debris clearance in marine demolition sequences.
- Demolition Tug:Compact maneuvering craft position larger assets and manage debris containment booms in restricted-access zones.
Floating crane vessels retain volume leadership in contract value; excavator barges hold the steepest expansion curve as coastal decommissioning pipelines mature.
Application:
Cost tier stratification separates capital-intensive offshore programs from standardized nearshore contracts with shorter procurement cycles.
- Marine Structures:Offshore platform, subsea pipeline, and wind farm foundation dismantling demands precision cutting in environmentally sensitive zones. EU Green Deal marine directives accelerate controlled demolition method adoption where debris containment is mandatory, compressing project timelines through remote-operated systems.
- Bridge Removal:Span dismantling over navigable waterways requires coordinated waterway closure permits and floating debris management. United Kingdom infrastructure renewal programs generate recurring demand for modular barge configurations that minimize traffic disruption windows.
- Industrial Sites:Coastal refinery and terminal decommissioning combines marine access with hazardous material handling protocols.
- Urban Redevelopment:Harbor-front renewal projects in constrained waterways prioritize low-draft vessels with minimal community impact.
Marine structures command premium day-rates; bridge removal represents the fastest-growing trajectory as aging infrastructure replacement cycles synchronize across European waterways.
Technology:
Margin profiles diverge between established hydraulic systems with proven maintenance networks and emerging precision methods carrying higher equipment amortization.
- Hydraulic Demolition:Ram and breaker systems mounted on barge-deck excavators constitute the largest installed base across nearshore demolition fleets. Norway's environmental regulator enforces noise and vibration thresholds that favor electric-hybrid hydraulic power packs in sensitive fjord zones.
- Controlled Demolition:Pre-weakened structural sequences with debris containment systems expand addressable scopes in protected marine habitats. The Netherlands Human Environment and Transport Inspectorate mandates hydraulic containment for projects within Natura 2000 boundaries, elevating method specification in contract awards.
- Mechanical Demolition:Conventional cutting and lifting operations serve standardized harbor and coastal dismantling with lower technology premiums.
- Implosion Technology:Explosive collapse sequences apply to isolated offshore jackets with comprehensive exclusion zone management.
Hydraulic demolition retains volume leadership; controlled demolition gains share fastest as environmental permit conditions tighten across North Sea jurisdictions.
End User:
Customer type determines contract structure complexity, from integrated engineering-procurement-construction awards to discrete service agreements with outcome-based liability.
- Marine Contractors:Specialized vessel operators like Heerema Marine Contractors assume direct performance risk for platform removal sequences. United Kingdom contract fragmentation trends disintermediate traditional integrated contractors, creating separate awards for topside removal, jacket severance, and debris clearance that favor dedicated marine demolition fleets.
- Government Agencies:Public infrastructure authorities specify compliance-heavy procurement with extended safety certification requirements. UK Maritime and Coastguard Agency vessel-specific certifications shape fleet upgrade cycles and create barrier-to-entry dynamics for new market entrants.
- Construction Firms:General contractors subcontract marine demolition as specialized work packages within larger redevelopment programs.
- Environmental Consultants:Technical advisors influence method selection and debris management specifications without direct vessel operation.
Marine contractors retain volume leadership; government agencies drive the steepest capability upgrade curve as regulatory thresholds tighten without grandfathering existing tonnage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine contractors and offshore asset operators concentrate procurement authority in North Sea jurisdictions where platform decommissioning timelines are most advanced. Regulatory divergence between EU marine environmental directives and national flag-state requirements shapes vessel certification complexity across key demand centers.
United Kingdom
The UK Continental Shelf hosts the most mature offshore decommissioning pipeline in Europe, with over 470 platforms approaching end-of-life. The UK Maritime and Coastguard Agency enforces vessel-specific safety certifications that extend drydock upgrade cycles for operators serving British waters. Aberdeen and Great Yarmouth anchor the country's marine demolition contractor clusters, where Heerema Marine Contractors and Subsea 7 maintain operational headquarters for North Sea campaign management.
Norway
Norwegian North Sea infrastructure retirement generates sustained demand for heavy-lift removal services alongside stringent fjord-zone environmental protections. The Norwegian Maritime Authority enforces noise and vibration thresholds that favor electric-hybrid propulsion systems in sensitive coastal waters. Stavanger and Bergen concentrate engineering-procurement-construction contractor offices, with local shipyards specializing in reinforced hull fabrication for debris-impact resistance.
Netherlands
Dutch maritime engineering clusters supply modular vessel designs that extend operational flexibility across varying water depths and debris profiles. The Human Environment and Transport Inspectorate mandates hydraulic containment systems for projects within Natura 2000 boundaries, elevating method specifications in contract awards. Rotterdam and Schiedam host Damen Shipyards Group facilities and Boskalis Westminster marine demolition divisions serving North Sea and Baltic contracts.
Germany
German industrial harbor renewal programs generate recurring demand for low-draft excavator barge configurations in constrained waterways. The Federal Maritime and Hydrographic Agency coordinates vessel safety inspections with state-level environmental regulators for Elbe and Baltic coastal projects. Hamburg and Bremerhaven anchor the country's marine demolition service provider networks, with specialized operators serving refinery decommissioning along the Lower Saxony coast.
United States
Gulf of Mexico platform decommissioning accelerates as shallow-water infrastructure reaches structural retirement thresholds. The Bureau of Safety and Environmental Enforcement oversees platform removal compliance timelines that cascade into vessel charter demand for heavy-lift and cutting operations. Houston and New Orleans concentrate marine contractor procurement functions, with Port Fourchon serving as the primary mobilization point for demolition vessel campaigns in federal waters.
Demolition Vessels Market Vendor Landscape
Channel-controlling players compete with product-specialist players across contract tiers differentiated by project scale and technical complexity. The vendor base organizes around three strategic archetypes: integrated offshore engineering contractors with captive vessel fleets, modular shipbuilders supplying adaptable platform designs, and regional operators serving harbor and nearshore maintenance contracts. Consolidation pressure concentrates among North Sea specialists seeking scale for platform removal liability pools, while fragmentation persists in coastal zones where lower capital thresholds attract niche barge operators. Dominant competitive moves include strategic partnerships between shipyards and marine contractors for newbuild co-development, and geographic expansion through flag-state certification harmonization to access adjacent North Sea jurisdictions.
Within the integrated contractor tier, Heerema Marine Contractors and Subsea 7 occupy positions defined by heavy-lift asset ownership and platform removal campaign management. Damen Shipyards Group represents the modular fabrication archetype, supplying vessel platforms that operators configure for varying water depth and debris containment requirements. Among demolition service specialists, Boskalis Westminster and Jan De Nul Group exemplify diversified marine contractors with demolition capabilities nested within broader dredging and offshore installation portfolios. Van Oord and Saipem S.p.A. anchor the European engineering-procurement-construction segment with vessel fleets positioned for large-scale decommissioning awards.
| Leading Market Players |
|---|
| Van Oord |
| Heerema Marine Contractors |
| Damen Shipyards Group |
| McDermott International |
| Subsea 7 |
| Boskalis Westminster |
| Jan De Nul Group |
| Wirana Shipping Company |
| Saipem S.p.A. |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Schiedam shipbuilding clusters concentrate reinforced hull fabrication capacity for debris-impact resistant vessels, translating into asymmetric pricing power for operators sourcing European-built tonnage versus Asian retrofit alternatives.
Pricing Analysis
Cost-plus contracts with steel price indexation dominate North Sea decommissioning awards, linking day-rates to London Metal Exchange nickel and high-tensile alloy benchmarks. Price differentiation rests on UK Maritime and Coastguard Agency certification tier and crane capacity class. Margins are tightening due to specialized steel alloy sourcing bottlenecks from limited European mill capacity. Regional harbor operators exhibit highest price sensitivity, while integrated platform removal contractors absorb premium vessel specifications for liability reduction.
Supply Chain Analysis
Damen Shipyards Group and Dutch maritime engineering clusters hold contract-manufacturing concentration for modular vessel platforms configurable across water depths. Supply draws from Netherlands, Norway, and South Korean specialized steel mills for reinforced hull plating and crane boom forgings. Single-source vulnerability concentrates in European high-tensile alloy supply given limited secondary sourcing for marine-grade impact-resistant specifications. Distribution runs through marine contractor fleet operators chartering to offshore asset owners and government infrastructure authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where UK Maritime and Coastguard Agency certification entrenchment creates switching costs that lock asset owners into established vessel operator relationships.
For Market Incumbents: Insulate market position through backward integration into specialized steel component sourcing and captive drydock maintenance capacity in Aberdeen and Great Yarmouth clusters. The threat of excavator barge substitution in nearshore zones demands preemptive capability expansion into modular barge configurations. Certification investment in EU Ship Recycling Regulation compliance ahead of flag-state deadlines preserves charter preference hierarchies. For New Entrants and Emerging Players: Build out presence in German industrial harbor renewal programs where Federal Maritime and Hydrographic Agency oversight is less stringent than UK equivalents. The Elbe and Baltic coastal zones represent the most penetrable geography given lower capital thresholds for low-draft excavator barge entry. A go-to-market angle anchored in electric-hybrid propulsion systems addresses Norwegian Maritime Authority noise thresholds without full heavy-lift vessel investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized marine contractors with integrated digital twin demolition planning capabilities and established North Sea liability track records. Long-term viability rests on contract pipeline visibility through platform retirement wave maturity. Acquisition targets should demonstrate UK Maritime and Coastguard Agency certification harmonization pathways into adjacent Norwegian and Dutch jurisdictions. The signal to watch is contract fragmentation velocity toward discrete service agreements with outcome-based liability structures.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit Program | EU Green Deal marine directives mandate lower-emission demolition methods across North Sea fleets. |
| Digital Twin Integration Partnership | Structural modeling software convergence with real-time sensor feeds enables predictive dismantling sequences. |
| Subsea Cable Decommissioning Capability Buildout | Offshore wind farm end-of-life cycles in United Kingdom create precision seabed clearing demand profiles. |
| Specialized Steel Sourcing Agreement | Reinforced hull plating supply bottlenecks from limited European mill capacity threaten fleet expansion timelines. |
| ROV Pilot Training Academy Establishment | Talent scarcity at the robotics-operation and structural-engineering intersection constrains concurrent project scaling. |
Methodological Framework
Desk research of Lloyd's List vessel databases, UK Continental Shelf decommissioning program filings, and EU Ship Recycling Regulation compliance registries preceded structured interviews with marine contractor fleet managers, offshore asset operator procurement leads, shipyard engineering directors, and regulatory affairs specialists at maritime authorities. Secondary validation drew from UK Maritime and Coastguard Agency safety certification records, Norwegian Maritime Authority environmental compliance filings, and Bureau of Safety and Environmental Enforcement platform removal timelines. Bottom-up charter rate aggregation and top-down contract value estimation were cross-referenced for triangulation.
Assumptions held fixed include current EU Green Deal marine directive enforcement intensity and North Sea platform retirement schedule adherence; variables stress-tested encompass steel price volatility and ROV pilot labor supply elasticity. Segmentation modeling spanned vessel type, application, technology method, and end-user contract structure across the projection horizon. CAGRs were derived from contract award velocity analysis and fleet capacity utilization trends. Industry-specific forecast inputs incorporated offshore wind farm commissioning-to-decommissioning cycle timelines and hydraulic containment system adoption curves in Natura 2000 zones.
Stress conditions across steel alloy pricing bands, regulatory compliance timeline acceleration, and substitute technology penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor sensitivities. Quarterly review of UK Continental Shelf platform removal award announcements and EU marine environmental directive amendment proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Roadheaders Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Hammer Unions Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Boom Cranes Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Yard Crane Market
Construction Equipment
Europe Ground Penetrating Radar Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Assembly Machine Market