
 Roadheaders Market | 2026-2036
Roadheaders Market Size, Share, and Industry Trends Forecast 2026-2036
Roadheaders Market Analysis
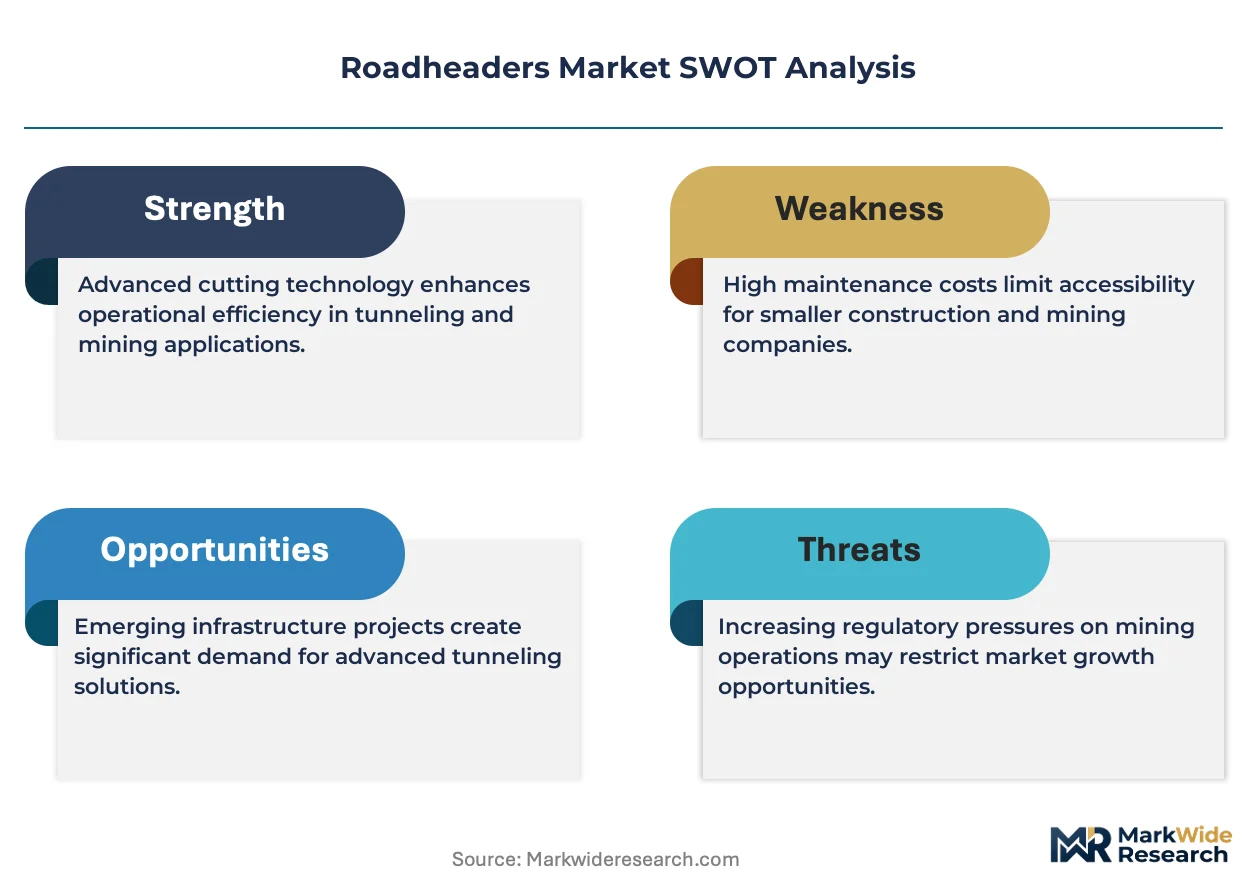
Aftermarket maintenance contracts and telemetry-based fleet management is realigning how roadheader OEMs capture lifetime value from each machine deployed underground. Sandvik leverages its global service infrastructure to lock in multi-year maintenance agreements across Scandinavian mining operations. Famur anchors its competitive position through deep vertical integration into cutting head metallurgy and hydraulic system manufacturing. China Railway Engineering Equipment Group dominates domestic tunneling projects through scale advantages in electric-powered machine production.
A roadheader is a boom-type partial-face cutting machine that employs a rotating cutter head mounted on an articulated arm to excavate rock or coal in underground environments, typically operating within cutting powers ranging from 100 kW to 400 kW depending on seam hardness. The equipment serves as the primary mechanical entry driver in underground mining and civil tunneling where drill-and-blast methods face restrictions from vibration, gas, or urban proximity. Continuous miners command the largest installed base among type segments due to decades of proven deployment in soft-to-medium rock coal seams, though hard rock miners are gaining traction as metal mining depths increase. Electric motors are displacing diesel engines fastest among power source categories, driven by underground ventilation cost pressures and emissions compliance burdens that compress total cost of ownership for battery-trolley hybrid architectures.
The EPA enforces MSHA-aligned diesel particulate limits that effectively bar non-compliant engines from US underground operations, while the EU F-Gas Regulation and Stage V emission standards from ECHA constrain hydraulic fluid and engine choices across European tunneling fleets. China's MEE implements dual carbon goals that pressure domestic manufacturers toward electric and hybrid system development for underground equipment sold into state-owned mining enterprises. Stakeholders must monitor how battery energy density improvements and fast-charging infrastructure investments reshape the economic boundary between diesel retention and electric conversion in deep-level applications.
Market Dynamics
Electric motor architectures are displacing diesel powertrains across underground mining and tunneling fleets, driven by ventilation cost pressures and emissions compliance burdens that compress total cost of ownership for battery-trolley hybrid systems.
Growth Catalysts
- EU Stage V emission standards:Underground equipment operators across Germany, Poland, and Scandinavia face mandatory diesel particulate limits that accelerate electric roadheader procurement.
- Deep ore body access:Metal mining operations in Western Australia and Chile require hard rock cutting machines capable of operating at depths exceeding 1,500 meters where conventional methods fail.
- China's western railway expansion:State-owned tunneling contractors in Sichuan and Xinjiang provinces deploy electric-powered roadheaders to connect inland resource basins to coastal manufacturing corridors.
Market Restraints
- Battery energy density limitations:Lithium-ion cell chemistry constraints restrict continuous cutting duration in deep-level applications without trolley-assist infrastructure.
- Cutting head metallurgy concentration:Premium tungsten carbide insert supply concentrates among a limited set of specialized powder metallurgy suppliers in Central Europe.
- MSHA ventilation equivalence:US underground coal operations face extended approval timelines for diesel-to-electric conversions that delay fleet modernization.
Strategic Opportunities
- India's underground coal mechanization:The country's national mining enterprise seeks to raise mechanized extraction share from current levels, creating first-mover advantage for electric roadheader suppliers.
- Telemetry-based predictive maintenance:Real-time vibration monitoring and cutting force analytics enable outcome-based service contracts that capture lifetime equipment value.
- Fast-charging infrastructure:Trolley pantograph and battery swap station investments at mine sites reshape the economic boundary between diesel retention and full electric conversion.
Industry Challenges
- Deep-level automation integration:Remote operation centers require seamless machine-to-surface communication protocols that legacy analog hydraulic systems cannot support without complete control architecture replacement.
- Cutting head rebuild skill scarcity:Specialized welders capable of precision brazing tungsten carbide inserts to steel bodies command premium wages that inflate aftermarket service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roadheaders Market |
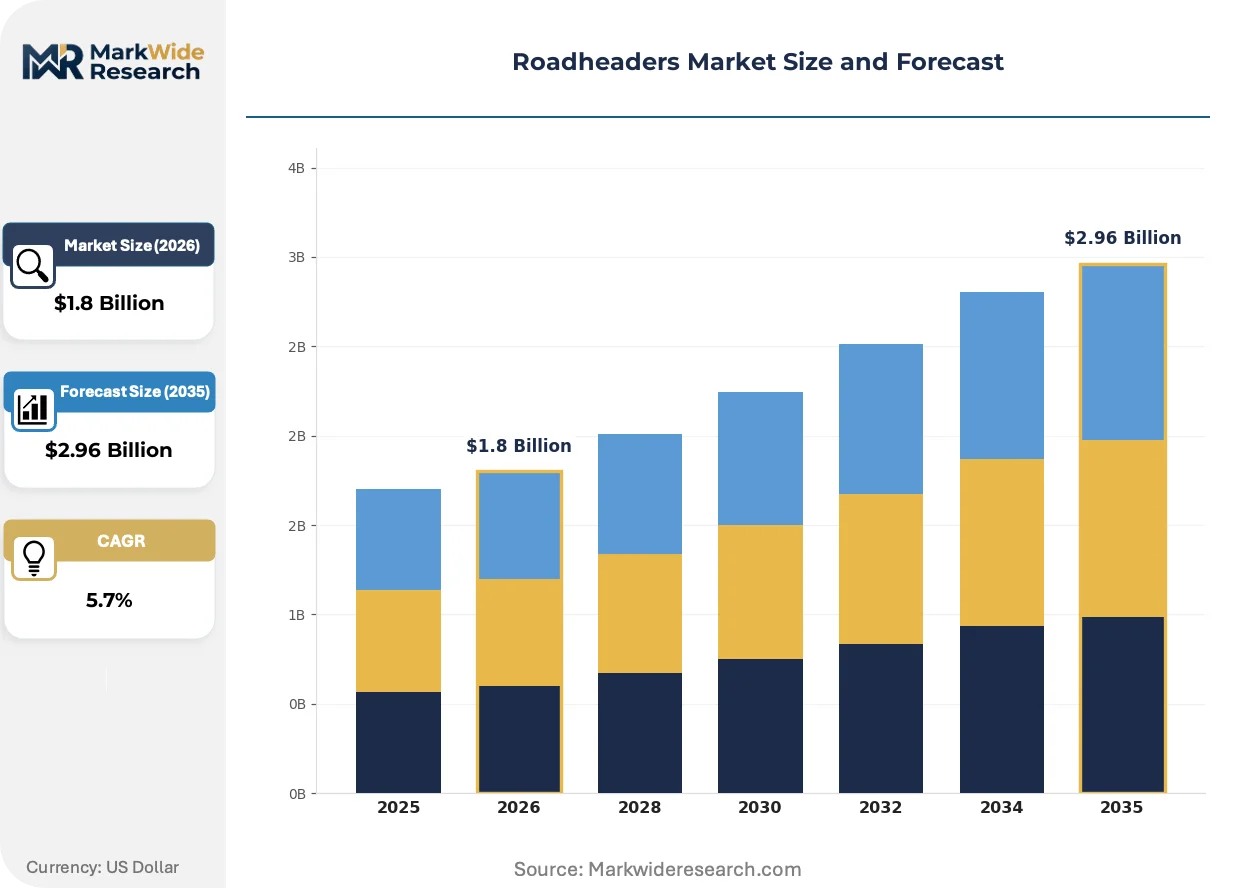
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Continuous Miners, Crossover Miners, Hard Rock Miners, Tunneling Machines End User: Mining Companies, Construction Firms, Infrastructure Developers, Utility Providers Application: Tunneling Projects, Underground Excavation, Road Construction, Mineral Extraction Power Source: Diesel Engines, Electric Motors, Hybrid Systems, Pneumatic Systems |
| Companies Covered | Famur, China Railway Engineering Equipment Group, Sandvik, BBM Group, Mitsui Miike Machinery, Sany, Antraquip, Komatsu, XCMG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roadheaders Market Emerging Trajectories
Machine learning algorithms and sensor fusion architectures are actively reshaping how roadheaders adapt cutting parameters in real-time, shifting competitive advantage from mechanical durability to data-driven operational intelligence.
Lidar-based seam tracking combined with force-feedback cutting arms is automating horizon control in variable geology without operator intervention. Australian longwall development operations deploy these systems to maintain precise grade through faulted zones. The technology is compressing labor requirements in round-the-clock cutting cycles while reducing unplanned downtime from cutter head collisions with roof strata.
The EPA's MSHA-aligned diesel particulate limits and the EU F-Gas Regulation constrain hydraulic fluid and engine choices across North American and European tunneling fleets. Underground contractors face equipment retirement timelines that accelerate capital replacement cycles. Hard rock mining segments in Nevada and Sweden respond with pilot programs for battery-electric continuous miners ahead of regulatory deadlines.
Aftermarket service unbundling allows mining houses to separate maintenance contracts from original equipment procurement, pressuring OEM margins while opening third-party provider entry. Major Australian coal operators now tender telemetry and spare parts supply independently from machine purchase. This pattern concentrates most visibly in Queensland's Bowen Basin where consolidated mining houses possess sufficient fleet scale to justify in-house maintenance capabilities.
Roadheaders Market Segmentation
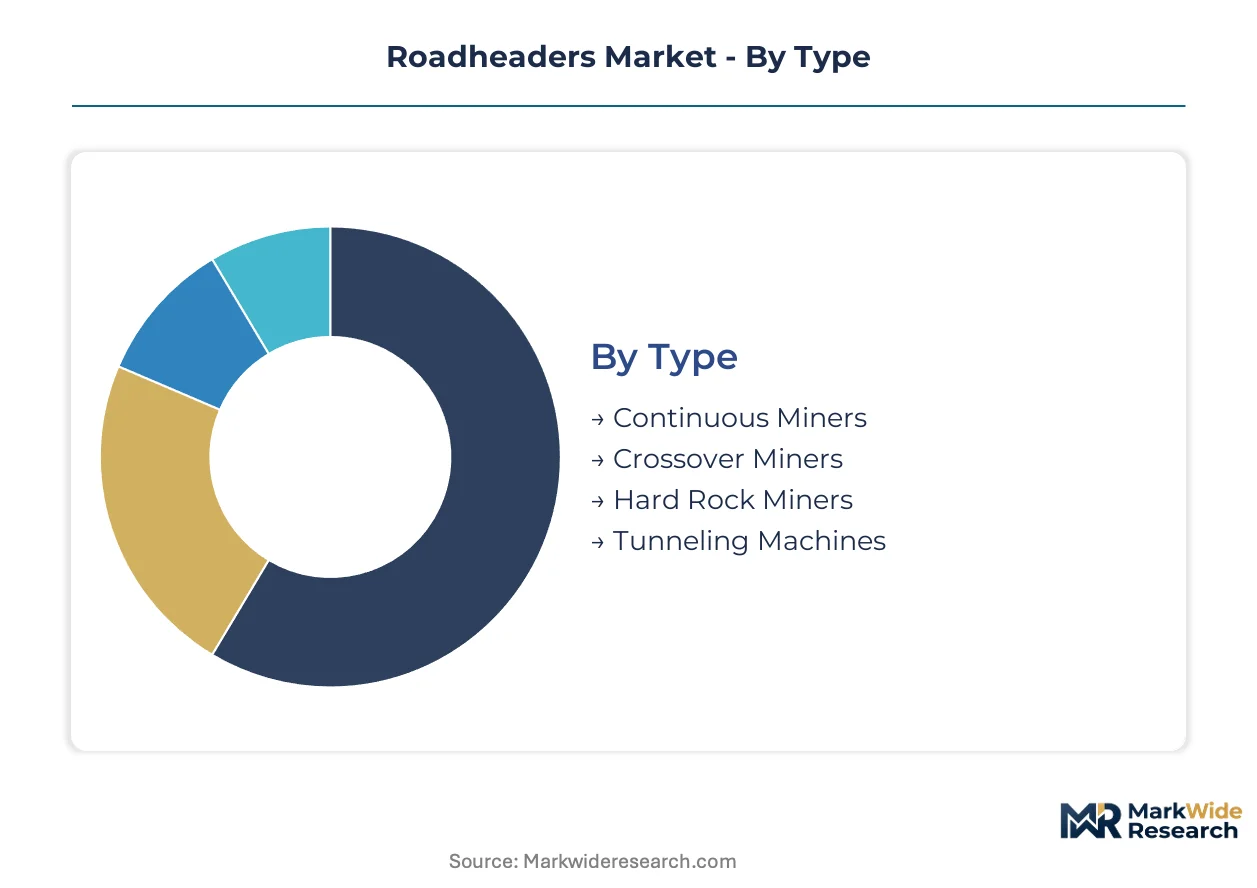
Roadheader procurement decisions hinge on matching machine specifications to geological conditions, regulatory environments, and operational depth. Segmentation reveals where capital concentrates and which technology trajectories reshape competitive positioning.
Type:
Standardized designs dominate high-volume coal applications while custom-engineered cutting heads address variable rock hardness in metal mining.
- Continuous Miners:These machines employ rotating drum cutters with integral loading mechanisms designed for soft-to-medium coal seams. Australian longwall development operations in Queensland's Bowen Basin deploy the largest installed fleets, driven by labor cost pressures that favor fully mechanized extraction cycles over drill-and-blast alternatives.
- Hard Rock Miners:Specialized cutting heads with higher torque ratings and reinforced boom structures penetrate abrasive metalliferous formations. Chilean copper operations below 1,500 meters depth generate concentrated demand as conventional raise boring methods fail at extreme hydrostatic pressure.
- Crossover Miners:Modular frame designs accept interchangeable cutting heads for operators managing mixed geology. South African platinum mines near Rustenburg value this adaptability.
- Tunneling Machines:Compact profiles suit civil infrastructure with strict vibration limits. Urban metro projects in Chengdu and Istanbul specify these for residential proximity.
Leading the category by volume: Continuous Miners. Expanding most quickly: Hard Rock Miners.
End User:
Procurement sophistication varies sharply across customer types, with consolidated miners leveraging fleet scale against fragmented contractors purchasing single units.
- Mining Companies:Integrated operators with multi-site portfolios negotiate multi-year service agreements bundling telemetry, spare parts, and rebuild services. BHP and Rio Tinto in Western Australia structure procurement around total cost of ownership models that internalize ventilation and energy costs.
- Construction Firms:Project-based contractors prioritize rental and lease-to-own structures that match equipment payments to milestone cash flows. Turkish contractors building the Ankara-Sivas high-speed rail corridor favor short-term electric roadheader leases.
- Infrastructure Developers:State-owned entities in China's western provinces specify domestic electric equipment through centralized tender processes.
- Utility Providers:Water and power tunneling operations in Norway and Switzerland require low-emission machines for alpine hydroelectric schemes.
Dominating procurement value: Mining Companies. Gaining share fastest: Infrastructure Developers.
Application:
Application selection determines cutting head geometry, dust suppression requirements, and automation integration depth.
- Tunneling Projects:Civil engineering applications demand precise grade control and minimal overbreak to limit concrete lining costs. China's railway expansion through Sichuan's mountainous terrain consumes electric-powered machines with automated seam tracking.
- Mineral Extraction:Production cutting in coal and metal mines prioritizes raw throughput and integration with continuous haulage systems. Polish hard coal mines in Upper Silesia retrofit legacy roadheaders with EU Stage V compliant powertrains.
- Underground Excavation:Development headings and access drifts require machines with rapid tramming capabilities between faces.
- Road Construction:Slope stabilization and mountain highway tunnels in Peru and Colombia specify compact roadheaders for altitude-restricted sites.
Commanding the largest equipment base: Mineral Extraction. Climbing the fastest: Tunneling Projects.
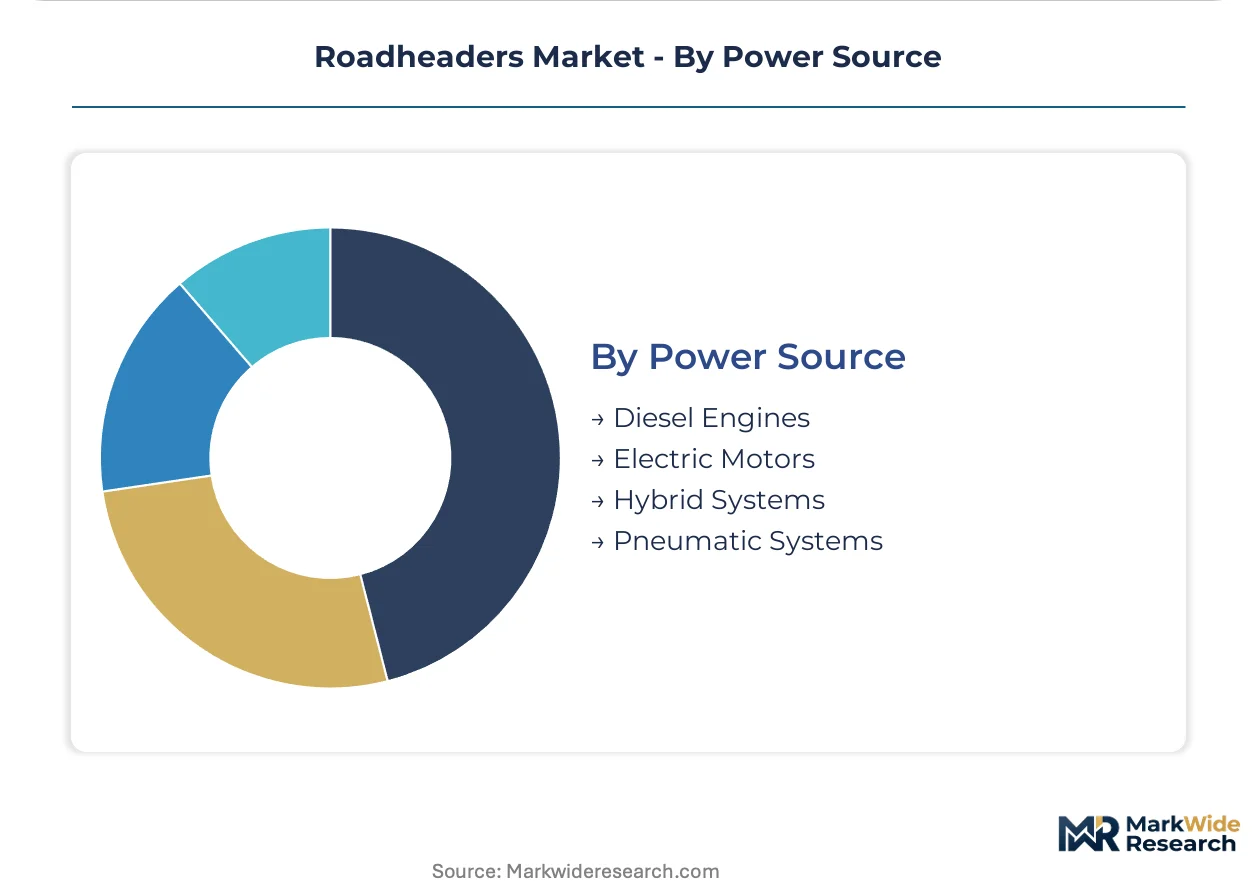
Power Source:
Energy architecture selection now hinges on ventilation economics and regulatory compliance timelines rather than capital cost alone.
- Electric Motors:Trolley-fed or battery-electric architectures eliminate diesel particulate exposure and reduce refrigeration loads in deep mines. Swedish iron ore operations at Kiruna have completed full fleet conversion ahead of EU F-Gas Regulation deadlines.
- Hybrid Systems:Battery-trolley configurations offer diesel-free cutting with cable-free tramming between faces. Nevada gold mines pilot these for intermittent duty cycles in development headings.
- Diesel Engines:MSHA-compliant engines with exhaust aftertreatment retain niche roles where trolley infrastructure is uneconomic. US Appalachian coal retains limited deployments.
- Pneumatic Systems:Compressed air power persists in gassy mines where ignition source control overrides efficiency concerns. Polish and Czech coal operations maintain legacy fleets.
Fastest displacement trajectory: Electric Motors. Steepest expansion: Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's Bowen Basin anchors the world's most concentrated deployment of continuous miners, where labor costs and seam geology favor mechanized extraction over conventional methods. Underground contractors across Australia, China, and Scandinavia are expanding fleet orders to access deeper ore bodies and comply with tightening emissions mandates.
Australia
Western Australian iron ore and gold operations below 1,500 meters generate demand for hard rock cutting machines as conventional raise boring fails at extreme depths. The country's EPA-aligned state regulators enforce diesel particulate exposure limits that accelerate electric roadheader trials. BHP and Rio Tinto operate concentrated fleets across the Pilbara and Kalgoorlie regions where total cost of ownership models internalize ventilation and energy economics.
China
State-owned tunneling contractors in Sichuan and Xinjiang provinces deploy electric-powered roadheaders to connect inland resource basins to coastal manufacturing corridors. The MEE implements dual carbon goals that pressure domestic manufacturers toward electric and hybrid system development for equipment sold into state-owned mining enterprises. China Railway Engineering Equipment Group dominates production clusters in Zhengzhou and supplies the majority of machines for western railway expansion projects.
Sweden
EU Stage V emission standards and the F-Gas Regulation constrain hydraulic fluid and engine choices across Scandinavian tunneling fleets. LKAB's Kiruna iron ore operations have completed full fleet conversion to electric architectures ahead of regulatory deadlines. Sandvik leverages its global service infrastructure to lock in multi-year maintenance agreements across Nordic mining operations.
United States
Nevada gold mines pilot battery-trolley hybrid configurations for intermittent duty cycles in development headings. The EPA enforces MSHA-aligned diesel particulate limits that effectively bar non-compliant engines from underground operations. Appalachian coal retains limited diesel deployments where trolley infrastructure remains uneconomic.
Chile
Copper operations below 1,500 meters depth generate concentrated demand for hard rock miners as hydrostatic pressure renders conventional methods impractical. The national mining regulator enforces ventilation standards that favor electric equipment in deep-level applications. Codelco and Anglo American deploy specialized cutting heads across the Atacama Desert and central mining districts.
Roadheaders Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the roadheader supply base, with integrated manufacturers controlling cutting head metallurgy and hydraulic system production while specialized fabricators focus on frame assembly and regional customization. The market structure consolidates around three strategic archetypes: diversified mining equipment conglomerates with global service networks, state-backed tunneling machinery producers with domestic scale advantages, and regional specialists with deep vertical integration into wear component supply. Dominant competitive moves include captive supply of tungsten carbide inserts and telemetry-based fleet management contracts that capture lifetime equipment value.
Among diversified equipment conglomerates, Sandvik and Komatsu occupy positions defined by aftermarket service infrastructure and multi-site maintenance agreements. Famur anchors the specialist tier with backward integration into cutting head metallurgy and hydraulic system manufacturing. China Railway Engineering Equipment Group exemplifies the state-backed producer archetype, leveraging scale advantages in electric-powered machine production for domestic tunneling projects.
| Leading Market Players |
|---|
| Famur |
| China Railway Engineering Equipment Group |
| Sandvik |
| BBM Group |
| Mitsui Miike Machinery |
| Sany |
| Antraquip |
| Komatsu |
| XCMG |
| Others |
Supply Flow & Price Mechanics
Precision welders capable of brazing tungsten carbide inserts in Upper Silesia and the Ruhr Valley command wage premiums that widen pricing spreads between premium rebuild services and economy parts sourcing. Labor-cost differentials between Central European metallurgy specialists and Asian fabrication centers stratify aftermarket service tiers.
Pricing Analysis
Value-based pricing anchored to machine uptime guarantees dominates procurement for deep-level mining operations. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized rebuild services from independent workshops and gray-market component suppliers. Cost compression in economy tiers intensifies because Chinese manufacturers scale electric motor production for domestic tunneling projects. Mining companies with consolidated fleet scale exhibit lowest price sensitivity, while project-based construction contractors in Turkey and Peru negotiate aggressively on lease rates.
Supply Chain Analysis
Reverse-logistics flows for cutting head refurbishment concentrate rebuild capacity in Poland, Germany, and Sweden where specialized powder metallurgy suppliers cluster. Tungsten carbide insert production draws from Central European sintering facilities, Chinese rare earth processing, and Australian hard rock mining operations. Single-source vulnerability concentrates in premium insert grades where two German suppliers control high-performance formulations. Distribution runs through OEM-authorized service depots for mining customers and rental fleet operators for construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roadheader supply remains constrained by the scarcity of certified rebuild technicians, a bottleneck that sustains pricing power for incumbents with captive service networks.
For Market Incumbents: Lock in multi-year telemetry-based maintenance agreements before fast-charging infrastructure investments erode the economic case for diesel-to-electric conversion delays. Deepen backward integration into cutting head metallurgy to defend margin position against Chinese electric motor producers expanding into Western markets. Prioritize certification investment for EU Stage V compliance to exclude non-compliant competitors from Scandinavian procurement tenders.
For New Entrants and Emerging Players: Mining fleet operators in India's underground coal sector present the most penetrable entry point given national mechanization targets and limited incumbent service infrastructure. Target first-mover advantage in battery-trolley hybrid configurations for development heading applications where intermittent duty cycles suit emerging technology. Partner with regional rental fleet operators to bypass capital-intensive direct sales channels and match contractor cash flow preferences.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized rebuild service providers given telemetry adoption and outcome-based contract proliferation. Long-term viability over the next decade hinges on positioning for electric fleet transition rather than legacy diesel maintenance. Watch battery energy density breakthroughs at the cell chemistry level as the inflection signal that accelerates full electric conversion timelines in deep-level applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cutting Head Metallurgy | Famur's captive tungsten carbide supply insulates margins from insert price volatility. |
| Telemetry-Based Predictive Maintenance Launch | Sandvik's vibration analytics enable outcome-based contracts across Australian iron ore operations. |
| Fast-Charging Infrastructure Partnership | Trolley pantograph investments at Chilean copper mines reshape diesel-to-electric economics. |
| Electric Motor Production Scale-Up | China Railway Engineering Equipment Group dominates state-owned railway tunnel procurement. |
| Specialized Rebuild Technician Certification Program | Polish technical institutes address skill scarcity inflating aftermarket service costs. |
Methodological Framework
Independent corroboration across maintenance directors at Australian longwall operations, procurement leads at Chilean copper mines, and aftermarket service heads at Nordic equipment suppliers underwrites the qualitative findings. Primary interviews with plant engineers, OEM procurement teams, and tunneling contractors combined with secondary validation from customs trade data, MSHA ventilation equivalence filings, and EU Stage V compliance registries. Bottom-up equipment deployment tallies and top-down mining capital expenditure estimates triangulate market sizing.
Comparable historical periods across the projection horizon anchor growth assumptions to proven electric motor adoption curves in underground equipment. Segmentation dimensions modeled include machine type, power source architecture, end-user procurement sophistication, and application geology hardness. CAGRs derive from equipment replacement cycles tied to regulatory compliance deadlines and depth-driven mechanization thresholds. Forecast inputs incorporate battery energy density improvement trajectories and trolley infrastructure investment pipelines.
Caveats apply where lithium-ion cell chemistry breakthroughs or abrupt regulatory timeline accelerations could materially shift the outlook. Forecasts reflect assumptions about ventilation cost economics and emissions compliance enforcement intensity. Material deviation in battery cost curves or deep-level automation integration pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
Pressure Washer Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Case Erectors Market
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
LAMEA Water Pump Market