
 Work Barges Market | 2026-2036
Work Barges Market Size, Share, and Industry Trends Forecast 2026-2036
Work Barges Market Analytics
Charter brokerage networks for inland tank barges is tilting toward direct fleet operator relationships, compressing third-party margins. Kirby Corporation leverages its vertically integrated inland distribution system across the Mississippi River basin. Ingram Marine Group anchors its competitive stance through extensive fleeting and terminal assets near St. Louis and Cincinnati. American Commercial Barge Line competes on long-haul coal and grain movements with dedicated towboat capacity.
Work barges are flat-bottomed, non-self-propelled vessels designed for cargo transport, construction support, or crew accommodation, typically constructed from welded steel plate with loadline certifications dictating draft and freeboard limits; their primary purpose centers on moving bulk commodities and heavy equipment in shallow-water corridors where deep-draft vessels cannot operate. Construction barges dominate capital allocation due to offshore wind turbine foundation demand, while transport barges sustain the volume base through coal, grain, and petrochemical movements along inland waterways. Accommodation barges represent the fastest-growing segment as offshore maintenance campaigns lengthen and crew rotation logistics tighten.
The U.S. Coast Guard enforces Subchapter M inspection standards that mandate towing vessel compliance, while the U.S. Army Corps of Engineers controls lock and dam infrastructure funding that directly shapes barge route economics. EPA ballast water discharge rules and OSHA marine terminal safety protocols further constrain fleet operations and capital deployment timelines. Stakeholders must monitor Corps of Engineers infrastructure appropriations as the decisive variable for throughput capacity expansion on the Ohio and Upper Mississippi systems.
Market Dynamics
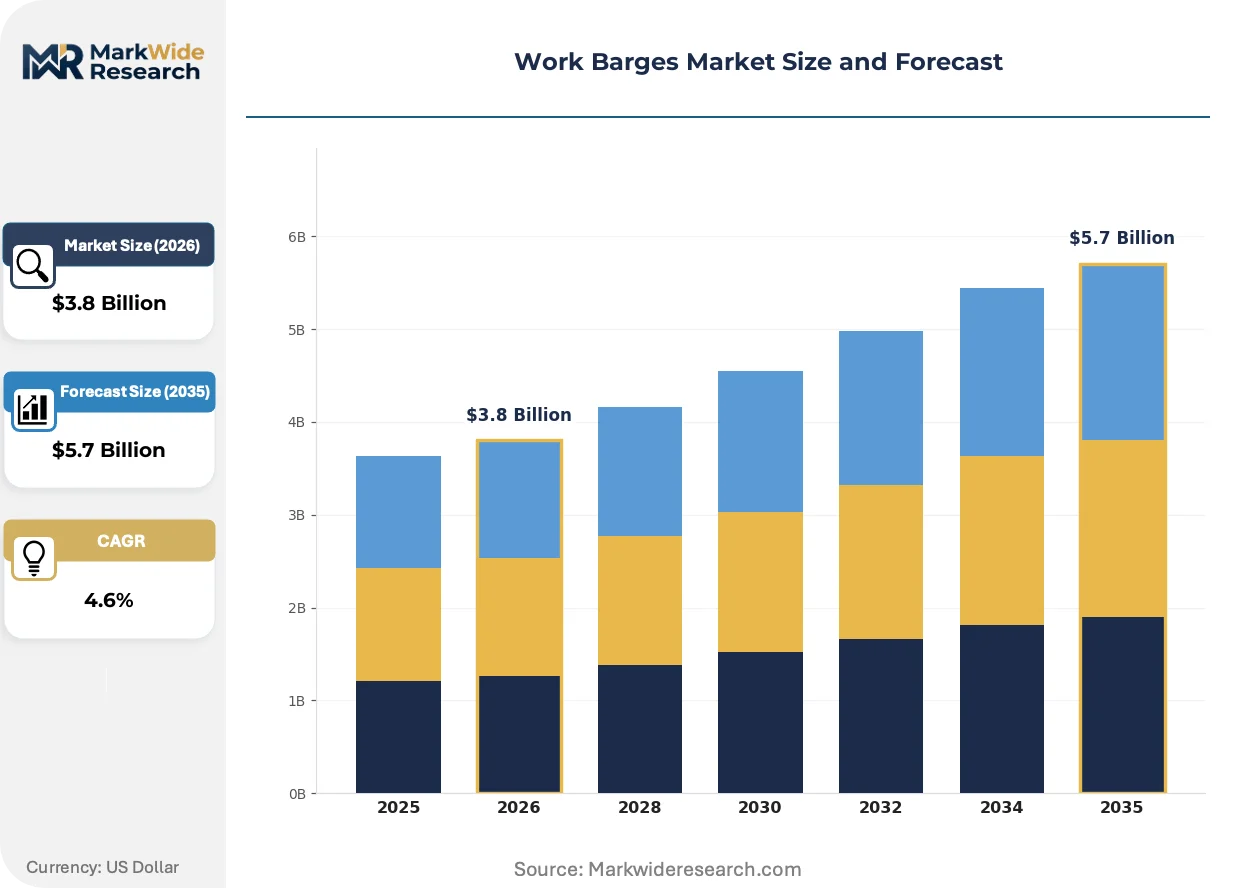
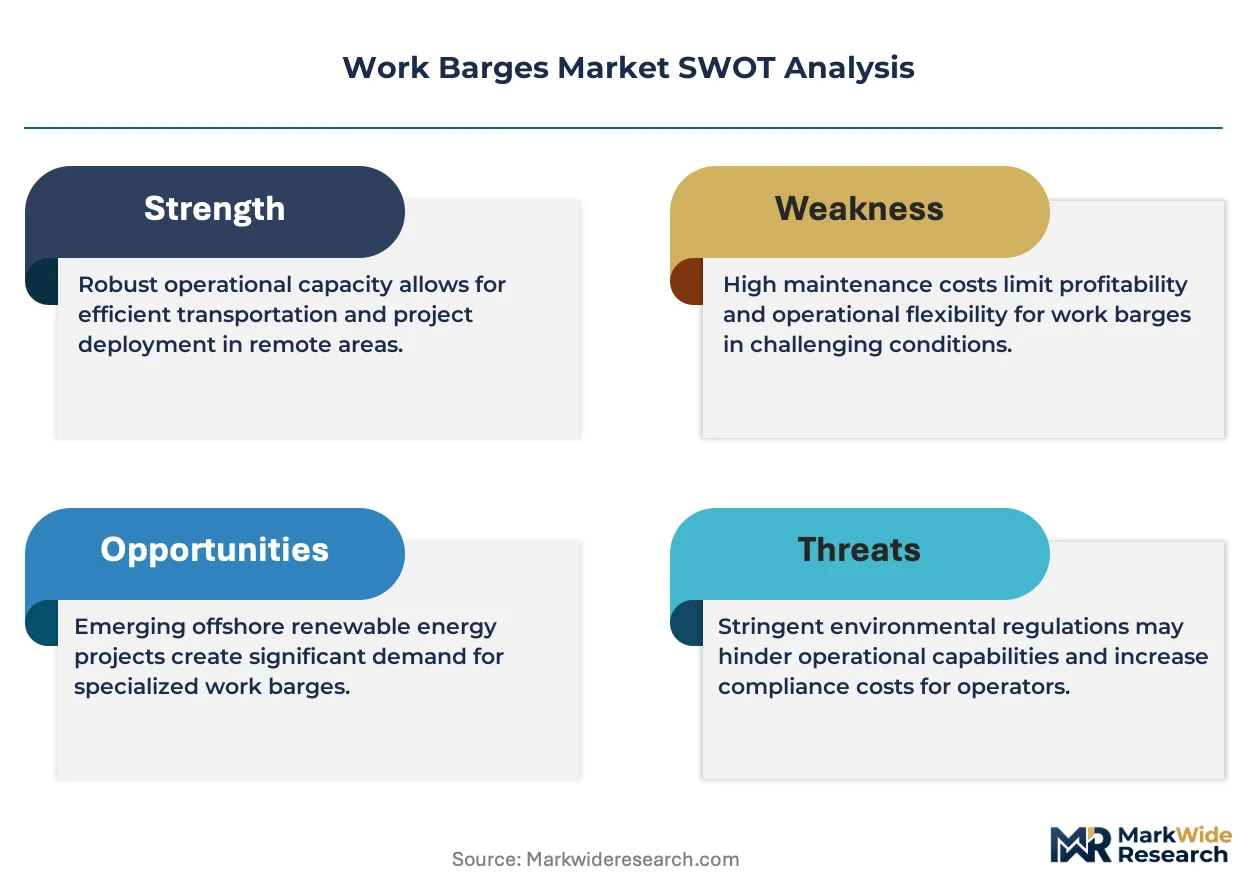
Subchapter M towing vessel regulations are compressing fleet compliance timelines while offshore wind foundation installation schedules pull construction barges toward Northern European waters. This regulatory-demand tension is reallocating capital from inland transport fleets to specialized offshore accommodation and heavy-lift platforms.
Growth Catalysts
- Offshore Wind Foundation Installation:Monopile and jacket foundation deployment in the North Sea and Baltic corridors is absorbing flat-deck construction barge capacity. Developers charter multi-month campaigns that lock in vessel availability years ahead.
- US Subchapter M Compliance Deadlines:The Coast Guard's phased inspection schedule is forcing towing vessel upgrades that extend barge fleet utility through mandatory hull and machinery investments.
- Petrochemical Corridor Expansion:Gulf Coast ethane cracker buildouts between Houston and New Orleans are lengthening towboat-barge unit requirements for NGL and chemical feedstock movements.
Market Restraints
- Steel Plate Input Volatility:Domestic mill pricing for ABS-certified steel plate fluctuates with scrap and energy costs, compressing newbuild margins for welded hull construction.
- Lock Infrastructure Funding Gaps:Corps of Engineers appropriations delays on the Ohio and Upper Mississippi systems constrain throughput expansion and route economics for grain and coal movements.
- Crew Accommodation Standards:OSHA marine terminal safety protocols and Coast Guard inspection regimes extend outfitting timelines for living-quarter barges, stretching capital deployment cycles.
Strategic Opportunities
- US Inland Waterway Electrification Pilots:Battery-electric towboat trials on the Tennessee-Tombigbee Waterway create demand for shore-power-equipped fleeting and terminal infrastructure.
- Decommissioning Support Vessels:North Sea oil platform removal campaigns are converting construction barges to heavy-lift demolition platforms with integrated cutting and waste-processing modules.
- Direct Charter Relationships:Petrochemical shippers are bypassing traditional brokerage layers to contract directly with fleet operators, compressing third-party margins while securing dedicated capacity.
Industry Challenges
- Marine Engineer Talent Pipeline:Subchapter M inspection requirements and diesel-electric propulsion complexity outpace the supply of credentialed marine engineers and towing vessel officers.
- Ballast Water Treatment Retrofits:EPA discharge rules mandate treatment system installations that consume deck space and power allocation on transport barges with limited freeboard.
- Multi-Vessel Campaign Coordination:Offshore wind installation sequences require precise jack-up barge, heavy-lift vessel, and crew transfer unit synchronization that strains project management capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Work Barges Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transport Barges, Construction Barges, Accommodation Barges, Maintenance Barges End User: Oil & Gas, Maritime, Construction, Utilities Deployment: Offshore, Inland, Coastal, Riverine Functionality: Storage, Transport, Installation, Maintenance |
| Companies Covered | Kirby Corporation, Ingram Marine Group, American Commercial Barge Line, Crowley Maritime Corporation, Florida Marine Transporters, Campbell Transportation Company, Magnolia Marine Transport Company, Genesis Energy, Marquette Transportation Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Work Barges Market Evolving Landscape
Digital fleet management systems and modular barge architecture are displacing conventional steel-hull construction and paper-based dispatch operations. These shifts compress operating costs while enabling rapid reconfiguration between cargo, construction, and accommodation roles.
Sensor-integrated hull monitoring is digitizing structural health assessment for aging inland fleets. Barge operators on the Mississippi River system deploy continuous strain-gauge and corrosion-mapping networks that feed predictive maintenance algorithms. This capability extends asset life beyond original design cycles while satisfying Subchapter M inspection documentation requirements.
EPA ballast water discharge standards are forcing treatment technology adoption across coastal and Great Lakes fleets. Vessel operators install ultraviolet and electrochlorination systems that consume cargo space and electrical load capacity. The regulatory burden falls heaviest on smaller transport operators lacking capital reserves for retrofit campaigns.
Charter contracting patterns are consolidating around multi-year direct agreements that displace spot-market brokerage. Petrochemical producers along the Houston Ship Channel negotiate dedicated towboat-barge units with priority dispatch guarantees. This behavioral shift compresses third-party broker margins while locking fleet capacity into contracted lanes rather than open market availability.
Work Barges Market Segmentation
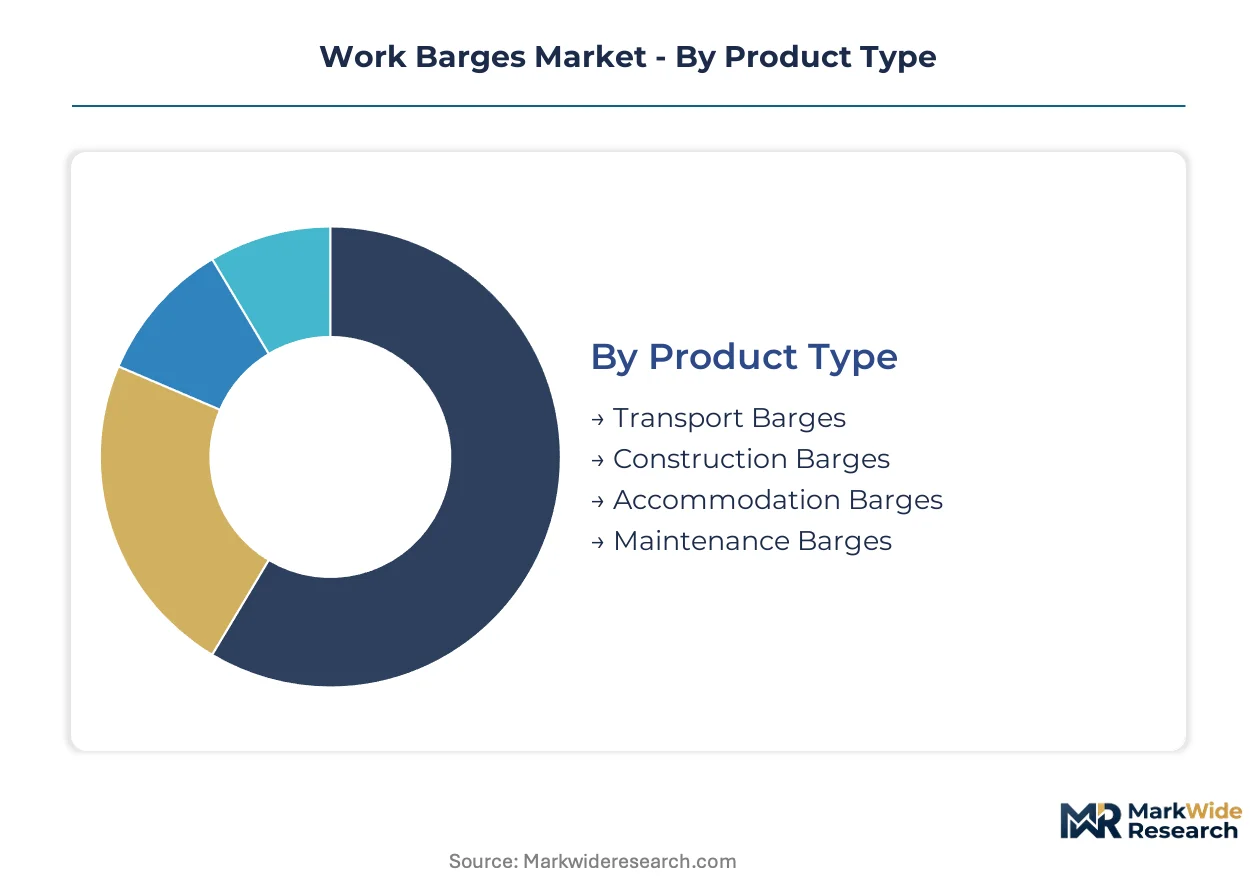
Work barge segmentation reveals how vessel specialization aligns with capital intensity and regulatory exposure. Each dimension—product configuration, end-use vertical, operating environment, and operational role—carries distinct margin profiles and compliance burdens that reshape fleet investment priorities.
Product Type:
Mature welded-steel platforms dominate capital deployment, while emerging modular designs gain traction for rapid reconfiguration between roles.
- Construction Barges:Flat-deck steel platforms with reinforced load-bearing structures support heavy-lift crane operations and pile-driving equipment. Offshore wind foundation installation in the North Sea and Baltic Sea corridors absorbs multi-year charter commitments for monopile and jacket deployment campaigns.
- Accommodation Barges:Integrated living-quarter modules with marine-grade habitability systems house rotating maintenance crews. Extended offshore decommissioning schedules and wind farm service campaigns in Northern European waters tighten crew logistics and extend charter durations.
- Transport Barges:Standard hopper or tank configurations move bulk commodities along inland corridors.
- Maintenance Barges:Outfitted with workshops and spare parts storage for field repair operations.
Construction barges handle the majority of throughput; accommodation barges are expanding most quickly on share.
End User:
Cost tier separation runs from capital-intensive offshore energy to price-sensitive inland commodity movements.
- Oil & Gas:Platform installation, subsea pipeline support, and decommissioning operations demand heavy-lift certified vessels with dynamic positioning. Gulf of Mexico and North Sea producers contract dedicated fleets with priority dispatch guarantees for emergency response and scheduled maintenance windows.
- Construction:Bridge foundation work, marine civil engineering, and port expansion projects require modular deck configurations for pile hammers and concrete batching plants. Coastal infrastructure programs in the Netherlands and Germany absorb seasonal barge capacity for lock and dam rehabilitation.
- Maritime:Port dredging support, ship repair platforms, and pilot station facilities.
- Utilities:Power transmission cable laying and offshore substation installation.
Oil & Gas commands premium day rates; construction is gaining share fastest through infrastructure stimulus programs.
Deployment:
Geographic scope dictates regulatory jurisdiction and crew certification requirements across operating environments.
- Offshore:Operations beyond territorial limits fall under international maritime conventions and flag-state inspection regimes. North Sea wind farm zones and Gulf of Mexico oil fields require vessels with enhanced stability criteria and helicopter landing facilities for crew transfer.
- Inland:River and canal networks governed by national waterway authorities and lock dimensions constrain vessel beam and draft. The Mississippi River system and Rhine-Main-Danube corridor move bulk grain, coal, and petrochemical feedstocks under US Coast Guard Subchapter M or EU river inspection standards.
- Coastal:Nearshore operations within territorial waters face overlapping port state and environmental regulations.
- Riverine:Shallow-draft corridors with seasonal draft restrictions limit cargo capacity.
Inland deployment carries the highest vessel count; offshore shows the steepest expansion trajectory on charter rates.
Functionality:
Application focus separates commodity logistics from specialized marine construction services.
- Installation:Heavy-lift and precision positioning capabilities for wind turbine foundations, bridge piers, and subsea infrastructure. North Sea developers charter jack-up barges and flat-deck platforms years ahead for monopile driving and transition piece mating operations.
- Maintenance:Workshop-equipped vessels with crane access and parts storage support offshore platform upkeep and wind turbine service campaigns. Extended rotation schedules in the German Bight and UK sector tighten demand for hotel-style accommodation integration.
- Transport:Bulk cargo movement with minimal outfitting beyond cargo holds and pumping systems.
- Storage:Stationary or moored capacity for fuel, water, or construction materials staging.
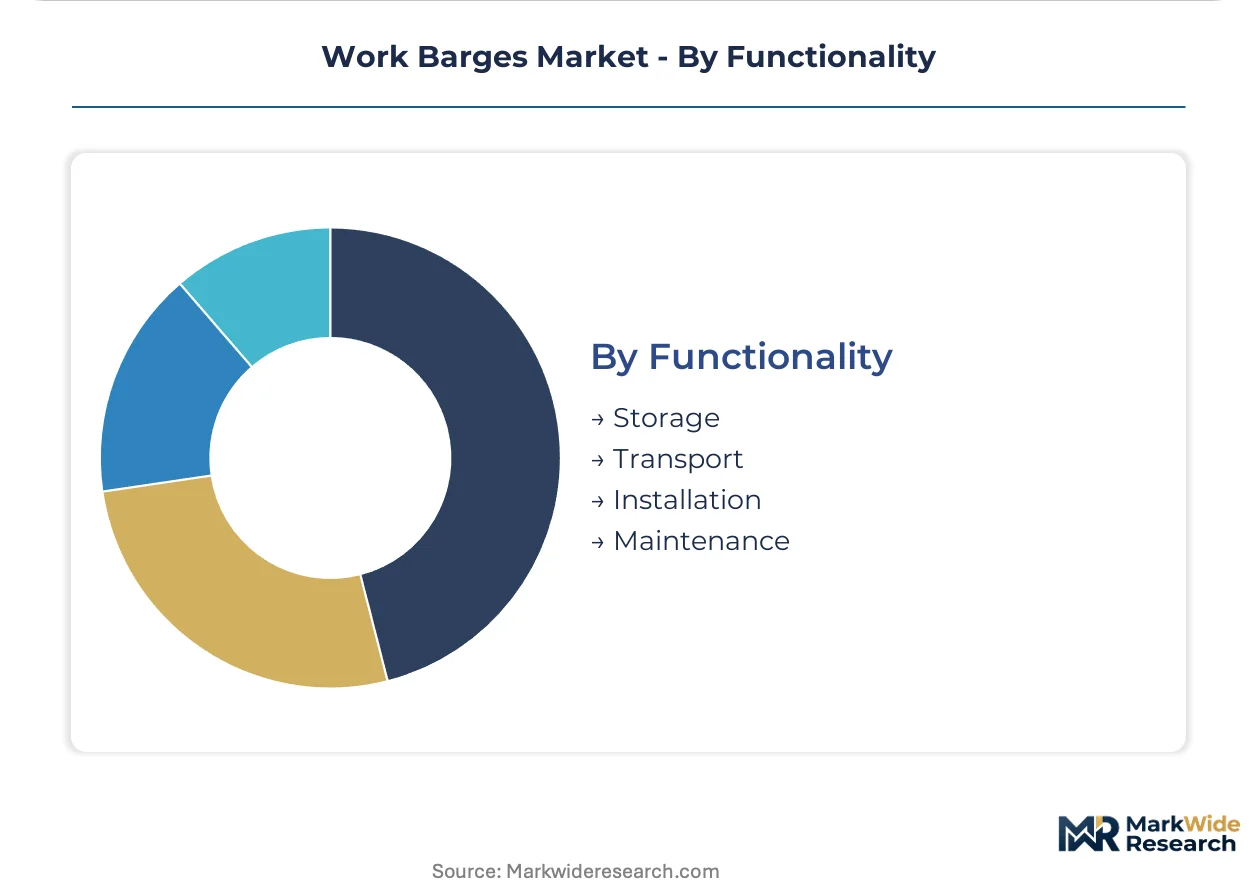
Installation absorbs the largest capital commitments; maintenance is climbing the fastest on fleet reconfiguration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax credit extensions for offshore wind deployment in the United States are redirecting construction barge capacity toward Atlantic Coast foundation projects. Germany's accelerated coal phase-out is shrinking Rhine coal movements while expanding barge demand for wind turbine component logistics.
United States
Gulf Coast ethane cracker expansions between Houston and New Orleans are absorbing tank barge capacity for NGL feedstock movements. The U.S. Coast Guard's Subchapter M inspection deadlines are forcing towing vessel upgrades that extend fleet utility through mandatory hull investments. Kirby Corporation anchors Mississippi River operations through vertically integrated fleeting terminals near St. Louis.
Germany
North Sea offshore wind installation campaigns in the German Bight are locking in multi-year construction barge charters for monopile foundation work. The EU Green Deal's renewable targets are accelerating decommissioning schedules for aging North Sea oil platforms. Port clusters in Bremerhaven and Cuxhaven are converting heavy-lift barges for turbine component staging.
United Kingdom
Dogger Bank wind farm phases are pulling flat-deck construction barges from European spot markets into dedicated UK sector charters. The Maritime and Coastguard Agency's updated towing vessel codes are extending inspection documentation requirements. Aberdeen harbor operators are reconfiguring accommodation barges for extended offshore maintenance rotations.
Netherlands
IJmuiden sea lock expansion projects are demanding modular construction barges for civil engineering support in North Sea access channels. Dutch environmental regulations on inland waterway emissions are piloting shore-power infrastructure at Rotterdam terminals. Dredging contractors in the Rhine-Meuse delta are deploying sensor-integrated hull monitoring on aging transport fleets.
China
Yangtze River Delta offshore wind installation is absorbing domestic construction barge production for monopile and jacket foundation deployment. The Ministry of Ecology and Environment's vessel emission standards are tightening engine retrofit timelines for inland fleets. Shanghai port authorities are expanding heavy-lift barge capacity for offshore substation integration.
Work Barges Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated fleet operators with captive fleeting infrastructure and direct charter relationships with petrochemical shippers. Strategic archetypes separate inland commodity transport specialists from offshore construction platform providers and integrated logistics conglomerates. Dominant competitive moves include backward integration into terminal assets and multi-year dedicated capacity contracts that displace spot-market brokerage layers.
Among U.S.-based integrated operators, Kirby Corporation and Ingram Marine Group exemplify the vertically integrated archetype through Mississippi River basin coverage and St. Louis/Cincinnati terminal concentration. American Commercial Barge Line occupies a position within the long-haul bulk transport tier. These three anchors demonstrate how fleet scale and captive infrastructure separate tier-one operators from regional competitors dependent on third-party fleeting.
| Leading Market Players |
|---|
| Kirby Corporation |
| Ingram Marine Group |
| American Commercial Barge Line |
| Crowley Maritime Corporation |
| Florida Marine Transporters |
| Campbell Transportation Company |
| Magnolia Marine Transport Company |
| Genesis Energy |
| Marquette Transportation Company |
| Others |
Value Network & Pricing Analysis
Domestic ABS-certified steel plate production concentrates in U.S. Great Lakes mill corridors, tethering newbuild construction margins to scrap metal and energy input cycles while downstream charter rates stratify around vessel specialization tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Subchapter M-compliant vessels with enhanced stability certification from legacy inland transport units and spot-market brokerage arrangements. Price differentiation hinges on Coast Guard inspection tier and charter duration scale, with multi-year direct contracts commanding rate premiums over volatile spot assignments. Cost compression in standard-tier transport barges is intensifying because petrochemical shippers are bypassing intermediary layers to secure dedicated capacity. Inland grain and coal operators exhibit the highest price sensitivity due to thin commodity margins, while offshore wind developers demonstrate minimal sensitivity given project finance structures that absorb vessel day rates as fixed costs.
Supply Chain Analysis
Upstream feedstock flows draw from U.S. domestic steel mills, South Korean shipyard component suppliers, and German marine equipment manufacturers for dynamic positioning and habitability systems. Raw material dependencies center on ABS-grade steel plate, diesel-electric propulsion packages, and modular living-quarter prefabrication. Single-source vulnerability concentrates in specialized jack-up leg fabrication and heavy-lift crane integration, where European and Asian fabricators hold dominant technical positions. Distribution runs through vertically integrated fleet operators with captive fleeting terminals rather than fragmented third-party brokerage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Work barge market fragmentation creates carve-out opportunities as regulatory compliance timelines and offshore wind installation schedules pull capital toward divergent vessel archetypes, opening niches for specialized operators.
For Market Incumbents: Insulate core fleet utility through backward integration into St. Louis and Cincinnati terminal assets that lock in fleeting control over Mississippi River basin corridors. Accelerate Subchapter M inspection documentation capabilities to capture towing vessel upgrade demand before compliance deadlines compress available yard capacity. Prioritize certification investment in dynamic positioning and helicopter landing facilities to defend premium-rate positioning against emerging offshore specialists. For New Entrants and Emerging Players: Build out modular accommodation barge offerings targeting North Sea decommissioning campaigns and extended offshore wind maintenance rotations, where crew logistics complexity outpaces incumbent reconfiguration speed. Target the German Bight and UK Dogger Bank zones as the most penetrable geographies given charter duration extension and limited local hotel-vessel supply. Pursue direct contracting relationships with offshore wind developers as the primary go-to-market angle, displacing traditional spot-market brokerage layers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap fleet operators with captive terminal infrastructure and documented Subchapter M compliance progress, positioned for consolidation as regulatory costs force smaller competitors toward exit. Long-term viability across the analysis window rests on exposure to contracted revenue streams rather than spot-market dependence. Watch Corps of Engineers appropriation signals for Ohio and Upper Mississippi lock rehabilitation as the inflection indicator for inland throughput expansion and route economics improvement.| Strategic Initiative | Industry Significance |
|---|---|
| Subchapter M Compliance Investment | Coast Guard inspection deadlines force hull upgrades that extend asset utility and capture regulatory-driven demand. |
| Offshore Wind Charter Lock-In | Multi-year foundation installation campaigns in North Sea corridors absorb construction barge capacity years ahead. |
| Terminal Infrastructure Acquisition | St. Louis and Cincinnati fleeting assets anchor vertically integrated positioning along Mississippi River corridors. |
| Modular Accommodation Conversion | Extended decommissioning schedules in German Bight tighten crew rotation logistics and lengthen charter durations. |
| Direct Shipper Relationship Development | Petrochemical producers bypass brokerage layers to secure dedicated towboat-barge units with priority dispatch guarantees. |
Research Methodology
Desk research of U.S. Coast Guard regulatory filings, Corps of Engineers infrastructure appropriations records, and offshore wind project development databases preceded structured interviews with fleet operations directors, marine terminal managers, shipyard procurement leads, and petrochemical logistics coordinators. Primary intelligence combined with secondary validation across SEC 10-K disclosures, customs trade data, and EU maritime safety agency records. Bottom-up vessel inventory counts triangulated against top-down charter market value estimates.
Assumptions held fixed include Subchapter M inspection deadline schedules, offshore wind foundation installation timelines, and Corps of Engineers funding authorization levels; variables stress-tested encompass steel plate pricing volatility, crew certification pipeline constraints, and ballast water treatment retrofit adoption curves. Segmentation modeling spanned product configuration, end-use vertical, deployment environment, and operational functionality dimensions. CAGRs derived from historical fleet growth patterns applied against announced project development pipelines and regulatory-driven replacement demand.
Stress conditions across steel input cost bands, charter rate sensitivity thresholds, and infrastructure funding delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions that may revise with unanticipated regulatory amendments or macroeconomic shifts affecting commodity transport volumes. Cross-checking against Corps of Engineers Waterborne Commerce Statistics and offshore wind installation vessel tracking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market