
 Europe Ground Penetrating Radar Market | 2026-2036
Europe Ground Penetrating Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ground Penetrating Radar Market Insights
Silicon carbide antenna substrates is decoupling GPR hardware costs from legacy ceramic pricing, enabling tighter margin structures across the value chain. Hilti AG leverages its construction channel density to dominate handheld unit distribution in German-speaking markets. IDS GeoRadar s.r.l. anchors its position through deep specialization in 3D imaging arrays for infrastructure monitoring. Guideline Geo AB competes on software-integrated workflows that reduce field interpretation time for survey contractors.
Ground Penetrating Radar denotes a geophysical method employing electromagnetic radiation in the microwave band to detect reflected signals from subsurface structures, typically operating between 10 MHz and 2.6 GHz depending on required penetration depth and resolution trade-offs. The technology serves primary industrial purposes in non-destructive evaluation of buried utilities, pavement layers, and geological formations without excavation disruption. Vehicle-mounted systems lead current revenue contribution due to highway and rail corridor survey volumes across European member states. Handheld configurations represent the fastest-growing product category, driven by contractor accessibility and reduced training barriers in construction end-use. Data Processing Software captures disproportionate margin pools as vendors shift toward recurring licensing models and cloud-based interpretation platforms.
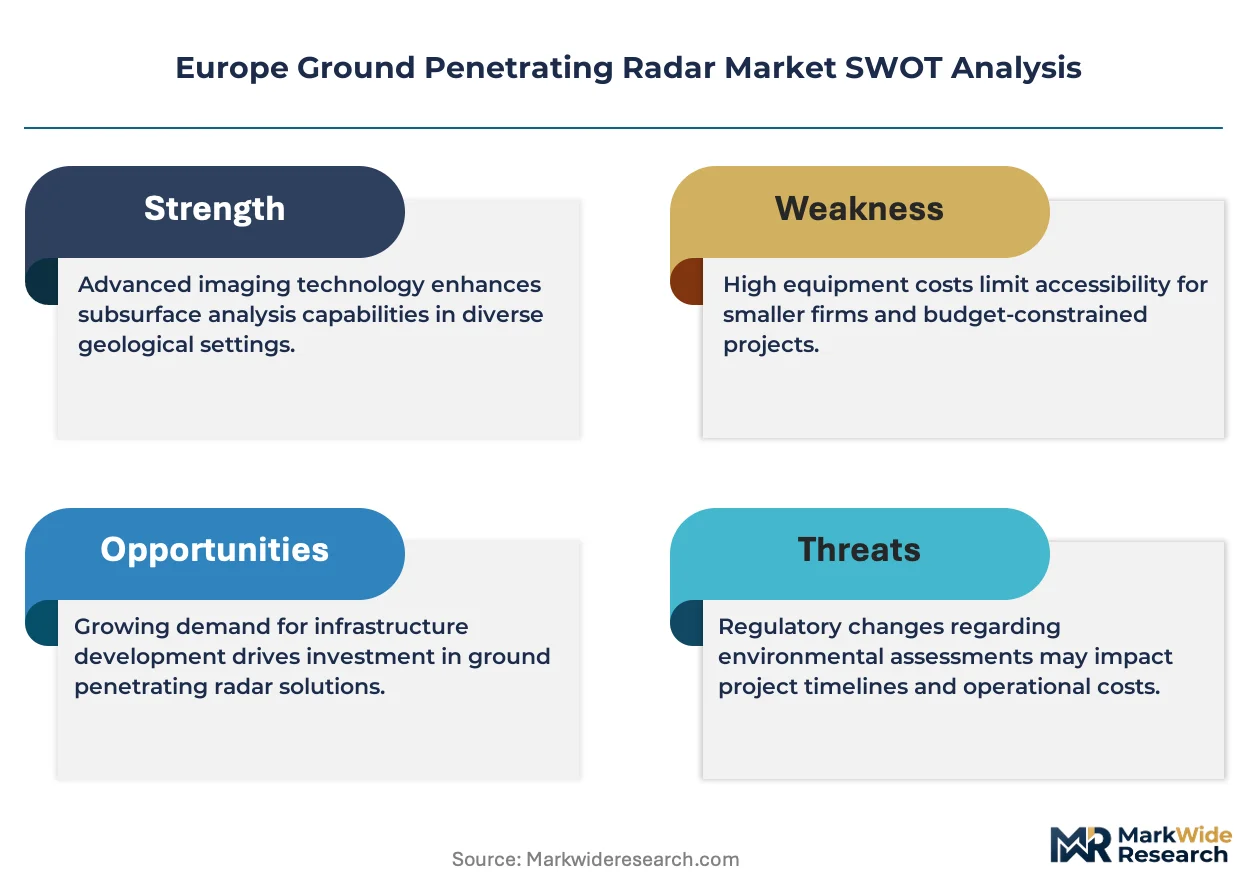
CE marking under the EU Radio Equipment Directive governs electromagnetic emissions compliance for GPR transmitters, while REACH constraints affect antenna substrate material selection across manufacturers. ECHA substance restrictions are pushing vendors toward halogen-free PCB laminates and recycled aluminum chassis to maintain market access. The EU AI Act's risk classification framework will increasingly shape automated subsurface interpretation tools that embed machine learning detection algorithms. Stakeholders must monitor evolving harmonized standards for drone-integrated airborne GPR operations as unmanned aerial system regulations crystallize across member states.
Market Dynamics
Silicon carbide antenna substrates are compressing hardware costs while EU Green Deal subsurface mandates tighten compliance thresholds across infrastructure agencies. This dual pressure is redistributing margin pools from equipment toward software and service layers.
Growth Catalysts
- EU Green Deal mandates:Subsurface investigation requirements for environmental compliance are accelerating utility mapping procurement across German and French infrastructure agencies.
- Urban renewal corridors:Tunneling and brownfield redevelopment projects in Germany's Ruhr region and Netherlands port zones are generating sustained vehicle-mounted system demand.
- Silicon carbide substrates:This material transition is decoupling antenna costs from legacy ceramic pricing structures, enabling tighter margin capture across hardware vendors.
Market Restraints
- REACH substance restrictions:ECHA constraints on halogenated compounds are forcing antenna substrate material requalification, extending product development cycles.
- Electromagnetic spectrum congestion:CE marking under the EU Radio Equipment Directive imposes emission limits that constrain transmitter power and penetration depth trade-offs.
- Interpretation skill scarcity:Qualified geophysicists capable of manual GPR data validation remain concentrated in Northern European survey firms, limiting service scalability.
Strategic Opportunities
- Drone-integrated airborne GPR:Unmanned aerial system regulatory crystallization across member states is opening corridor-scale survey applications for rail and pipeline operators.
- Cloud-based interpretation platforms:Survey contractors in Poland and Czechia are adopting subscription software workflows that reduce field interpretation time.
- EU AI Act risk classification:Automated subsurface detection algorithms face emerging compliance frameworks that first-movers can shape through regulator engagement.
Industry Challenges
- Cross-border certification fragmentation:Harmonized standards for drone-integrated operations remain incomplete, forcing vendors to maintain multiple national compliance dossiers.
- Legacy system integration:Municipal utility databases in Southern Europe lack standardized data formats, complicating 3D imaging array deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ground Penetrating Radar Market |
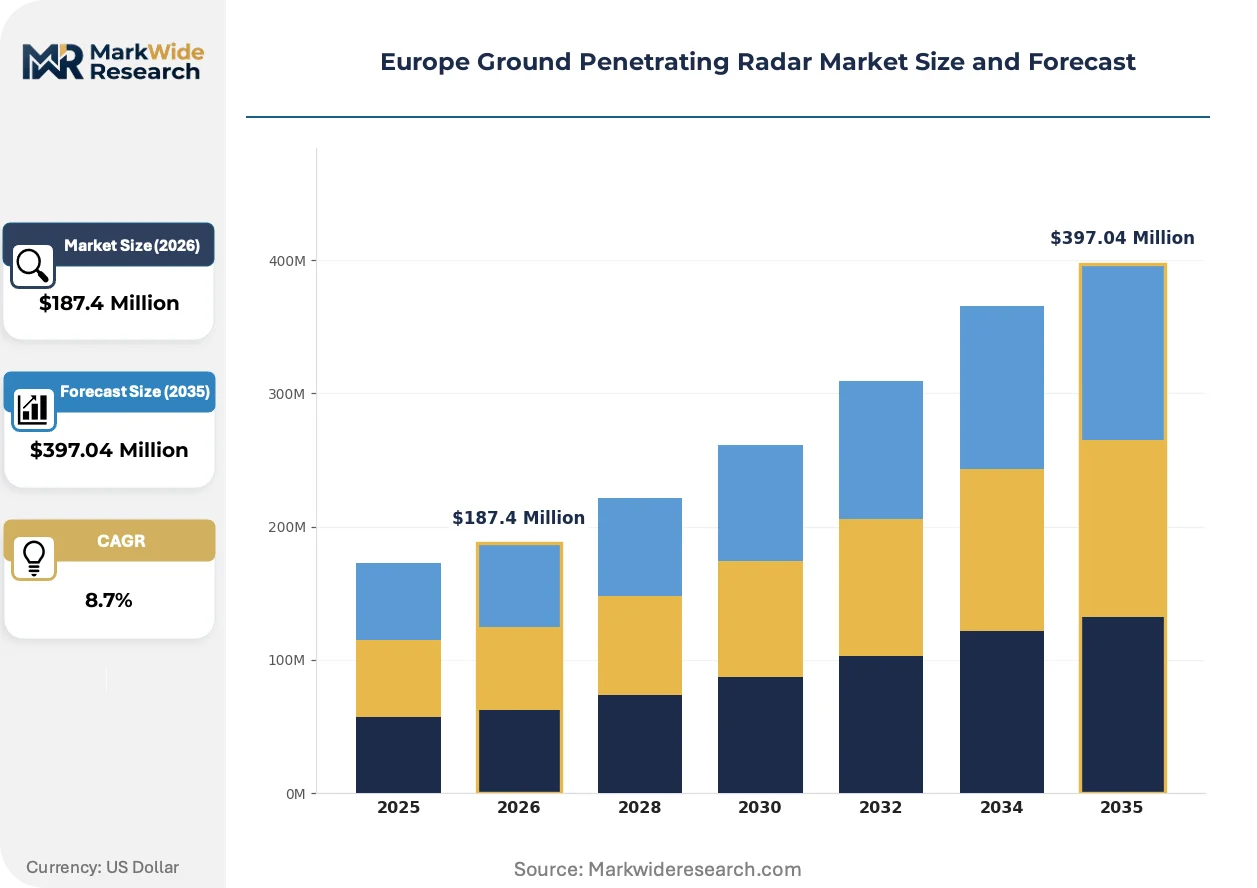
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Vehicle-Mounted, Ground-Mounted, Airborne End User: Construction, Archaeology, Environmental, Law Enforcement Application: Utility Mapping, Structural Analysis, Forensics, Research Technology: 2D Imaging, 3D Imaging, Data Processing Software, Signal Analysis |
| Companies Covered | Hilti AG, Guideline Geo AB, IDS GeoRadar s.r.l., Geoscanners AB, Geophysical Survey Systems, Inc., Radiodetection Ltd., PipeHawk plc, Penetradar Corporation, Chemring Group PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ground Penetrating Radar Market Trends and Innovations
Machine learning interpretation tools and silicon carbide hardware platforms are converging to compress survey cycle times while regulatory frameworks reshape automated detection compliance requirements.
Multi-channel 3D imaging arrays are unifying subsurface data capture across utility, geological, and structural assessment applications. German rail corridor operators are deploying these systems at accelerating replacement cycles for pavement and ballast evaluation. This unification is collapsing the historical segmentation between highway survey contractors and tunneling specialists into integrated infrastructure monitoring service providers.
REACH constraints on halogen-free PCB laminates are mandating antenna substrate material transitions across European manufacturers. ECHA substance restrictions are disqualifying legacy epoxy formulations from new product introductions. Vendors are responding by qualifying recycled aluminum chassis and ceramic-filled polymer laminates to maintain CE marking compliance.
Recurring licensing models for data processing software are displacing perpetual license sales among survey contractors in France and Benelux. Cloud-based interpretation platforms with automated feature extraction are capturing preference share from desktop-installed solutions. This shift concentrates most visibly among mid-sized infrastructure monitoring firms seeking to reduce capital deployment in field equipment.
Europe Ground Penetrating Radar Market Segmentation
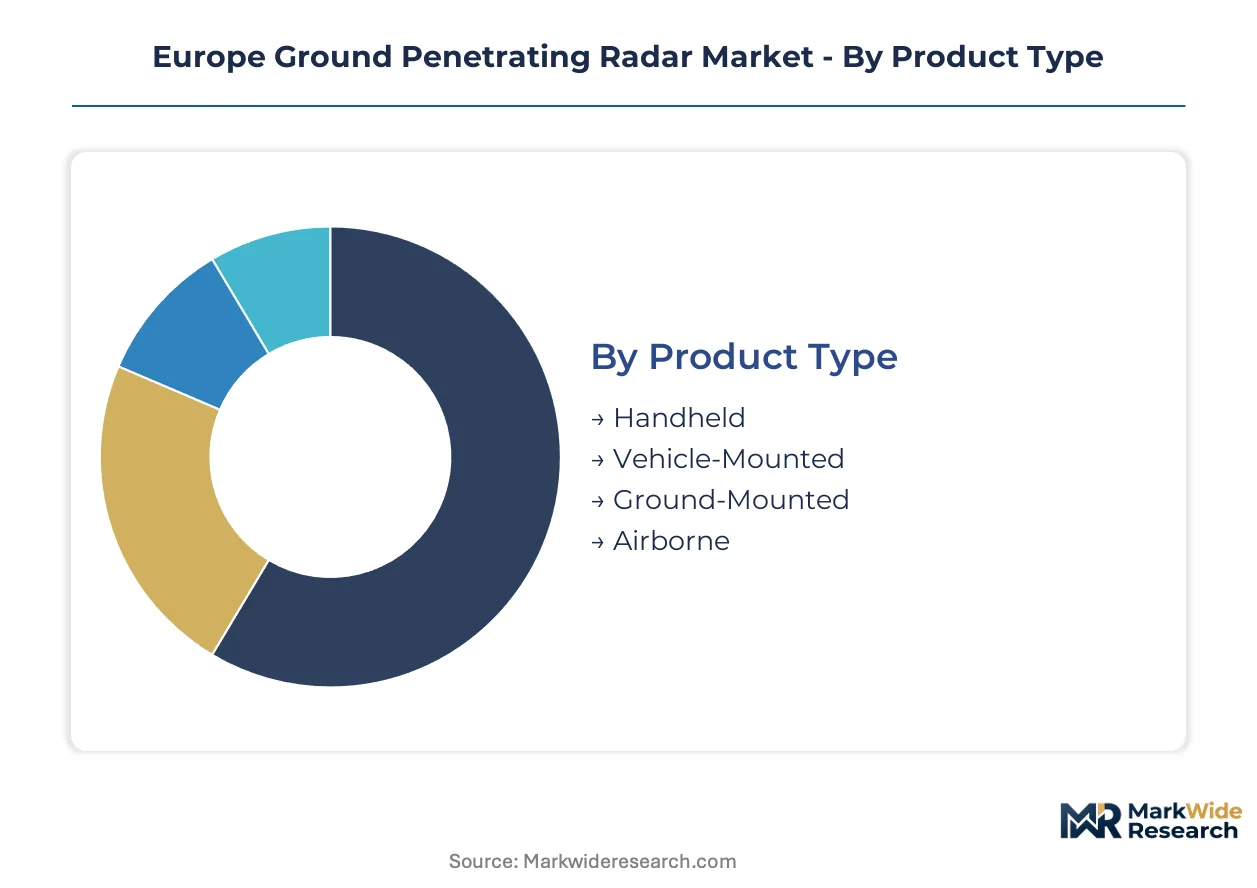
Ground penetrating radar systems fragment across deployment configurations, end-use specializations, and analytical capabilities that reshape procurement patterns across European infrastructure agencies. Each segmentation axis reveals distinct margin structures, certification requirements, and technology adoption curves that vendors must navigate to capture value.
Product Type:
Standardization dominates at the vehicle-mounted tier while handheld configurations demand extensive field customization for contractor workflows.
- Vehicle-Mounted:These systems integrate multi-channel antenna arrays on survey vehicles for highway and rail corridor mapping at highway speeds. German federal transport agencies and Netherlands infrastructure operators deploy these units for pavement layer assessment and ballast evaluation across renewal corridors. Most installed capacity flows through vehicle-mounted systems. Expansion is steepest in handheld configurations.
- Handheld:Portable single-antenna units weighing under 5 kilograms enable utility location on congested construction sites without vehicle access. French and Benelux contractors favor these systems for urban renewal projects where space constraints prevent vehicle deployment, with silicon carbide substrates reducing unit costs and training barriers.
- Ground-Mounted:Tripod-stabilized arrays for stationary high-resolution scans at archaeological and forensic investigation sites.
- Airborne:Drone-integrated platforms for pipeline and rail corridor surveys across inaccessible terrain.
Vehicle-mounted systems absorb the majority of capital deployment, while handheld units gain preference share fastest among mid-sized contractors.
End User:
Public infrastructure agencies concentrate procurement volume while private contractors fragment across specialized service tiers.
- Construction:Civil engineering contractors deploy GPR for pre-excavation utility clearance and concrete structural assessment. German tunneling consortia and Dutch port redevelopment projects generate sustained demand for 3D imaging arrays that integrate with BIM workflows.
- Environmental:Remediation consultants map contaminated plumes and landfill boundaries under EU Green Deal investigation mandates. French environmental agencies and German state environmental offices procure vehicle-mounted systems for brownfield site characterization prior to redevelopment approvals.
- Archaeology:Academic and heritage institutions conduct non-destructive subsurface survey at protected sites.
- Law Enforcement:Police forensic units locate clandestine graves and buried evidence with court-admissible documentation protocols.
Construction end-users command the largest equipment budgets. Environmental compliance investigations are climbing the fastest.
Application:
Recurring revenue potential concentrates in interpretation software while hardware sales dominate one-time utility mapping engagements.
- Utility Mapping:Location of buried electrical, water, and telecommunications infrastructure prior to excavation. German municipalities and French regional infrastructure agencies mandate pre-construction surveys under worker safety regulations, with 3D arrays reducing false-positive rates in dense urban subsurface environments.
- Structural Analysis:Bridge deck and pavement layer evaluation for maintenance prioritization. Austrian and Swiss alpine tunnel operators deploy vehicle-mounted systems for continuous structural monitoring, with data processing software enabling predictive maintenance scheduling.
- Forensics:Subsurface evidence location for criminal investigation support.
- Research:Academic geophysical survey and technology validation studies.
Utility mapping absorbs the majority of system operating hours. Structural analysis applications are expanding most quickly as predictive maintenance budgets grow.
Technology:
Hardware commoditization pressures are shifting vendor investment toward software-defined interpretation and automated feature extraction.
- Data Processing Software:Cloud-based platforms with subscription licensing enable automated subsurface interpretation and collaborative project workflows. Polish and Czech survey contractors adopt these tools to reduce field geophysicist staffing requirements, with EU AI Act compliance emerging as a vendor differentiation axis.
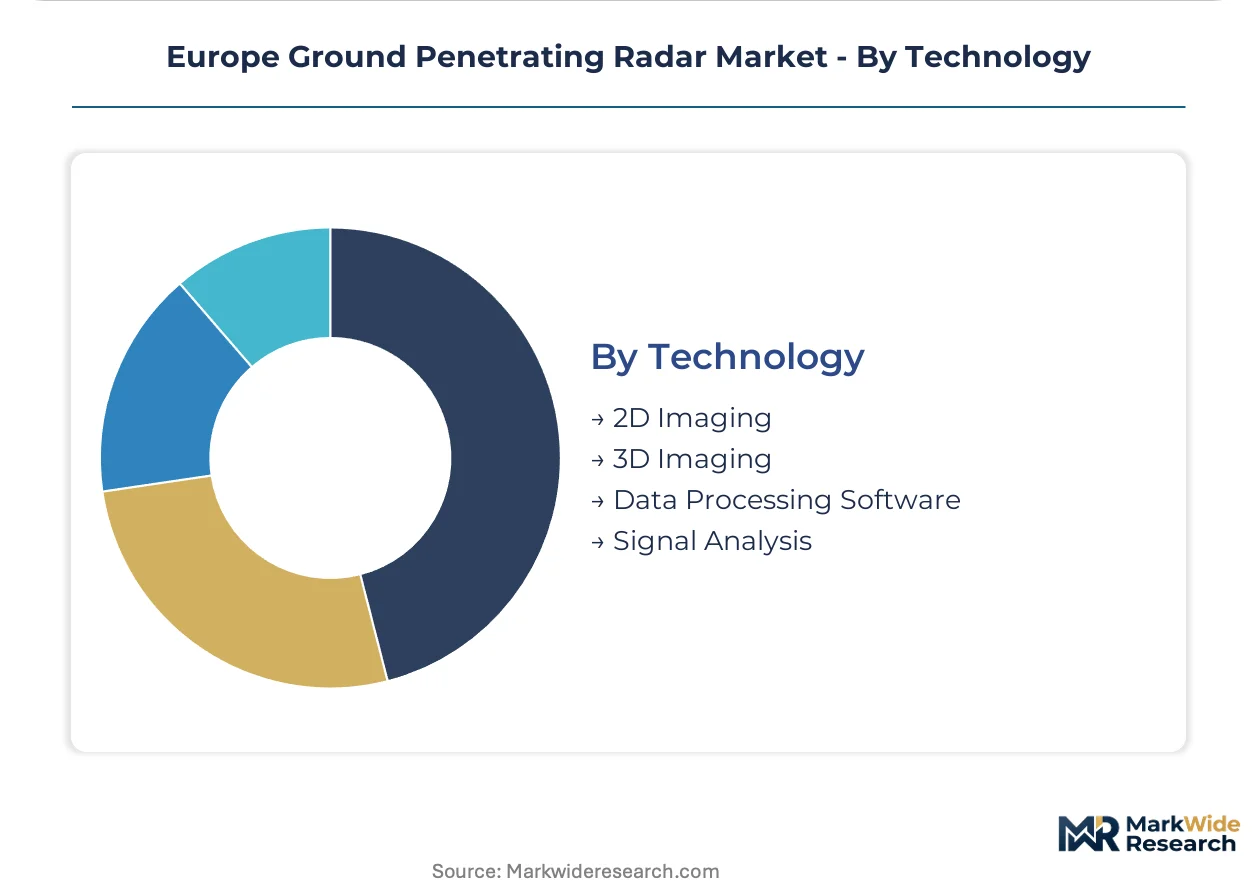
- 3D Imaging:Multi-channel antenna arrays capture volumetric subsurface data for complex utility and geological environments. German rail operators and Netherlands port authorities deploy these systems for unified infrastructure monitoring across previously segmented highway and tunneling applications.
- 2D Imaging:Single-profile scanning for linear utility location and basic geological assessment.
- Signal Analysis:Raw data processing tools for specialized geophysical interpretation.
3D imaging hardware commands the highest unit economics. Data processing software is gaining share fastest as recurring revenue models displace perpetual licenses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr urban renewal corridors and tunneling clusters anchor European GPR procurement volume. Federal transport agencies across member states are mandating pre-construction subsurface surveys under worker safety frameworks. CE marking compliance and EU Green Deal investigation requirements are reshaping vendor certification priorities.
Germany
Ruhr region brownfield redevelopment and alpine tunnel maintenance drive vehicle-mounted system deployment. Federal Ministry of Transport mandates under worker protection regulations require utility mapping prior to excavation permits. Munich and Stuttgart rail operators deploy 3D imaging arrays for continuous ballast evaluation across renewal corridors.
France
Regional infrastructure agencies in Île-de-France mandate pre-construction GPR surveys for dense urban subsurface environments. EU Green Deal environmental compliance investigations accelerate procurement for contaminated site characterization. Lyon and Marseille port authorities deploy multi-channel arrays for unified infrastructure monitoring.
Netherlands
Rotterdam and Amsterdam port zone redevelopment generates sustained demand for vehicle-mounted pavement assessment systems. REACH constraints on halogenated compounds force antenna substrate requalification among Dutch survey contractors. Randstad metropolitan clusters concentrate handheld unit adoption for congested construction sites.
United Kingdom
Transport for London and Network Rail corridor surveys absorb substantial vehicle-mounted capacity for utility and geological assessment. HSE excavation safety regulations mandate subsurface investigation before ground disturbance. Birmingham and Manchester urban renewal projects drive contractor procurement of portable single-antenna configurations.
Poland
Infrastructure modernization programs and EU cohesion fund projects accelerate utility mapping adoption among Polish survey contractors. Cloud-based interpretation platforms with subscription licensing reduce field geophysicist staffing requirements. Warsaw and Kraków municipal agencies deploy handheld systems for pre-excavation clearance in dense historic districts.
Europe Ground Penetrating Radar Market Competitive Landscape
Global majors compete with regional champions across distribution channel density and software-integrated workflows. The vendor base fragments between construction equipment conglomerates, specialized geophysical instrument makers, and survey service providers with captive hardware development. Three archetypes dominate: channel-dominant equipment suppliers, deep-specialization imaging array developers, and software-centric workflow integrators. Competitive moves concentrate on construction channel partnerships and recurring licensing model transitions.
Among the named European participants, Hilti AG exemplifies channel-dominant positioning through construction equipment distribution networks. IDS GeoRadar s.r.l. and Guideline Geo AB occupy specialist tier positions, with the former representing deep hardware specialization and the latter anchoring software-integrated service workflows. These three collectively illustrate the competitive tension between equipment scale and analytical capability differentiation.
| Leading Market Players |
|---|
| Hilti AG |
| Guideline Geo AB |
| IDS GeoRadar s.r.l. |
| Geoscanners AB |
| Geophysical Survey Systems, Inc. |
| Radiodetection Ltd. |
| PipeHawk plc |
| Penetradar Corporation |
| Chemring Group PLC |
| Others |
Pricing and Supply Chain Analysis
Qualified geophysicists concentrated in Northern European survey firms command wage premiums that compress pricing spreads between premium and economy-tier GPR service contracts. Labor-cost differentials between German specialist crews and Polish contractor teams drive three-tier pricing stratification across utility mapping engagements.
Pricing Analysis
Input-cost pass-through from silicon carbide substrate adoption is compressing hardware pricing while amplifying software margin capture. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked vehicle-mounted arrays from handheld contractor units and refurbished legacy systems. Pricing pressure stems from REACH-mandated material requalification cycles extending vendor R&D recovery timelines. Mid-sized Polish and Czech survey contractors exhibit highest price sensitivity, while German federal transport agencies prioritize certification compliance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German rail operators and Netherlands port authorities, while construction equipment distributors serve fragmented contractor procurement. Component supply concentrates in Germany for antenna array fabrication, China for silicon carbide substrate sourcing, and Sweden for cloud-based interpretation platform development. Raw material dependencies span halogen-free PCB laminates, recycled aluminum chassis, and ceramic-filled polymer substrates. Single-source vulnerability in ECHA-compliant substrate formulations threatens production continuity. Distribution runs through specialized geophysical instrument dealers and captive service-provider networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory compliance costs in Germany and France subsidize margin expansion for vendors with Polish and Czechia-based interpretation service delivery.
For Market Incumbents: Lock in construction channel density through exclusive distribution agreements with Hilti-equivalent equipment networks before silicon carbide cost compression commoditizes handheld hardware. Defend margin pools by accelerating recurring licensing transitions in data processing software, as cloud-based platforms face EU AI Act compliance barriers that favor established vendors with regulator relationships. For New Entrants and Emerging Players: Drone-integrated airborne GPR arrays offer a technology-first wedge into corridor-scale rail and pipeline survey applications where harmonized UAS standards remain incomplete. Target Polish survey contractors adopting subscription software workflows to reduce field geophysicist staffing. White-space exists in automated subsurface detection algorithms for EU AI Act risk classification engagement. For Investors and Strategic Acquirers: Valuations sit cheapest among software-centric workflow integrators with cloud-based interpretation platforms and established CE marking compliance dossiers. Long-term viability hinges on recurring revenue model transitions displacing perpetual license sales. Acquisition target archetype: mid-sized infrastructure monitoring firms in Benelux with integrated 3D imaging array deployment capabilities. Watch drone-integrated GPR regulatory crystallization across EU member states as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Hardware Transition | Decouples antenna costs from legacy ceramic pricing structures across German-speaking markets. |
| Cloud-Based Interpretation Platform Launch | Captures recurring revenue from Polish and Czech survey contractors reducing field staffing. |
| EU AI Act Compliance Investment | Shapes automated detection algorithm standards before risk classification frameworks crystallize. |
| Drone-Integrated Airborne GPR Development | Opens corridor-scale rail and pipeline applications as UAS regulations harmonize. |
| REACH-Compliant Material Requalification | Maintains CE marking access as ECHA halogen restrictions disqualify legacy epoxy formulations. |
Research Methodology
Coverage spans Germany, France, Netherlands, United Kingdom, and Poland, with primary inputs from each market cluster combining executive interviews with infrastructure agency procurement officers, survey contractor operations managers, geophysical instrument R&D directors, and construction equipment distribution channel heads. Secondary validation draws from EU Green Deal implementation documents, ECHA substance restriction databases, CE marking harmonized standards, and national transport agency procurement records. Bottom-up equipment shipment analysis triangulates against top-down infrastructure spending forecasts.
Granularity-level modeling disaggregates revenue across vehicle-mounted, handheld, ground-mounted, and airborne deployment configurations; construction, environmental, archaeology, and law enforcement end-use sectors; and data processing software, 3D imaging, 2D imaging, and signal analysis technology tiers. CAGRs derive from segment-level growth rate synthesis applied across the projection horizon. Industry-specific inputs include EU cohesion fund disbursement trajectories, tunneling project pipelines, and REACH compliance transition timelines.
The model holds under stable EU regulatory enforcement and continued infrastructure modernization funding; deviation in ECHA substance restriction acceleration or UAS harmonization delays would shift hardware and software adoption curves. Forecasts reflect documented assumptions regarding silicon carbide cost compression rates and cloud platform subscription conversion. Periodic stress-testing of base assumptions against regulatory implementation pace and municipal utility database standardization progress is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Turkey Construction Equipment Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Industrial Grout Pumps Market
Construction Equipment
Global Excavator Attachments Market