
 Decanter Centrifuge Market | 2026-2036
Decanter Centrifuge Market Size, Share, and Industry Trends Forecast 2026-2036
Decanter Centrifuge Market Intelligence
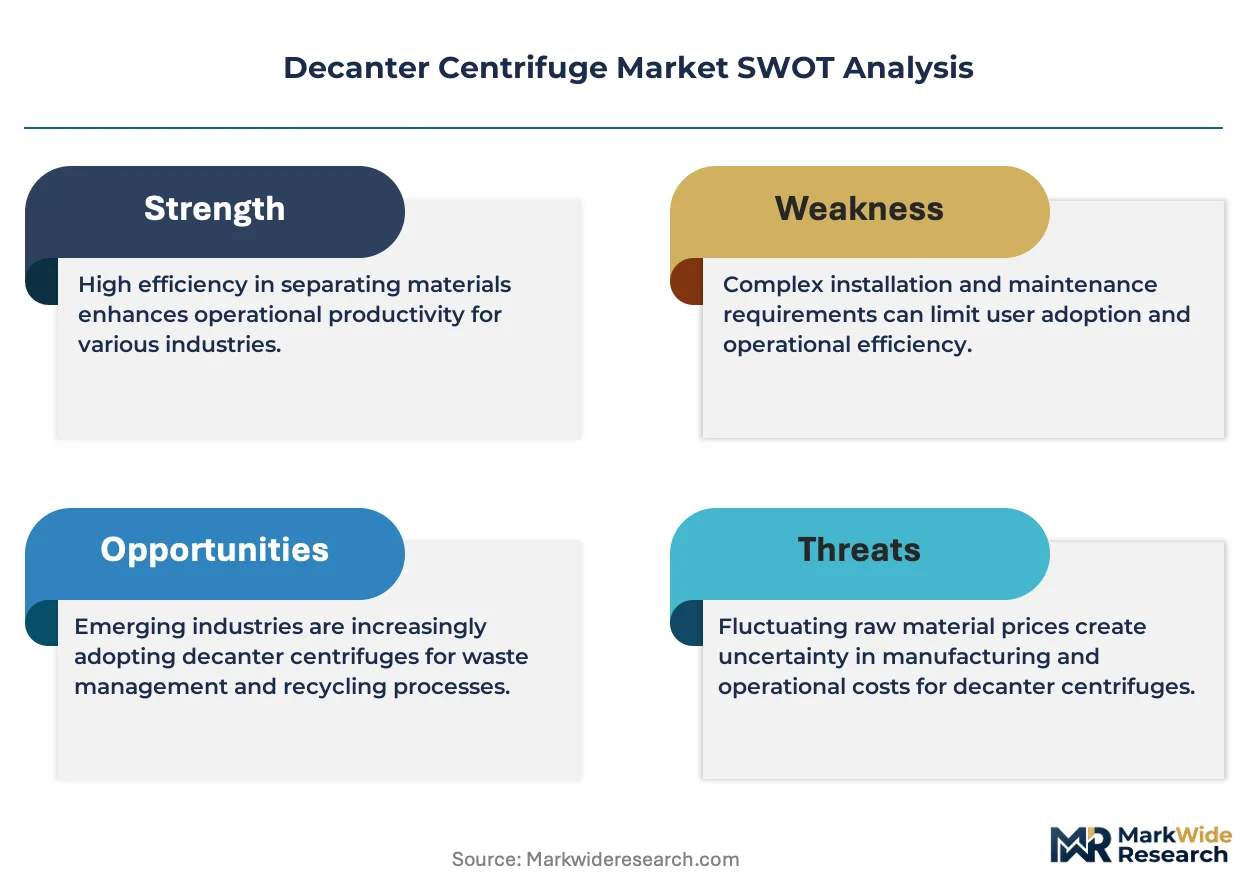
The EU Green Deal is hardening discharge requirements for industrial effluent across European processing corridors. Alfa Laval leverages its Scandinavian engineering base to sustain high-G force decanter lines for biopharmaceutical sludge. ANDRITZ AG anchors Central European demand through integrated dewatering systems bundled with service contracts. GEA Group Aktiengesellschaft differentiates via hygienic-design decanters purpose-built for dairy and food plant effluent.
A decanter centrifuge separates solids from liquids through continuous rotational sedimentation, typically operating at bowl speeds between 1,600 and 4,000 RPM with differential scroll conveyors discharging dewatered cake. Continuous decanter configurations dominate municipal and industrial installations where uninterrupted throughput outweighs batch flexibility. Food processing applications represent the fastest-expanding demand pool as manufacturers face escalating disposal costs for organic slurry. Oil recovery decanters retain mature margin pools in North American shale basins, though growth has flattened relative to wastewater and food segments.
EPA effluent limitation guidelines tighten permissible solids in wastewater discharge, compelling US municipalities toward higher-capacity decanter retrofits. REACH chemical registration requirements in Europe restrict certain bowl alloys and coatings, reshaping supplier material specifications. ISO 1940 balance standards govern high-speed rotor assembly tolerances, creating certification barriers for new entrants. Stakeholders must weigh bowl alloy selection against evolving chemical compliance regimes while monitoring municipal capex cycles for replacement timing.
Market Dynamics
Municipal wastewater treatment plants face accelerating replacement cycles as EPA effluent limitation guidelines tighten permissible solids thresholds, forcing capital deployment toward higher-capacity bowl assemblies and precision scroll conveyor systems.
Growth Catalysts
- EU Green Deal industrial emissions directives:European processing facilities must upgrade sludge management infrastructure to meet hardened discharge requirements, accelerating equipment replacement timelines across Germany's chemical corridor and Dutch food processing clusters.
- Shale basin oil recovery operations:North American energy producers deploy high-torque decanter configurations for drilling mud dewatering, sustaining aftermarket parts demand despite flat unit expansion in mature basins.
- Food manufacturing slurry volumes:Dairy and plant-based protein processors generate escalating organic waste streams, creating installed base expansion in Wisconsin, California, and the Netherlands where disposal cost pressures concentrate.
Market Restraints
- Specialized alloy supply concentration:Duplex stainless steel and super-duplex bowl materials depend on Scandinavian and German metallurgical suppliers, exposing lead times to regional energy cost volatility.
- REACH chemical registration barriers:ECHA restrictions on certain hard-facing coatings and weld consumables force reformulation of corrosion-resistant bowl surfaces, extending qualification timelines for new equipment variants.
- High-G force rotor balancing infrastructure:ISO 1940 certification requirements for high-speed assembly tolerances limit field service capabilities to specialized workshops, constraining aftermarket geographic reach.
Strategic Opportunities
- India municipal sanitation expansion:Jawaharlal Nehru National Urban Renewal Mission allocations target sewage treatment capacity in tier-2 cities, opening greenfield decanter deployment for sludge thickening applications.
- Biopharmaceutical cell harvest integration:Single-use bioreactor scaling creates demand for hygienic-design decanters with CIP/SIP capability, bridging upstream fermentation and downstream purification workflows.
- China dual carbon goals:MEE enforcement of industrial wastewater recycling mandates drives retrofit demand in Jiangsu and Zhejiang chemical parks, favoring energy-efficient bowl drive configurations.
Industry Challenges
- Scroll conveyor wear specialist scarcity:Hardfacing repair of tungsten carbide tiles requires certified welders with centrifuge-specific expertise, creating service bottlenecks in remote municipal installations.
- Legacy PLC integration complexity:Brownfield plants operate decades-old control architectures, complicating retrofit of variable frequency drives and automated differential speed adjustment systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decanter Centrifuge Market |
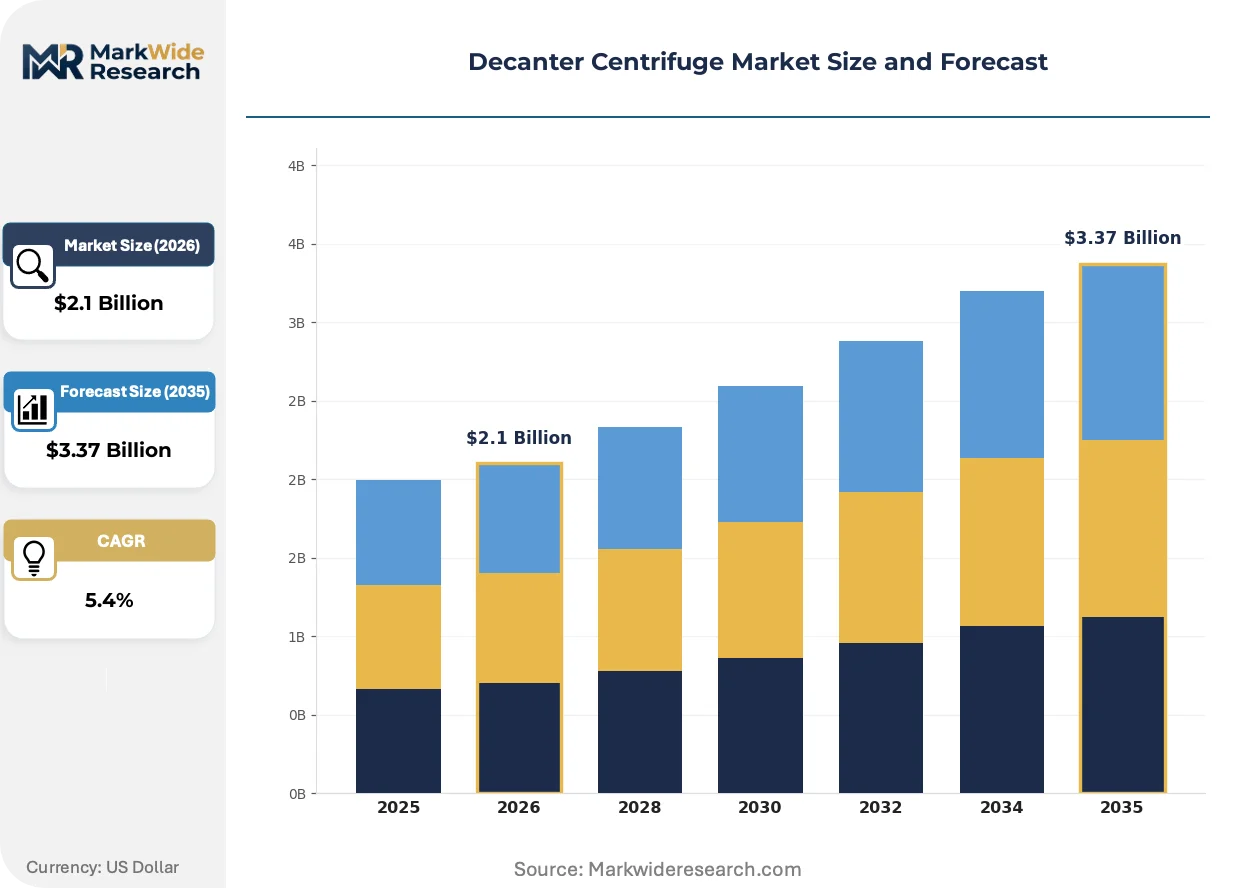
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Decanter, Continuous Decanter, Portable Decanter, Decanting System Application: Wastewater Treatment, Oil Recovery, Food Processing, Chemical Processing End User: Municipalities, Food Manufacturers, Oil & Gas Industries, Chemical Companies Installation: On-site Installation, Off-site Installation, Mobile Units, Fixed Units |
| Companies Covered | Flottweg SE, FLSmidth A/S, Alfa Laval, Centrisys, IHI Corporation, GEA Group Aktiengesellschaft, SPX FLOW Inc., Pieralisi Group S.p.A., ANDRITZ AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decanter Centrifuge Market Strategic Shifts & Innovations
Electrification of bowl drive systems and predictive maintenance architectures are compressing operating cost structures while regulatory chemical restrictions reshape material specifications across supplier portfolios.
Direct-drive permanent magnet motors are overtaking traditional gearbox-and-belt configurations in municipal installations above 500 cubic meters per hour throughput. Dutch water authorities specify these systems for Amsterdam-Rijnland and Hollandse Delta treatment networks, eliminating mechanical transmission losses and enabling precise torque control during fluctuating feed solids loading. The technology is overtaking legacy drive architectures by reducing maintenance intervals from quarterly to annual schedules.
REACH Annex XVII restrictions on chromium(VI) compounds in surface treatments are compelling bowl manufacturers to transition toward thermal spray ceramic coatings and laser-clad corrosion barriers. German chemical processors in Ludwigshafen and Leverkusen now require coating documentation traceable to ECHA-registered formulations. Food-grade decanter lines face the steepest compliance burden, as dairy and beverage plants demand both regulatory conformity and FDA-equivalent surface finish validation.
Performance-based service contracting is displacing traditional time-and-materials maintenance arrangements among North American industrial users. Large food processors in California's Central Valley and Texas Panhandle chemical facilities now specify guaranteed cake dryness percentages and availability uptime in multi-year agreements. Equipment vendors absorb operational risk through remote vibration monitoring and predictive bearing replacement, shifting buyer preference toward integrated service bundling over component procurement.
Decanter Centrifuge Market Segmentation
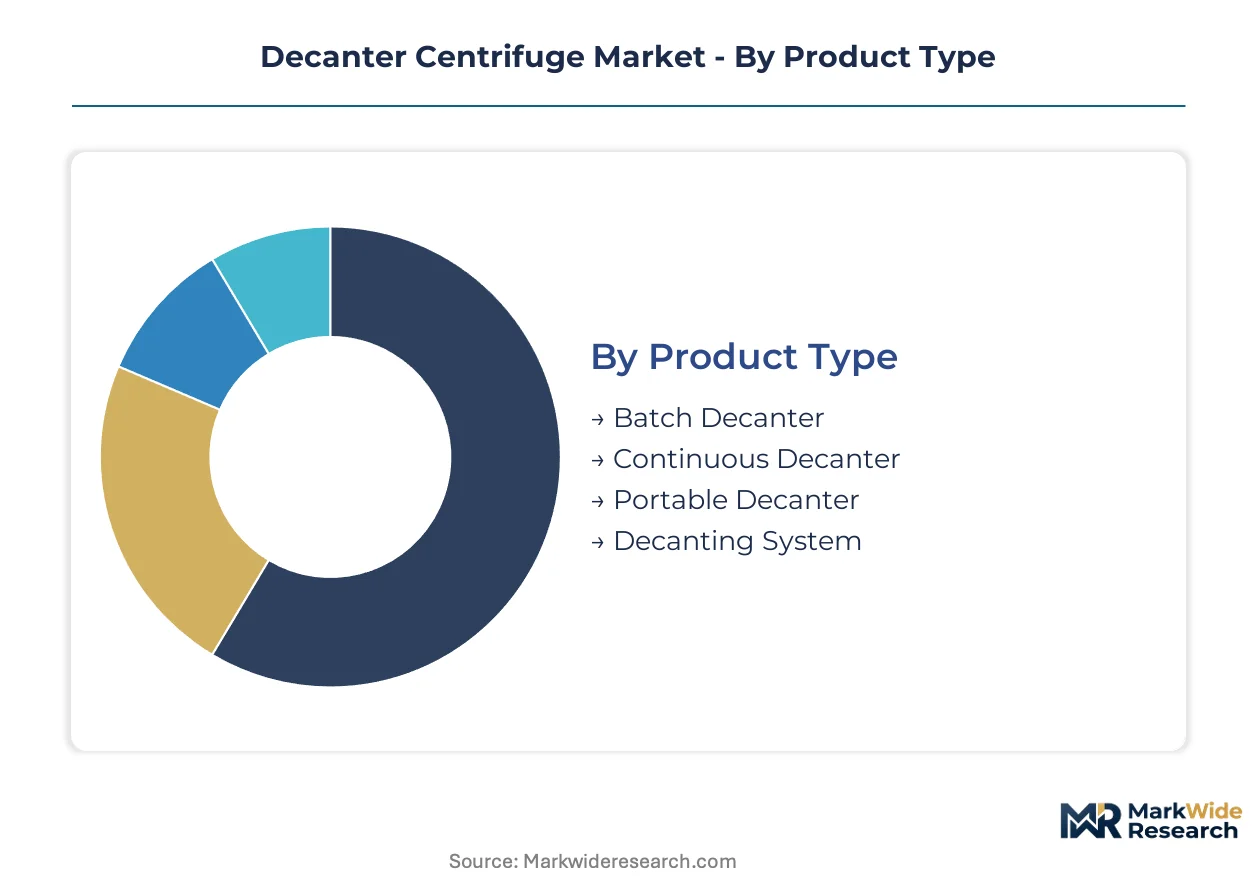
Decanter centrifuge procurement patterns diverge sharply between high-volume municipal installations and precision-engineered industrial configurations. Understanding these segment boundaries clarifies where bowl specification, drive architecture, and service contracting models concentrate commercial value.
Product Type:
Continuous decanters command the premium tier through uninterrupted throughput architectures, while batch configurations serve cost-sensitive applications requiring flexibility over volume.
- Continuous Decanter:Bowl speeds between 1,600 and 4,000 RPM with differential scroll conveyors enable uninterrupted solids discharge. Amsterdam-Rijnland and Hollandse Delta treatment networks in the Netherlands specify direct-drive permanent magnet configurations for installations above 500 cubic meters per hour throughput, eliminating mechanical transmission losses and compressing maintenance intervals from quarterly to annual schedules.
- Batch Decanter:Cyclic operation suits pharmaceutical and specialty chemical applications where product isolation and CIP/SIP validation take precedence over throughput velocity. Biopharmaceutical cell harvest operations in Scandinavian clusters favor these systems for bridging upstream fermentation and downstream purification workflows with single-use bioreactor integration.
- Portable Decanter:Trailer-mounted configurations serve remote shale basin drilling mud dewatering in North American energy corridors.
- Decanting System:Integrated skids combine feed pumps, polymer dosing, and cake conveyance for greenfield municipal deployments.
Mature deployment sits with continuous configurations in established wastewater networks. Newer deployment is concentrated in portable units for distributed oilfield services and modular food processing expansions.
Application:
Regulatory discharge thresholds determine specification intensity, with effluent compliance costs driving replacement cycles faster in wastewater than in mature oil recovery basins.
- Wastewater Treatment:EPA effluent limitation guidelines tighten permissible solids thresholds, compelling US municipalities toward higher-capacity bowl assemblies and precision scroll conveyor retrofits. Germany's chemical corridor deploys cluster-scale sludge management upgrades to meet EU Green Deal industrial emissions directives, accelerating equipment replacement timelines across Ludwigshafen and Leverkusen processing facilities.
- Food Processing:Dairy and plant-based protein processors in Wisconsin, California, and the Netherlands generate escalating organic waste streams where disposal cost pressures concentrate demand. REACH Annex XVII restrictions on chromium(VI) surface treatments impose the steepest compliance burden here, as dairy and beverage plants require both ECHA-registered coating documentation and FDA-equivalent surface finish validation.
- Oil Recovery:High-torque configurations sustain aftermarket parts demand in North American shale basins despite flat unit expansion.
- Chemical Processing:Corrosion-resistant bowl alloys from Scandinavian and German metallurgical suppliers serve aggressive process streams.
Performance-based service contracting now dominates food processing and wastewater procurement, with guaranteed cake dryness percentages and availability uptime specified in multi-year agreements.
End User:
Municipal capex cycles follow federal funding authorizations, while industrial users prioritize operational expenditure reduction through predictive maintenance architectures.
- Municipalities:Jawaharlal Nehru National Urban Renewal Mission allocations target sewage treatment capacity in India's tier-2 cities, opening greenfield decanter deployment for sludge thickening applications. Brownfield plants in legacy US networks operate decades-old control architectures, complicating retrofit of variable frequency drives and automated differential speed adjustment systems.
- Food Manufacturers:Large processors in California's Central Valley now specify integrated service bundling over component procurement, with equipment vendors absorbing operational risk through remote vibration monitoring and predictive bearing replacement.
- Oil & Gas Industries:Drilling contractors in Texas Panhandle chemical facilities favor guaranteed uptime arrangements amid volatile hydrocarbon price environments.
- Chemical Companies:Jiangsu and Zhejiang chemical parks in China drive retrofit demand under MEE enforcement of industrial wastewater recycling mandates, favoring energy-efficient bowl drive configurations aligned with dual carbon goals.
Procurement sophistication varies: municipalities follow structured tender protocols, while chemical and food processors negotiate outcome-based performance guarantees.
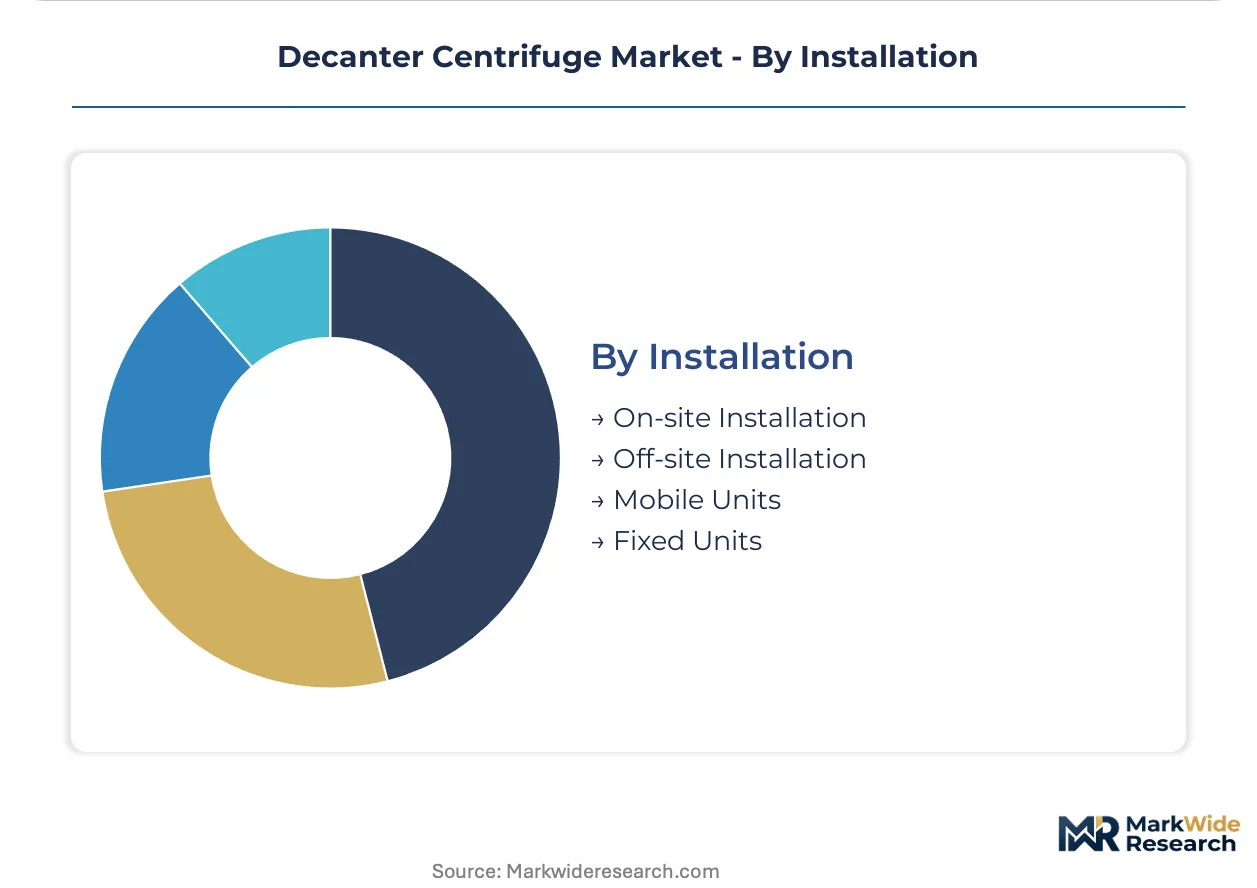
Installation:
Fixed infrastructure dominates capital-intensive municipal builds, whereas mobility requirements shape oilfield and emergency response procurement.
- Fixed Units:Permanent foundations support high-G force rotor balancing infrastructure certified to ISO 1940 tolerances, limiting field service capabilities to specialized workshops. These installations anchor Germany's chemical corridor and Dutch water authority networks where decades-long asset lifecycles justify precision engineering premiums.
- Mobile Units:Rapid deployment configurations serve emergency wastewater bypass operations and seasonal food processing peaks. Remote municipal installations face scroll conveyor wear specialist scarcity, as hardfacing repair of tungsten carbide tiles requires certified welders with centrifuge-specific expertise.
- On-site Installation:Turnkey construction management reduces interface risk for greenfield municipal projects.
- Off-site Installation:Prefabricated skids minimize construction disruption in dense European industrial zones.
Fixed installations retain the deepest aftermarket attachment through long-term service contracts. Mobile configurations are gaining share fastest in distributed industrial wastewater treatment and contingency response planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen and Leverkusen anchor European decanter deployment through Germany's chemical corridor, where cluster-scale sludge management upgrades respond to hardened EU discharge mandates.
Germany
Industrial emissions directives from the EU Green Deal accelerate equipment replacement across processing facilities in the Rhineland. ECHA REACH restrictions on chromium(VI) surface treatments compel bowl manufacturers toward thermal spray ceramic coatings. BASF and Bayer sites in Ludwigshafen and Leverkusen now require coating documentation traceable to registered formulations.
United States
EPA effluent limitation guidelines tighten permissible solids thresholds, compelling municipalities toward higher-capacity retrofits. Wisconsin and California dairy processors generate escalating organic waste streams where disposal cost pressures concentrate demand. Large food processors in California's Central Valley specify performance-based service contracts with guaranteed cake dryness percentages.
China
MEE enforcement of industrial wastewater recycling mandates drives retrofit demand in Jiangsu and Zhejiang chemical parks. Dual carbon goals favor energy-efficient bowl drive configurations. Municipal sanitation expansion targets tier-2 cities under national urban renewal allocations, opening greenfield deployment for sludge thickening applications.
India
Jawaharlal Nehru National Urban Renewal Mission allocations target sewage treatment capacity in tier-2 cities. BIS standards govern equipment specifications for municipal procurement. Cluster demand concentrates in Maharashtra and Gujarat where industrial effluent treatment capacity lags manufacturing growth.
Netherlands
Amsterdam-Rijnland and Hollandse Delta treatment networks specify direct-drive permanent magnet configurations for installations above 500 cubic meters per hour throughput. Dutch water authorities lead electrification adoption, eliminating mechanical transmission losses and compressing maintenance intervals from quarterly to annual schedules.
Decanter Centrifuge Market Key Industry Players
The competitive structure tilts toward diversified industrial engineering conglomerates with centrifuge divisions alongside specialized centrifuge fabricators. Scandinavian and German engineering bases sustain premium-tier positions through metallurgical expertise and precision rotor balancing infrastructure. Three archetypes dominate: integrated process technology conglomerates bundling dewatering with upstream separation equipment; centrifuge specialists focusing exclusively on sedimentation technology; and diversified industrial manufacturers leveraging cross-divisional service networks. Geographic expansion through local assembly partnerships and vertical integration into specialized alloy supply chains represent the dominant competitive moves.
Among German-based engineering groups, Flottweg SE and ANDRITZ AG occupy positions anchored in Central European industrial demand. Alfa Laval represents Scandinavian engineering heritage in high-G force decanter lines. GEA Group Aktiengesellschaft exemplifies diversified process technology conglomerates with hygienic-design capabilities purpose-built for food and dairy applications. These three anchors span the archetype spectrum from centrifuge specialization to integrated process solutions.
| Leading Market Players |
|---|
| Flottweg SE |
| FLSmidth A/S |
| Alfa Laval |
| Centrisys |
| IHI Corporation |
| GEA Group Aktiengesellschaft |
| SPX FLOW Inc. |
| Pieralisi Group S.p.A. |
| ANDRITZ AG |
| Others |
Cost & Logistics Intelligence
Direct-drive permanent magnet motor electrification is compressing lifecycle cost structures while simultaneously concentrating procurement power among Dutch and German water authorities with sufficient scale to justify premium configurations. This technological transition rewards suppliers with ISO 1940-certified balancing infrastructure and REACH-registered coating documentation, widening the bid-ask spread between qualified incumbents and marginal competitors.
Pricing Analysis
Guaranteed cake dryness percentages and availability uptime anchor value-based contracting in North American food processing and wastewater procurement. Premium-mid-economy pricing differentiation separates continuous municipal configurations above 500 cubic meters per hour from portable oilfield units and batch pharmaceutical systems. Cost compression in standard-tier municipal retrofits is intensifying because EPA effluent guidelines force accelerated replacement cycles without proportional federal funding increases. Small municipalities in India's tier-2 cities exhibit highest price sensitivity, while Dutch water authorities and German chemical processors prioritize operational expenditure reduction over capital outlay.
Supply Chain Analysis
Freight costs for precision-balanced rotor assemblies limit economic delivery radius to specialized workshops in Germany, Scandinavia, and the Netherlands. Duplex stainless steel and super-duplex bowl materials draw from German and Scandinavian metallurgical suppliers, with tungsten carbide hardfacing tiles sourced from Central European coating specialists. Single-source vulnerability concentrates in REACH-registered thermal spray ceramic formulations required for food-grade surface validation. Distribution runs through OEM-direct channels for large municipal projects and authorized service networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal industrial emissions directives and EPA effluent limitation guidelines have erected a cost-of-compliance moat around REACH-registered coating documentation and ISO 1940 balancing certification, privileging incumbent suppliers with sunk qualification investments.
For Market Incumbents: Hedge against margin erosion in standard-tier municipal retrofits by deepening captive supply of super-duplex bowl alloys and thermal spray coating capacity. Counter emerging Asian competitors in India's Jawaharlal Nehru National Urban Renewal Mission tenders through local assembly partnerships that preserve certification integrity while compressing landed cost. For New Entrants and Emerging Players: Tier-2 Indian municipalities with BIS-governed procurement standards represent the most penetrable buyer archetype for greenfield sludge thickening deployment. Bypass entrenched European competition by targeting mobile decanter configurations for China's Jiangsu and Zhejiang chemical park retrofits under MEE wastewater recycling mandates, using energy-efficient bowl drive architectures as the technical wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified process technology conglomerates seeking centrifuge specialization to complete separation technology portfolios. Five-to-ten year viability favors targets with hygienic-design capabilities for biopharmaceutical cell harvest integration. Watch for inflection when China's dual carbon enforcement accelerates retrofit demand beyond domestic supplier capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Super-Duplex Alloy Supply | Captive metallurgical capacity insulates German and Scandinavian incumbents from regional energy cost volatility affecting lead times. |
| Performance-Based Service Contracting Expansion | California Central Valley food processors now specify guaranteed uptime, shifting revenue from equipment sales to recurring service streams. |
| REACH-Registered Coating Documentation Investment | ECHA compliance for thermal spray ceramic barriers creates qualification barriers protecting premium-tier positioning in dairy applications. |
| Local Assembly Partnerships in India | Tier-2 city sanitation expansion under JNNURM allocations requires BIS-certified production proximity to compete for municipal tenders. |
| Predictive Maintenance Architecture Deployment | Remote vibration monitoring enables Dutch water authorities to compress maintenance intervals from quarterly to annual schedules. |
Research Approach
Trade publications, customs databases, and SEC filings formed the secondary backbone, supplemented by structured interviews with municipal wastewater plant engineers, aftermarket service heads at centrifuge OEMs, and procurement leads at North American food processors. Bottom-up and top-down triangulation validated installed base estimates against polymer dosing system shipments and scroll conveyor replacement part demand.
Bottom-up modeling anchored volume projections to individual country-level municipal capex cycles and industrial effluent treatment capacity additions, while top-down cross-checks applied macroeconomic filters across the analysis window. Segmentation dimensions included product type, application intensity, end-user procurement sophistication, and installation mobility. CAGRs derived from regression analysis against historical replacement rates, with forecast inputs weighted toward EPA and EU regulatory compliance timelines and China's MEE enforcement patterns.
Revisions become necessary when REACH Annex XVII restrictions expand to additional coating chemistries, when ISO 1940 certification requirements tighten for high-G force assemblies, or when India's BIS standards diverge from European equipment specifications. Stakeholders should weight assumptions against their own operating context and regulatory jurisdiction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Food Sorting Machines Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market