
 Conveyor Ovens and Impinger Ovens Market | 2026-2036
Conveyor Ovens and Impinger Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Ovens and Impinger Ovens Market Outlook
Foodservice equipment distribution is reconfiguring around direct manufacturer-to-chain relationships and consolidated dealer networks. Middleby Corporation leverages its broad portfolio to anchor multi-brand supply contracts with major restaurant groups. Illinois Tool Works competes through specialized heating technology and aftermarket parts density. TurboChef Technologies differentiates via ventless, high-speed impinger platforms that reduce installation complexity for franchise operators.
Conveyor ovens and impinger ovens are forced-convection baking systems that use high-velocity hot air jets or continuous belt mechanisms to achieve rapid, uniform heat transfer at temperatures typically ranging from 250°F to 600°F; impinger ovens specifically direct concentrated air streams through perforated plates above and below the product surface to accelerate cooking in commercial and industrial food preparation. Their primary purpose is to deliver consistent throughput for high-volume prepared foods, frozen dough, and protein items with minimal labor intervention. Electric and gas technologies dominate the installed base, though hybrid systems are gaining traction where utilities fluctuate and operators seek redundancy. By end user, restaurants and food production facilities represent the core demand pool, with catering services emerging as a faster-growing segment due to event-sector recovery and ghost kitchen proliferation.
NSF International standards, UL safety certifications, and EU energy labeling frameworks govern equipment approval and market access across major sales corridors. EPA Energy Star requirements and evolving DOE commercial oven efficiency rules in the United States tighten compliance thresholds and favor R&D investment in insulated cavity designs and burner optimization. Stakeholders must monitor how fragmented municipal electrification timelines and divergent gas-connection policies reshape total cost-of-ownership calculations for new installations.
Market Dynamics
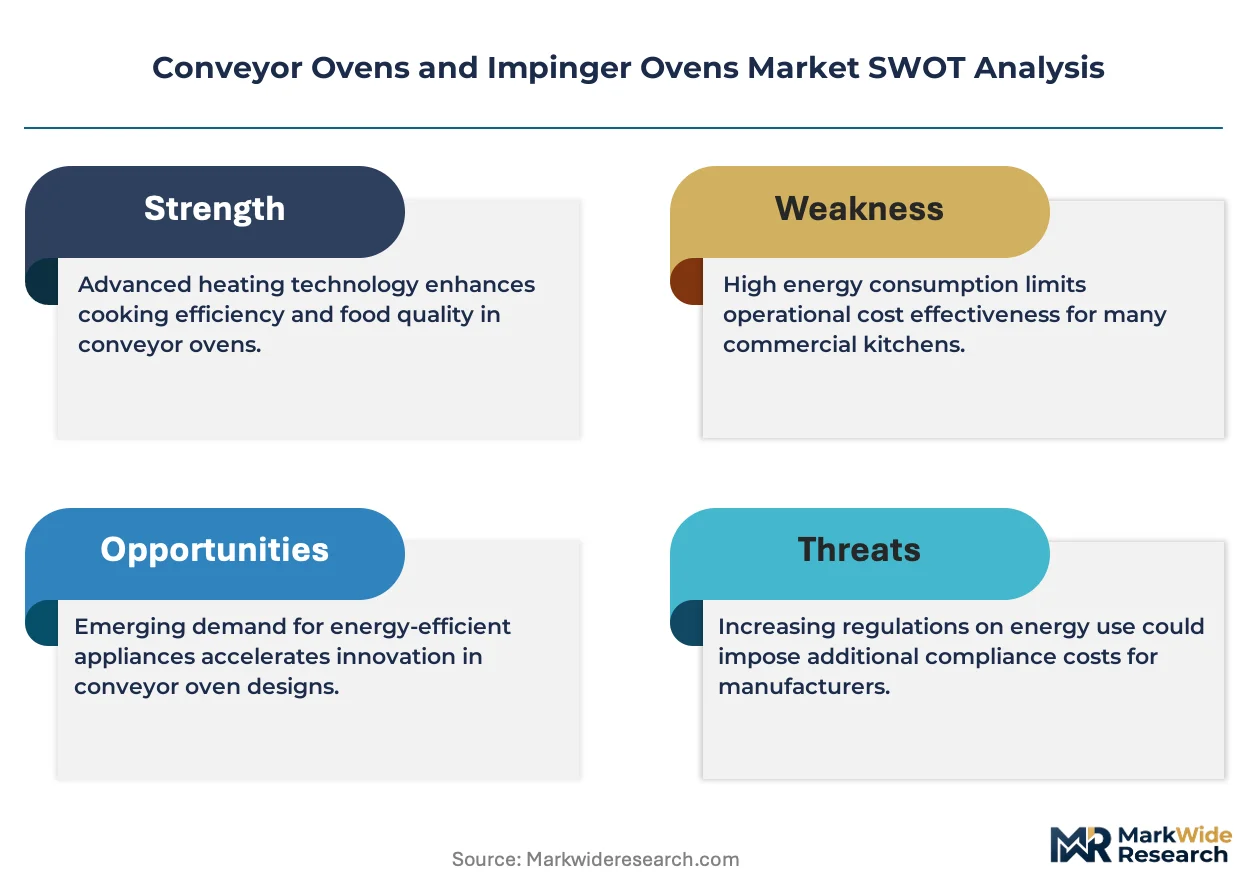
Energy-efficiency mandates from the EPA and EU Ecodesign Directive are compressing replacement cycles and forcing manufacturers to redesign combustion systems and insulation cavities for commercial kitchen operators.
Growth Catalysts
- Cloud kitchen proliferation:Ghost kitchen operators in urban United States markets require compact, ventless impinger systems to maximize throughput in limited footprints. These facilities prioritize equipment that delivers consistent results with minimal ventilation infrastructure.
- EU Ecodesign Directive:European commercial kitchen operators face mandatory efficiency thresholds that accelerate retirement of legacy gas-fired units. Equipment suppliers gain volume through compliance-driven replacement demand.
- Frozen dough processing:Centralized food production facilities handling par-baked goods and frozen pizza rely on conveyor ovens for uniform thermal profiles. This segment demands precise temperature control across high-volume continuous operations.
Market Restraints
- Stainless steel input volatility:Conveyor belt fabrication and cavity construction depend on nickel-alloy grades subject to commodity price swings. Manufacturers absorb margin pressure or pass costs through long equipment sales cycles.
- Gas connection restrictions:Municipal electrification timelines in California, New York, and Massachusetts create uncertainty for gas-fired oven installations. Operators delay capital commitments pending clarity on utility infrastructure.
- Ventless certification limits:UL certification for ventless impinger systems restricts maximum temperature outputs and cooking categories. This technical ceiling constrains menu versatility for some high-heat applications.
Strategic Opportunities
- India catering sector:Event-service recovery and institutional feeding programs create demand for portable conveyor systems. Domestic manufacturers lack high-velocity impinger expertise, opening import channels for specialized suppliers.
- Hybrid fuel flexibility:Dual-power ovens combining electric and gas burners address utility redundancy needs. This convergence technology captures operators in markets with unreliable grid infrastructure or volatile energy pricing.
- Direct-to-chain distribution:National restaurant groups consolidate supplier relationships around single-source equipment contracts. Bypassing traditional dealer networks improves margin capture and service response times.
Industry Challenges
- Controls engineering talent:Programming sophisticated HMI interfaces for multi-zone temperature management requires specialized skill sets. Equipment manufacturers compete with broader automation sectors for limited firmware developers.
- NSF certification timelines:Sanitation validation for new cavity geometries and belt materials extends product launch schedules. Delays between prototype completion and commercial availability compress revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyor Ovens and Impinger Ovens Market |
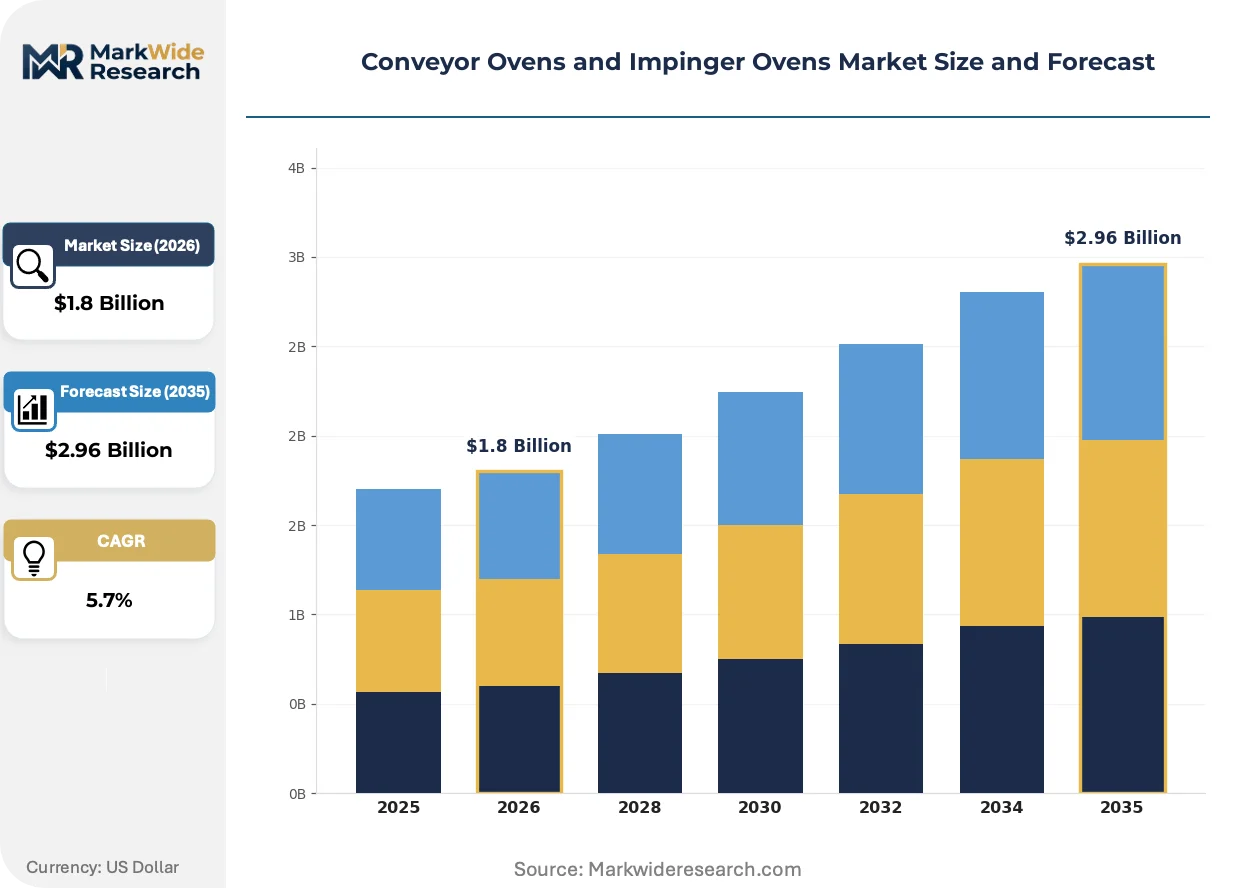
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Ovens, Impinger Ovens, Modular Ovens, Batch Ovens End User: Restaurants, Bakeries, Catering Services, Food Production Installation: On-site, Commercial, Industrial, Portable Technology: Electric, Gas, Infrared, Hybrid |
| Companies Covered | Illinois Tool Works, XLT Ovens, Middleby Corporation, Ovention, TurboChef Technologies, Welbilt, RATIONAL AG, Moretti Forni, Alto-Shaam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Ovens and Impinger Ovens Market Strategic Shifts
IoT-enabled thermal monitoring and predictive maintenance capabilities are transforming how commercial kitchen operators manage equipment uptime and energy consumption across distributed restaurant footprints.
Smart oven technology integrating cloud-connected temperature sensors and automated recipe management is digitizing kitchen operations for multi-unit restaurant chains. Franchise operators deploy these systems to enforce consistency across locations while reducing labor training burdens. Real-time performance data is digitizing equipment service models from reactive breakdown response toward condition-based intervention.
The EPA's evolving commercial oven efficiency standards under the Energy Star program tighten allowable standby energy consumption and idle-mode losses. Equipment manufacturers redesign burner assemblies and add variable-speed convection fans to meet thresholds. Full-service restaurant chains in California and New York face the earliest compliance deadlines, accelerating specification changes in new build-outs.
Buying committees at major restaurant groups now consolidate equipment decisions through centralized procurement functions rather than franchisee autonomy. Dealer networks lose influence as manufacturers establish direct technical support relationships with chain engineering teams. This concentration is most visible among quick-service pizza and sandwich concepts expanding through corporate-owned development.
Conveyor Ovens and Impinger Ovens Market Segmentation
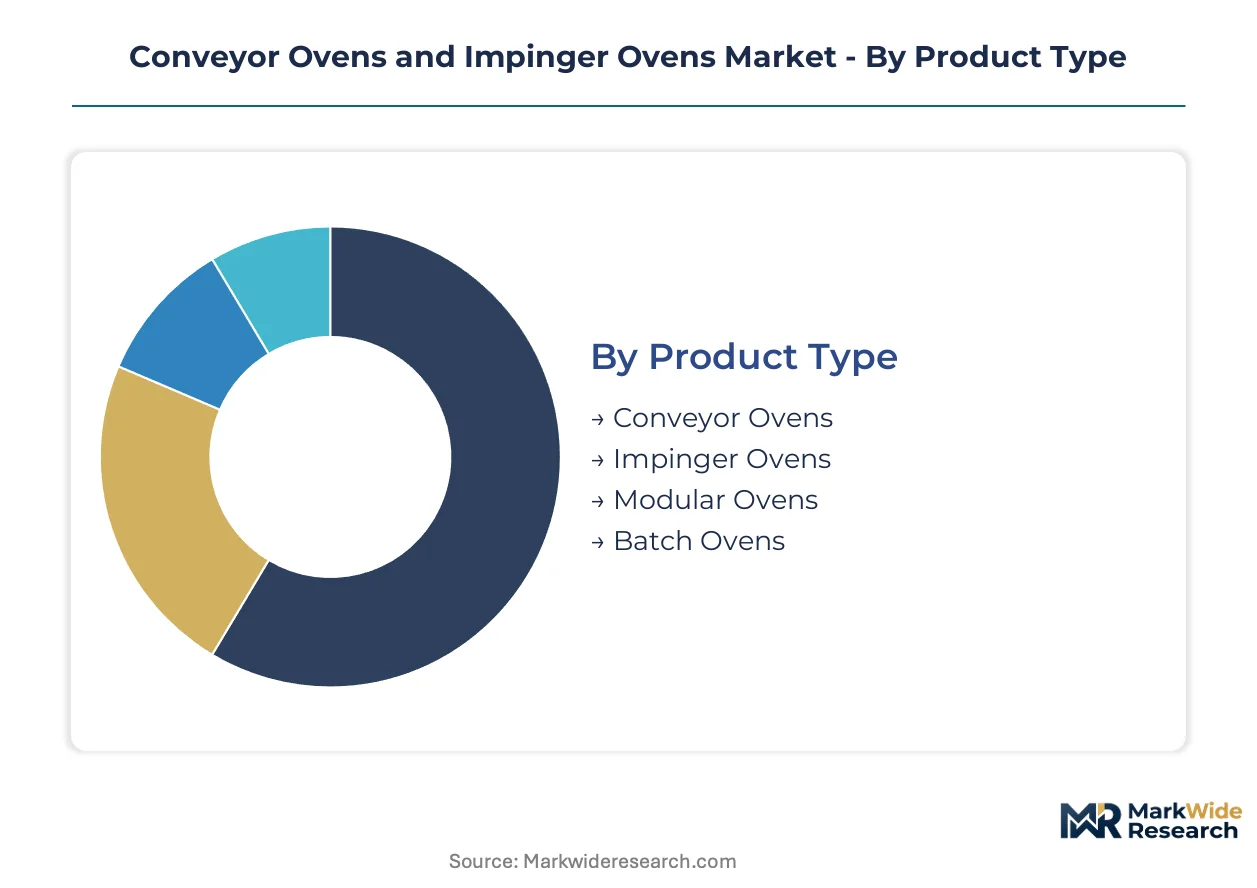
Equipment specification varies sharply across operational environments. Cycle times, throughput requirements, and utility access dictate which oven configurations command premium positioning versus commodity replacement demand.
Product Type:
Replacement cycles stretch from five years for entry modular units to twelve-plus years for heavy-duty impinger platforms in high-throughput chains.
- Conveyor Ovens:Continuous belt mechanisms move product through fixed temperature zones at controlled speeds. Frozen pizza processors in the United States specify these for uniform crust development across high-volume shifts.
- Impingement Ovens:High-velocity air jets directed through perforated plates accelerate surface heat transfer. Ghost kitchen operators in urban Germany prioritize ventless impinger configurations to minimize ductwork in leased warehouse spaces.
- Modular Ovens:Stackable cavity designs allow capacity expansion without footprint relocation. Institutional feeding programs value this flexibility.
- Batch Ovens:Static rack configurations serve lower-volume specialty bakeries with intermittent production schedules.
Conveyor ovens dominate installed base. Impinger ovens are where expansion concentrates.
End User:
Margin structures diverge sharply across customer types, with equipment-as-a-service models penetrating fastest where capital constraints meet high utilization.
- Restaurants:Quick-service chains standardize on manufacturer-direct procurement to enforce menu consistency. EPA Energy Star compliance deadlines in California and New York accelerate specification upgrades for legacy gas-fired units.
- Bakeries:Par-baked goods producers require precise humidity control and multi-zone thermal profiling. Artisan operators in France emphasize steam injection compatibility.
- Catering Services:Mobile event operators drive portable electric segment demand. India's post-pandemic wedding sector recovery imports compact conveyor systems lacking domestic alternatives.
- Food Production:Centralized commissaries for retail private-label pizza represent concentrated volume. EU Ecodesign Directive thresholds force combustion system redesigns for export-oriented facilities.
Food production commands the largest average transaction values. Catering services are climbing the fastest as event-sector normalization continues.
Installation:
Site preparation costs often exceed equipment purchase price, making installation type a primary filter in capital planning.
- On-site:Custom-fabricated solutions for flagship locations with architectural constraints. High-end steakhouse chains specify these for open-kitchen visibility.
- Commercial:Standardized configurations for franchise rollouts with repeatable build specifications. Dominates unit volume.
- Industrial:Heavy-gauge construction for 24/7 frozen dough processing. Requires reinforced flooring and dedicated utility drops.
- Portable:Castor-mounted electric units for temporary foodservice at construction sites and festivals. Limited to sub-600°F applications per UL ventless certification.
Commercial installations represent the volume anchor. Portable configurations are gaining share fastest where mobility premiums offset throughput limitations.
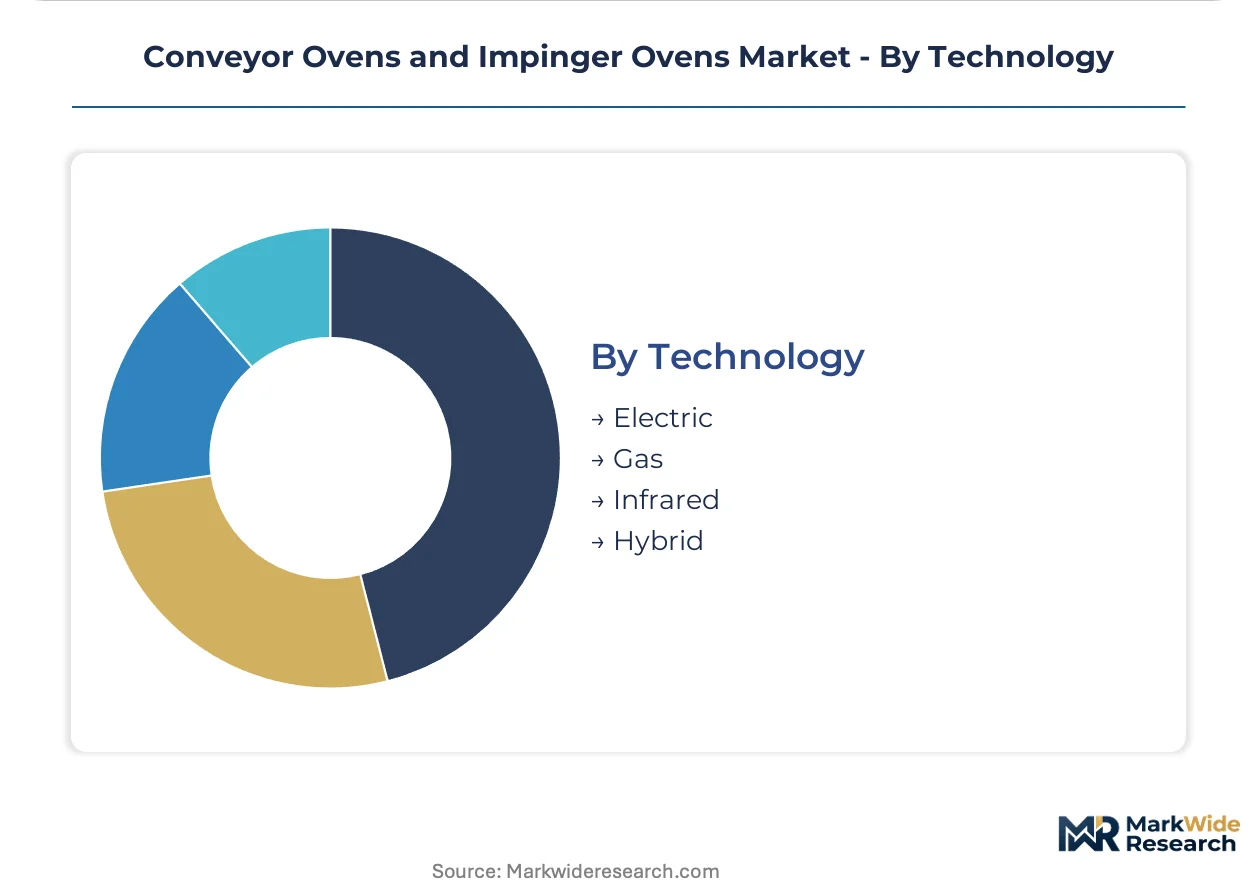
Technology:
Fuel choice locks operators into fifteen-year infrastructure commitments, amplifying the stakes of electrification timeline uncertainty.
- Electric:Resistance-element heating with precise digital control. Municipal gas connection moratoria in Massachusetts and New York City accelerate specification shifts.
- Gas:Atmospheric or power burner configurations with faster recovery times. Legacy installed base remains substantial in Texas and Florida markets with reliable pipeline access.
- Infrared:Ceramic or metal-sheath emitters for rapid surface browning. Niche applications in high-speed sandwich toasting.
- Hybrid:Dual-fuel capability combining gas primary with electric boost. Addresses grid reliability concerns in developing markets without sacrificing peak output.
Gas technology retains the deepest installed base. Electric platforms are where manufacturer R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA commercial appliance standards and the EU Ecodesign Directive are accelerating equipment replacement cycles across major foodservice markets. These regulatory frameworks compress payback periods for energy-efficient conveyor and impinger oven investments. The analysis examines five countries where centralized procurement and cloud kitchen infrastructure are reshaping demand.
United States
Quick-service restaurant chains dominate capital deployment through manufacturer-direct contracts. EPA Energy Star efficiency thresholds tighten standby power limits for new installations. Ghost kitchen clusters in Atlanta and Dallas prioritize ventless impinger configurations to minimize ductwork costs in converted warehouse spaces.
Germany
Bakery commissaries and frozen dough processors drive specification of multi-zone thermal profiling systems. EU Ecodesign Directive mandates force combustion system redesigns for export-oriented equipment. Industrial food production concentrates in Baden-Württemberg, where centralized baking facilities serve retail private-label programs across Central Europe.
China
Cloud kitchen operators in Shanghai and Beijing specify compact electric conveyor platforms for high-throughput delivery-only facilities. National energy efficiency labeling frameworks tighten compliance windows for commercial kitchen equipment. Yangtze River Delta manufacturing clusters supply domestic food production facilities scaling frozen prepared meals for retail distribution.
India
Catering services and institutional feeding programs generate demand for portable electric conveyor systems lacking domestic manufacturing alternatives. FSSAI equipment safety standards govern commercial kitchen certification for imported ovens. Post-pandemic event-sector recovery in Maharashtra and Gujarat drives imports of compact impinger units for wedding and corporate catering.
United Kingdom
Quick-service sandwich and pizza chains consolidate procurement through centralized engineering functions. UKCA marking requirements replace CE certification for equipment market access post-Brexit. Greater London ghost kitchen infrastructure in repurposed industrial estates favors ventless configurations to circumvent planning permission delays for ventilation systems.
Conveyor Ovens and Impinger Ovens Market Competitive Environment
On the supply side, the industry is consolidating around diversified equipment portfolios and specialized heating technology platforms. Tiered competitive dynamics separate full-line manufacturers from focused impinger specialists and regional fabrication houses. Strategic archetypes include multi-brand conglomerates leveraging scale, technology licensors monetizing patent estates, and regional assemblers serving price-sensitive replacement demand. Dominant competitive moves encompass direct-to-chain distribution bypassing dealer networks and vertical integration into control system firmware development.
Within the diversified equipment tier, Illinois Tool Works and Middleby Corporation anchor competitive positioning through breadth of portfolio and density of aftermarket parts networks. TurboChef Technologies exemplifies the specialized impinger archetype, occupying a position defined by ventless platform development for franchise operators with constrained installation footprints. XLT Ovens represents the focused conveyor fabrication segment, sitting within a tier where throughput engineering and stainless steel fabrication expertise determine specification wins in high-volume frozen pizza processing.
| Leading Market Players |
|---|
| Illinois Tool Works |
| XLT Ovens |
| Middleby Corporation |
| Ovention |
| TurboChef Technologies |
| Welbilt |
| RATIONAL AG |
| Moretti Forni |
| Alto-Shaam |
| Others |
Value Chain & Pricing Dynamics
Nickel-alloy stainless steel volatility compresses margin buffers across equipment tiers while simultaneously forcing geographic sourcing diversification that reshapes tier spreads and procurement lead times. EPA Energy Star compliance thresholds and EU Ecodesign Directive certification costs create pricing stratification that separates premium insulated-cavity designs from commodity modular units, with buyer archetypes sorting by replacement cycle urgency and ventilation infrastructure constraints.
Pricing Analysis
Certification level (UL/NSF/CE-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with NSF sanitation validation and ventless UL certification commanding material premiums. Cost compression in economy modular segments is intensifying because of Chinese manufacturer price competition in entry-level electric conveyor platforms. Quick-service franchise operators exhibit highest price sensitivity due to standardized build specifications and volume procurement leverage, while ghost kitchen developers prioritize ventless configurations with lower total installation cost despite higher unit pricing.
Supply Chain Analysis
Stainless steel feedstock draws from Indonesian nickel processing, Chinese cold-rolling capacity, and Italian specialty alloy fabrication for high-temperature cavity components. Control system firmware hinges on Taiwanese semiconductor sourcing for HMI interfaces and variable-speed convection drives. Single-source vulnerability concentrates in nickel-alloy grades subject to LME price swings and Indonesian export restriction risk. Distribution runs through consolidated dealer networks losing share to direct manufacturer-to-chain relationships with national restaurant group engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles are compressing under regulatory compliance deadlines, positioning the market for cyclical recovery as legacy gas-fired unit retirement accelerates across California, New York, and EU member states.
For Market Incumbents: Build aftermarket parts density moats through captive supply of burner assemblies and belt drive components to lock in service revenue streams. Deepen backward integration into control system firmware development to reduce dependency on Taiwanese semiconductor sourcing. Anchor multi-brand supply contracts with quick-service pizza and sandwich chains expanding corporate-owned development pipelines.
For New Entrants and Emerging Players: Portable electric conveyor systems for India's post-pandemic catering recovery represent the most penetrable entry point given absent domestic high-velocity impinger expertise. Cloud kitchen operators in German urban warehouse conversions present secondary white-space demand for ventless configurations circumventing planning permission delays. Pursue equipment-as-a-service financing models to bypass capital constraints among mobile event operators.
For Investors and Strategic Acquirers: The market sits at a regulatory-forced replacement phase that favors diversified equipment portfolios with density in aftermarket service networks. Long-term viability rests on manufacturers capturing compliance-driven specification shifts rather than commodity replacement demand. Monitor municipal electrification timeline clarity in Massachusetts and New York City as inflection indicator for gas-fired unit valuation recovery. Cross-checking against EPA commercial oven efficiency rulemaking schedules is advised before commitment-grade decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Ventless Platform Development | UL-certified impinger configurations capture ghost kitchen operators avoiding ductwork infrastructure costs. |
| Hybrid Fuel System Launch | Dual-power ovens address grid reliability concerns in developing markets without sacrificing peak thermal output. |
| Direct-to-Chain Distribution | Bypassing dealer networks improves margin capture and service response times with national restaurant groups. |
| IoT-Enabled Predictive Maintenance | Cloud-connected thermal sensors transform service models from reactive breakdown toward condition-based intervention. |
| Backward Integration into Controls | In-house firmware development reduces semiconductor sourcing risk and accelerates multi-zone temperature management innovation. |
Study Parameters
A spread of perspectives from quick-service chain engineering directors, ghost kitchen facility operators, commercial equipment dealers, NSF certification specialists, and stainless steel procurement managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EPA Energy Star equipment databases, EU Ecodesign Directive technical documentation, UL safety certification filings, and customs trade data on nickel-alloy imports. Bottom-up unit economics triangulated against top-down regulatory replacement cycle modeling.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user category, installation configuration, and technology fuel source, with additional granularity on ventless certification status. CAGRs derived from replacement cycle compression rates under evolving efficiency standards and cloud kitchen infrastructure build-out trajectories. Industry-specific forecast inputs incorporated municipal electrification policy timelines and frozen dough processing capacity expansion announcements.
Practitioners should monitor EPA commercial oven efficiency rulemaking acceleration, EU Ecodesign Directive enforcement tightening, and nickel LME price volatility for early signals requiring forecast revision. Cross-checking against National Restaurant Association equipment expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Automatic Liquid Dispenser Machine Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Deaeration Machine Market