
 Deep Fryer Oil Filtration Market | 2026-2036
Deep Fryer Oil Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Fryer Oil Filtration Market Outlook
REACH compliance in Europe is restructuring capital allocation for filtration system manufacturers serving cross-border foodservice chains. Middleby Corp. leverages its vertical manufacturing footprint to control component costs across portable and in-line filter assemblies. Henny Penny sustains technology leadership through electrostatic filtration R&D programs. Pitco anchors its competitive position with specialized vacuum filter designs for high-volume frying operations.
Deep fryer oil filtration encompasses mechanical and chemical processes that remove particulate matter, free fatty acids, and polymerized contaminants from heated cooking oils to extend usable life and maintain food quality standards. Centrifugal systems spin oil at high rotational velocities to separate denser debris, while in-line filters integrate directly into fryer plumbing for continuous processing during service hours. Portable filter units dominate current equipment sales due to lower upfront capital requirements and retrofit compatibility with existing fryer banks. Electrostatic filtration technology represents the fastest-expanding segment as operators seek chemical-free alternatives that reduce consumable costs and simplify waste handling.
The U.S. FDA Food Code and state-level health department inspections shape equipment specifications by mandating oil quality documentation and discard protocols. Germany's KBA-aligned commercial kitchen efficiency standards and EU Ecodesign requirements for energy-consuming appliances influence filtration system thermal performance benchmarks. Stakeholders must weigh regulatory trajectory against total cost-of-ownership models as compliance thresholds tighten across major foodservice jurisdictions.
Market Dynamics
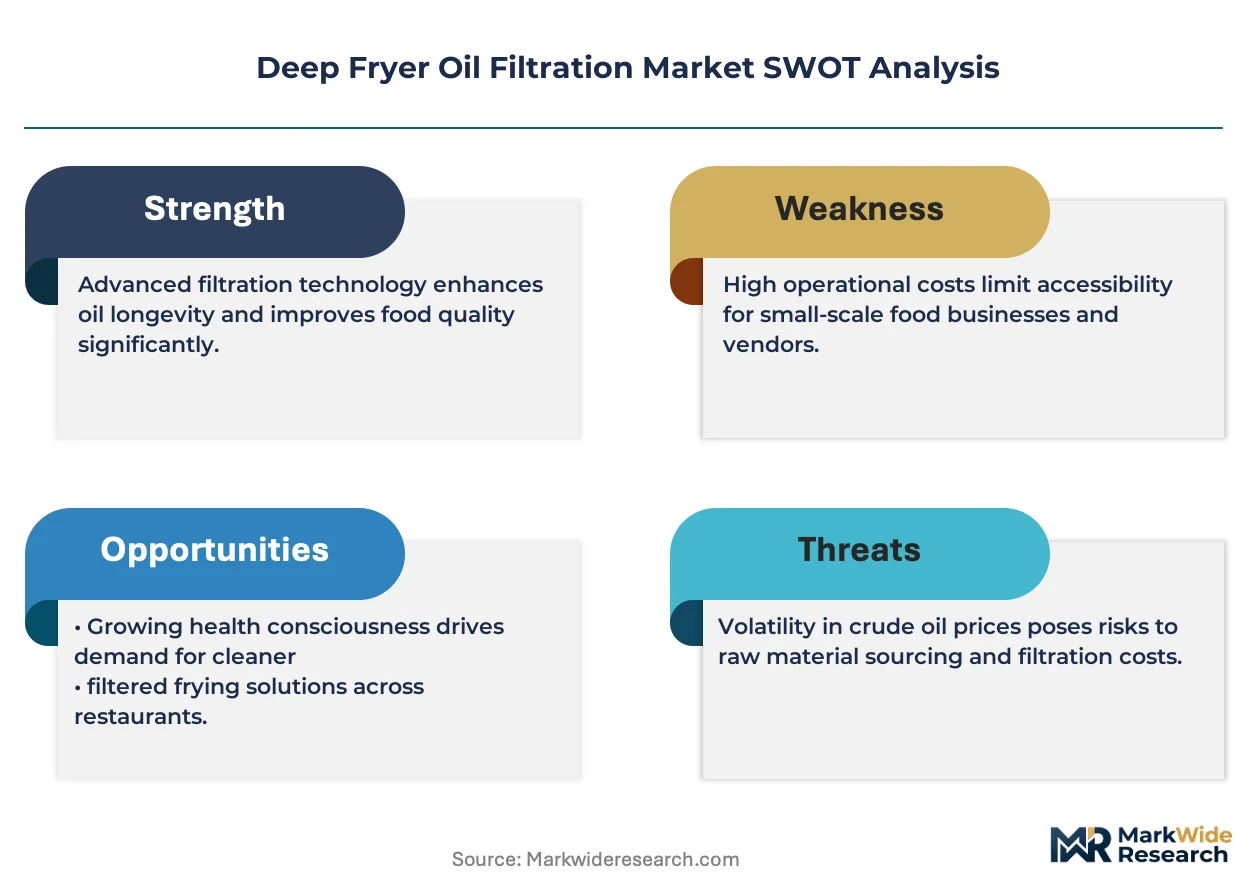
The Deep Fryer Oil Filtration Market is experiencing structural compression as regulatory documentation mandates from the U.S. FDA Food Code force equipment replacement cycles while electrostatic filtration technology captures operator attention through reduced consumable dependency.
Growth Catalysts
- Electrostatic Filtration Advancement:Chemical-free oil purification systems eliminate filter paper and powder consumables, cutting waste handling costs for high-volume frying operations in quick-service restaurant chains.
- Germany's Commercial Kitchen Retrofit Mandates:KBA-aligned efficiency standards and EU Ecodesign requirements accelerate filtration equipment upgrades in centralized food production facilities.
- Edible Oil Price Volatility:Sustained cost pressure on frying oils drives capital allocation toward filtration systems that extend oil usable life by 50-75% in continuous frying environments.
Market Restraints
- Stainless Steel Input Cost Volatility:Filtration system chassis and pressure vessel fabrication depends on nickel-alloy steel pricing, exposing manufacturers to commodity swings that compress equipment margins.
- Centrifugal System Technical Limitations:High-rotational-velocity separators require precise balancing maintenance and generate significant noise levels, restricting deployment in open-kitchen formats.
- REACH Compliance Capital Burden:European chemical registration requirements force filtration media suppliers to reformulate adsorbent materials, extending product development timelines.
Strategic Opportunities
- Underpenetrated Ghost Kitchen Infrastructure:Delivery-only food production facilities in urban France and Spain lack standardized filtration protocols, creating first-mover equipment installation potential.
- IoT-Enabled Predictive Maintenance Convergence:Integration of oil quality sensors with cloud-based monitoring platforms allows filtration-as-a-service business models for franchise operators.
- India FSSAI Oil Quality Enforcement:India's food safety regulator is tightening street food and quick-service restaurant inspection protocols, opening equipment sales channels in Mumbai and Bangalore clusters.
Industry Challenges
- Electrostatic System Integration Complexity:Retrofitting ionization chambers into existing fryer plumbing requires certified technician deployment, stretching service network capacity during peak installation periods.
- Multi-Jurisdiction Certification Timelines:Equipment manufacturers must sequence UL, CE, and NSF approvals for cross-border foodservice chain contracts, creating order-to-delivery gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Fryer Oil Filtration Market |
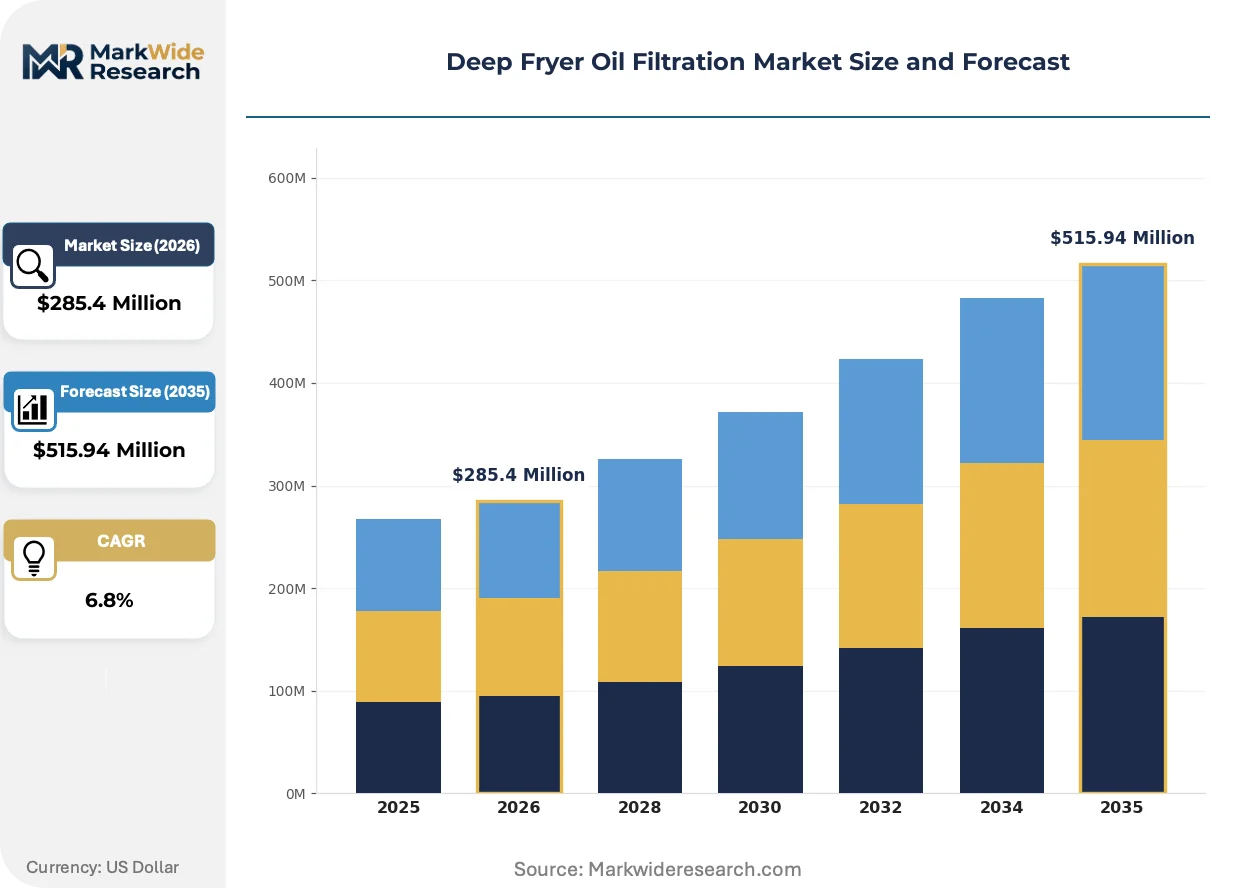
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Filters, In-Line Filters, Vacuum Filters, Centrifugal Filters Technology: Gravity Filtration, Mechanical Filtration, Electrostatic Filtration, Chemical Filtration End User: Restaurants, Food Trucks, Catering Providers, Supermarkets Service Type: Scheduled Maintenance, On-Demand Service, Replacement Parts, Consultation Services |
| Companies Covered | Dean, Middleby Corp., Frymaster, ITW, Electrolux Professional, Pitco, Henny Penny, Welbilt, Vulcan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Fryer Oil Filtration Market Strategic Shifts
Active transformation in filtration technology is compressing traditional equipment categories while regulatory documentation requirements reshape operator purchasing criteria across foodservice verticals.
Electrostatic precipitation technology is expanding into mainstream quick-service restaurant deployments as operators seek to eliminate chemical filter media entirely. Chains with 50-plus unit footprints in Texas and California are piloting ionization-based systems that reduce daily consumable handling. This displacement of mechanical filtration is compressing aftermarket revenue streams for traditional filter paper suppliers while opening recurring service contracts for system calibration.
REACH chemical registration requirements in Europe are forcing filtration media manufacturers to reformulate activated clay and synthetic adsorbent compositions. The industrial consequence extends product recertification timelines by 12-18 months for cross-border suppliers. German and Dutch foodservice equipment distributors are responding by consolidating supplier relationships with vertically integrated media producers who control raw material sourcing.
Franchise operators are unbundling filtration equipment procurement from fryer OEM bundles, creating direct purchasing relationships with specialized filtration vendors. Quick-service restaurant procurement teams in Illinois and Ohio are issuing standalone RFPs for portable filter units, bypassing integrated fryer-filtration packages. This channel disintermediation is most visible among mid-scale chicken and seafood chains seeking to standardize oil quality protocols across heterogeneous fryer installed bases.
Deep Fryer Oil Filtration Market Segmentation
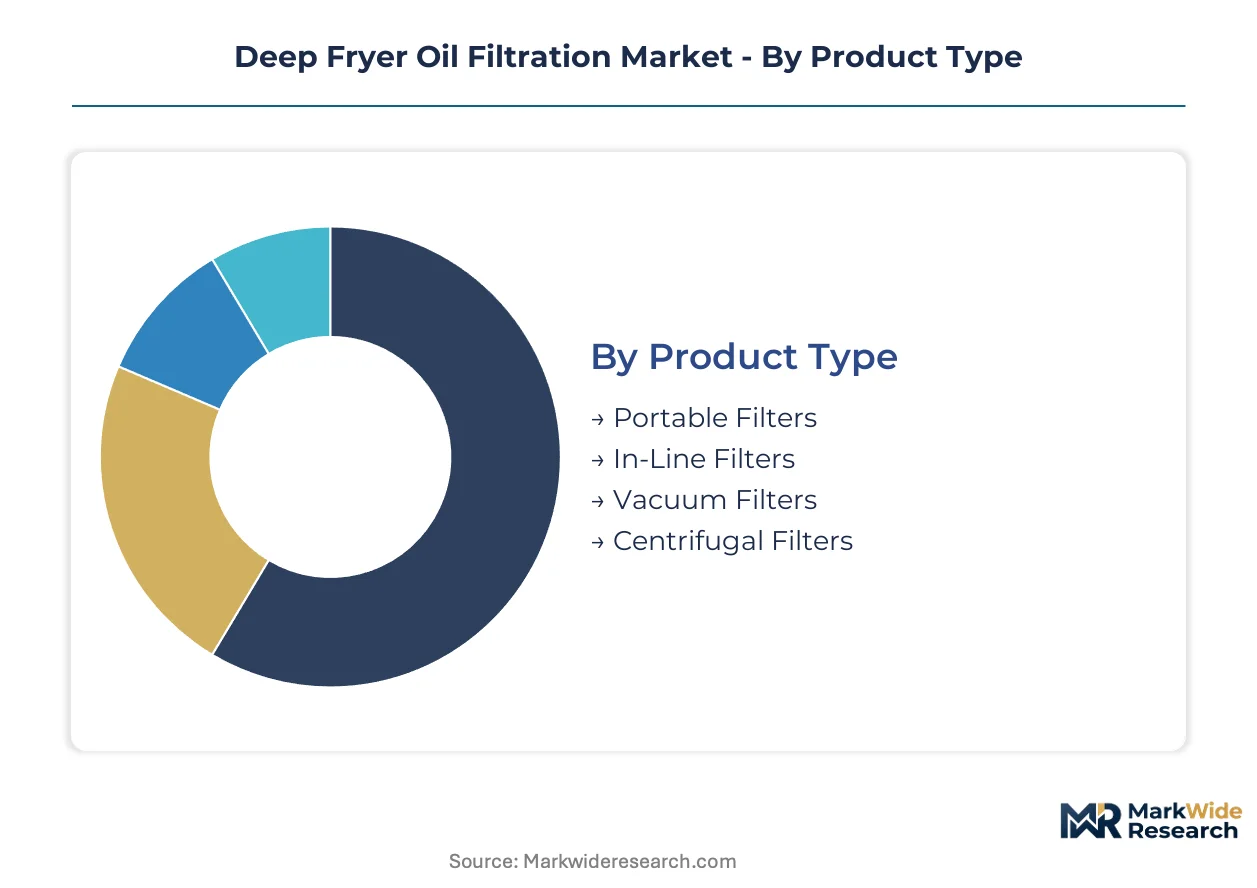
Equipment segmentation in the Deep Fryer Oil Filtration Market reflects divergent capital deployment strategies across foodservice verticals. Operator scale and kitchen configuration determine whether portable units or fixed in-line systems deliver superior lifecycle economics.
Product Type:
Supply concentration among stainless steel fabricators favors modular equipment architectures that reduce field installation complexity.
- Portable Filters:Mobile filtration carts with pump assemblies and reusable mesh screens dominate retrofit installations. Quick-service chains in Texas and Ohio standardize on portable units to synchronize oil quality protocols across heterogeneous fryer banks without plumbing modifications.
- In-Line Filters:Permanent plumbing integration enables continuous filtration during service hours. Germany's centralized food production facilities deploy in-line systems to satisfy KBA-aligned efficiency mandates and minimize manual handling labor.
- Vacuum Filters:Negative-pressure designs extract moisture and fine particulates simultaneously. High-volume frying operations specify vacuum configurations for extended oil life in continuous-use environments.
- Centrifugal Filters:High-rotational-velocity separators demand precise balancing maintenance. Noise generation restricts deployment in open-kitchen formats despite superior debris separation efficiency.
Portable filters absorb the bulk of installed capacity; electrostatic-enabled portable configurations are expanding most quickly.
Technology:
Cost tier differentiation separates chemical-dependent systems from capital-intensive electrostatic alternatives with divergent consumable economics.
- Electrostatic Filtration:Ionization chambers precipitate contaminants without filter media. Chains with 50-plus unit footprints in California pilot these systems to eliminate daily consumable handling and reduce waste disposal costs.
- Mechanical Filtration:Pump-driven circulation through pleated paper or mesh screens remains the baseline technology. Smaller independent restaurants select mechanical systems for predictable capital outlay and familiar maintenance protocols.
- Chemical Filtration:Activated clay and synthetic adsorbent compositions remove free fatty acids and polymerized compounds. REACH compliance in Europe is forcing reformulation of filtration media compositions, extending product recertification timelines for cross-border suppliers.
- Gravity Filtration:Passive settling tanks with minimal moving parts serve low-volume operators. Food trucks in France and Spain deploy gravity systems where electrical capacity and maintenance access are constrained.
Mechanical filtration retains the largest installed base; electrostatic precipitation is gaining share fastest among multi-unit chains.
End User:
Application intensity varies dramatically across customer types, with fryer utilization rates dictating filtration system specifications and service intervals.
- Restaurants:Full-service and quick-service establishments generate concentrated demand for scheduled maintenance contracts. Illinois-based chicken chains issue standalone RFPs for portable filtration to standardize oil quality across franchise locations.
- Catering Providers:Centralized production kitchens with batch frying cycles require robust filtration for intermittent high-volume use. German commercial kitchen retrofit mandates accelerate equipment upgrades in this segment.
- Food Trucks:Mobile operators prioritize compact, electrically efficient units with minimal consumable requirements. India's FSSAI enforcement in Mumbai and Bangalore is penetrating this previously unregulated channel.
- Supermarkets:In-store deli and prepared food departments deploy filtration for rotisserie and fried food operations. Volume scale justifies in-line system investment despite higher upfront capital requirements.
Restaurants command the dominant share of equipment procurement; catering providers are climbing the fastest as centralized production expands.
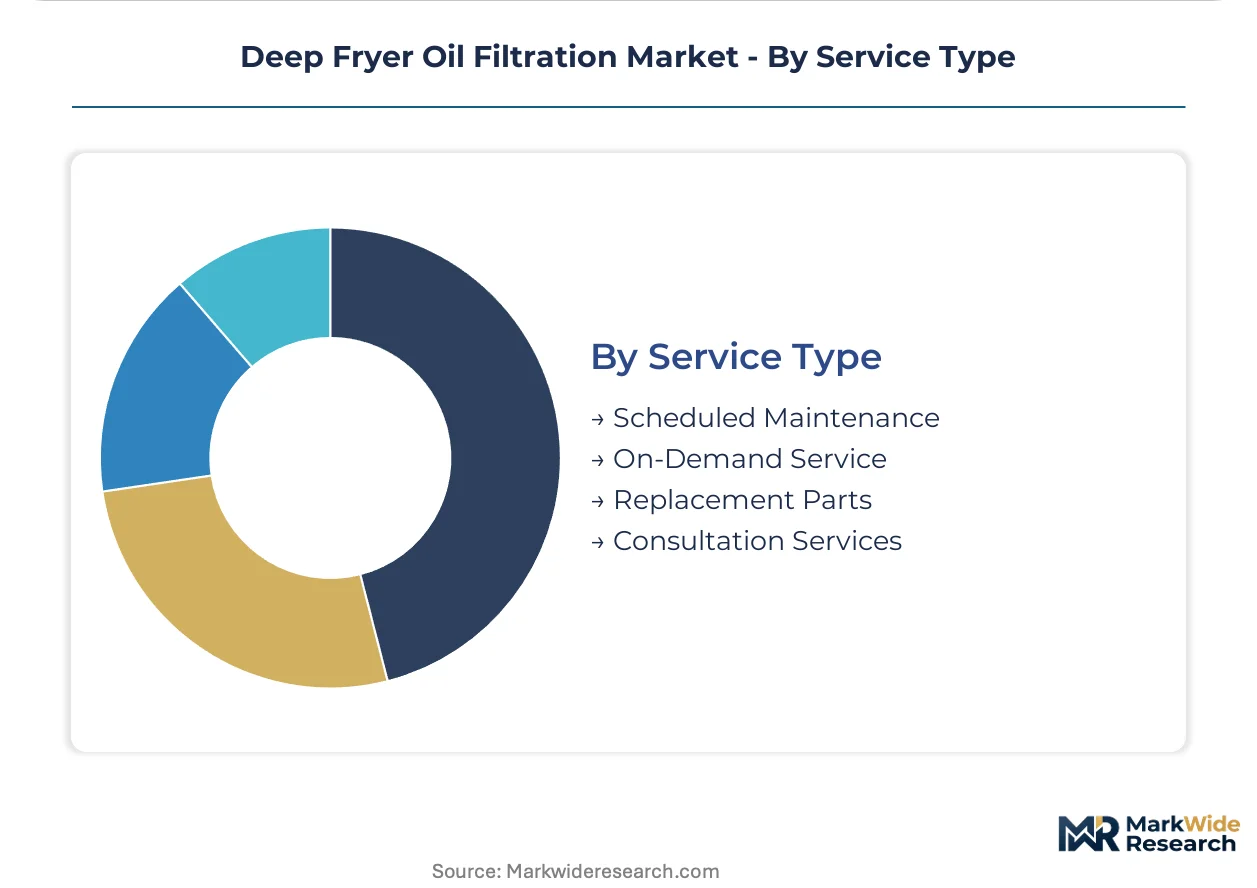
Service Type:
Customer type determines whether preventive maintenance contracts or reactive service models generate superior margin stability for equipment vendors.
- Scheduled Maintenance:Recurring calibration and component replacement contracts lock in multi-year revenue streams. Franchise operators with standardized protocols across 20-plus units negotiate enterprise service agreements.
- Replacement Parts:Aftermarket sales of pump assemblies, filter media, and gaskets sustain vendor profitability. Electrostatic system adoption is compressing traditional filter paper revenue while expanding ionization chamber replacement demand.
- On-Demand Service:Emergency repair and troubleshooting calls address equipment failures. Service network capacity constraints emerge during peak installation periods for electrostatic retrofits.
- Consultation Services:Oil quality auditing and compliance documentation support regulatory inspection preparation. FDA Food Code documentation mandates in the U.S. are expanding this advisory segment.
Scheduled maintenance captures the bulk of recurring service revenue; replacement parts for electrostatic systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates concentrate commercial kitchen equipment distribution for Middle East foodservice markets. Germany's industrial clusters anchor European filtration manufacturing. India's coastal manufacturing zones serve export-oriented food processing equipment.
United States
Quick-service restaurant chains in Texas and California drive equipment procurement for electrostatic filtration pilots. FDA Food Code documentation mandates accelerate replacement cycles across multi-unit operators. Illinois-based chicken chains issue standalone RFPs for portable filtration to standardize oil quality protocols.
Germany
Centralized food production facilities in Bavaria and North Rhine-Westphalia deploy in-line filtration systems. KBA-aligned commercial kitchen efficiency standards and EU Ecodesign requirements accelerate equipment upgrades. Frankfurt and Munich clusters concentrate catering provider procurement for retrofit mandates.
India
Mumbai and Bangalore quick-service restaurant clusters face tightening FSSAI oil quality enforcement in street food segments. Food safety regulator inspections penetrate previously unregulated channels. Maharashtra and Karnataka states generate equipment sales growth for mobile filtration units.
France
Ghost kitchen infrastructure in urban Paris and Lyon remains underpenetrated for standardized filtration protocols. Delivery-only food production facilities lack consistent equipment deployment. Île-de-France and Auvergne-Rhône-Alpes regions present first-mover installation potential for specialized vendors.
Spain
Food truck operators in Barcelona and Madrid deploy gravity filtration systems where electrical capacity constraints limit mechanical alternatives. Catalonia and Andalusia mobile catering segments prioritize compact units with minimal consumable requirements. REACH compliance forces reformulation of filtration media for cross-border suppliers.
Deep Fryer Oil Filtration Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment categories. The vendor base stratifies into three tiers: integrated fryer-filtration bundlers, standalone filtration specialists, and regional stainless steel fabricators. Strategic moves center on disintermediating traditional distribution channels and consolidating aftermarket service relationships.
Among diversified foodservice equipment manufacturers, Middleby Corp. and Welbilt occupy positions spanning integrated fryer systems and standalone filtration components. Pitco and Henny Penny exemplify the specialist archetype with concentrated R&D in vacuum and electrostatic configurations. Dean and Frymaster, as legacy fryer OEMs, sit within the bundling tier where franchise procurement teams increasingly unbundle filtration purchases.
| Leading Market Players |
|---|
| Dean |
| Middleby Corp. |
| Frymaster |
| ITW |
| Electrolux Professional |
| Pitco |
| Henny Penny |
| Welbilt |
| Vulcan |
| Others |
Value Chain & Pricing Dynamics
Quick-service restaurant procurement teams with 50-plus unit footprints anchor pricing power through consolidated RFPs, compressing margins for filtration equipment vendors while rewarding suppliers who bundle preventive maintenance contracts with hardware sales.
Pricing Analysis
Lead-time premiums command 15-25% markups for expedited electrostatic system delivery during retrofit peaks, while spot inventory of portable mechanical units trades at discounts to contract pricing. Three-tier pricing structure across premium electrostatic, standard in-line, and economy portable configurations reflects certification tier and after-sales bundling. Cost compression in stainless steel chassis fabrication is intensifying because nickel-alloy volatility feeds through to equipment margins. Independent restaurants exhibit highest price sensitivity; multi-unit chains with standardized protocols accept premium positioning for compliance documentation features.
Supply Chain Analysis
Single-source vulnerability sits with German stainless steel fabricators supplying pressure vessel components for vacuum filtration systems. Manufacturing concentrates in Germany, China, and the United States for finished equipment assembly. Raw material inputs draw from Indonesian nickel mines, Chinese rare earth processors for electrostatic ionization components, and domestic steel mills. Tariff exposure on nickel-alloy imports threatens margin stability for North American fabricators. Distribution runs through specialized foodservice equipment distributors with certified technician networks for installation and calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as REACH compliance costs and electrostatic R&D capital requirements force sub-scale mechanical filtration specialists toward exit or acquisition.
For Market Incumbents: Anticipate displacement of traditional filter paper revenue by securing ionization chamber replacement contracts and predictive maintenance platform subscriptions. Backward integration into activated clay sourcing defends margin position against REACH-driven media reformulation costs. Channel control through direct procurement relationships with multi-unit chains locks out bundling competitors. For New Entrants and Emerging Players: Enter via ghost kitchen infrastructure in urban France and Spain, where standardized filtration protocols remain underdeployed. India's FSSAI enforcement in Mumbai and Bangalore quick-service clusters offers regulatory tailwind penetration. Position around compact portable electrostatic units with minimal consumable requirements for mobile food truck operators. For Investors and Strategic Acquirers: The window for entry favors filtration-as-a-service platform operators with IoT-enabled predictive maintenance capabilities. Target acquisition archetypes include regional stainless steel fabricators with certified technician networks and electrostatic technology specialists with UL/CE/NSF approval sequencing expertise. Watch for ionization chamber calibration service contract attach rates as inflection indicator of platform stickiness.| Strategic Initiative | Industry Significance |
|---|---|
| Electrostatic Technology Licensing | Henny Penny's R&D programs accelerate chemical-free system deployment across California quick-service chains. |
| Preventive Maintenance Platform Launch | IoT-enabled oil quality monitoring supports FDA Food Code documentation mandates for franchise operators. |
| Backward Integration into Filtration Media | Vertical control over activated clay sourcing mitigates REACH compliance timeline extensions for cross-border suppliers. |
| Ghost Kitchen First-Mover Installation | Delivery-only facilities in Paris and Lyon lack standardized protocols, creating equipment sales white space. |
| Certification Pre-Approval Investment | Sequenced UL, CE, and NSF approvals compress order-to-delivery gaps for electrostatic retrofit contracts. |
Study Parameters
Trade association filings, EU Ecodesign regulatory databases, and FDA Food Code documentation standards formed the secondary backbone for market sizing and compliance trajectory mapping. Primary interviews with quick-service restaurant procurement directors, commercial kitchen equipment distributors, and filtration system maintenance technicians validated equipment deployment patterns and service contract structures. Bottom-up unit economics triangulated against top-down foodservice capital expenditure estimates anchored volume projections.
Bottom-up modeling built from individual operator filtration system specifications, replacement cycles, and service contract attach rates across portable, in-line, vacuum, and centrifugal configurations. Top-down validation cross-referenced foodservice equipment industry reports and stainless steel fabrication output data. CAGRs derived from regression analysis of historical equipment shipments against frying oil price indices and regulatory enforcement intensity. Segmentation dimensions spanned product type, technology category, end-user vertical, and service model across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated electrostatic adoption or extended REACH recertification delays. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Food Industry Vacuum Cooling Equipment Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Deaeration Machine Market