
 Industrial Food Slicers Market | 2026-2036
Industrial Food Slicers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Food Slicers Market Outlook
Modular blade-cartridge systems are decoupling slicing hardware from sanitation service contracts, forcing buyers to evaluate total cost of ownership across discrete component lifecycles. Urschel Laboratories leverages its vertical integration into custom cutting tool metallurgy to sustain premium positioning in high-volume cheese and vegetable processing. GEA Group anchors European demand through integrated line solutions that combine slicing with downstream packaging, while Bizerba differentiates via precision weighing-slicing hybrids for deli-counter automation.
Industrial food slicers are electromechanical or pneumatic cutting machines designed to portion meat, cheese, bread, and produce at throughputs exceeding 500 kg per hour, with blade diameters typically ranging from 250 mm to 400 mm and stainless-steel construction rated for IP69K washdown protocols. Their primary commercial purpose is to replace manual cutting with repeatable thickness control, yield optimization, and labor reduction in high-volume food manufacturing. Automatic slicers dominate installed base value due to continuous-feed designs that integrate with upstream forming and downstream packaging lines, while multi-functional slicers represent the fastest-expanding configuration as processors seek format flexibility across protein, dairy, and bakery applications. Gravity slicers occupy a mature niche in retail deli environments where space constraints and intermittent batch sizes limit capital deployment.
USDA FSIS inspection guidelines mandate clean-in-place compatibility and allergen-control documentation for slicing equipment used in federally inspected facilities, while NSF/ANSI standards govern hygienic design validation for commercial kitchen deployments. The EU Machinery Directive and CE marking requirements enforce interlock systems and noise exposure limits on slicers sold throughout Europe, shaping R&D allocation toward operator safety engineering. Stakeholders must monitor evolving MDR-equivalent pressures on food-contact materials and decide whether to front-load stainless-steel alloy certifications or pursue modular retrofit strategies that extend incumbent equipment compliance windows.
Market Dynamics
Modular blade-cartridge architectures are fragmenting equipment ownership models across North American protein processing, compelling operators to treat slicing hardware as service-managed infrastructure rather than depreciable capital assets.
Growth Catalysts
- USDA FSIS Clean-in-Place Mandates:Federally inspected meat facilities must document allergen-control protocols for slicing equipment, accelerating replacement cycles in legacy plants.
- Precision Weighing-Slicing Convergence:Deli-counter automation demands gram-accurate portioning integrated with blade systems, pulling capital into retail-format machinery.
- Germany:Weber Maschinenbau and Bizerba anchor engineering clusters that export precision cutting technology to global protein processors.
Market Restraints
- Stainless-Steel Alloy Volatility:Nickel and molybdenum price swings compress margins on IP69K-rated washdown equipment, forcing hedging strategies or specification downgrades.
- CE Marking Compliance Burden:EU Machinery Directive interlock and noise-limit requirements extend R&D timelines for European-market entrants by 8-14 months.
- Manual Cutting Substitution:Low-wage processing jurisdictions in Southeast Asia retain hand-slicing for artisanal charcuterie, capping automatic slicer penetration.
Strategic Opportunities
- Plant-Based Protein Formats:Extruded mycelium and textured vegetable proteins require novel blade geometries optimized for fibrous, non-uniform structures absent in animal muscle.
- NSF/ANSI 169 Equipment Certification:Commercial kitchen operators increasingly specify validated hygienic design, creating premium positioning for certified manufacturers.
- Remote Diagnostics Integration:IoT-enabled vibration monitoring and predictive blade-wear algorithms enable outcome-based service contracts that capture recurring revenue streams.
Industry Challenges
- IP69K Validation Bottlenecks:Third-party washdown certification testing capacity constraints delay product launches by 4-6 months during peak demand periods.
- Legacy Pneumatic System Integration:Electromechanical slicer retrofits into existing compressed-air line architectures require custom mechanical engineering that extends deployment timelines.
- Multi-Species Contamination Protocols:Pork-beef-poultry sequence changes demand rapid blade-cartridge swaps with full traceability documentation, straining operator training programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Food Slicers Market |
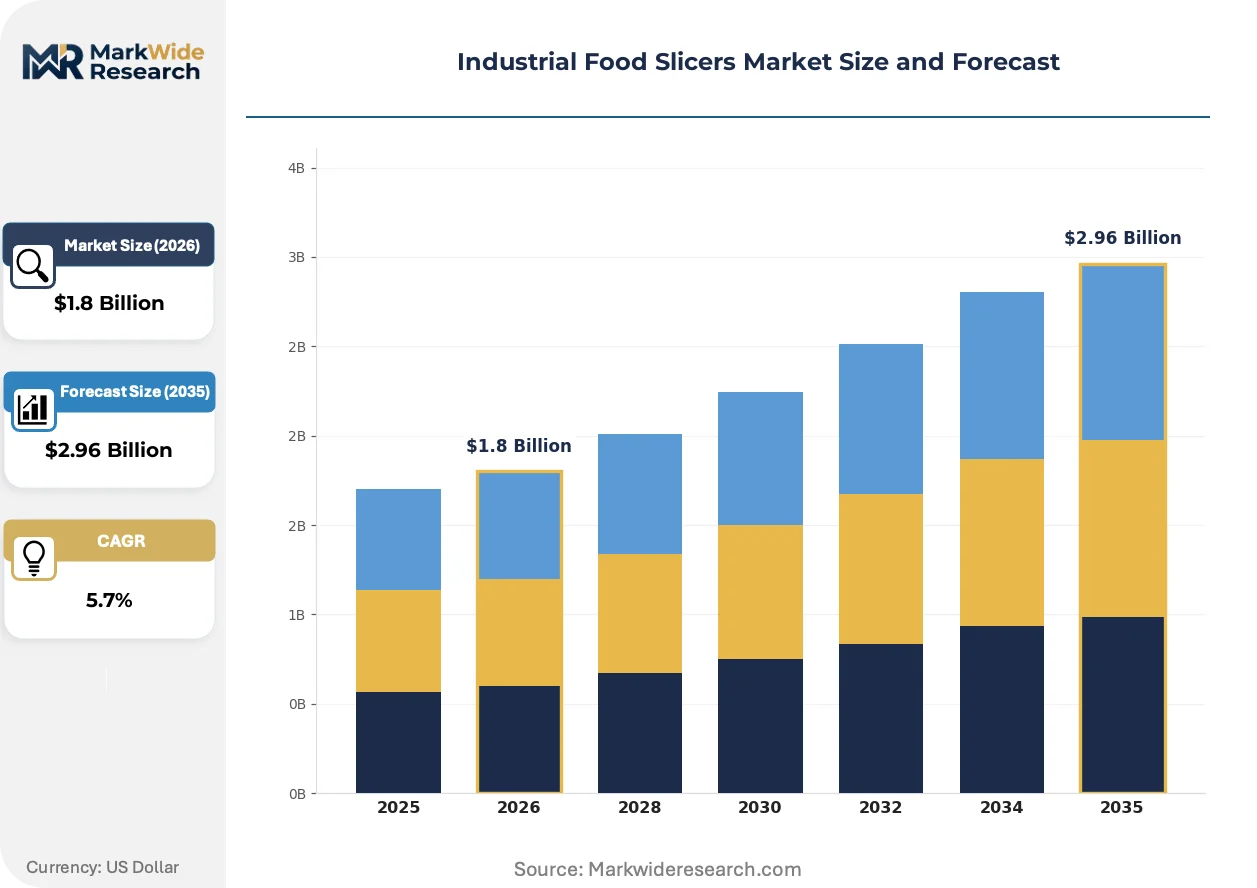
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Slicers, Manual Slicers, Multi-functional Slicers, Gravity Slicers End User: Restaurants, Supermarkets, Food Processing Plants, Catering Services Technology: Electric Slicers, Pneumatic Slicers, Blades, Laser Cutters Size: Small, Medium, Large, Industrial |
| Companies Covered | Urschel Laboratories, GEA Group, Globe Food Equipment, Bizerba, Weber Maschinenbau, BIRO Manufacturing, FAM, TREIF Maschinenbau, Grote Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Food Slicers Market Strategic Shifts
Equipment intelligence and regulatory stringency are converging to reshape how slicing machinery is specified, financed, and maintained across protein, dairy, and bakery verticals.
Vision-guided portioning systems using hyperspectral imaging are automating real-time fat-lean ratio detection in fresh meat blocks. Large North American beef processors are deploying these systems at greenfield facilities with throughputs exceeding 2,000 kg per hour. This capability is automating yield optimization that previously required skilled manual trimmers, compressing labor cost structures in high-volume operations.
REACH restrictions on food-contact chromium compounds are accelerating tungsten-carbide and ceramic blade coating adoption across EU-destined equipment. Manufacturers must reformulate surface treatments or risk market exclusion under evolving ECHA substance evaluations. German and Dutch slicing equipment exporters are front-loading material certifications to maintain continental market access.
Service-unbundling is separating blade sharpening, metallurgical refurbishment, and sanitation validation into discrete purchase decisions. Foodservice distributors now compete with OEM service arms for aftermarket attach rates. This pattern is most visible in US retail deli chains where equipment leasing and maintenance are sourced through separate procurement channels.
Industrial Food Slicers Market Segmentation
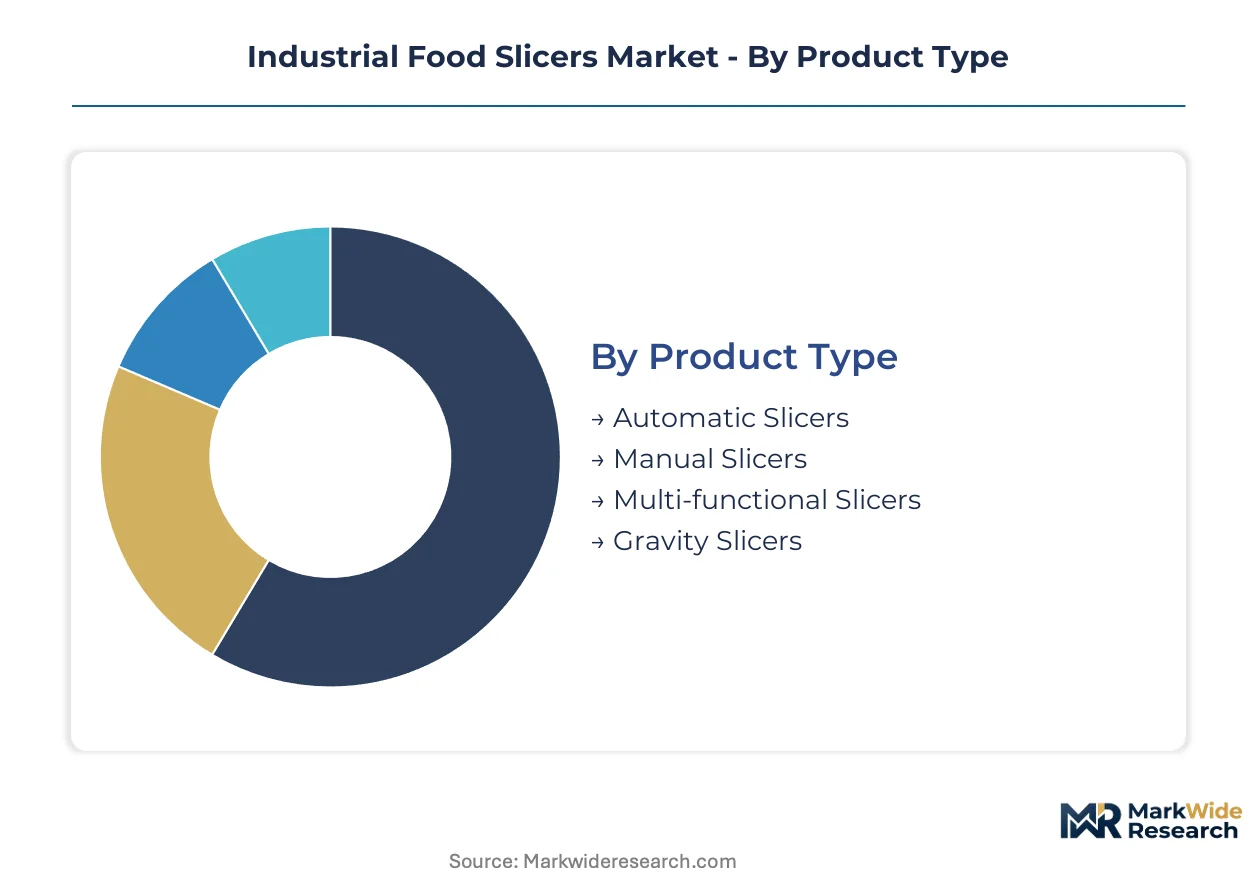
Industrial food slicer procurement patterns diverge sharply across equipment configurations, end-use environments, and power architectures. Understanding these splits reveals where capital deployment concentrates and where specification flexibility creates competitive advantage.
Product Type:
Supply concentration in automatic slicing systems shapes how OEMs allocate R&D budgets and service infrastructure across hardware tiers.
- Automatic Slicers:Continuous-feed electromechanical designs integrate with upstream forming and downstream packaging lines. Demand clusters in North American beef processing plants where USDA FSIS mandates accelerate replacement cycles in legacy facilities.
- Multi-functional Slicers:Modular architectures enable format switching across protein, dairy, and bakery applications without full line reconfiguration. German engineering clusters at Weber Maschinenbau and Bizerba anchor precision development for this configuration.
- Manual Slicers:Hand-fed designs persist in Southeast Asian artisanal charcuterie operations where labor cost structures resist capital substitution.
- Gravity Slicers:Space-constrained retail deli environments in US supermarket chains deploy these for intermittent batch processing.
Today's leader: Automatic Slicers. Tomorrow's challenger: Multi-functional Slicers.
End User:
Cost tier differentiation separates specification requirements across customer types, from NSF-certified commercial kitchens to IP69K-rated industrial washdown environments.
- Food Processing Plants:Federally inspected meat facilities require clean-in-place compatibility and allergen-control documentation. USDA FSIS protocols drive capital intensity here.
- Supermarkets:Deli-counter automation demands gram-accurate portioning integrated with blade systems. Precision weighing-slicing hybrids dominate this tier.
- Restaurants:Commercial kitchen operators specify NSF/ANSI 169 validated hygienic design, creating premium positioning for certified manufacturers.
- Catering Services:Mobile and event-driven operations prioritize compact footprints and rapid sanitation turnaround over throughput maximization.
Volume concentrates in Food Processing Plants. Margin expansion potential sits with Supermarkets.
Technology:
Application-specific cutting demands determine whether electromechanical precision, pneumatic force, or advanced blade materials deliver optimal yield.
- Electric Slicers:Servo-motor drives enable programmable thickness control with repeatability below 0.5 millimeters. These systems dominate high-volume cheese and vegetable processing where Urschel Laboratories leverages captive metallurgy capabilities.
- Blades:Tungsten-carbide and ceramic coatings are displacing chromium compounds under REACH restrictions. German and Dutch exporters front-load material certifications to maintain EU market access.
- Pneumatic Slicers:Compressed-air actuation persists in legacy plant architectures where electromechanical retrofits require custom mechanical engineering.
- Laser Cutters:Thermal portioning remains niche for specialized protein geometries where mechanical blade contact compromises product integrity.
Electric Slicers command installed base value. Blade material innovation is climbing the fastest.
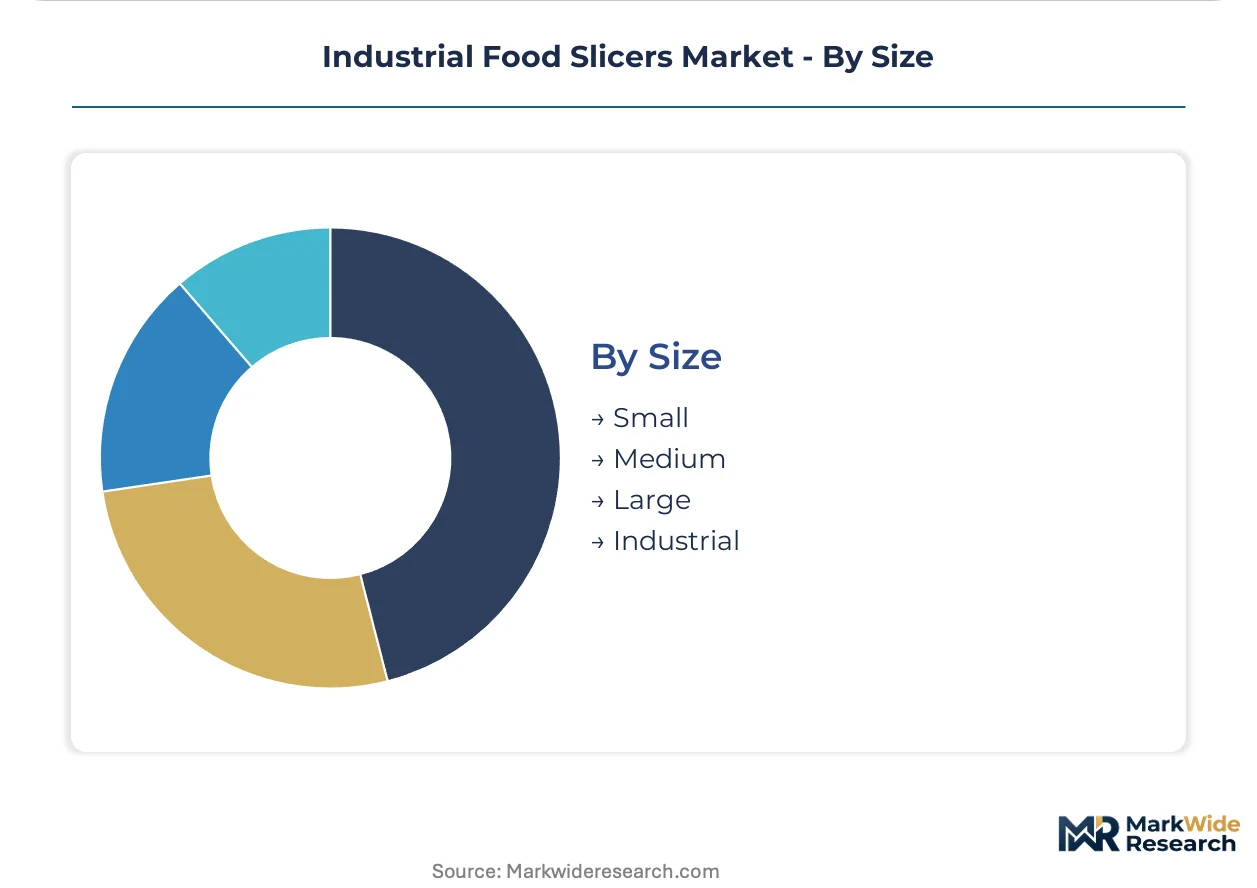
Size:
Customer type and facility constraints dictate scale, from countertop units to integrated line solutions spanning entire production halls.
- Industrial:Throughput exceeding 2,000 kilograms per hour with blade diameters of 300-400 millimeters. Large North American beef processors deploy these at greenfield facilities with vision-guided portioning systems.
- Large:Mid-tier operations in regional protein processing balance capital efficiency with format flexibility.
- Medium:Independent dairy processors and bakery cooperatives specify these for batch-scale artisanal production.
- Small:Space-constrained retail and catering environments where intermittent use patterns limit depreciation recovery.
Industrial scale captures capital deployment. Medium units are expanding most quickly in specialty food manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering houses pioneered precision cutting machinery for protein processing during the post-war industrial expansion. Their technical legacy now diffuses through regional manufacturing clusters across three continents.
Germany
Precision engineering clusters in Bavaria and Baden-Württemberg dominate high-end automatic slicer development for global export. CE marking requirements under the EU Machinery Directive enforce interlock systems and noise exposure limits that shape R&D allocation toward operator safety engineering. Weber Maschinenbau and Bizerba anchor this concentration, supplying integrated weighing-slicing hybrids to deli-counter automation projects worldwide.
United States
USDA FSIS inspection protocols mandate clean-in-place compatibility and allergen-control documentation for slicing equipment in federally inspected facilities. Large beef processors in Nebraska and Texas deploy vision-guided portioning systems at greenfield facilities exceeding 2,000 kg per hour throughput. NSF/ANSI standards govern hygienic design validation for commercial kitchen deployments across supermarket deli chains.
China
Domestic food processing expansion drives demand for mid-tier electromechanical slicers in regional protein and dairy operations. GB standards and SAMR oversight shape equipment safety certifications for both domestic consumption and export manufacturing. Yangtze River Delta fabrication clusters supply cost-optimized slicing machinery to Southeast Asian markets where labor cost structures resist full automation.
Netherlands
Dutch equipment exporters front-load material certifications to maintain EU market access under evolving ECHA substance evaluations. REACH restrictions on food-contact chromium compounds accelerate tungsten-carbide and ceramic blade coating adoption across Randstad engineering centers. Integrated line solutions that combine slicing with downstream packaging dominate capital deployment in dairy processing cooperatives.
Japan
Meticulous portioning requirements in prepared food manufacturing sustain demand for gram-accurate slicing systems. METI industrial standards and JIS certification protocols ensure equipment reliability for high-mix, low-volume production environments. Osaka-based machinery specialists serve domestic convenience store supply chains with compact, rapid-sanitation designs optimized for intermittent batch processing.
Industrial Food Slicers Market Competitive Environment
The competitive structure tilts toward precision-engineering specialists with captive metallurgy capabilities. Consolidation pressure concentrates around integrated line solution providers and modular component architects. Two strategic archetypes dominate: vertically integrated precision manufacturers controlling blade material supply chains, and systems integrators bundling slicing with packaging automation. Geographic expansion through distributor partnerships and technology licensing agreements constitute the primary competitive moves.
Among German precision-engineering specialists, Weber Maschinenbau GmbH and Bizerba SE & Co. KG exemplify the integrated-weighing-slicing hybrid archetype, while Urschel Laboratories Inc. occupies a position representing captive cutting-tool metallurgy capabilities. These three anchors demonstrate how regional engineering heritage translates into differentiated equipment architectures across protein, dairy, and bakery verticals.
| Leading Market Players |
|---|
| Urschel Laboratories |
| GEA Group |
| Globe Food Equipment |
| Bizerba |
| Weber Maschinenbau |
| BIRO Manufacturing |
| FAM |
| TREIF Maschinenbau |
| Grote Company |
| Others |
Value Chain & Pricing Dynamics
USDA FSIS clean-in-place mandates and NSF/ANSI 169 certification requirements are forcing equipment buyers to absorb premium-grade stainless-steel specifications and validated hygienic design protocols. Supply chains must front-load metallurgical certifications and third-party washdown testing capacity, compressing margin structures for non-integrated manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement. Premium tiers capture IP69K-rated washdown validation and integrated weighing-slicing hybrids; standard tiers serve mid-volume processors with electric servo-motor drives; economy tiers supply gravity-fed retail deli units. Cost compression in the standard tier is intensifying because nickel and molybdenum price volatility erodes alloy margins. Food processing plants exhibit lowest price sensitivity due to regulatory non-compliance risk; catering services and small independent restaurants show highest sensitivity to capital outlay.
Supply Chain Analysis
Skilled precision-engineering labor availability in Bavaria and Baden-Württemberg, coupled with technical workforce density in Nebraska and Texas, anchors global production capacity. Supply chains draw from German blade-metallurgy clusters, Dutch integrated-line engineering centers, and Chinese mid-tier fabrication in the Yangtze River Delta. Raw material dependencies center on nickel-molybdenum stainless-steel alloys, tungsten-carbide blade coatings, and ceramic surface treatments. Single-source vulnerability concentrates in third-party IP69K certification testing capacity. Distribution runs through OEM direct sales for large processing plants and foodservice distributor networks for retail and commercial kitchen segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Industrial Food Slicers Market functions as a stable compounder. Regulatory ratcheting on food-contact materials and sanitation protocols sustains replacement-cycle demand regardless of protein price cycles.
For Market Incumbents: Acquire captive blade-metallurgy capabilities to defend against Urschel Laboratories' upstream integration advantage. Consolidate service infrastructure around predictive blade-wear algorithms and IoT-enabled vibration monitoring to capture recurring revenue streams. Offset margin pressure from REACH-compliant coating transitions by bundling sanitation validation into multi-year equipment leases. For New Entrants and Emerging Players: Vision-guided portioning systems with hyperspectral imaging offer technology-first entry into North American beef processing greenfield deployments. Plant-based protein formats present white-space opportunity where novel blade geometries for fibrous mycelium structures remain underdeveloped. Pursue outcome-based service contracts with regional dairy cooperatives rather than capital-equipment sales to bypass incumbent OEM relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with modular component architects controlling blade-cartridge standardization rather than full-system integrators. Five-to-ten-year viability favors precision-engineering specialists with captive metallurgy and validated hygienic design portfolios. Watch for IP69K certification testing capacity expansion announcements as inflection indicator for product launch velocity and market share capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blade Metallurgy | Captive supply of tungsten-carbide coatings insulates margins from REACH-driven chromium substitution costs. |
| IoT-Enabled Predictive Maintenance Platform | Vibration monitoring algorithms enable outcome-based service contracts with food processing plant maintenance directors. |
| NSF/ANSI 169 Certification Acceleration | Validated hygienic design unlocks premium positioning in commercial kitchen procurement specifications. |
| Plant-Based Protein Blade Geometry Development | Novel cutting surfaces for extruded mycelium capture share in fastest-expanding protein format vertical. |
| Regional Service Hub Expansion | Proximity maintenance infrastructure reduces downtime penalties for USDA-inspected facilities under FSIS protocols. |
Study Parameters
Multiple input streams — structured interviews with plant engineers and maintenance directors, aftermarket service heads at OEMs, and procurement leads at protein processing cooperatives — were reconciled against trade data from customs records, USDA FSIS facility registration databases, and EU Machinery Directive compliance filings. Secondary validation incorporated NSF/ANSI equipment certification registries, ECHA substance evaluation updates, and SEC 10-K disclosures from listed food equipment manufacturers. Bottom-up equipment unit economics and top-down protein processing capacity expansion plans were triangulated to establish market sizing boundaries.
Data-stream reconciliation across the projection horizon applied segment-specific growth coefficients to automatic slicer, multi-functional slicer, manual slicer, and gravity slicer configurations. Technology splits modeled electric, pneumatic, and advanced blade material penetration. End-use segmentation captured food processing plant, supermarket, restaurant, and catering service demand patterns. CAGRs were derived from replacement-cycle analysis tied to regulatory compliance deadlines and greenfield capacity announcements. Forecast inputs incorporated nickel-molybdenum price trajectory assumptions and third-party washdown certification testing capacity constraints.
The model holds under stable regulatory enforcement intensity and continuous protein processing capacity expansion; deviation in ECHA substance evaluation acceleration or USDA FSIS mandate postponement would shift replacement-cycle timing. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Decanter Centrifuge Market
Food Processing Equipment
Mixing Vessels Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
Mushroom Fermenter Market
Food Processing Equipment
Pasta Machine Market