
 Planetary Mixer Market | 2026-2036
Planetary Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Planetary Mixer Market Outlook
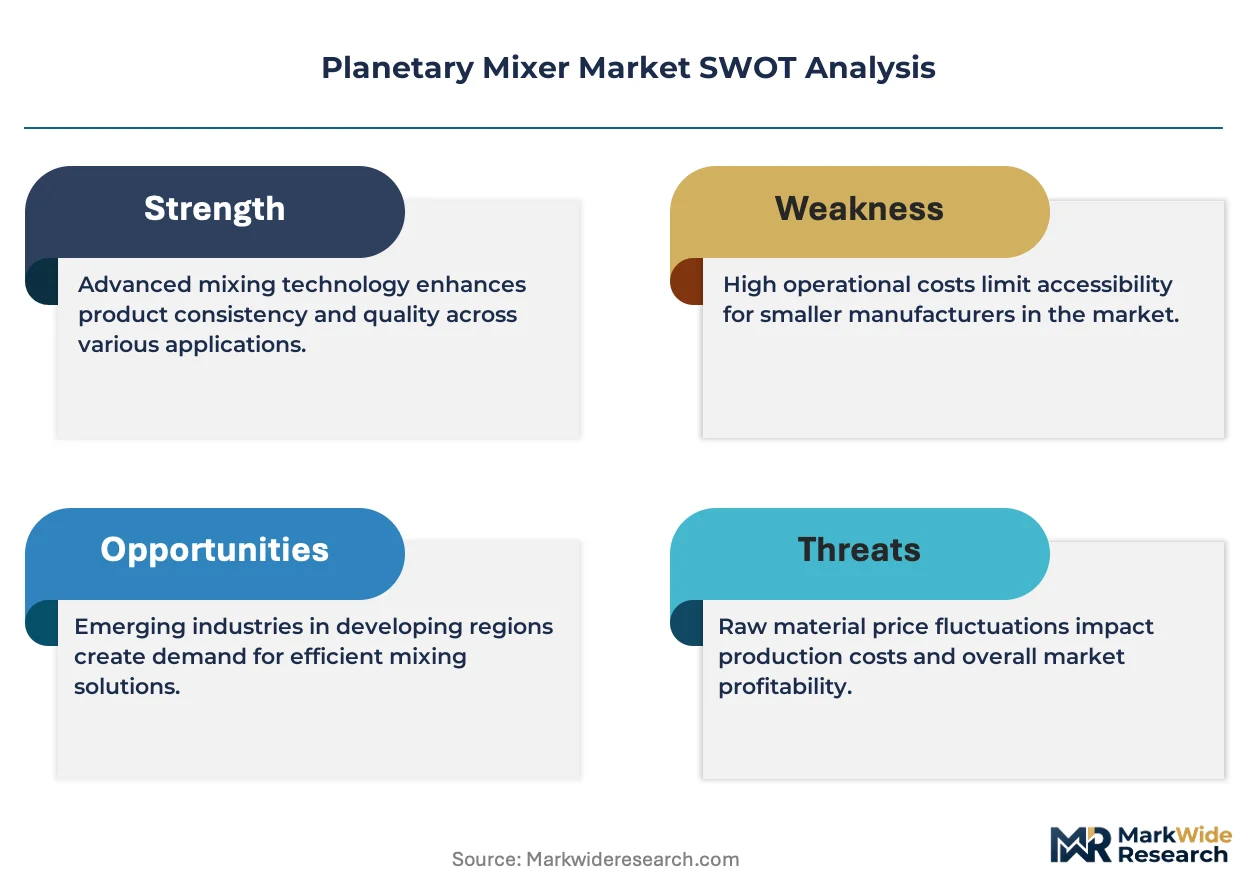
Variable-frequency drive integration is tilting planetary mixer design toward precision torque control and energy recovery. Hobart Corporation leverages its century-long installed base in North American commercial kitchens to sustain aftermarket parts revenue. ROSS Mixers anchors its position in chemical and pharmaceutical processing with heavy-duty agitator configurations that handle viscous, abrasive slurries. Robot Coupe SAS competes in the European compact-equipment segment with countertop units designed for high-turnover patisseries and central commissaries.
A planetary mixer employs an epicyclic agitation pattern in which a mixing tool rotates on its own axis while orbiting a stationary bowl, typically achieving tip speeds of 50–300 rpm and handling batch volumes from 5 to 600 liters depending on frame construction. Its primary purpose is to homogenize multi-phase materials—doughs, batters, pastes, suspensions—without shear damage to sensitive ingredients. Batch mixers occupy the dominant share of food processing installations where recipe flexibility and allergen control matter, while continuous mixers are gaining ground in chemical manufacturing lines that run dedicated product streams for extended campaigns. Laboratory mixers represent a concentrated margin pool serving pharmaceutical formulation development and quality-assurance protocols.
Food contact equipment in the United States falls under FDA 21 CFR standards for material safety, while European manufacturers must comply with EFSA guidelines and CE machinery directives for electrical and mechanical guarding. OSHA lockout/tagout rules and EU machinery safety regulations shape guard interlock designs and maintenance access panel configurations on industrial units. Stakeholders should monitor how evolving Ecodesign requirements and emerging state-level energy efficiency mandates in California and New York reshape motor specifications and drive retrofit economics for installed base equipment.
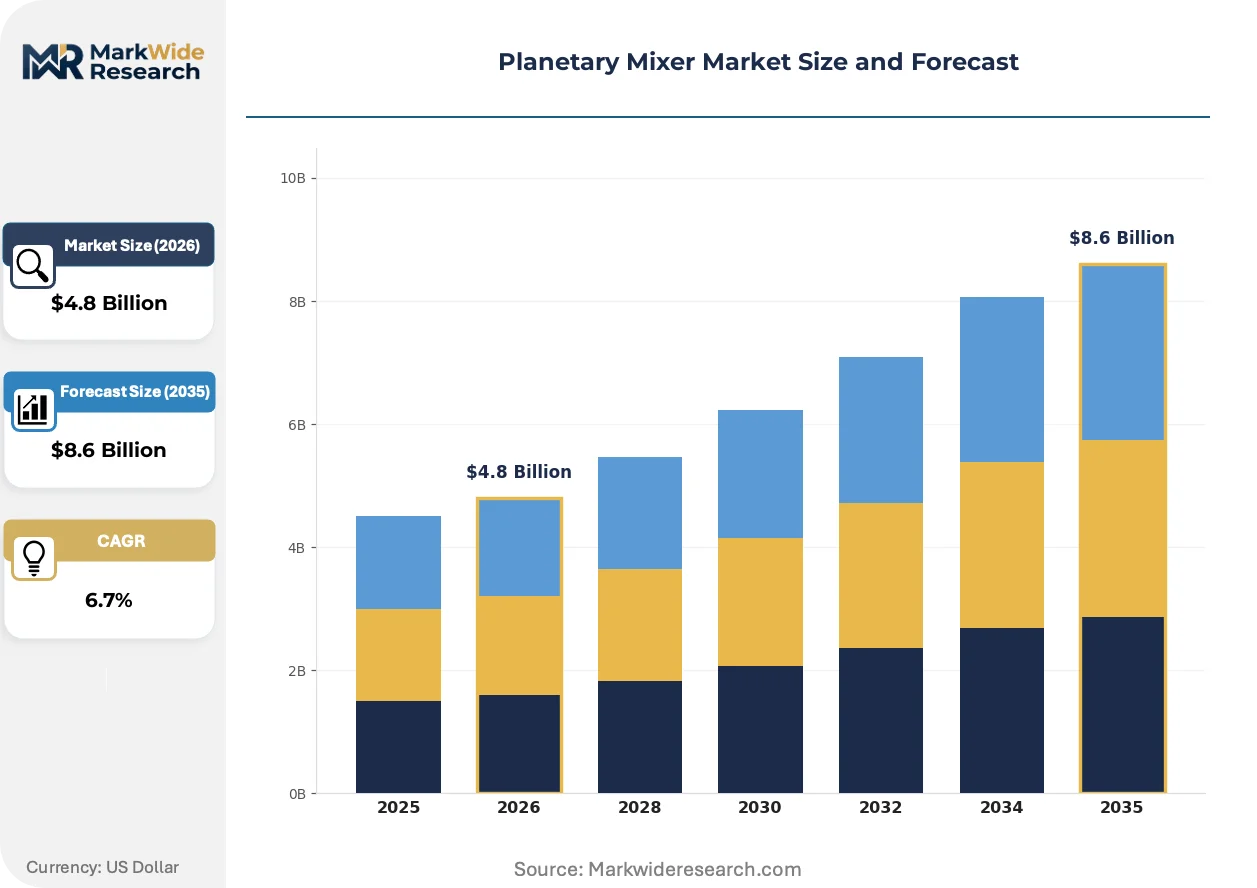
Market Dynamics
Variable-frequency drive technology is forcing a wholesale redesign of planetary mixer electromechanical architectures, compressing energy consumption while expanding torque precision across batch sizes from laboratory to industrial scale.
Growth Catalysts
- FDA 21 CFR Material Compliance:Food contact surface mandates in the United States are accelerating stainless steel adoption, eliminating legacy cast-iron components from commercial bakery equipment procurement specifications.
- Artisan Bakery Expansion:Specialty baked goods production lines in Germany and Japan are driving automated mixing equipment installations to meet consumer preference for premium texture and consistency.
- Energy Recovery Systems:Regenerative braking in variable-speed drives is capturing waste kinetic energy, reducing operational costs for high-volume confectionery operations.
Market Restraints
- Electrical Steel Supply Concentration:Motor core laminations depend on specialized silicon steel production concentrated in East Asian foundries, exposing equipment manufacturers to input cost volatility and extended lead times.
- CE Machinery Directive Certification Burden:European safety interlock and guarding requirements impose extended validation timelines, delaying product launches for compact countertop unit segments.
- Continuous Mixer Substitution:Dedicated chemical processing lines are migrating from batch planetary configurations to single-screw and twin-screw extrusion systems for extended production campaigns.
Strategic Opportunities
- California Energy Efficiency Mandates:State-level motor performance standards are creating retrofit demand for variable-frequency drive upgrades across installed base equipment in commercial kitchens.
- Pharmaceutical Formulation Services:Contract development and manufacturing organizations are expanding laboratory-scale mixer procurement for quality-assurance protocols and small-batch validation.
- Central Commissary Channel:High-turnover patisseries and foodservice operators are consolidating production into centralized facilities, expanding demand for 200-600 liter frame constructions.
Industry Challenges
- Electromechanical Integration Complexity:Precision torque control systems require specialized commissioning expertise that remains scarce in field service organizations across secondary markets.
- Allergen Control Protocol Certification:Bakery and confectionery operators demand rapid changeover validation, compressing equipment qualification timelines and straining manufacturer technical support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Planetary Mixer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Mixers, Continuous Mixers, Multi-Function Mixers, Laboratory Mixers Application: Food Processing, Chemical Manufacturing, Pharmaceutical Production, Construction Materials End User: Bakeries, Confectioneries, Cosmetic Manufacturers, Automotive Suppliers Technology: Electromechanical, Pneumatic, Hydraulic, Manual |
| Companies Covered | Voeller Mixers, Robot Coupe SAS, Hobart Corporation, Unifiller Systems, Kitchenaid, Univex Corporation, ROSS Mixers, Mirabake, Varimixer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Planetary Mixer Market Strategic Shifts
Digital twin technology is virtualizing equipment performance before physical commissioning, compressing design validation cycles and enabling predictive maintenance architectures across planetary mixer installations.
Digital twin platforms are replicating electromechanical behavior in cloud-based simulation environments, allowing manufacturers to validate torque profiles and thermal loading without physical prototyping. Industrial bakeries in Germany are piloting these systems for production line optimization, reducing commissioning downtime by enabling virtual operator training. This capability is virtualizing the traditional equipment qualification process, shifting competitive advantage toward software-integrated hardware suppliers.
REACH substance restrictions are eliminating certain polymer formulations from food contact seals and gaskets, forcing reformulation of bowl scraper and shaft seal assemblies. Equipment manufacturers serving European confectionery processors must document full material composition chains, extending supplier audit requirements. The laboratory mixer segment faces the steepest compliance burden, as pharmaceutical quality-assurance protocols demand traceable material certifications for every contact surface component.
After-sales service unbundling is fragmenting traditional equipment procurement into separate hardware, installation, and maintenance contracts. Large bakery chains in the United States are negotiating direct spare parts sourcing agreements, bypassing manufacturer service networks for routine maintenance items. This pattern concentrates in high-volume operations with in-house technical staff, while smaller patisseries retain bundled service relationships for warranty compliance and technical support access.
Planetary Mixer Market Segmentation
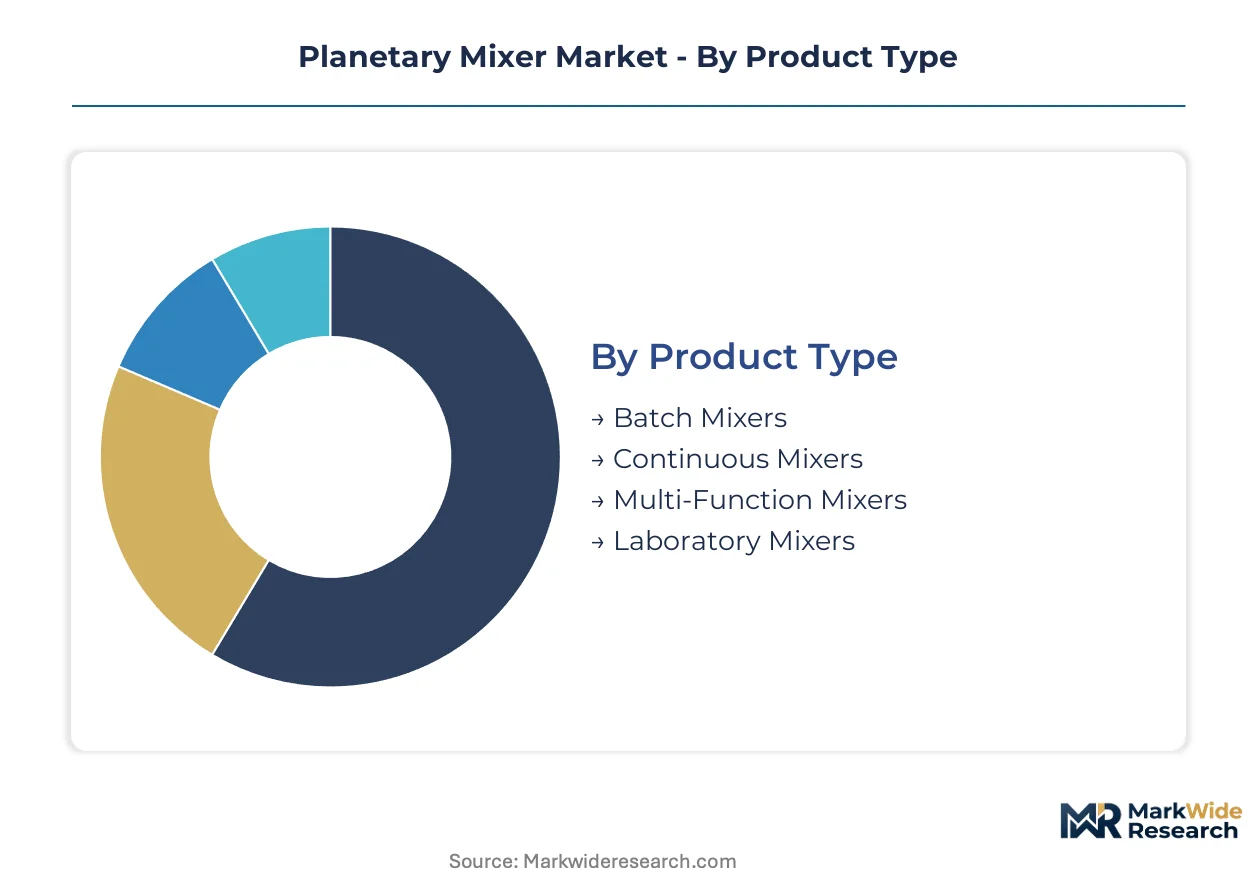
Planetary mixer procurement varies sharply by operational tempo—bakeries cycle equipment every 7-10 years while pharmaceutical laboratories refresh on 3-5 year validation schedules. Segmentation reveals where capital concentrates versus where replacement revenue flows fastest.
Product Type:
Batch configurations turn over slowest due to mechanical simplicity and field-serviceability, while laboratory units refresh fastest driven by protocol updates and contamination sensitivity.
- Batch Mixers:Stationary bowl designs with orbiting agitator heads handle 5-600 liter volumes across stainless steel contact surfaces. Demand clusters in German artisan bakeries and Japanese confectionery processors where recipe flexibility and allergen isolation protocols predominate.
- Continuous Mixers:Twin-screw and single-screw extrusion systems displace planetary configurations in dedicated chemical processing lines running extended campaigns without changeover. These units sacrifice flexibility for throughput consistency in high-volume polymer and adhesive manufacturing.
- Multi-Function Mixers:Modular head attachments enable dough hook, paddle, and whisk interchangeability for central commissaries serving diverse menu portfolios.
- Laboratory Mixers:Benchtop 1-20 liter units with precision torque logging support pharmaceutical formulation development and quality-assurance validation protocols.
Batch Mixers dominate installed base. Laboratory Mixers are where expansion concentrates.
Application:
Cost tier stratification separates premium pharmaceutical specifications from standard food-grade and economy construction-grade configurations.
- Food Processing:FDA 21 CFR material compliance mandates stainless steel contact surfaces, eliminating legacy cast-iron from commercial bakery procurement specifications. EFSA guidelines in Europe enforce parallel material traceability requirements for confectionery processors.
- Chemical Manufacturing:Abrasive slurry handling demands heavy-duty agitator configurations with hardened shaft seals and variable-frequency drive integration for viscosity-responsive torque control.
- Pharmaceutical Production:cGMP documentation requirements and isolator-compatible designs command 3-4x capital premiums over food-grade equivalents.
- Construction Materials:Grout, mortar, and sealant mixing tolerates economy electromechanical drives with minimal guarding sophistication.
Food Processing anchors volume demand. Pharmaceutical Production captures margin concentration.
End User:
Customer type determines service bundling preferences—large chains unbundle maintenance while independent operators retain bundled warranty relationships.
- Bakeries:High-turnover operations in the United States and Germany are consolidating into central commissaries, shifting demand toward 200-600 liter frame constructions with rapid changeover validation protocols.
- Confectioneries:Specialty chocolate and pastry producers in Japan require precision temperature control and gentle agitation for shear-sensitive ingredients.
- Cosmetic Manufacturers:Cream, lotion, and emulsion production demands sanitary-grade finishes with FDA-compliant seals and documented material certifications.
- Automotive Suppliers:Sealant and adhesive compounders prioritize throughput consistency over recipe flexibility in dedicated production lines.
Bakeries represent the largest addressable base. Confectioneries are climbing the fastest on premium texture demand.
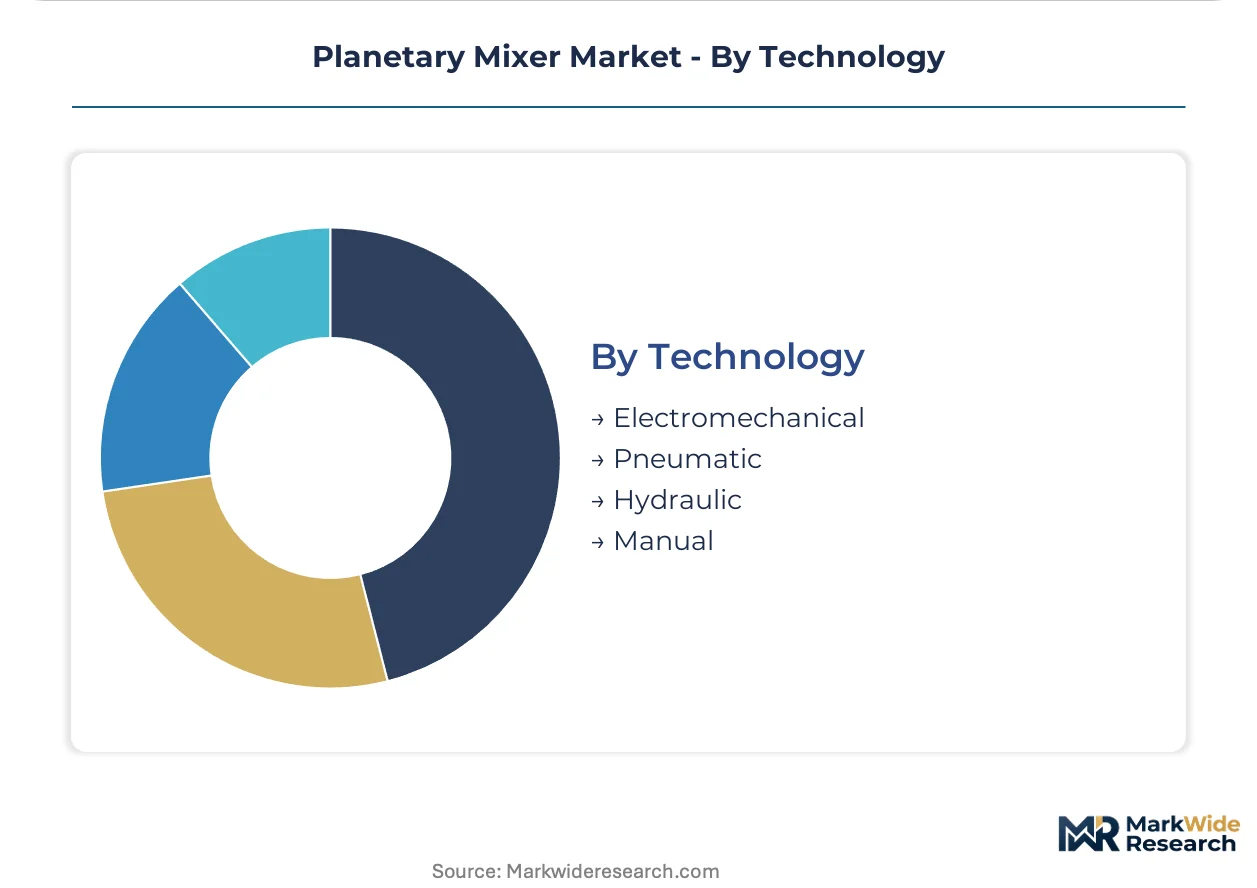
Technology:
Supply concentration in East Asian electrical steel foundries shapes motor cost trajectories across drive architectures.
- Electromechanical:Variable-frequency drive integration enables precision torque control and regenerative braking for energy recovery in high-volume operations. California and New York state mandates are accelerating retrofit demand across installed base equipment.
- Pneumatic:Explosion-proof configurations serve solvent-laden chemical and coating applications where electrical ignition risks predominate.
- Hydraulic:Ultra-high-viscosity material handling in construction sealants and heavy chemical pastes requires hydraulic power density beyond electromechanical limits.
- Manual:Countertop crank-operated units persist in developing market micro-enterprises with unreliable electrical infrastructure.
Electromechanical dominates new installations. Pneumatic holds defensive position in hazardous environment niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export precision planetary mixers to Japanese confectionery processors, sustaining a transcontinental trade corridor that channels European engineering into Asian specialty food production.
United States
Commercial bakery chains and central commissaries in California and New York drive demand for 200-600 liter electromechanical units. FDA 21 CFR material compliance mandates eliminate cast-iron components from procurement specifications. The Chicago metropolitan area anchors Midwest food equipment distribution, with retrofit specialists servicing installed base variable-frequency drive upgrades.
Germany
Artisan bakeries in Bavaria and North Rhine-Westphalia automate mixing lines to meet premium texture demand. EFSA guidelines and CE machinery directives enforce strict material traceability and safety interlock standards. The Stuttgart industrial cluster hosts precision drive component suppliers serving planetary mixer OEMs with torque control systems.
Japan
Specialty chocolate and pastry producers require gentle agitation for shear-sensitive ingredients. METI industrial standards shape equipment performance benchmarks for food processing machinery. The Kansai region around Osaka concentrates confectionery manufacturing, importing German-engineered batch mixers for high-turnover patisserie operations.
China
Domestic bakery chain expansion and central kitchen consolidation create demand for mid-capacity stainless steel units. GB standards and SAMR food safety regulations govern material compliance for edible product contact surfaces. The Yangtze River Delta manufacturing belt produces electrical steel laminations and variable-frequency drive components for regional equipment assembly.
India
Organized bakery retail and QSR central commissaries expand automated mixing capacity. FSSAI food safety standards mandate stainless steel contact surfaces for commercial food equipment. Maharashtra and Karnataka states concentrate food processing equipment demand, with Mumbai and Bangalore serving as procurement hubs for national bakery chains.
Planetary Mixer Market Competitive Environment
On the supply side, the industry is moderately consolidated around established electromechanical specialists and diversified food equipment conglomerates. Tiered competitive positioning separates premium precision manufacturers from volume-oriented fabricators and regional assembly operations. Strategic archetypes include century-scale installed base defenders, laboratory-scale precision specialists, and heavy-duty industrial agitation engineers. Dominant competitive moves encompass aftermarket parts network expansion and variable-frequency drive technology licensing arrangements.
Within the precision laboratory and compact equipment tier, Robot Coupe SAS and Varimixer exemplify European specialists serving high-turnover patisseries and quality-assurance protocols. ROSS Mixers occupies a position among heavy-duty industrial agitation engineers, anchoring the chemical and pharmaceutical processing segment with hardened configurations for abrasive slurry applications. Hobart Corporation represents the century-scale installed base defender archetype, sustaining aftermarket revenue through North American commercial kitchen equipment legacy relationships.
| Leading Market Players |
|---|
| Voeller Mixers |
| Robot Coupe SAS |
| Hobart Corporation |
| Unifiller Systems |
| Kitchenaid |
| Univex Corporation |
| ROSS Mixers |
| Mirabake |
| Varimixer |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Osaka maritime corridor carries stainless steel components and precision drive assemblies from German OEMs to Japanese confectionery processors, with freight cost volatility amplifying price spreads between electromechanical tiers and compressing margins on economy-grade cast-iron legacy equipment destined for developing markets.
Pricing Analysis
The technology-generation pricing gap separates variable-frequency drive units commanding premium positioning from fixed-speed legacy designs in steep discount and emerging next-generation servo-motor configurations in early-adopter pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with FDA 21 CFR compliance tiers extracting material cost premiums. Pricing pressure stems from East Asian motor component cost volatility. Construction-grade buyers exhibit highest price sensitivity; pharmaceutical laboratories show lowest.
Supply Chain Analysis
Electrical steel laminations and silicon steel feedstock draw from concentrated East Asian foundry capacity in China, Japan, and South Korea, with secondary sourcing from German specialty steel producers for precision laboratory units. Variable-frequency drive electronics, hardened shaft seals, and stainless steel contact surfaces constitute critical component dependencies. Single-source vulnerability in electrical steel exposes equipment OEMs to input cost spikes. Distribution runs through regional food equipment distributors and direct OEM relationships with central commissary chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Variable-frequency drive integration is disrupting electromechanical architectures across food processing and pharmaceutical applications, with California and New York state energy mandates accelerating retrofit demand that revalues installed base service relationships.
For Market Incumbents: Build installed base data moats through predictive maintenance platform deployment and aftermarket parts network densification. Defend against continuous mixer substitution in chemical processing by anchoring batch flexibility value propositions. Deepen backward integration into electrical steel sourcing partnerships to buffer East Asian supply concentration.
For New Entrants and Emerging Players: Compact laboratory mixers for contract development and manufacturing organizations in the United States and Europe represent the most penetrable entry point, with 1-20 liter precision torque logging configurations underserved by legacy pharmaceutical equipment suppliers. Target central commissary retrofits in California and New York where state mandates create upgrade urgency. Pursue white-label manufacturing partnerships with established drive component suppliers to compress R&D timelines.
For Investors and Strategic Acquirers: Precision drive component specialists with FDA-validated manufacturing processes and established EFSA material certification pathways offer the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on software-integrated hardware capabilities across the 5-10 year automation horizon. Watch for inflection signals in central commissary consolidation velocity and state-level energy mandate adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Frequency Drive Retrofit Program | Captures California and New York mandate-driven demand in commercial bakery installed base. |
| Backward Integration into Electrical Steel Sourcing | Reduces exposure to East Asian foundry concentration and input cost volatility. |
| Digital Twin Platform Deployment | Compresses commissioning cycles for German industrial bakery pilot programs. |
| Laboratory Mixer Precision Tier Expansion | Serves CDMO quality-assurance protocols with cGMP documentation capabilities. |
| Central Commissary Channel Partnership | Consolidates 200-600 liter frame demand from high-turnover patisserie operators. |
Study Parameters
A spread of perspectives from plant engineers at commercial bakeries, procurement leads at confectionery processors, aftermarket service heads at equipment distributors, and regulatory affairs specialists at pharmaceutical manufacturers converged on the working assumptions underlying demand trajectories. Primary interview insights were cross-validated against FDA 21 CFR filings, EFSA guidance documents, SEC equipment manufacturer disclosures, and customs trade data for stainless steel food processing machinery. Bottom-up volume builds from segment-level procurement patterns were reconciled with top-down industry spend estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling spanning batch versus continuous versus laboratory configurations, food-grade versus pharmaceutical-grade versus construction-grade application tiers, and electromechanical versus pneumatic versus hydraulic technology architectures. CAGRs were derived from fitted growth curves calibrated to equipment replacement cycles and regulatory mandate implementation timelines. Forecast inputs incorporated electrical steel price indices and state-level energy efficiency adoption curves.
Stress conditions across electrical steel supply disruption, California mandate acceleration or delay, and continuous mixer substitution rates in chemical processing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about equipment replacement cycles and regulatory implementation pacing. Cross-checking against customs data for food processing machinery imports and hospital procurement database spending patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
Canada Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Food Sorting Machines Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Food Preservation Equipment Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Shawarma Grill Machine Market