
 Commercial Beer Tap System Market | 2026-2036
Commercial Beer Tap System Market Size, Share, and Industry Trends Forecast 2026-2036
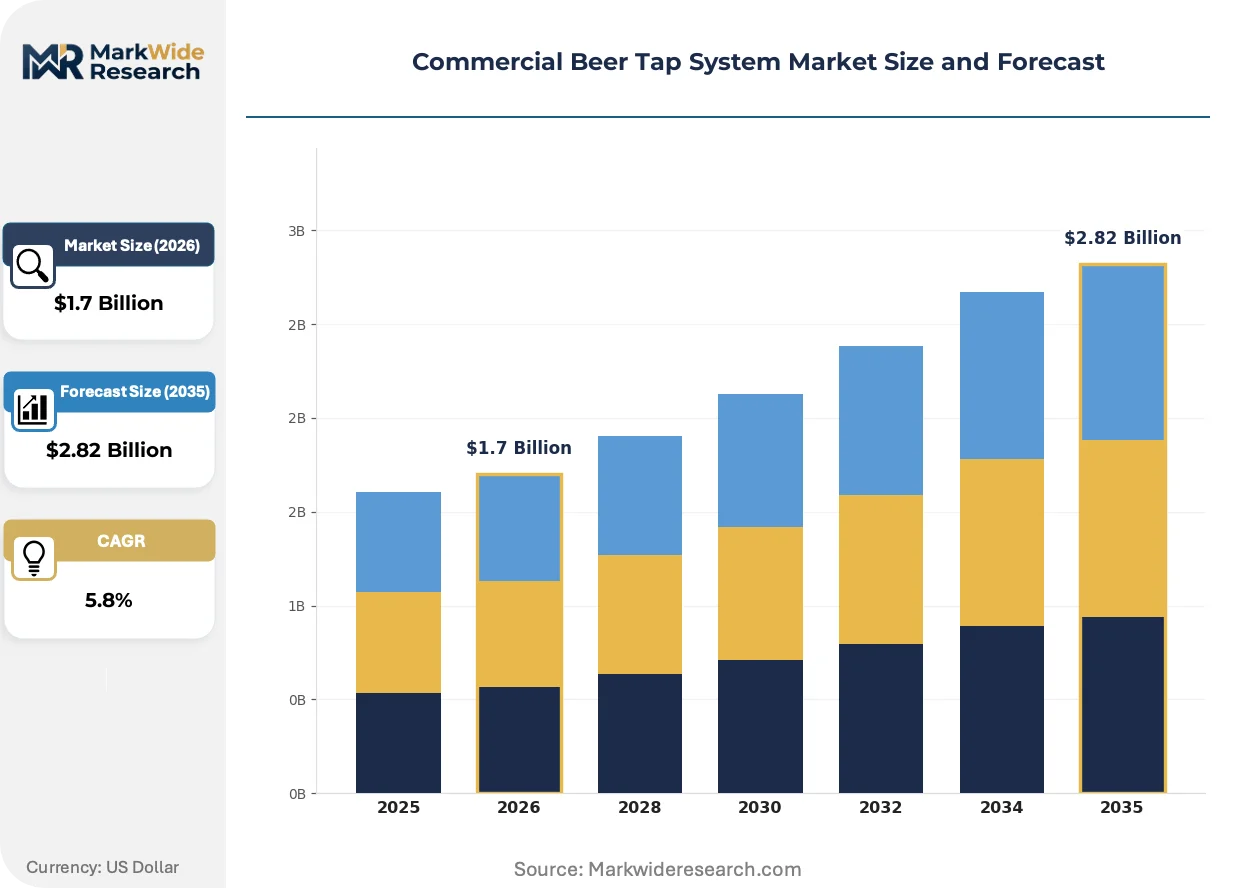
Commercial Beer Tap System Market Outlook
Multi-source component procurement is broadening across the commercial beer tap system supply base. Perlick Corporation leverages its domestic manufacturing footprint to sustain premium positioning in stainless steel tap towers. Micro Matic anchors European distribution through specialized keg coupler and line cleaning portfolios. Tianwan (Shanghai) Intelligent Equipment Co., Ltd. competes on cost-optimized direct draw systems for high-volume Asian markets.
A commercial beer tap system comprises a keg coupler, beer line, faucet, and cooling apparatus—typically direct draw, long draw, or glycol-cooled—engineered to maintain beverage temperature between 2°C and 4°C from keg to pour. Its primary commercial purpose is to deliver carbonated beer at controlled pressure and temperature to preserve flavor integrity and regulatory compliance in foodservice environments. Direct draw systems dominate installation counts in compact bars where proximity cooling suffices, while long draw configurations capture margin pools in stadium and hotel applications requiring remote keg storage. Smart integration connectivity is expanding fastest among brewery taprooms seeking pour-data analytics and inventory automation.
The FDA governs food-contact surface materials under 21 CFR, while NSF International certifies commercial food equipment sanitation performance, jointly shaping stainless steel grade requirements and cleaning protocol standards. The EPA regulates refrigerants in glycol cooling units through SNAP program phase-downs, pressuring equipment transitions to lower-GWP alternatives. Stakeholders must monitor evolving refrigerant compliance timelines and smart-pour data privacy frameworks to inform capital allocation and product roadmaps.
Market Dynamics
Smart-pour telemetry and IoT-enabled inventory tracking are compressing maintenance cycles and reorder lead times across brewery taprooms and hotel chains. This connectivity layer is forcing legacy equipment suppliers to reconfigure warranty terms and service revenue models.
Growth Catalysts
- Reinheitsgebot tradition in Germany:Strict brewing purity laws sustain dense pub infrastructure and per-capita draft system deployment rates unmatched elsewhere in Europe.
- 21 CFR food-contact surface standards:FDA material specifications for stainless steel equipment are elevating certified-system premiums in US foodservice procurement.
- Direct-to-consumer taproom expansion:North American craft breweries are installing on-premise systems to capture margin pools previously lost to distributor channels.
Market Restraints
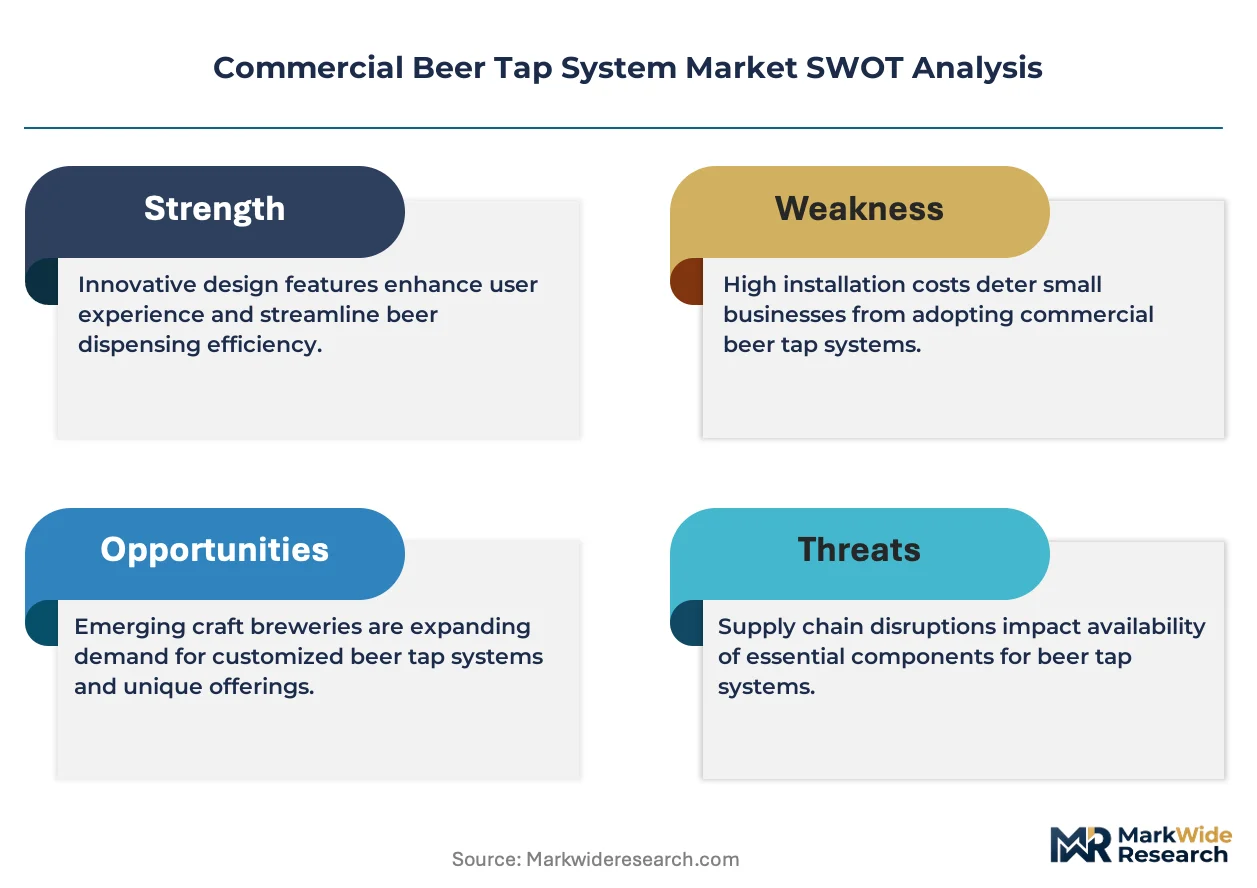
- Stainless steel grade volatility:Nickel and chromium input cost swings compress margin predictability for equipment fabricators.
- Glycol refrigerant phase-down timelines:EPA SNAP program restrictions on high-GWP coolants force premature equipment replacement cycles.
- Regional supplier concentration:Specialized keg coupler manufacturing clusters in Denmark and Italy create single-source vulnerability for long-draw system integrators.
Strategic Opportunities
- Untapped Southeast Asian hospitality:Vietnam and Thailand's hotel construction pipelines lack proportional draft infrastructure relative to beer consumption growth.
- EU F-Gas Regulation compliance services:Mandatory refrigerant audits create recurring revenue streams for equipment servicers retrofitting existing installations.
- Convergence of pour analytics and ERP systems:Real-time keg-level data integration with inventory management platforms enables predictive restocking contracts.
Industry Challenges
- NSF International certification timelines:Sanitation performance testing for new stainless steel configurations extends product launch windows by 8-14 months.
- Legacy system integration complexity:Smart-pour retrofits face protocol incompatibilities with existing cooling infrastructure in decades-old stadium and hotel installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Beer Tap System Market |
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Draw, Long Draw, Glycol-Cooled, Portable End User: Bars, Restaurants, Breweries, Catering Services Installation Type: Countertop, Wall-Mounted, Floor-Mounted, Custom Connectivity: Wi-Fi, Bluetooth, Wired, Smart Integration |
| Companies Covered | Tianwan (Shanghai) Intelligent Equipment Co., Ltd., Bev-Air, Perlick Corporation, Fagor Professional, True Manufacturing, Micro Matic, GS Draft System Solutions, Hoshizaki, Kegco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Beer Tap System Market Strategic Shifts
Digital instrumentation is penetrating draft systems at the component level, transforming passive dispensing hardware into data-generating assets. Equipment suppliers and beverage operators are recalibrating around telemetry-enabled service models.
Cloud-connected flow meters embedded in faucet assemblies are electrifying how draft system operators monitor pour consistency and detect line contamination. Brewery taprooms in Oregon and Colorado are deploying these sensors at scale to automate quality alerts. The technology is compressing response times to temperature excursions and pressure anomalies that previously required manual inspection rounds.
EPA SNAP program phase-downs of hydrofluorocarbon refrigerants are mandating glycol cooling unit redesigns ahead of 2025-2027 compliance windows. Equipment manufacturers serving stadium and hotel long-draw installations face accelerated R&D cycles to certify lower-GWP alternatives. The regulatory pressure is concentrating procurement decisions among buyers with sustainability mandates in California and New York.
After-sales service unbundling is fragmenting how hospitality groups contract maintenance and line cleaning. Large casino and resort operators in Nevada are separating equipment purchase from service agreements, pitting specialized cleaning contractors against OEM service divisions. This procurement model shift is visible most acutely in Las Vegas and Atlantic City, where multi-property beverage directors negotiate component-level vendor relationships.
Commercial Beer Tap System Market Segmentation
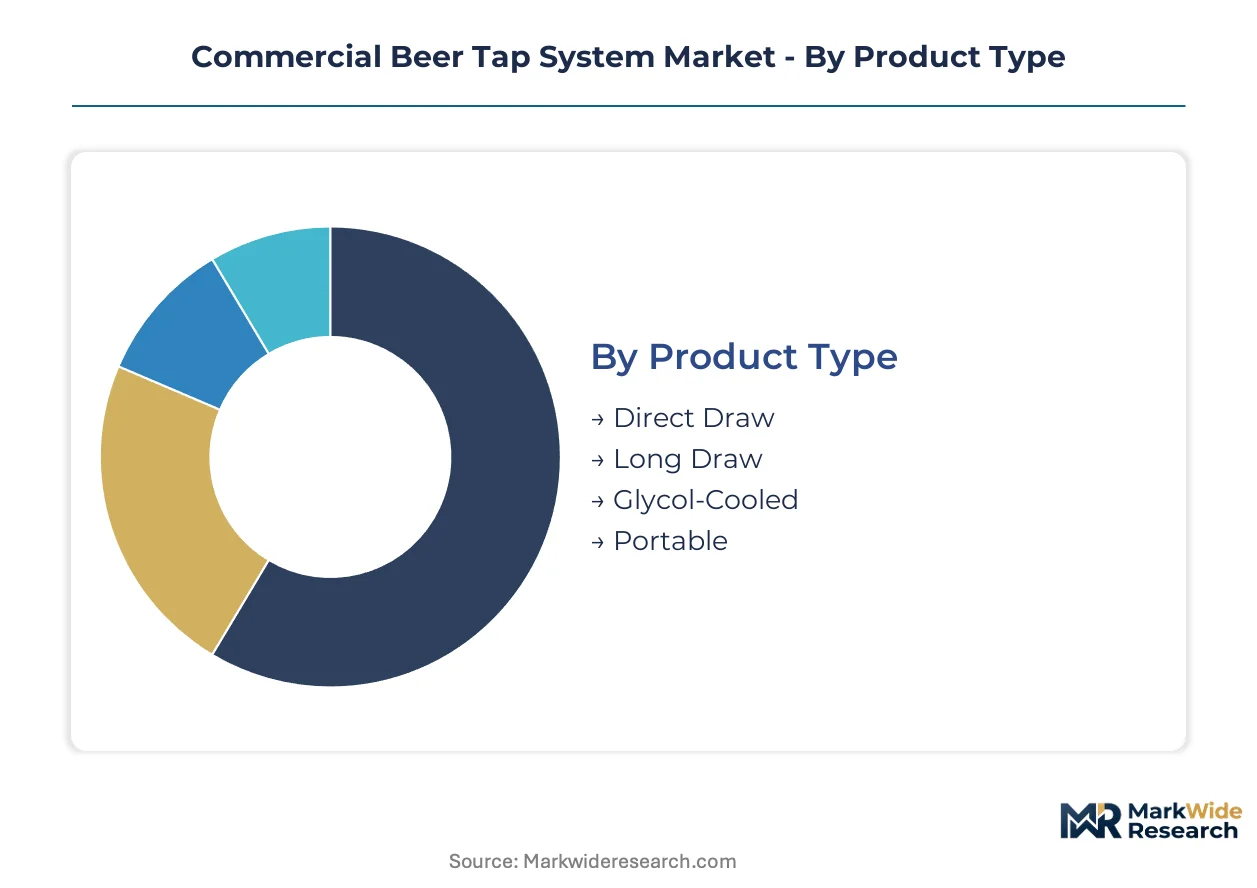
Commercial beer tap system segmentation reveals divergent margin structures across installation complexity and connectivity tiers. Product type and end-use configurations drive fundamentally different capital intensity and service revenue profiles for equipment suppliers.
Product Type:
Volume deployment concentrates in compact direct draw configurations, while premium margins attach to remote-cooled long draw systems.
- Direct Draw:Compact refrigeration units maintain keg temperature within arm's reach of the faucet, eliminating line run complexity. Demand clusters in neighborhood bars across Germany and compact urban taprooms in Portland and Denver where space constraints override remote storage needs.
- Long Draw:Glycol-chilled trunk lines transport beer across distances exceeding 25 feet from keg to tap, requiring engineered pressure balancing and cooling loops. Stadium concessions in Texas and hotel atriums in Las Vegas deploy these systems to centralize keg storage while distributing pour points across wide footprints.
- Glycol-Cooled:Recirculating propylene glycol solutions stabilize temperature across extended line runs in high-throughput environments.
- Portable:Self-contained mobile units serve outdoor events and temporary installations without permanent refrigeration infrastructure.
Mature deployment sits with Direct Draw. Newer deployment is concentrated in Glycol-Cooled configurations as EPA refrigerant phase-downs accelerate equipment replacement cycles.
End User:
Customer type segmentation separates high-volume replacement demand from greenfield installation growth.
- Bars:Traditional pub operators prioritize reliability and rapid pour recovery during peak hours, driving standardized component procurement. Irish-style pubs in Boston and Chicago maintain dense tap walls requiring synchronized maintenance schedules and line cleaning protocols.
- Restaurants:Full-service operators integrate tap systems into broader beverage programs with lower throughput per faucet, emphasizing space efficiency over pour speed. Casual dining chains in Florida and California specify compact under-counter units to preserve kitchen workflow.
- Breweries:Craft producers deploying on-premise taprooms seek telemetry-enabled systems for production-to-pour traceability and inventory automation.
- Catering Services:Event-based operators demand rapid deployment and breakdown capabilities with minimal technical support requirements.
Volume procurement runs through Bars. Steepest expansion trajectory is visible in Breweries as direct-to-consumer channel capture accelerates across North American craft segments.
Installation Type:
Physical mounting configuration determines labor specialization requirements and retrofit feasibility in existing hospitality infrastructure.
- Countertop:Surface-mounted towers dominate compact installations where structural modification is prohibited or cost-prohibited.
- Wall-Mounted:Bracketed systems free floor space in narrow bar configurations common in historic European pub buildings.
- Floor-Mounted:Freestanding columns and islands anchor high-visibility pour stations in casino floor plans and hotel lobbies.
- Custom:Architecturally integrated solutions accommodate irregular spatial constraints and branded aesthetic requirements in flagship locations.
Standardized deployment concentrates in Countertop. Architectural differentiation is driving Custom specification in Las Vegas and Atlantic City resort renovations.
Connectivity:
Data transmission architecture separates legacy passive systems from telemetry-enabled revenue optimization platforms.
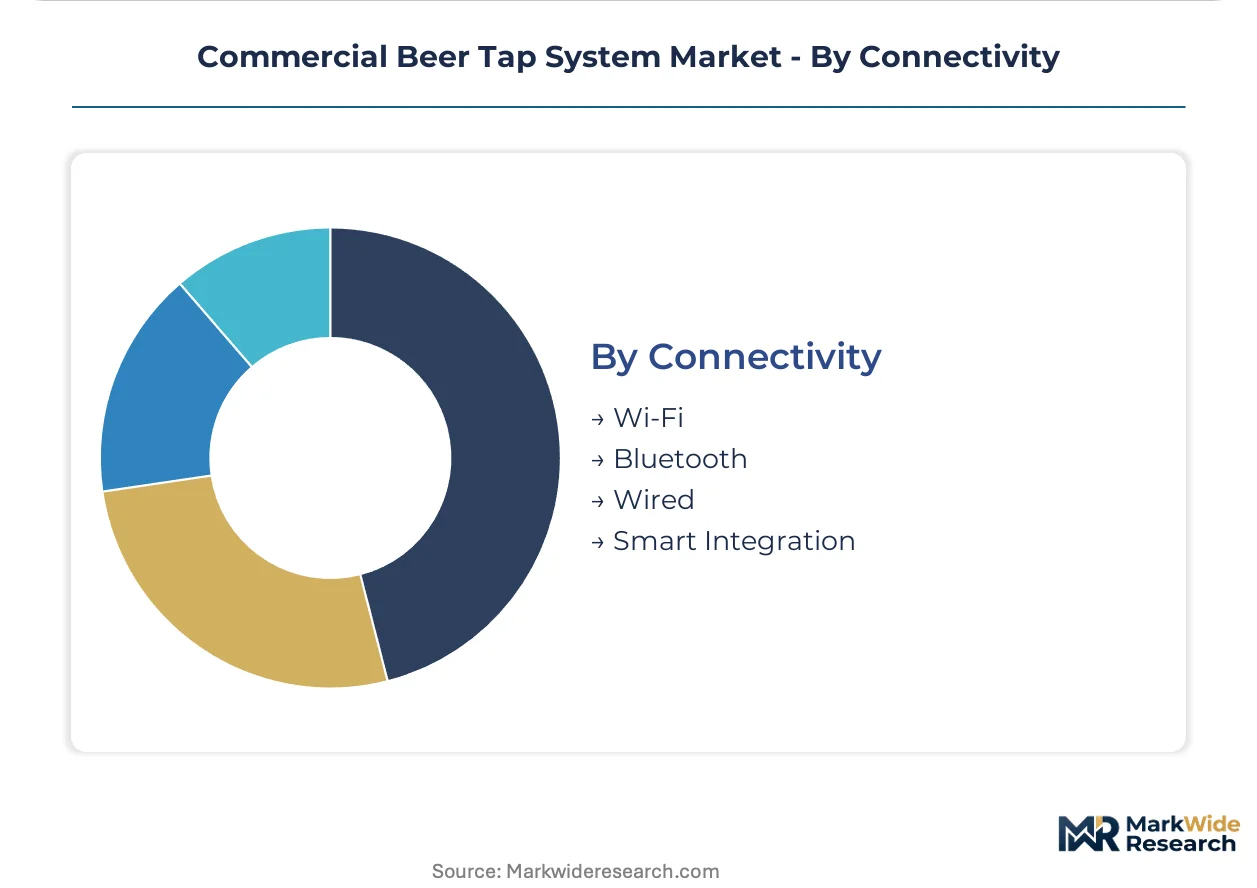
- Wi-Fi:Wireless cloud connectivity enables real-time pour monitoring and remote diagnostics without structured cabling retrofits. Brewery taprooms in Oregon and Colorado deploy these modules to aggregate consumption patterns across multiple locations.
- Bluetooth:Short-range pairing supports technician commissioning and local parameter adjustment without network infrastructure dependency.
- Wired:Ethernet-connected systems deliver deterministic latency for high-frequency data logging in stadium environments with existing IT backbone access.
- Smart Integration:API-connected platforms synchronize pour data with inventory management and ERP systems for predictive restocking.
Passive connectivity dominates legacy installed base. Smart Integration is gaining share fastest among multi-location hospitality operators pursuing centralized beverage program management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock availability from German and Chinese mills anchors geographic deployment patterns for commercial beer tap system manufacturing. Nickel and chromium pricing volatility propagates differently across regional supply bases. Regulatory divergence on refrigerant phase-downs is fragmenting equipment specification standards.
United States
Craft brewery taproom expansion in Oregon and Colorado drives direct-to-consumer system installations. FDA 21 CFR food-contact surface standards elevate certified-system premiums in procurement decisions. Chicago and Boston maintain dense Irish-style pub infrastructure requiring synchronized maintenance protocols.
Germany
The Reinheitsgebot brewing tradition sustains unmatched per-capita draft system density in Munich and Cologne pub clusters. EU F-Gas Regulation mandates refrigerant audits creating compliance service revenue pools. Bavarian equipment fabricators concentrate on precision-engineered long-draw configurations for export markets.
China
Cost-optimized direct draw system production scales from Shanghai-based manufacturing for high-volume Asian hospitality. SAMR and GB standards govern food equipment sanitation certification timelines. Yangtze River Delta industrial zones export glycol-cooled units to Southeast Asian hotel construction pipelines.
Vietnam
Ho Chi Minh City and Hanoi hotel construction outpaces proportional draft infrastructure installation rates. The country's national food safety regulator tightens import certification for stainless steel food-contact equipment. Da Nang hospitality clusters present greenfield specification opportunities for telemetry-enabled systems.
Australia
Sydney and Melbourne craft brewery taprooms adopt smart-pour telemetry for production-to-pour traceability. TGA-aligned state-level food equipment standards shape stainless steel grade requirements. Queensland mining-town hospitality venues drive portable system demand for temporary event deployment.
Commercial Beer Tap System Market Competitive Environment
Global majors compete with regional champions across refrigerant compliance expertise and smart-pour integration capabilities. The vendor base stratifies into three tiers: integrated cooling specialists, component fabricators, and connectivity platform providers. Tier-one players defend position through EPA SNAP program pre-certification and API-connected inventory management partnerships. Capacity expansion and strategic technology licensing dominate competitive moves as refrigerant transition deadlines compress.
Among North American fabricators, Perlick Corporation exemplifies premium-tier stainless steel positioning through domestic manufacturing anchoring. Micro Matic occupies a specialist role in European keg coupler and line cleaning portfolios. Tianwan (Shanghai) Intelligent Equipment Co., Ltd. represents cost-optimized scale production for high-volume Asian market penetration.
| Leading Market Players |
|---|
| Tianwan (Shanghai) Intelligent Equipment Co., Ltd. |
| Bev-Air |
| Perlick Corporation |
| Fagor Professional |
| True Manufacturing |
| Micro Matic |
| GS Draft System Solutions |
| Hoshizaki |
| Kegco |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators across Bavaria and Wisconsin anchor premium stainless steel tap tower production, their patient capital discipline insulating pricing power from nickel volatility while constraining capacity expansion that might erode margin structures.
Pricing Analysis
Warranty unbundling from equipment purchase is fragmenting how casino operators and brewery chains contract commercial beer tap systems. Three-tier pricing structure across premium NSF-certified, standard FDA-compliant, and economy non-certified levels separates Perlick's domestic fabrication from Tianwan's cost-optimized exports. Cost compression in the economy tier is intensifying because nickel and chromium input swings compress fabricator margins. Casual dining chains in Florida exhibit highest price sensitivity; Las Vegas resort beverage directors show lowest, prioritizing telemetry integration over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by stadium concessionaires and hotel chains force long-draw system integrators to qualify keg coupler suppliers across Denmark, Italy, and emerging Chinese alternatives. Stainless steel feedstock draws from German ThyssenKrupp mills and Yangtze River Delta producers, while glycol cooling compressors hinge on Japanese and South Korean component specialists. Single-source vulnerability clusters in specialized Danish keg coupler manufacturing. Distribution runs through specialized foodservice equipment distributors with certified technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NSF International certification bottlenecks constrain certified-system capacity, propping premium-tier pricing as fabricators queue for 8-14 month sanitation performance testing windows.
For Market Incumbents: Anticipate refrigerant phase-down compliance deadlines compressing replacement cycles by pre-certifying lower-GWP glycol cooling units through EPA SNAP program pathways. Backward integration into stainless steel finishing capacity in Wisconsin or Bavaria defends margin position against nickel volatility. Smart-pour telemetry retrofits threaten legacy warranty revenue streams; reconfigure service contracts around data-analytics subscriptions. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for refrigerant audit and retrofit service specialization, bypassing capital-intensive equipment fabrication. Vietnam's hotel construction pipeline in Ho Chi Minh City and Hanoi presents the most penetrable geography, with draft infrastructure lagging beer consumption growth. Partner with Yangtze River Delta fabricators for cost-optimized direct draw system white-label supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor connectivity-platform specialists with API-connected inventory management capabilities in North American craft brewery clusters. Long-term viability centers on telemetry-enabled recurring revenue models displacing transactional equipment sales. Watch for EPA SNAP program enforcement acceleration as inflection signal compressing replacement demand into concentrated windows.| Strategic Initiative | Industry Significance |
|---|---|
| EPA SNAP Pre-Certification | Lower-GWP glycol cooling certification ahead of 2025-2027 compliance windows secures stadium and hotel procurement decisions. |
| Smart-Pour Platform Integration | API-connected pour analytics synchronization with ERP systems enables predictive restocking contracts for multi-location operators. |
| Backward Integration into Stainless Finishing | In-house production of NSF-certified steel components insulates margin from nickel volatility and ThyssenKrupp pricing power. |
| Refrigerant Compliance Service Buildout | EU F-Gas Regulation audit capabilities in Germany create recurring revenue streams retrofitting existing long-draw installations. |
| Southeast Asian Distribution Partnership | Channel control through Vietnamese hospitality equipment distributors captures greenfield hotel specification in Da Nang clusters. |
Study Parameters
Document review covered SEC filings from foodservice equipment manufacturers, EPA SNAP program rulemakings, and EU F-Gas Regulation implementation guidance, complemented by interviews with brewery operations directors, casino beverage procurement managers, NSF International certification engineers, and stainless steel mill sales executives. Secondary validation drew from FDA 21 CFR food-contact surface standards, German Reinheitsgebot infrastructure surveys, and Yangtze River Delta export trade data. Bottom-up tap system installation counts and top-down hospitality construction pipelines were triangulated for market sizing.
Historical shipment data from refrigeration equipment manufacturers was cross-referenced against panel input from distribution channel partners across the analysis window. Segmentation modeling incorporated product type (direct draw, long draw, glycol-cooled, portable), end user (bars, restaurants, breweries, catering services), installation configuration, and connectivity tier. CAGRs were derived from regression analysis of replacement cycle compression and greenfield installation trajectories, with specific weighting for craft brewery taproom expansion rates and EPA refrigerant phase-down enforcement timelines.
The model assumes a particular technology adoption path; alternative pathways for smart-pour telemetry integration would alter the outlook if legacy stadium infrastructure retrofit complexity proves insurmountable. Forecasts reflect assumptions regarding nickel price stabilization and NSF certification timeline normalization. Deviation in EPA SNAP program enforcement acceleration or EU F-Gas Regulation audit mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Beer Glass Chillers Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
White Spirits Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Whiskey Market