
 Flakes Making Machine Market | 2026-2036
Flakes Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Flakes Making Machine Market Foresight
Stainless steel is consolidating its position as the dominant contact-surface material in flake processing equipment, displacing carbon-steel alternatives that carry higher sanitation compliance costs. Bühler Group leverages its integrated foundry-to-assembly operations in Uzwil to control material sourcing for high-grade roller flakers. GEA Group sustains engineering intensity through dedicated R&D centers for thermal flaking systems serving chemical and pharmaceutical clients. Wenger Manufacturing anchors its competitive position in North American feed-flaking with proprietary hydraulic pressing architectures designed for oilseed processing.
A flakes making machine is an industrial processing unit that compresses, shears, or thermally treats feedstocks into thin, uniform flakes through controlled mechanical or thermal action, typically operating at pressures between 20 and 100 bar and temperatures up to 180°C depending on material sensitivity. These machines serve core functions across food, chemical, and pharmaceutical sectors where controlled surface-area expansion, moisture reduction, or structural modification determines downstream processing efficiency. Roller flakers occupy the largest installed base due to their versatility across cereal grains and oilseeds, while thermal flaking systems represent the fastest-expanding technology segment as chemical processors adopt energy-integrated designs for polymer and wax applications. Drum flakers dominate margin pools in pharmaceutical manufacturing where batch consistency and cGMP compliance command premium pricing structures.
The FDA's Food Safety Modernization Act and OSHA's machinery safety directives shape equipment design requirements for U.S.-based food manufacturers, mandating hygienic construction and operator protection systems that elevate capital costs but create barriers for non-compliant imports. The EU's Machinery Directive and REACH chemical regulations similarly constrain market access for equipment lacking CE marking or constructed with restricted substances. Stakeholders must monitor evolving ESG disclosure rules under the EU Corporate Sustainability Reporting Directive, which will soon require documented lifecycle assessments for industrial equipment procurement decisions.
Market Dynamics
The FDA's Food Safety Modernization Act is compressing equipment replacement cycles across North American breakfast cereal processing, forcing manufacturers toward hygienic-design roller flakers with integrated clean-in-place systems that elevate capital requirements but lock out non-compliant imports.
Growth Catalysts
- Clean-label cereal demand:North American consumers are rejecting artificial additives, compelling processors to expand oat and corn flake capacity with equipment that preserves native grain structures without chemical treatment.
- REACH chemical compliance:European chemical processors are retrofitting thermal flaking lines to handle polymer and wax feedstocks under stricter substance restrictions, creating pull for energy-integrated designs.
- Oilseed processing intensity:Hydraulic pressing architectures for soybean and canola flaking are gaining traction in Brazilian and Argentine crush facilities seeking higher oil extraction yields.
Market Restraints
- Nickel alloy cost volatility:Stainless steel roller surfaces face input price swings that compress margins for equipment fabricators locked into fixed-price contracts.
- German supplier concentration:Bühler Group and GEA Group anchor a dense engineering ecosystem around Uzwil and Düsseldorf, creating bottleneck risk for buyers outside their service radius.
- CE marking friction:Non-European manufacturers face extended certification timelines and documentation burdens that delay market entry by 8-14 months.
Strategic Opportunities
- Indian pharmaceutical flaking:CDSCO's tightening cGMP enforcement is creating demand for batch-consistent drum flakers in Mumbai and Hyderabad manufacturing clusters.
- Feed-flaking automation:Integration of machine vision and adaptive roller gap control offers pathways to reduce operator dependence in remote oilseed processing locations.
- EU Green Deal alignment:Equipment vendors documenting lifecycle carbon footprints gain preferential access to sustainability-linked procurement pools under the Corporate Sustainability Reporting Directive.
Industry Challenges
- Sanitation engineering scarcity:Fewer than twelve accredited programs annually produce specialists capable of designing FDA-validated clean-in-place systems for high-pressure roller environments.
- Legacy control system integration:Brownfield cereal plants running 1990s-era SCADA architectures face prohibitive retrofit costs when connecting modern flaking lines to existing batch management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flakes Making Machine Market |
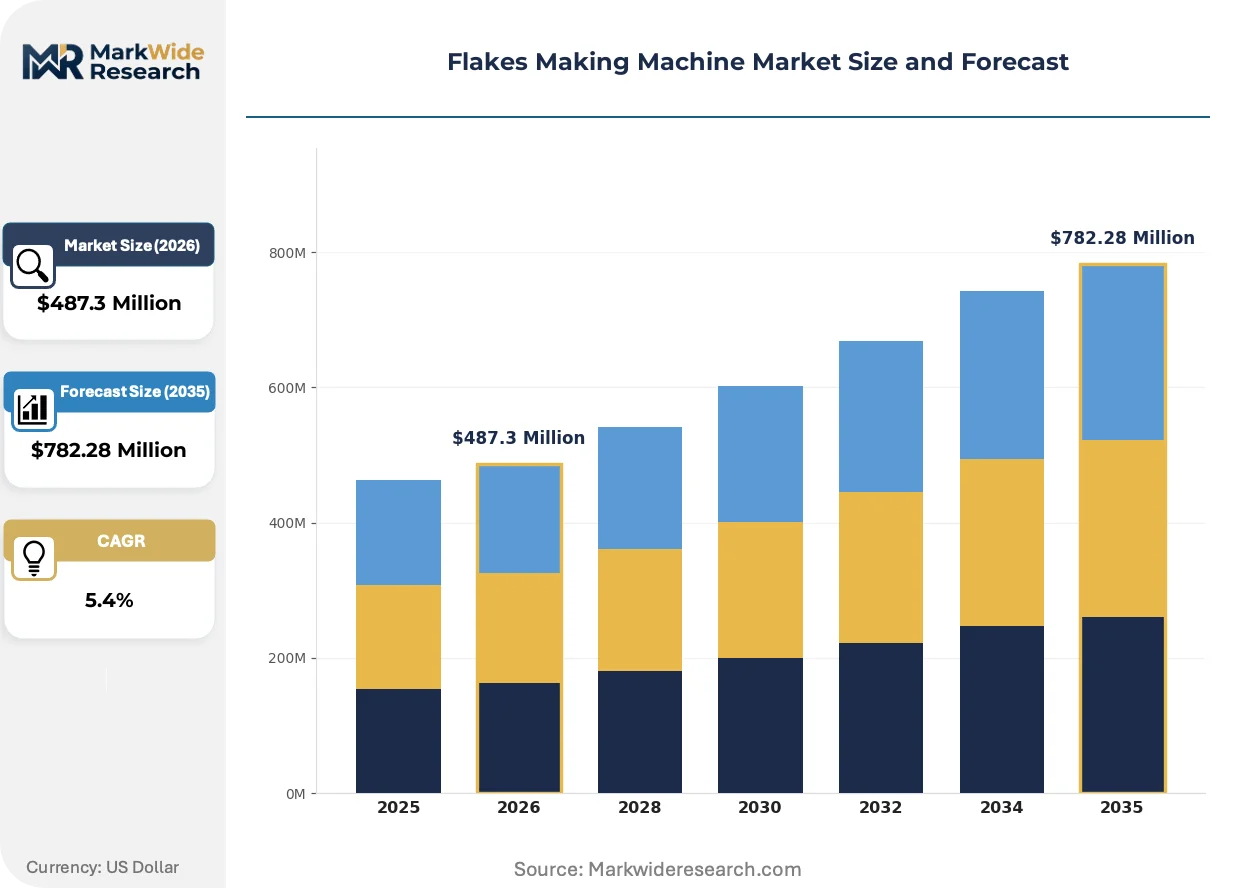
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $782.28 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Flaker, Drum Flaker, Plate Flaker, Rotary Flaker Technology: Hydraulic Pressing, Mechanical Pressing, Pneumatic Pressing, Thermal Flaking Application: Cereal Processing, Chemical Processing, Pharmaceutical Manufacturing, Animal Feed Production End User: Food Manufacturers, Chemical Producers, Feed Mills, Pharmaceutical Companies |
| Companies Covered | Bühler Group, GEA Group, Wenger Manufacturing, RHEON Automatic Machinery, Jinan Saibainuo Machinery, AKA Kocher GmbH, Jinan Sunrising Machinery Co., Ltd., Shandong Loyal Industrial Co., Ltd., Shanghai Fude Machinery Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flakes Making Machine Market Shifts & Advancements
Equipment architectures are fragmenting into configurable subsystems that let processors swap roller configurations, thermal modules, or pressing units without full line replacement, compressing capital commitment horizons.
Modular thermal flaking systems are modularizing around standardized heat-exchange cartridges that chemical processors can reconfigure between polymer, wax, and specialty chemical runs. European petrochemical buyers in Rotterdam and Antwerp are piloting these units to avoid dedicated single-product lines. The approach is compressing equipment utilization rates while extending asset depreciation schedules across multiple product lifecycles.
REACH substance restrictions are forcing reformulation of hydraulic fluids and bearing lubricants used in food-contact zones, compelling vendors to qualify synthetic ester alternatives that withstand 180°C operating temperatures. German and Swiss engineering houses are absorbing 12-18 month requalification timelines. Pharmaceutical drum flaker buyers are accelerating pre-purchase audits to verify lubricant compliance before installation.
Service unbundling is separating aftermarket parts, remote diagnostics, and field maintenance into discrete purchase decisions that large cereal processors negotiate through separate procurement towers. North American co-manufacturers are driving this fragmentation to arbitrage service costs against internal maintenance capabilities. The shift is most visible in Minneapolis and Chicago processing corridors where multi-brand facilities operate mixed-vendor flake lines.
Flakes Making Machine Market Segmentation
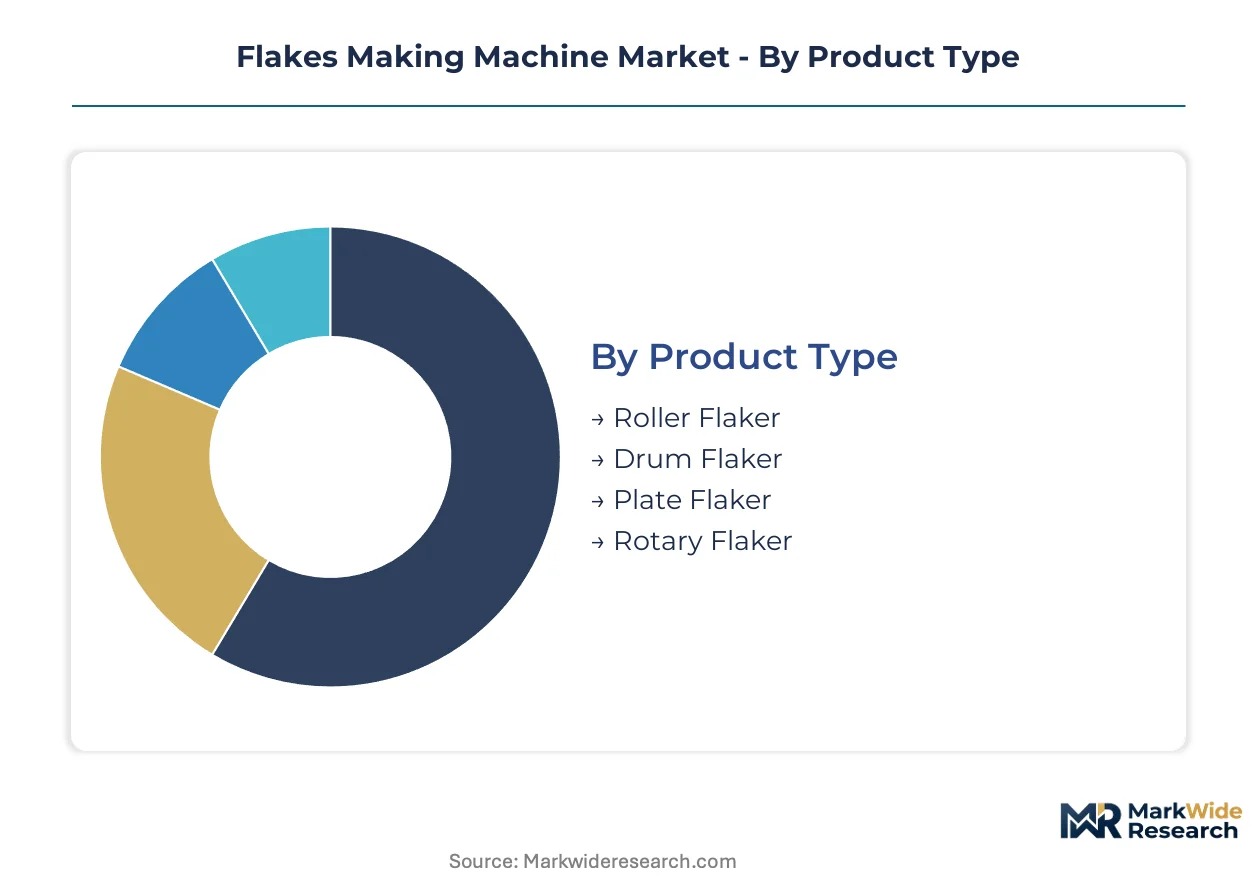
Flakes making machine procurement decisions hinge on material sensitivity, throughput requirements, and regulatory exposure. Equipment configurations diverge sharply between food-contact applications demanding hygienic construction and chemical processing environments prioritizing thermal precision. Understanding these segment boundaries clarifies where capital deployment concentrates and where technology substitution risks emerge.
Product Type:
Customization intensity varies from standardized roller platforms to application-specific drum architectures requiring extensive engineering validation.
- Roller Flaker:Twin-counter-rotating cylinders compress feedstocks through adjustable gap settings, typically achieving 0.3-2.0 mm flake thickness. Cereal processors in Minneapolis and Chicago corridors favor these units for oat and corn flake lines where FDA-validated clean-in-place systems dominate purchasing criteria.
- Drum Flaker:Rotating cooled cylinders solidify molten feedstocks into uniform sheets through conductive heat transfer. Pharmaceutical manufacturers in Mumbai and Hyderabad manufacturing clusters specify these units for cGMP-compliant batch consistency where drum surface finish tolerances command premium engineering attention.
- Plate Flaker:Fixed-bed pressing surfaces deliver high-pressure compression for brittle feedstocks. Chemical processors in Rotterdam pilot these for wax and polymer applications requiring controlled crystallization.
- Rotary Flaker:Continuous rotary action suits high-throughput oilseed processing. Brazilian and Argentine crush facilities deploy these for soybean and canola pre-treatment ahead of solvent extraction.
Most installed capacity flows through roller flakers. Expansion is steepest in drum flakers.
Technology:
Capital intensity escalates from purely mechanical systems through energy-integrated thermal designs with extended qualification timelines.
- Hydraulic Pressing:Closed-loop fluid power systems generate 20-100 bar compression forces with precise pressure profiling. Wenger Manufacturing anchors its North American feed-flaking position with proprietary hydraulic architectures designed for oilseed yield optimization.
- Mechanical Pressing:Screw or cam-driven mechanisms deliver lower capital cost but reduced pressure control fidelity. Small-scale cereal co-manufacturers in secondary US markets specify these for limited-batch specialty grain runs.
- Pneumatic Pressing:Compressed air actuation enables rapid cycling for temperature-sensitive pharmaceuticals. Limited adoption outside laboratory-scale installations due to energy efficiency constraints.
- Thermal Flaking:Integrated heat-exchange modules process polymers and waxes at controlled temperatures up to 180°C. European petrochemical buyers in Antwerp pilot modular configurations to avoid dedicated single-product lines.
Mechanical pressing retains the largest installed base. Thermal flaking is climbing the fastest as chemical processors retrofit for REACH-compliant substance handling.
Application:
Regulatory burden intensity separates food-contact validation requirements from chemical processing flexibility priorities.
- Cereal Processing:Breakfast cereal manufacturing demands hygienic-design roller flakers with integrated clean-in-place capabilities. The FDA's Food Safety Modernization Act compresses replacement cycles for North American facilities running legacy carbon-steel equipment.
- Chemical Processing:Polymer, wax, and specialty chemical applications require thermal precision and substance compatibility documentation. REACH restrictions on hydraulic fluids and bearing lubricants compel 12-18 month requalification timelines for German and Swiss engineering houses.
- Pharmaceutical Manufacturing:cGMP compliance mandates batch consistency documentation and surface finish validation. CDSCO enforcement tightening in Indian manufacturing clusters accelerates pre-purchase audits for lubricant compliance verification.
- Animal Feed Production:Oilseed crushing and grain processing prioritize throughput economics over surface finish precision. Remote Brazilian and Argentine facilities drive demand for automated roller gap control to reduce operator dependence.
Cereal processing commands the largest equipment fleet. Pharmaceutical manufacturing is gaining share fastest as regulatory enforcement tightens across emerging manufacturing clusters.
End User:
Procurement sophistication separates integrated multinationals with dedicated engineering teams from regional operators relying on vendor service networks.
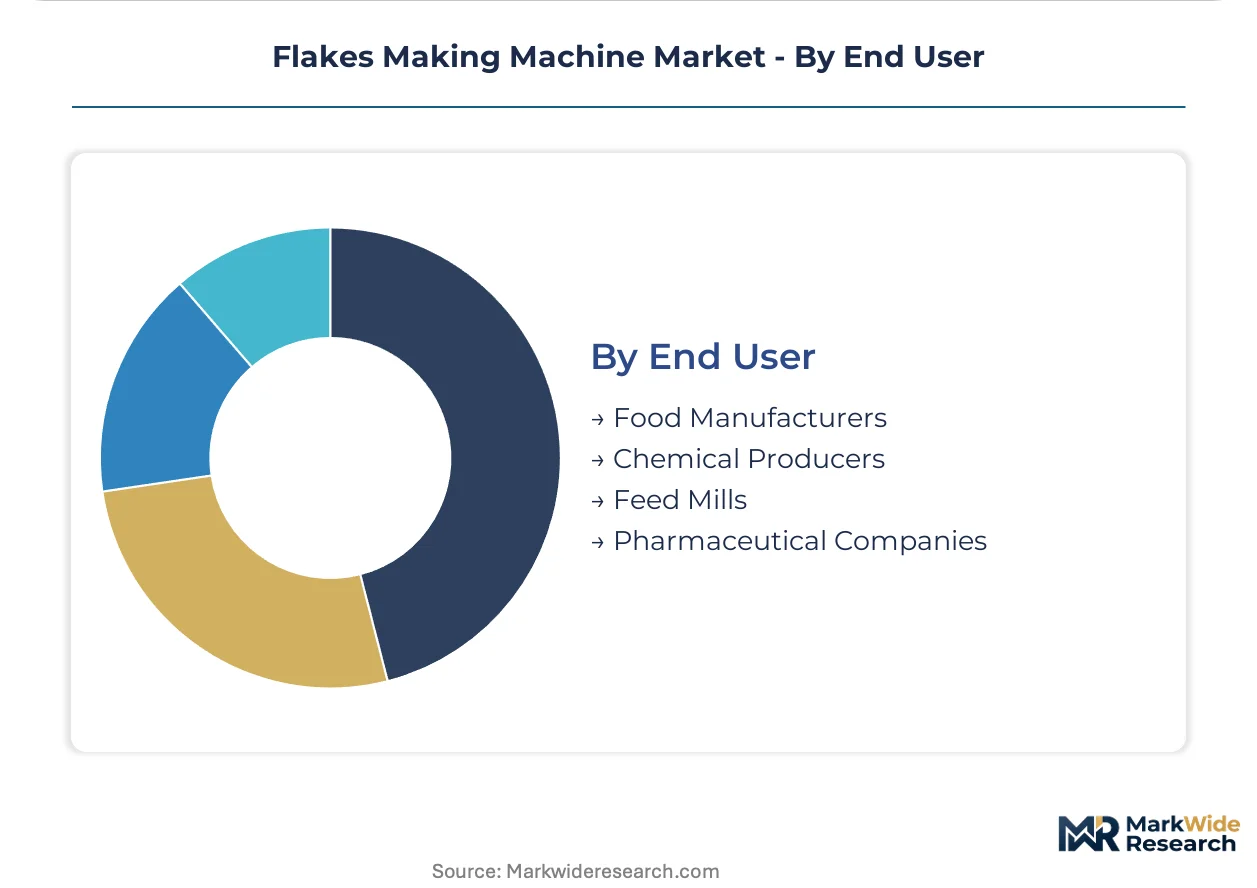
- Food Manufacturers:Breakfast cereal and snack processors specify hygienic-design equipment with documented sanitation validation. Minneapolis and Chicago co-manufacturers unbundle service contracts to arbitrage aftermarket costs against internal maintenance capabilities.
- Chemical Producers:Petrochemical and specialty chemical operators prioritize energy integration and multi-product flexibility. Rotterdam and Antwerp buyers pilot modular thermal systems to compress capital commitment horizons across product lifecycles.
- Feed Mills:Oilseed crush and grain processing facilities emphasize throughput reliability and remote service access. Argentine and Brazilian operators seek adaptive roller gap control for soybean and canola processing.
- Pharmaceutical Companies:Drug manufacturers demand batch consistency documentation and audit-ready compliance packages. Mumbai and Hyderabad clusters specify drum flakers with verified lubricant formulations ahead of CDSCO inspections.
Food manufacturers represent the largest procurement volume. Pharmaceutical companies are expanding their equipment budgets most aggressively as cGMP enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Uzwil anchors global engineering intensity for precision flaking equipment, with Swiss and German fabricators commanding premium positioning across food and chemical processing verticals.
United States
Breakfast cereal manufacturers in Minneapolis and Chicago corridors expand oat and corn flake capacity to meet clean-label demand. The FDA's Food Safety Modernization Act compresses replacement cycles for legacy carbon-steel equipment. North American co-manufacturers unbundle service contracts to arbitrage aftermarket costs against internal maintenance capabilities.
Germany
Bühler Group and GEA Group anchor a dense supplier ecosystem serving European food and chemical processors. REACH chemical compliance pressures retrofitting of thermal flaking lines for polymer and wax feedstocks. Engineering houses in Düsseldorf absorb 12-18 month requalification timelines for lubricant formulations.
India
CDSCO's tightening cGMP enforcement creates demand for batch-consistent drum flakers in pharmaceutical manufacturing. Mumbai and Hyderabad clusters specify equipment with verified lubricant compliance ahead of regulator inspections. Domestic fabricators compete on cost for feed-flaking applications in oilseed processing.
Brazil
Soybean and canola crush facilities seek hydraulic pressing architectures for higher oil extraction yields. Remote processing locations drive demand for automated roller gap control to reduce operator dependence. Argentine operators mirror this automation priority across the Mercosur processing corridor.
China
Jinan and Shandong province machinery manufacturers scale production of standardized roller platforms for domestic cereal and feed applications. NMPA-aligned pharmaceutical equipment standards elevate documentation requirements for drum flaker exports. Coastal fabricators compete with European suppliers on delivery timelines for Southeast Asian markets.
Flakes Making Machine Market Competitive Landscape
Global majors compete with regional champions across engineering validation and aftermarket service density. The vendor base stratifies between integrated European engineering houses with captive foundry operations and Asian fabricators competing on modular platform cost. Three archetypes dominate: precision-engineering specialists with metallurgical control, scale-driven manufacturers of standardized roller systems, and application-focused providers of thermal and hydraulic configurations. Competitive moves concentrate on geographic service network expansion and clean-in-place certification acceleration.
Among Swiss and German engineering houses, Bühler Group and GEA Group exemplify the precision-engineering archetype through integrated material sourcing and dedicated R&D infrastructure. Wenger Manufacturing occupies a position among North American specialists with proprietary hydraulic architectures. Chinese fabricators including Jinan Saibainuo Machinery and Shandong Loyal Industrial represent the scale-driven tier, while AKA Kocher GmbH sits within the mid-market European segment focused on application-specific configurations.
| Leading Market Players |
|---|
| Bühler Group |
| GEA Group |
| Wenger Manufacturing |
| RHEON Automatic Machinery |
| Jinan Saibainuo Machinery |
| AKA Kocher GmbH |
| Jinan Sunrising Machinery Co., Ltd. |
| Shandong Loyal Industrial Co., Ltd. |
| Shanghai Fude Machinery Manufacturing Co., Ltd. |
| Others |
Supply & Pricing Matrix
Nickel alloy price indices cascade through roller flaker fabrication costs, compressing margins for stainless steel equipment tiers while elevating premium spreads for FDA-validated hygienic-design units with clean-in-place certification. European engineering houses pass through alloy volatility via contract escalation clauses, whereas Asian fabricators absorb input swings to defend standardized platform pricing.
Pricing Analysis
Input-cost pass-through dominates pricing architecture, with nickel alloy surcharges flowing directly into roller surface quotations and thermal module assemblies. Premium-mid-economy pricing differentiation separates CE-marked European systems with documented REACH compliance from standardized Chinese platforms serving feed-flaking applications. Pricing pressure stems from fixed-price contract exposure among German fabricators locked into 12-18 month delivery timelines. Chemical processors exhibit lowest price sensitivity due to requalification cost avoidance, while feed mills in Mercosur corridors arbitrage aggressively across Asian and European vendor quotes.
Supply Chain Analysis
Dual-sourcing requirements for FDA-validated clean-in-place systems compel North American cereal processors to qualify both Swiss-German engineering houses and secondary European vendors, extending procurement cycles but mitigating single-source dependency. Supply concentration centers on Switzerland, Germany, and China for precision roller fabrication, with foundry capacity for high-grade stainless steel surfaces anchored in Uzwil and Düsseldorf industrial zones. Component dependencies include nickel alloy feedstock, precision bearing assemblies, and synthetic ester lubricants reformulated for REACH compliance. Tariff exposure on Chinese-fabricated control systems creates bottleneck risk for budget-tier procurement. Distribution runs through direct OEM sales for pharmaceutical drum flakers and regional distributor networks for feed-flaking equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Flakes Making Machine Market functions as a stable compounder anchored by regulatory-mandated equipment replacement cycles that compress capital commitment horizons regardless of macroeconomic cycles.
For Market Incumbents: Acquire specialized sanitation engineering capabilities to address the acute talent scarcity in FDA-validated clean-in-place system design. Consolidate aftermarket service density in Minneapolis and Chicago co-manufacturing corridors where unbundled procurement towers seek to arbitrage maintenance costs. Capacity addition in Brazilian oilseed processing hubs captures automation demand for adaptive roller gap control systems. Certification investment in CDSCO-aligned cGMP documentation secures pharmaceutical drum flaker positioning ahead of Indian regulatory enforcement intensification. For New Entrants and Emerging Players: The premium-to-economy price-point gap in thermal flaking systems offers entry opportunity for modular heat-exchange cartridge configurations serving Rotterdam and Antwerp petrochemical buyers seeking multi-product flexibility. White-space concentration appears in Indian pharmaceutical manufacturing clusters where domestic fabricators lack verified lubricant compliance documentation. Automated feed-flaking retrofits for remote Argentine crush facilities represent the most penetrable application segment. Go-to-market execution should leverage machine vision integration partnerships with established controls vendors rather than proprietary development. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-engineering specialists possessing captive metallurgical capabilities and established regulatory validation track records. Long-term viability over a 5-10 year horizon rests on sustained regulatory tightening across food safety and pharmaceutical manufacturing standards rather than cyclical capital expenditure recovery. Acquisition target archetype: mid-scale European engineering houses with CE marking infrastructure and dormant REACH requalification pipelines. The signal to watch is CDSCO inspection frequency escalation in Mumbai and Hyderabad manufacturing corridors, which would accelerate pharmaceutical equipment procurement irrespective of broader industrial capital deployment trends.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-in-Place Certification Acceleration | FDA validation timelines compress competitive windows for non-compliant imports into North American cereal processing. |
| Modular Thermal System Development | Rotterdam petrochemical buyers pilot reconfigurable heat-exchange cartridges to avoid dedicated single-product lines. |
| Aftermarket Service Network Expansion | Chicago co-manufacturers unbundle maintenance contracts to arbitrage internal capabilities against vendor offerings. |
| Synthetic Ester Lubricant Requalification | REACH substance restrictions force 12-18 month validation timelines for bearing formulations in food-contact zones. |
| Automated Roller Gap Control Integration | Remote Brazilian crush facilities adopt machine vision to reduce operator dependence in soybean and canola processing. |
Research Methodology
Multiple input streams — executive interviews with cereal processing plant engineers, procurement dialogues with chemical manufacturing technical directors, and aftermarket service discussions with feed-flaking maintenance heads — were reconciled against customs records for stainless steel processing equipment, SEC filings from listed engineering conglomerates, and CE marking registration databases. Secondary validation drew from FDA warning letter archives documenting clean-in-place system deficiencies, ECHA substance restriction updates affecting lubricant formulations, and Indian CDSCO cGMP inspection schedules. Bottom-up equipment shipment tallies by product type and application were triangulated against top-down capital expenditure surveys across food, chemical, and pharmaceutical manufacturing verticals.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling spanning roller, drum, plate, and rotary product architectures; hydraulic, mechanical, pneumatic, and thermal pressing technologies; and cereal, chemical, pharmaceutical, and feed production applications. CAGRs were derived from installed base depreciation schedules, regulatory-mandated replacement cycle compression, and emerging market capacity buildout trajectories. Industry-specific forecast inputs included REACH substance restriction implementation timelines and CDSCO enforcement intensity indices for Indian pharmaceutical manufacturing clusters.
The model assumes a particular technology adoption path; alternative pathways for thermal flaking modularization would alter the outlook if petrochemical buyers accelerate reconfigurable system deployment beyond current pilot phases. Forecasts reflect assumptions regarding sustained regulatory tightening in food safety and pharmaceutical manufacturing standards, with deviation in nickel alloy price volatility or CE marking timeline extensions shifting the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Mixing Vessels Market