
 Plant-Based Hot Dogs Market | 2026-2036
Plant-Based Hot Dogs Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Hot Dogs Market Analytics
Asset-light co-manufacturing and contract packaging is tilting competitive dynamics toward brands that outsource production rather than build captive plants. Beyond Meat leverages its dedicated extrusion facilities to control texture consistency across retail and foodservice channels. Impossible Foods anchors its position through heme-protein R&D intensity that competitors struggle to replicate. Morningstar Farms sustains volume leadership through deep supermarket distribution partnerships that newer entrants cannot easily penetrate.
Plant-based hot dogs comprise emulsified or extruded protein batters, typically containing pea or soy isolate, fat analogs, and binding hydrocolloids, formed into cylindrical casings and thermally processed to achieve snap and umami delivery comparable to conventional frankfurters. Pea protein formulations are gaining fastest within product type segments as brands seek to sidestep soy allergen concerns while achieving neutral flavor profiles. Distribution through supermarkets still captures the dominant margin pool, though online retail channels are expanding fastest as direct-to-consumer subscription models reduce intermediary costs for emerging brands.
The U.S. FDA scrutinizes protein content claims and allergen disclosures on plant-based meat labels, while the EU's EFSA evaluates novel protein safety dossiers before granting market authorization across member states. The EU Green Deal's farm-to-fork targets indirectly channel public procurement toward lower-carbon protein alternatives in institutional foodservice. Stakeholders must monitor whether regulatory divergence between American and European labeling standards fragments product development roadmaps or creates opportunities for dual-certified formulations.
Market Dynamics
Co-manufacturing networks are compressing capital barriers for new entrants while fragmenting supply-side control, forcing established brands to defend margin through proprietary extrusion IP and captive R&D facilities rather than scale economies alone.
Growth Catalysts
- EU Green Deal procurement mandates:Institutional foodservice contracts across Germany, France, and the Netherlands now require carbon-labeled protein alternatives, redirecting volume toward plant-based suppliers with verified LCA data.
- Pea protein extraction advances:Wet-fractionation improvements at processing facilities in Manitoba and Saskatchewan are neutralizing beany off-notes, enabling clean-label formulations without soy allergen warnings.
- Stadium and QSR placement expansion:Major league sports venues in Los Angeles, London, and São Paulo are adding dedicated plant-based concession lines, normalizing trial among occasional meat consumers.
Market Restraints
- Input cost volatility:Pea protein isolate prices swing with pulse crop yields in the Canadian prairies and Black Sea region, compressing gross margins when contracted volumes face spot-market renegotiation.
- Extrusion equipment concentration:High-shear twin-screw systems capable of fibrous texture simulation remain concentrated among three European and two North American OEMs, creating queuing delays for new production lines.
- Heme protein regulatory friction:EFSA novel food dossier requirements for fermented leghemoglobin extend approval timelines to 18-24 months, blocking EU market entry for formulations dependent on blood-like flavor chemistry.
Strategic Opportunities
- Direct-to-consumer subscription channels:Emerging brands bypass supermarket slotting fees through refrigerated delivery networks, capturing full retail margin while building repeat-purchase data assets.
- India institutional foodservice:FSSAI protein fortification guidelines for mid-day meal schemes create procurement specifications favoring affordable plant-based options over dairy-dependent alternatives.
- High-moisture extrusion convergence with 3D food printing:Pilot installations at culinary R&D centers in Singapore and Barcelona are enabling customized texture layering for premium foodservice applications.
Industry Challenges
- Food technologist scarcity:Formulation chemists skilled in protein-protein interaction modeling and hydrocolloid binding systems command premium compensation, constraining R&D throughput at mid-scale manufacturers.
- Dual-certification complexity:Divergent FDA and EFSA labeling standards for protein content claims force parallel packaging runs or lowest-common-denominator formulations that underperform in either market.
- Cold-chain reconfiguration:Refrigerated meat alternatives require distinct logistics from frozen or ambient plant-based categories, forcing distributors to segment warehouse zones and delivery routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Hot Dogs Market |
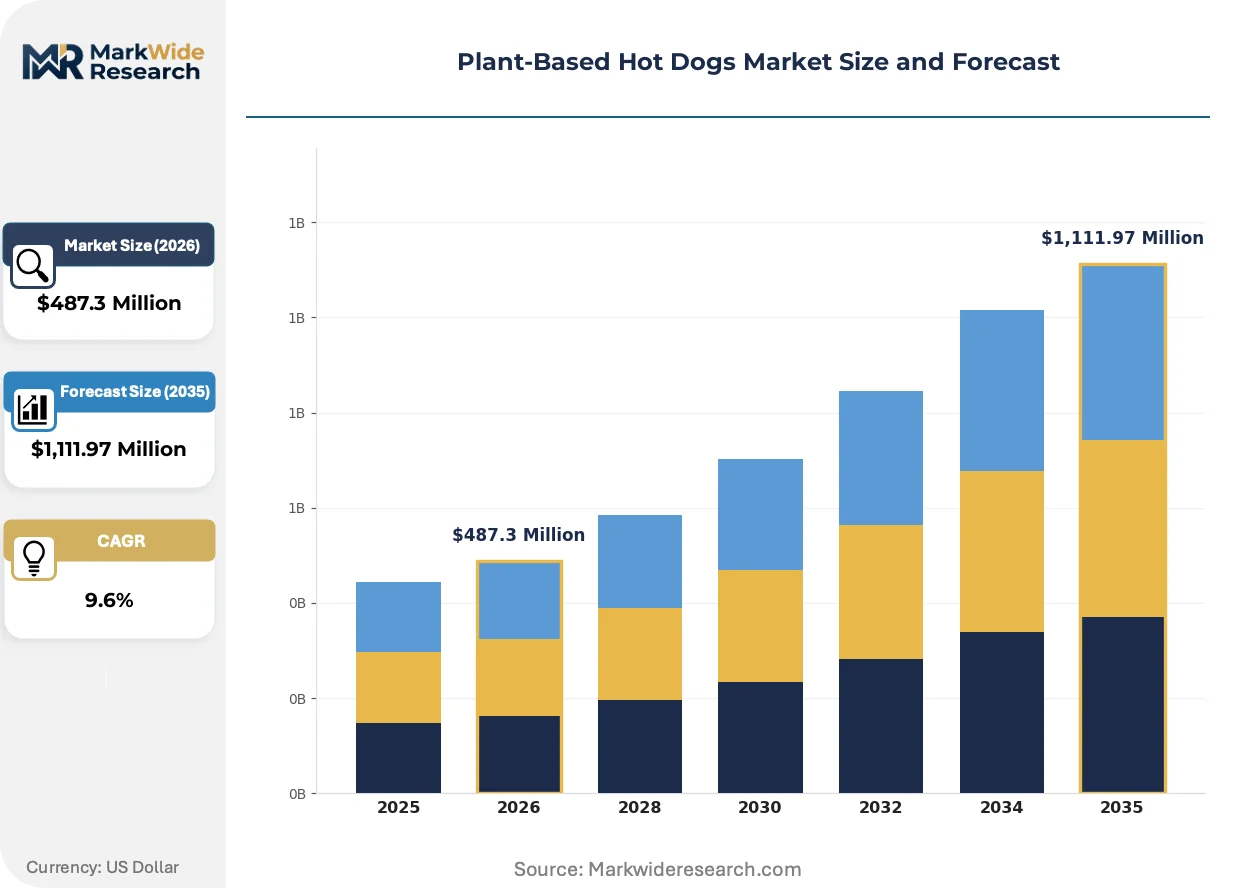
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,111.97 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Veggie Dogs, Soy-Based, Wheat-Based, Pea Protein End User: Households, Restaurants, Food Trucks, Vegan Cafes Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores Packaging Type: Single-Serve Packs, Bulk Packs, Vacuum-Sealed, Recyclable |
| Companies Covered | Tofurky, Morningstar Farms, Beyond Meat, Amy's Kitchen, Maple Leaf Foods, Impossible Foods, Quorn Foods, Yves Veggie Cuisine, Lightlife Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Hot Dogs Market Evolving Landscape
Texture-engineering breakthroughs and procurement-model disruption are redefining competitive advantage away from ingredient sourcing toward finished-product performance and channel control.
High-moisture extrusion is collapsing the texture gap between plant-based and conventional emulsified sausages. Foodservice operators in Germany and the Netherlands are adopting these formulations for grilled applications previously dominated by pork frankfurters. The technology is collapsing premium pricing power for first-generation products dependent on static cooling and forming methods.
REACH-compliant fat analog development is accelerating as European regulators scrutinize hydrogenated oil residues in processed alternatives. Reformulation teams are pivoting toward enzymatically interesterified blends and oleogel systems. Manufacturers serving EU retail channels are absorbing 12-18 month redevelopment cycles to maintain shelf placement.
Buyer consolidation among contract foodservice management companies is compressing supplier negotiation cycles. Sodexo and Compass Group are centralizing protein procurement decisions at continental headquarters, replacing distributed regional purchasing. This concentration is most visible in North American university and corporate campus contracts, where annual RFP processes now bundle plant-based specifications with conventional meat volumes.
Plant-Based Hot Dogs Market Segmentation
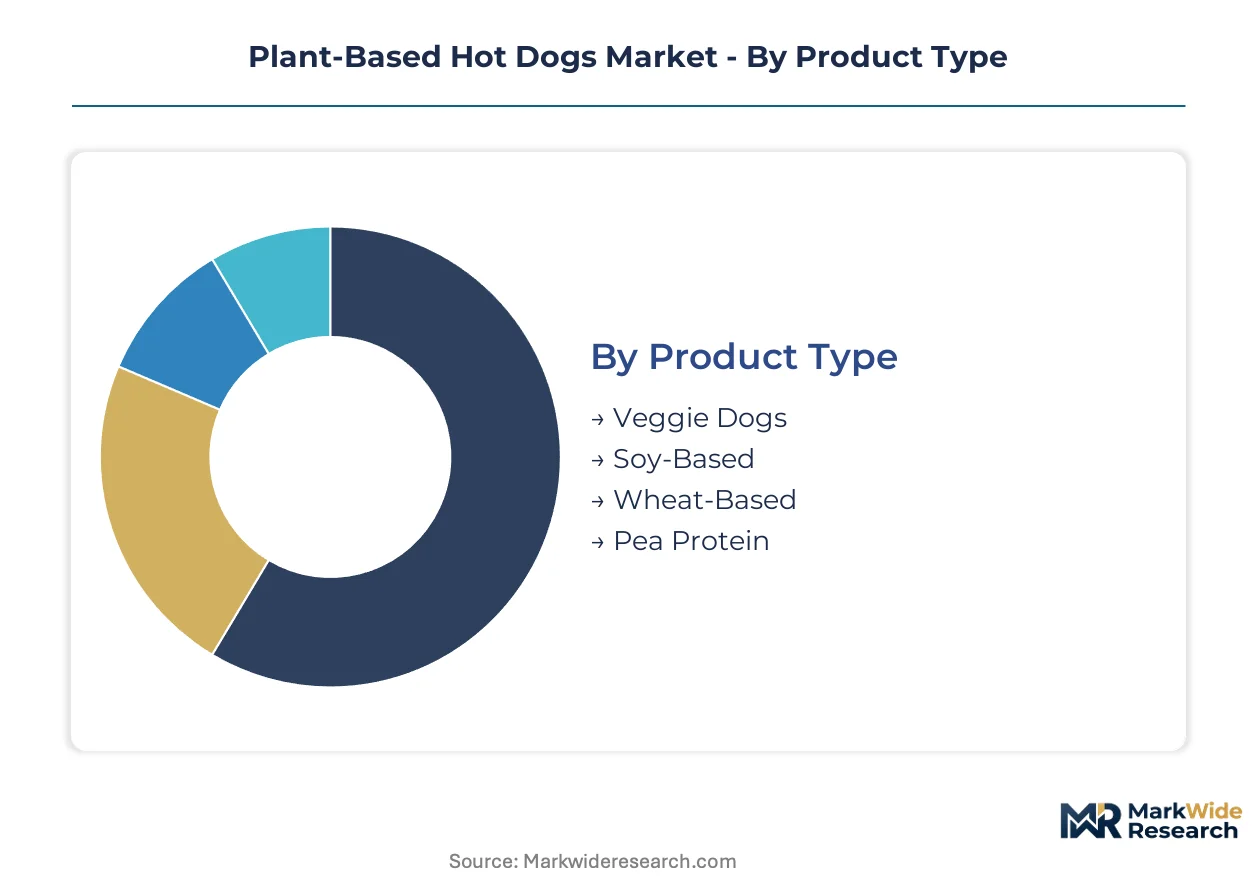
Product architecture and channel configuration determine margin capture in plant-based hot dogs. Formulation chemistry, thermal processing requirements, and cold-chain logistics create distinct competitive arenas across each dimension.
Product Type:
Cost tier structures the competitive intensity across protein base alternatives, with premium positioning commanding proprietary extrusion investments and economy tiers competing on input cost arbitrage.
- Pea Protein:Wet-fractionation advances at Manitoba processing facilities neutralize beany off-notes, enabling clean-label formulations without soy allergen warnings. Demand concentrates in Germany and the Netherlands where retail shelf space for refrigerated meat alternatives has expanded significantly, though EFSA novel food dossier timelines for fermented additives constrain flavor chemistry options.
- Soy-Based:Isolate and concentrate formulations dominate legacy production capacity with established emulsification protocols. Volume leadership persists through deep supermarket distribution partnerships that newer entrants cannot easily penetrate, particularly in North American mass retail channels where price elasticity remains acute.
- Veggie Dogs:Whole-vegetable and mycoprotein blends targeting flexitarian trialists with visible ingredient differentiation.
- Wheat-Based:Seitan-derived formulations leveraging established European bakery infrastructure for textural development.
Pea protein holds installed capacity. Soy-based is rotating up the share rankings.
End User:
Application context dictates formulation specifications, with foodservice requiring thermal stability under holding lamps and retail demanding extended refrigerated shelf life.
- Restaurants:Quick-service operators specify high-moisture extruded products capable of grill-mark retention and snap delivery comparable to conventional frankfurters. Procurement centralization at Sodexo and Compass Group headquarters bundles plant-based specifications with conventional meat volumes, compressing supplier negotiation cycles across North American university contracts.
- Households:Refrigerated retail packs dominate purchase frequency with subscription models capturing full margin through direct-to-consumer channels. German households demonstrate densest demand clustering as EU Green Deal procurement mandates redirect institutional volume toward verified LCA data holders.
- Food Trucks:Mobile operators prioritize ambient-stable or frozen formats with minimal prep infrastructure requirements.
- Vegan Cafes:Ideologically-aligned venues absorb premium positioning for certified organic and non-GMO verified alternatives.
Restaurants command specification authority. Households are climbing the fastest.
Distribution Channel:
Channel margin structures separate volume scale from value capture, with intermediary costs determining brand profitability at equivalent price points.
- Supermarkets:Dominant margin pool with slotting fees and promotional allowances consuming 15-25% of manufacturer revenue. Morningstar Farms sustains position through refrigerated case placement negotiations that emerging brands cannot match.
- Online Retail:Direct-to-consumer subscription models reduce intermediary costs for emerging brands while building repeat-purchase data assets. Los Angeles and São Paulo metro areas show concentrated adoption of refrigerated delivery networks.
- Health Food Stores:Premium positioning with educated consumer base accepting higher price points for clean-label attributes.
- Convenience Stores:Frozen and ambient formats targeting impulse purchase occasions with limited cold-chain investment.
Supermarkets anchor volume throughput. Online retail is expanding most quickly.
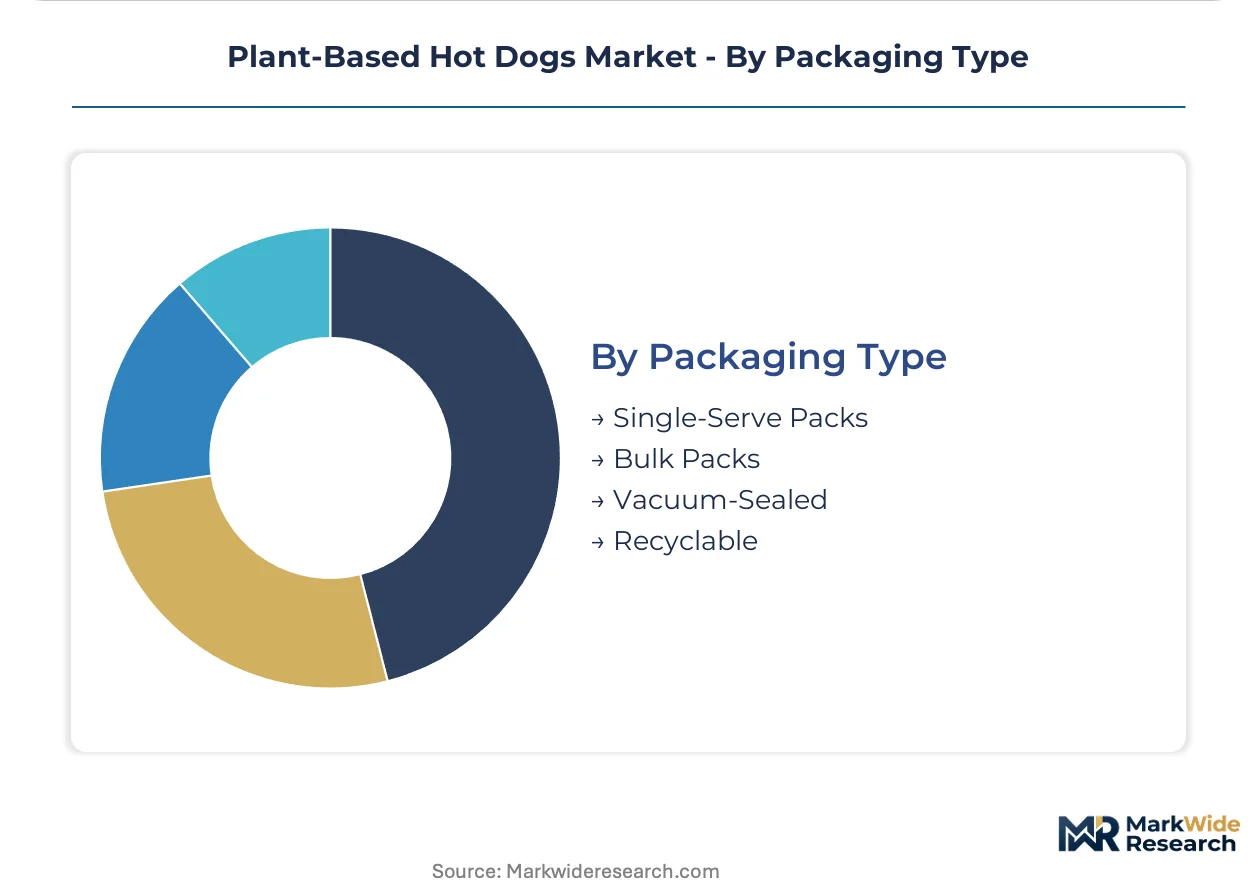
Packaging Type:
Packaging configuration aligns with consumption occasion and sustainability positioning, with material science investments differentiating premium from economy tiers.
- Vacuum-Sealed:Modified atmosphere packaging extends refrigerated shelf life to 45-60 days, reducing spoilage allowances for distributors. REACH-compliant film development absorbs 12-18 month redevelopment cycles as European regulators scrutinize hydrogenated oil residues in processed alternatives.
- Recyclable:Fiber-based trays and mono-material films respond to EU packaging waste directives with premium price acceptance in German and Dutch retail channels.
- Single-Serve Packs:Portion-controlled formats for trial and on-the-go consumption with higher unit economics.
- Bulk Packs:Foodservice-oriented configurations reducing per-unit packaging cost for high-volume operators.
Vacuum-sealed commands shelf-life premiums. Recyclable is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement mandates redirect institutional foodservice contracts toward carbon-labeled protein alternatives, while FDA labeling scrutiny in the United States accelerates reformulation timelines. Demand clustering intensifies in Germany, where retail shelf space for refrigerated meat alternatives has expanded significantly.
United States
Stadium concession operators and quick-service restaurants drive volume through dedicated plant-based menu lines. The FDA's updated guidance on alternative protein labeling pressures manufacturers to clarify protein content claims and allergen disclosures. Los Angeles metro area hosts concentrated adoption of refrigerated delivery networks for direct-to-consumer subscription models.
Germany
Retail shelf space for refrigerated meat alternatives has expanded significantly, creating densest demand clustering across European markets. EU Green Deal farm-to-fork targets channel public procurement toward lower-carbon protein alternatives in institutional foodservice. Berlin and Frankfurt foodservice operators adopt high-moisture extruded formulations for grilled applications previously dominated by conventional frankfurters.
Canada
Wet-fractionation improvements at Manitoba and Saskatchewan processing facilities neutralize beany off-notes in pea protein isolates. Pulse crop yield volatility in the Canadian prairies creates input cost swings that compress manufacturer margins during spot-market renegotiation. Toronto and Vancouver metro areas anchor refrigerated distribution infrastructure for cross-border retail supply.
Netherlands
REACH-compliant fat analog development accelerates as regulators scrutinize hydrogenated oil residues in processed alternatives. EFSA novel food dossier requirements for fermented leghemoglobin extend approval timelines for blood-like flavor chemistry formulations. Rotterdam and Amsterdam culinary R&D centers pilot high-moisture extrusion convergence with 3D food printing for customized texture layering.
Brazil
São Paulo metro area shows concentrated adoption of refrigerated delivery networks alongside stadium concession expansion for plant-based menu placements. ANVISA evaluates protein fortification claims under national food safety frameworks. São Paulo-based foodservice operators bundle plant-based specifications with conventional meat volumes through centralized procurement decisions.
Plant-Based Hot Dogs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply-side dynamics. Co-manufacturing networks compress capital barriers for new entrants while fragmenting production control, forcing established participants to defend margin through proprietary extrusion intellectual property and captive research facilities. Three archetypes dominate: dedicated plant-based pure-plays, diversified protein conglomerates with legacy meat operations, and emerging direct-to-consumer brands bypassing supermarket slotting fees. Competitive moves concentrate on strategic partnerships for distribution access and technology licensing for texture-engineering capabilities.
Within the pure-play tier, Beyond Meat exemplifies asset-heavy extrusion investment, while Impossible Foods anchors positioning through heme-protein research intensity. Among diversified protein participants, Maple Leaf Foods occupies a position bridging conventional meat infrastructure with plant-based portfolio expansion, and Morningstar Farms exemplifies volume leadership through deep supermarket distribution partnerships. These three companies represent distinct strategic postures: captive manufacturing control, novel ingredient chemistry differentiation, and legacy channel access leverage.
| Leading Market Players |
|---|
| Tofurky |
| Morningstar Farms |
| Beyond Meat |
| Amy's Kitchen |
| Maple Leaf Foods |
| Impossible Foods |
| Quorn Foods |
| Yves Veggie Cuisine |
| Lightlife Foods |
| Others |
Value Network & Pricing Analysis
Refrigerated trucking corridors connecting Manitoba processing facilities to Toronto and Vancouver distribution hubs transmit pea protein isolate cost volatility directly into manufacturer margin structures, compressing pricing power at the economy tier while premium formulations absorb logistics premiums through clean-label positioning.
Pricing Analysis
Certification level creates the primary spread between economy and premium tiers, with EFSA novel food authorization and FDA allergen compliance separating validated formulations from commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects extrusion technology intensity and protein content claims. Cost compression in the standard tier intensifies because wet-fractionation capacity expansions in Saskatchewan flood lower-grade isolate into spot markets. Foodservice procurement teams at contract management companies exhibit acute price sensitivity, while direct-to-consumer subscription buyers accept 15-20% premiums for verified LCA data and transparent sourcing.
Supply Chain Analysis
EU REACH restrictions on hydrogenated oil residues and EFSA novel food dossier requirements constrain formulation ingredient flows into European retail channels. Geographic supply concentration centers on Canada for pea protein isolate, the Netherlands for high-shear extrusion equipment, and Germany for modified atmosphere packaging films. Raw material dependencies include Canadian prairie pulse crops, enzymatically interesterified fat blends, and binding hydrocolloid systems. Single-source vulnerability runs through the three European and two North American OEMs controlling high-shear twin-screw extrusion systems. Distribution runs through refrigerated warehouse zones segmented from frozen and ambient plant-based categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against precision-fermented proteins and cultivated meat alternatives that threaten to displace first-generation plant-based formulations entirely.
For Market Incumbents: Insulate core margin through captive extrusion IP and backward integration into pea protein processing capacity in Manitoba or Saskatchewan. Defend supermarket refrigerated case placement against emerging brands by absorbing slotting fee increases that subscription-model competitors cannot match. Monitor precision-fermented protein cost curves as the primary substitute threat accelerating beyond 2030.
For New Entrants and Emerging Players: Brazilian institutional foodservice underpenetration offers white-space expansion through ANVISA-compliant formulations targeting São Paulo stadium concessions and corporate campus contracts. India's mid-day meal procurement specifications under FSSAI protein fortification guidelines create accessible volume without competing against entrenched retail shelf space. Pursue direct-to-consumer refrigerated delivery networks in Los Angeles and São Paulo metro areas to capture full retail margin and build repeat-purchase data assets.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors extrusion-technology specialists with proprietary high-moisture texture-engineering capabilities over brand-dependent marketing plays. Long-term viability across the projection horizon hinges on defensible formulation chemistry rather than channel access alone. Watch EFSA approval timelines for fermented leghemoglobin as the inflection signal separating viable heme-protein competitors from stranded R&D investments.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Buildout | Captures foodservice grill-mark specifications previously dominated by conventional frankfurters in German and Dutch markets. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees while building repeat-purchase data assets in Los Angeles and São Paulo corridors. |
| EFSA Novel Food Dossier Submission | Unlocks EU retail distribution for fermented leghemoglobin formulations blocked by 18-24 month approval timelines. |
| Backward Integration into Pea Processing | Neutralizes prairie pulse crop yield volatility through captive supply of clean-label isolate without soy allergen warnings. |
| REACH-Compliant Fat Analog Reformulation | Maintains European shelf placement through enzymatically interesterified blends replacing scrutinized hydrogenated oil residues. |
Research Methodology
A spread of perspectives from extrusion technology directors, supermarket category buyers, contract foodservice procurement managers, and regulatory affairs leads at plant-based protein manufacturers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA guidance documents, EFSA novel food registers, EU Green Deal procurement mandate texts, and refrigerated meat alternative retail audit data. Bottom-up volume estimates from pea protein isolate processing capacity and top-down demand projections from institutional foodservice contract awards were triangulated against cross-border trade flows.
Demand-supply balance modeling across the analysis window segmented volume by protein base chemistry, thermal processing method, distribution channel margin structure, and geographic regulatory cluster. CAGRs were derived from installed extrusion capacity expansion schedules, supermarket shelf space allocation trends, and stadium concession placement pipelines. Industry-specific forecast inputs included EFSA approval timeline distributions for novel food dossiers and wet-fractionation yield improvement curves at Manitoba processing facilities.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by diversified protein conglomerates or breakthroughs in precision-fermented protein cost structures would shift outcomes materially. Cross-checking against EU public procurement database award notices and FDA alternative protein labeling enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Plant-Based Butter Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Plant Based Tuna Market