
 Refrigerated Vending Machines Market | 2026-2036
Refrigerated Vending Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Vending Machines Market Analytics
Energy Star certification and premium insulation specifications is reorganizing procurement criteria across the refrigerated vending machines landscape. Fuji Electric Company Ltd. leverages its compressor technology heritage to anchor positions in high-efficiency cooling systems. Azkoyen Group differentiates through cashless payment integration and IoT connectivity modules. Seaga Manufacturing, Inc. specializes in compact footprint designs for space-constrained deployment environments.
Refrigerated vending machines are self-service retail units maintaining temperatures between two and eight degrees Celsius for perishable goods, utilizing vapor-compression refrigeration cycles with R-290 or R-600a hydrocarbon refrigerants to preserve food safety and extend shelf life in unattended commercial settings. Beverage machines occupy the largest installed base due to universal demand and simpler cold-chain requirements, while meal machines represent the fastest-expanding category as fresh prepared food programs displace traditional ambient snack options. IoT-enabled technology segments command premium positioning through remote diagnostics and dynamic inventory management capabilities.
The US Department of Energy enforces minimum efficiency standards under its commercial refrigeration equipment program, while the EPA regulates refrigerant phase-downs through its SNAP program, collectively compelling redesign of compressor architectures and insulation packages. Japan's METI administers Top Runner standards that accelerate efficiency benchmarks beyond international baselines. Stakeholders must weigh refrigerant transition timelines against retrofit economics as hydrocarbon adoption intensifies.
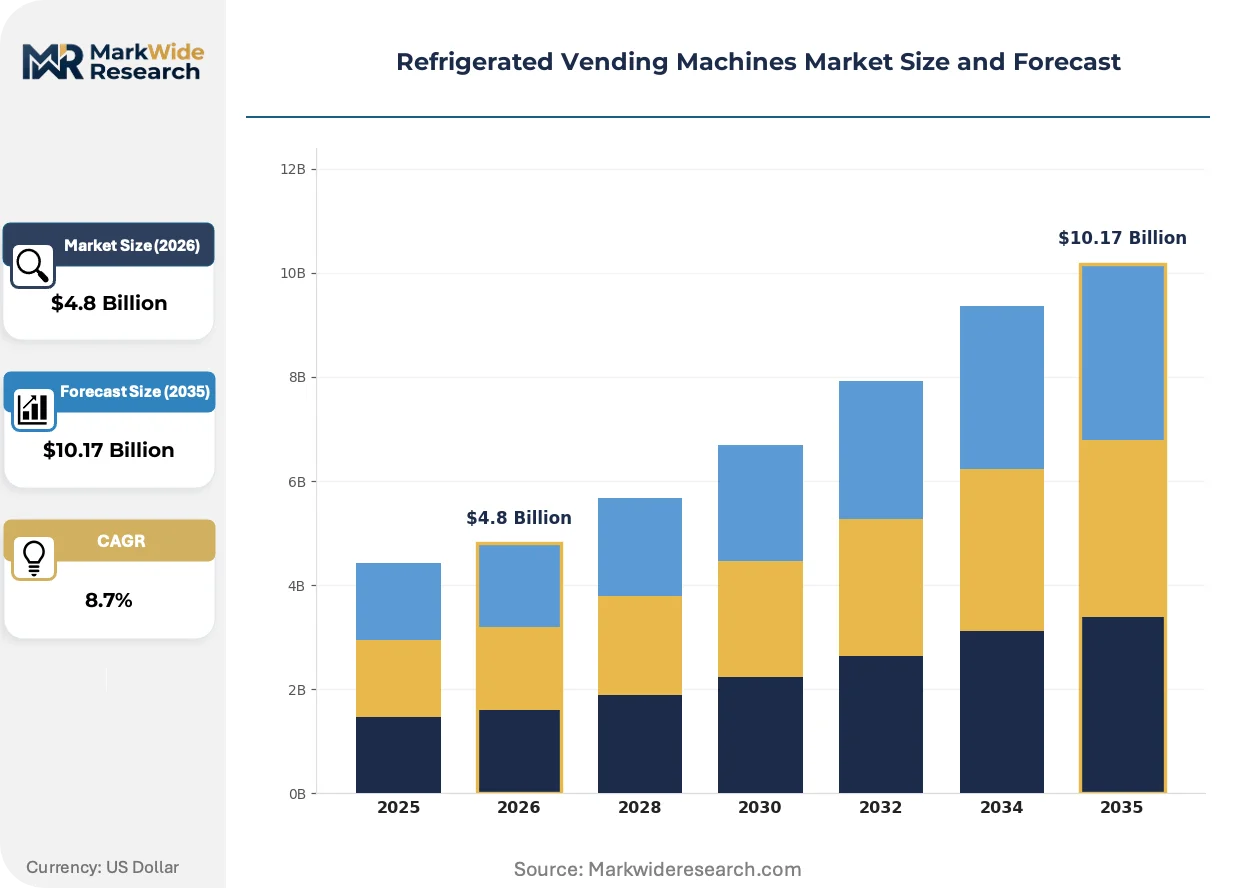
Market Dynamics
Variable-speed compressor technology is forcing wholesale redesign of cooling architectures as hydrocarbon refrigerant transitions collide with efficiency mandates from Washington, Brussels, and Tokyo.
Growth Catalysts
- Japan's METI Top Runner standards:Accelerated efficiency benchmarks are pulling next-generation insulation and compressor technologies into commercial deployment ahead of international baselines.
- Hospital campus expansion:Twenty-four-hour patient and staff access requirements are extending cold-food vending footprints across acute care and outpatient facilities.
- Cashless payment integration:IoT-enabled transaction modules are unlocking unattended retail in transit hubs and corporate campuses previously constrained by cash-handling logistics.
Market Restraints
- Hydrocarbon refrigerant supply concentration:R-290 and R-600a production clusters in select chemical manufacturing regions create input cost volatility and security-of-supply exposure.
- Retrofit economics:Legacy machine replacement cycles stretch across multi-year horizons, compressing near-term addressable volume for integrated efficiency platforms.
- Ambient snack substitution:Shelf-stable alternatives retain cost and logistical advantages in price-sensitive deployment environments.
Strategic Opportunities
- Fresh prepared food programs:Meal vending machines are capturing share from traditional ambient snack options in corporate and education verticals.
- Remote diagnostics convergence:IoT-enabled platforms combining predictive maintenance with dynamic inventory management command premium positioning.
- US IRA efficiency incentives:Tax credits for commercial refrigeration equipment are improving payback calculations for variable-speed compressor upgrades.
Industry Challenges
- Refrigeration technician scarcity:Specialized hydrocarbon handling certification requirements are constraining installation and service capacity expansion.
- Multi-standard compliance timelines:Simultaneous EPA SNAP phase-downs, DOE efficiency standards, and state-level refrigerant regulations are fragmenting product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Vending Machines Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Machines, Beverage Machines, Meal Machines, Frozen Food Machines Technology: IoT-Enabled, Cashless Transactions, Touchless Options, Digital Displays End User: Office Buildings, Schools, Airports, Fitness Centers Distribution Channel: Online Retail, Direct Sales, Distributors, Franchise Options |
| Companies Covered | Fuji Electric Company Ltd., Azkoyen Group, Seaga Manufacturing, Inc., Rheavendors Group, Westomatic Vending Services Ltd., Rockwell Industries Limited, FAS International, Royal Vendors, Inc., Crane Merchandising, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Vending Machines Market Evolving Landscape
Refrigerated vending architectures are fragmenting into modular, software-defined platforms where hardware standardization meets application-specific customization.
Variable-speed compressor technology is decomposing the traditional fixed-speed paradigm by matching cooling output to real-time thermal load. Hospital and campus operators are specifying these systems for 24-hour duty cycles with fluctuating ambient conditions. The technology is decomposing energy consumption baselines by 30-40% in field deployments, compressing total cost-of-ownership calculations against legacy equipment.
EPA SNAP program phase-down schedules are accelerating hydrocarbon refrigerant adoption timelines across the installed base. Manufacturers must redesign compressor architectures and safety systems to accommodate flammable refrigerant chemistries. Beverage machine segments face compressed redesign cycles as 2025-2027 regulatory deadlines approach, while meal machine categories integrate compliant platforms from initial design.
Facility managers are unbundling after-sales service contracts from equipment procurement, selecting specialized refrigeration service networks over manufacturer-captive programs. Corporate and healthcare buyers are negotiating direct relationships with regional cold-chain service providers. This pattern concentrates in Japan's high-machine-density urban corridors and US hospital campus clusters where uptime requirements exceed standard warranty terms.
Refrigerated Vending Machines Market Segmentation
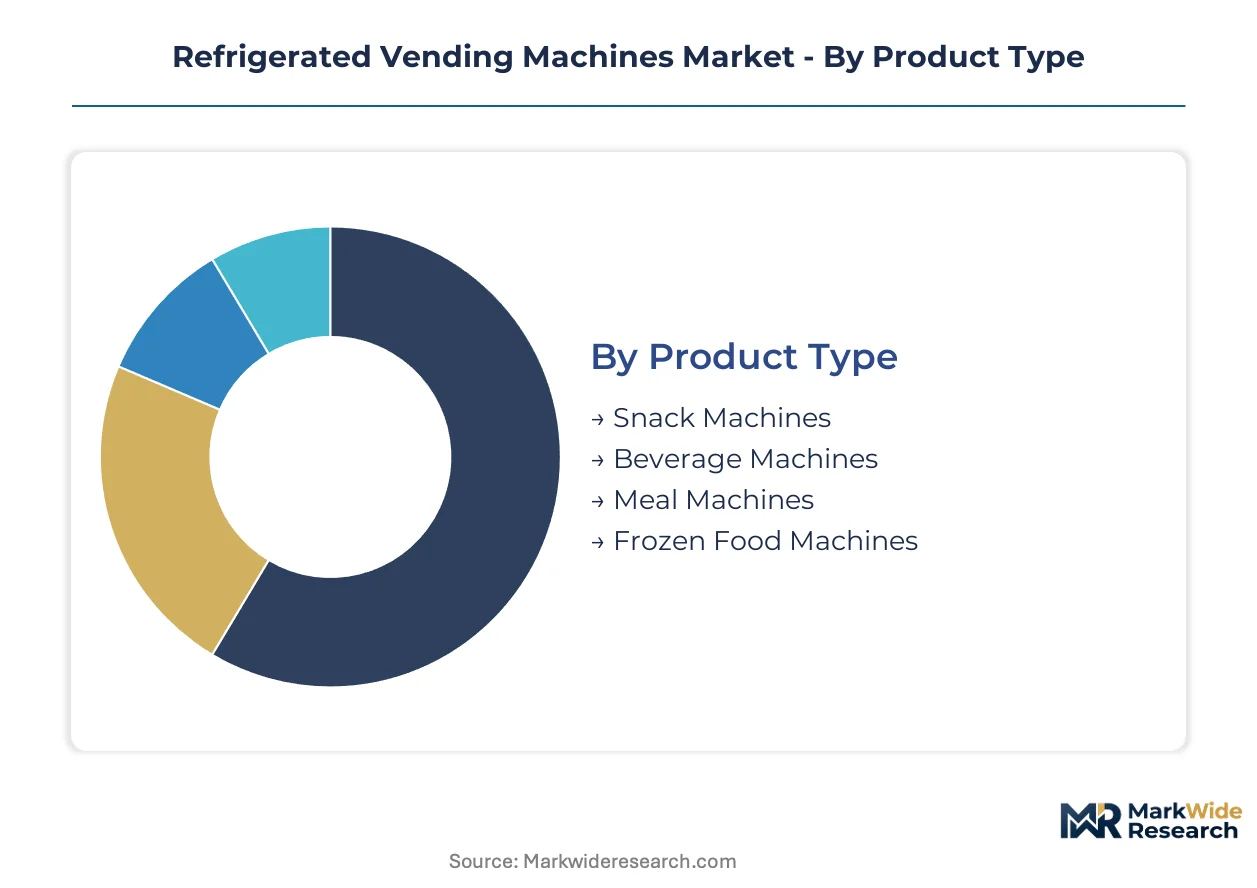
Segmentation in refrigerated vending machines reveals how regulatory pressure, operational requirements, and payment infrastructure reshape procurement decisions across deployment environments. Product categories diverge sharply in cold-chain complexity, while technology adoption clusters around facilities with 24-hour access mandates and connectivity budgets.
Product Type:
EPA SNAP refrigerant phase-down schedules and DOE efficiency standards are fragmenting product development roadmaps by thermal load intensity and duty cycle requirements.
- Beverage Machines:These units maintain simpler cold-chain protocols with uniform temperature zones for packaged drinks, utilizing single-evaporator configurations. Demand concentrates in US hospital campuses and Japanese urban corridors where 24-hour access requirements exceed 10,000 annual operating hours; variable-speed compressor retrofits dominate replacement cycles due to measurable energy recovery.
- Meal Machines:Multi-zone refrigeration architectures preserve fresh prepared foods across protein, produce, and dairy compartments with distinct humidity controls. Corporate and education verticals in Japan are displacing ambient snack options; fresh food program adoption accelerates where on-site cafeteria labor costs exceed unattended retail economics.
- Snack Machines:Hybrid units combine refrigerated and ambient compartments for perishable items alongside shelf-stable alternatives.
- Frozen Food Machines:Deep-freeze architectures maintain minus-18 degrees Celsius for ice cream and prepared meals with enhanced insulation packages.
Beverage machines handle the majority of installed base throughput; meal machines are gaining share fastest as fresh food programs penetrate corporate and healthcare verticals.
Technology:
Cost tier differentiation separates premium connected platforms from basic mechanical units, with payback calculations hinging on labor avoidance and energy recovery.
- IoT-Enabled:Remote diagnostic platforms combine predictive maintenance algorithms with dynamic inventory management through cloud-connected sensors. US hospital operators specify these systems for uptime-critical deployments; METI Top Runner compliance in Japan accelerates adoption where energy monitoring integrates with building management systems.
- Cashless Transactions:Contactless payment modules eliminate cash-handling logistics and expand addressable locations to transit hubs and corporate campuses. Airports and fitness centers prioritize deployment; transaction friction reduction drives volume in high-frequency environments.
- Touchless Options:Gesture-controlled interfaces and mobile app integration reduce surface contact points for hygiene-sensitive settings.
- Digital Displays:Programmable screens enable dynamic pricing and nutritional information presentation for compliance with menu labeling requirements.
Cashless transaction modules anchor the largest deployment volume; IoT-enabled platforms are expanding most quickly in facilities with integrated facility management mandates.
End User:
Application-specific duty cycles and access patterns determine refrigeration architecture specifications and service contract structures.
- Office Buildings:Corporate campuses deploy meal and beverage combinations for hybrid workforce refreshment with extended holding periods. US metropolitan markets concentrate procurement; IRA efficiency incentives compress payback periods for variable-speed compressor upgrades.
- Schools:K-12 and university environments balance nutritional compliance with limited operational windows. USDA school meal standards influence product mix; fresh food program pilots displace traditional snack configurations in districts with kitchen infrastructure constraints.
- Airports:24-hour concession requirements and passenger flow volatility demand high-availability refrigeration with rapid restocking protocols.
- Fitness Centers:Protein-focused product assortments and hydration emphasis drive beverage-dominant configurations with health-positioned SKUs.
Office buildings generate the largest aggregate procurement volume; airports are climbing the fastest on per-location technology specification intensity.
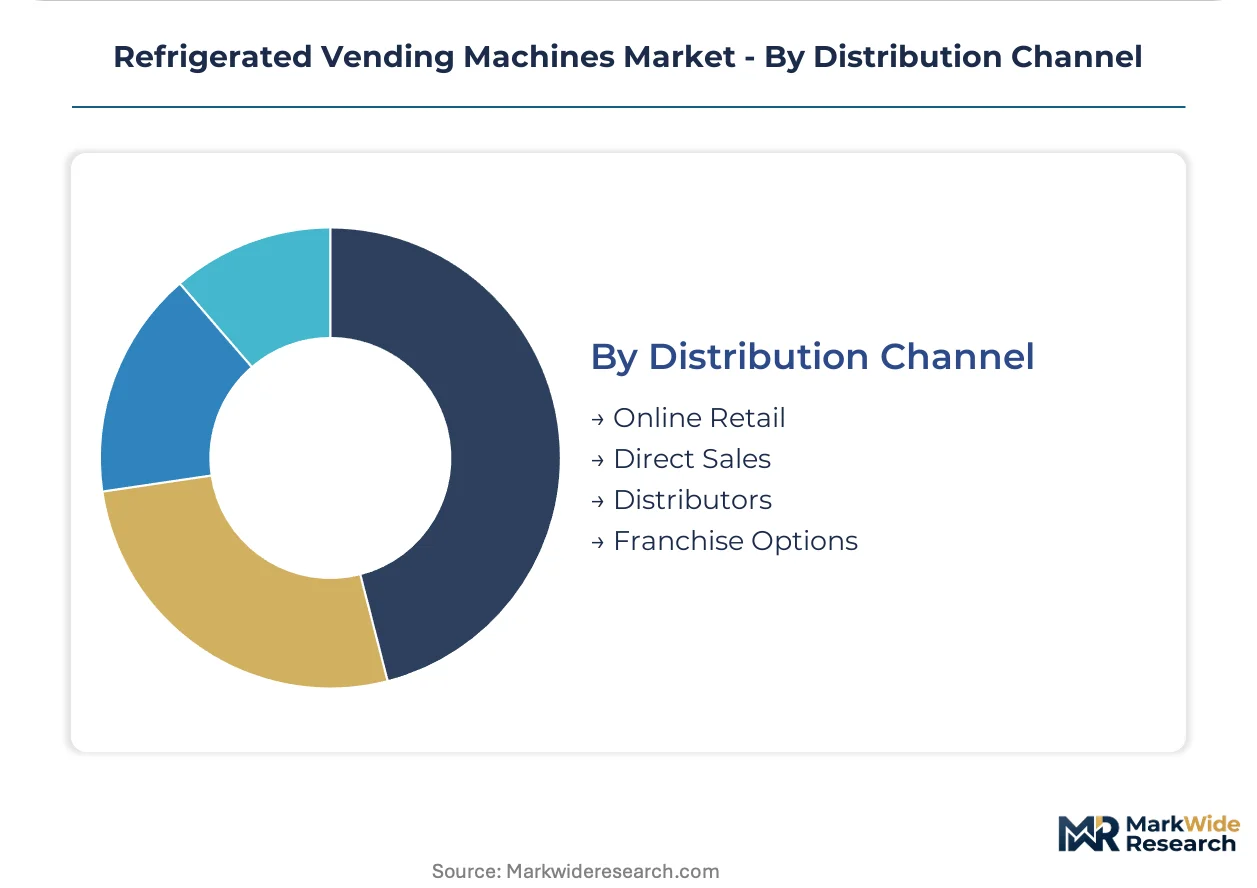
Distribution Channel:
Customer type and procurement sophistication determine channel preference, with integrated service capabilities outweighing equipment-only transactions.
- Direct Sales:Manufacturers maintain captive relationships with large healthcare systems and corporate accounts requiring customized configurations. US hospital campus clusters negotiate directly for standardized fleet deployments; multi-site operators prioritize single-source accountability for warranty and service.
- Distributors:Regional refrigeration specialists bundle equipment with installation and maintenance networks for mid-market accounts. Geographic coverage gaps constrain direct sales economics; distributor relationships concentrate in secondary metropolitan markets.
- Online Retail:E-commerce platforms serve small operators and replacement part procurement with limited configuration support.
- Franchise Options:Turnkey vending business packages combine equipment, location procurement, and operational support for independent operators.
Direct sales channels capture the majority of enterprise-scale transactions; distributor relationships are expanding most quickly in mid-market geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in refrigerated vending machines tilt toward manufacturing concentration in East Asia against equipment absorption in North American healthcare and European transit infrastructure. Japan maintains net exporter status through compressor technology specialization. The United States and Germany represent the largest import markets for premium-configured units.
United States
Hospital campus networks and corporate headquarters drive procurement volumes for 24-hour cold-food access. The Department of Energy enforces commercial refrigeration efficiency standards under its appliance program, compelling variable-speed compressor adoption. Texas and California hospital clusters negotiate standardized fleet deployments with direct manufacturer relationships.
Japan
Aging demographics and convenience culture sustain the highest machine density per capita globally, with urban corridors requiring continuous refreshment access. METI administers Top Runner standards that accelerate efficiency benchmarks beyond international baselines. Tokyo and Osaka metropolitan areas concentrate deployment of IoT-enabled platforms with building management system integration.
Germany
Corporate campus fresh-food programs and railway station concessions expand meal machine penetration against traditional ambient alternatives. The EU F-Gas Regulation mandates refrigerant phase-downs that accelerate hydrocarbon transitions in new equipment. Bavaria and North Rhine-Westphalia industrial zones host manufacturing facilities serving Central European distribution networks.
China
Urban metro systems and airport expansions create deployment corridors for cashless-enabled beverage configurations. National dual carbon goals pressure domestic manufacturers toward energy-efficient cooling architectures. Yangtze River Delta manufacturing clusters supply compressor components and complete units for regional and export markets.
United Kingdom
Transit hub modernization and workplace refreshment services sustain demand for compact footprint designs in space-constrained environments. Post-Brexit regulatory alignment with EU efficiency directives maintains equipment specification continuity. London and Southeast England concentrate procurement for rail station and airport concession networks.
Refrigerated Vending Machines Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology integration vectors. The vendor base organizes into three tiers: diversified industrial conglomerates with captive refrigeration divisions, pure-play vending equipment manufacturers, and regional fabricators serving localized service networks. Consolidation pressures concentrate among mid-scale operators unable to fund hydroc refrigerant transition costs. Dominant competitive moves include strategic partnerships for IoT platform integration and geographic expansion through distributor network acquisition.
Among Japanese and Spanish industrial groups, Fuji Electric Company Ltd. and Azkoyen Group exemplify the technology-integrated archetype, while Seaga Manufacturing, Inc. occupies a position within the specialized compact-design segment. These three entities represent distinct strategic postures: compressor heritage anchoring, payment systems differentiation, and space-constrained deployment specialization respectively.
| Leading Market Players |
|---|
| Fuji Electric Company Ltd. |
| Azkoyen Group |
| Seaga Manufacturing, Inc. |
| Rheavendors Group |
| Westomatic Vending Services Ltd. |
| Rockwell Industries Limited |
| FAS International |
| Royal Vendors, Inc. |
| Crane Merchandising |
| Others |
Value Network & Pricing Analysis
EPA SNAP refrigerant phase-down schedules gate both supplier qualification and price differentiation simultaneously, as hydrocarbon handling certification requirements concentrate production among certified fabricators while energy efficiency tiers separate premium variable-speed configurations from legacy fixed-speed alternatives. Hospital procurement teams and corporate campus operators face compressed payback calculations where IRA efficiency incentives intersect with specialized refrigeration service network availability.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium IoT-enabled platforms, standard efficiency-compliant units, and economy mechanical configurations. Price differentiation rests on Energy Star certification tier and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because hydrocarbon refrigerant conversion expenses concentrate among smaller regional fabricators. Corporate campus operators exhibit highest price sensitivity due to hybrid workforce utilization uncertainty, while hospital networks prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Inventory cycles for variable-speed compressor components stretch across extended lead times as East Asian manufacturing clusters manage capacity allocation between appliance and commercial refrigeration verticals. Component sourcing draws from China for compressor castings, Japan for precision motor assemblies, and South Korea for electronic control modules. Single-source vulnerability concentrates in R-290 and R-600a hydrocarbon refrigerant supply from select chemical manufacturing regions. Distribution runs through manufacturer-direct relationships with healthcare systems alongside regional refrigeration specialist networks serving mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles are accelerating from decade-long horizons toward seven-year refresh intervals as efficiency mandates compress obsolescence timelines. This cyclical recovery is anchored by hospital campus standardization programs and corporate fresh-food program expansion.
For Market Incumbents: Secure hydrocarbon refrigerant handling certification capacity through captive technician training programs or exclusive regional service partnerships. Lock in compressor supply agreements with East Asian motor assembly specialists before capacity allocation shifts toward residential appliance demand. Variable-speed platform standardization represents the critical defensive lever against emerging IoT-native competitors.
For New Entrants and Emerging Players: Lead with cashless payment integration and compact footprint designs targeting space-constrained UK transit hubs and Japanese urban corridors. Corporate education verticals in North America present the most penetrable segment where fresh prepared food programs displace legacy ambient snack configurations. Direct-to-facility-manager digital sales channels bypass incumbent distributor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed vending equipment specialists that consolidated during the previous decade but now face hydrocarbon transition capital requirements. Five-to-ten year viability hinges on IoT platform integration capabilities and installed base service contract attachment rates. Monitor EPA SNAP implementation acceleration as the inflection signal for replacement demand timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Refrigerant Platform Redesign | EPA SNAP compliance deadlines compress development timelines for beverage machine segments. |
| IoT Platform Integration Partnership | Remote diagnostic convergence commands premium positioning in hospital uptime-critical deployments. |
| Variable-Speed Compressor Supply Agreement | East Asian motor assembly capacity anchors energy efficiency differentiation against legacy equipment. |
| Regional Service Network Acquisition | Facility manager unbundling of after-sales contracts creates direct relationship opportunities. |
| Cashless Payment Module Development | Contactless transaction infrastructure unlocks transit hub and corporate campus addressable locations. |
Research Methodology
Desk research of EPA regulatory filings, DOE efficiency standard dockets, and METI Top Runner certification databases preceded structured interviews with vending equipment procurement directors, refrigeration service network operators, and compressor technology specialists. Primary fieldwork with hospital facilities managers and corporate campus refreshment program coordinators validated replacement cycle assumptions. Secondary sources included customs trade records for compressor component flows and SEC disclosures from diversified industrial conglomerates with captive refrigeration divisions. Bottom-up unit economics modeling triangulated against top-down market size estimates.
Variance decomposition across product type, technology tier, and end-use application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base turnover rates segmented by equipment vintage and regulatory compliance status. Segment-level growth trajectories incorporated hospital campus expansion pipelines, corporate hybrid workforce refreshment policies, and refrigerant phase-down implementation schedules.
Underlying assumptions cover hydrocarbon refrigerant supply stability and technician certification capacity expansion, with deviation risk concentrated in multi-standard compliance timeline fragmentation across EPA, DOE, and state-level regulations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Automatic Evisceration System Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Distillation Analyzer Market
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
Food-Grade Mixing Tank Market