
 Food Sorting Machines Market | 2026-2036
Food Sorting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Food Sorting Machines Market Analysis
Stainless steel is hardening as the dominant enclosure and contact-surface material across mid-range and premium sorter configurations, replacing coated carbon steel as processors face stricter washdown protocols. Buhler AG leverages its milling-equipment heritage to anchor integrated sorting-to-grinding lines for grain processors. TOMRA sustains technology leadership in near-infrared detection for nut and seed applications. Sesotec Inc. specializes in electromagnetic systems that detect metallic contaminants in meat processing environments.
Food sorting machines are automated systems that use optical sensors, laser diodes, weight load cells, or electromagnetic coils to classify, grade, or reject food items based on physical properties, chemical composition, or defect presence, operating at throughput rates from 2 to 30 tons per hour depending on product density. Vision systems dominate fresh produce grading where color uniformity and dimensional consistency determine commercial value, while AI-based sorting represents the fastest-expanding technology segment as convolutional neural networks reduce false-reject rates below legacy threshold-based algorithms. Optical sorters occupy the largest installed base across grains and nuts, though laser sorters command premium pricing in protein applications where bone fragment detection carries liability exposure.
FDA enforcement of FSMA preventive controls mandates documented foreign-material intervention points, directly expanding mandatory sorter deployment across US food processing facilities. EFSA hazard analysis frameworks and EU Green Deal sustainability targets are converging to reward European processors that reduce food waste through precision sorting, while China's SAMR food safety audits are accelerating domestic equipment substitution for imported legacy systems. Stakeholders must monitor how regulatory divergence between hazard-analysis mandates and sustainability reporting obligations reshapes equipment specification priorities across their installed base.
Market Dynamics
AI-based detection algorithms are compressing false-reject rates below legacy threshold systems, forcing processors to retire mechanical sorters ahead of depreciation schedules and rewiring competitive advantage toward data-science capabilities.
Growth Catalysts
- FSMA preventive controls:FDA mandates documented foreign-material intervention points across US food processing facilities, expanding mandatory sorter deployment at critical control points.
- Near-infrared spectroscopy:Nut and seed processors deploy advanced optical detection to identify aflatoxin contamination and shell fragments, reducing liability exposure and premium downgrades.
- China's equipment substitution:SAMR food safety audits accelerate domestic sorter procurement as local manufacturers scale production capacity and match imported system performance.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 enclosure material costs fluctuate with nickel and molybdenum spot markets, compressing margin on mid-range system configurations.
- Optical sensor supply concentration:High-resolution CMOS arrays and specialized laser diodes concentrate among Japanese and German component suppliers, creating single-source vulnerability.
- Legacy mechanical system entrenchment:Smaller grain cooperatives and regional meat processors defer capital replacement where existing sorters operate below failure threshold.
Strategic Opportunities
- India FSSAI enforcement expansion:Packaged food safety audits in secondary cities create first-mover advantage for automated sorting lines in spice and pulse processing clusters.
- EU Green Deal food waste targets:Precision sorting systems that recover off-grade produce for secondary processing qualify for sustainability-linked financing and procurement preference.
- Hyperspectral-plus-AI convergence:Combining chemical imaging with convolutional neural networks enables real-time moisture and protein mapping in grain streams, opening premium pricing tiers.
Industry Challenges
- Machine vision engineer scarcity:Food equipment OEMs compete with autonomous vehicle and medical imaging sectors for talent capable of training production-grade detection models.
- Legacy PLC integration complexity:Brownfield facilities require custom middleware to connect AI sorters to existing SCADA architectures, extending commissioning timelines and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Sorting Machines Market |
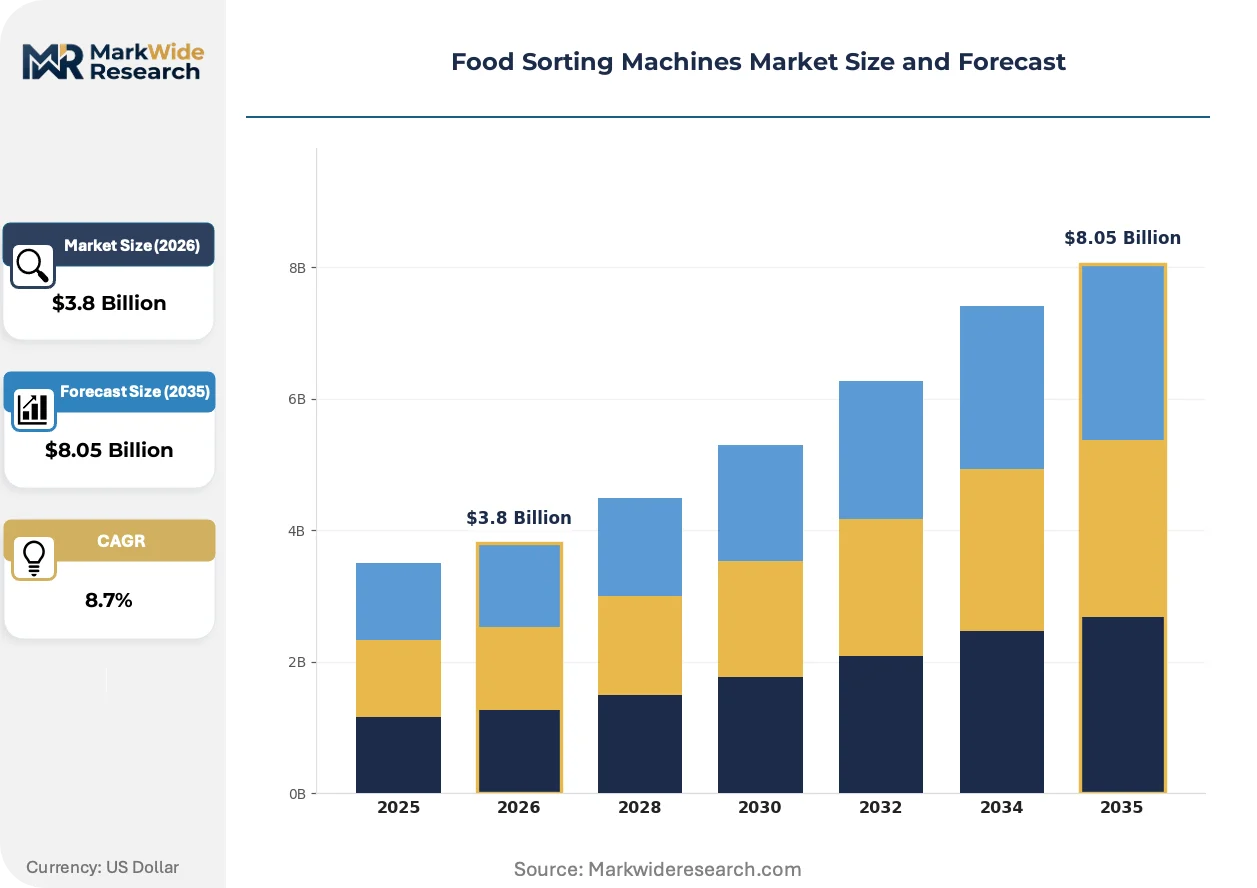
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sorters, Laser Sorters, Weight Sorters, Mechanical Sorters Technology: Vision Systems, Infrared Technology, Electromagnetic Systems, AI-Based Sorting End User: Agriculture, Food Processing, Retail, Packaged Foods Application: Fruits & Vegetables, Grains, Nuts & Seeds, Meat Products |
| Companies Covered | Buhler AG, Raytec Vision SpA, TOMRA, Pellenc ST, Aweta G & P BV, Sesotec Inc., Key Technology Inc., Newtec, Satake Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Sorting Machines Market Emerging Trajectories
Convolutional neural networks are rewiring detection architectures while regulatory mandates harden intervention-point requirements and procurement patterns concentrate among integrated food conglomerates.
Hyperspectral imaging is integrating chemical composition mapping into standard optical sorter configurations. Protein processors and oilseed refiners adopt these systems to detect oil content variation and contaminant signatures in real time. The technology is integrating formerly separate laboratory testing stages into inline production workflows, collapsing quality-control cycle times from hours to milliseconds.
EU Green Deal sustainability targets and EFSA hazard analysis frameworks are converging to reward precision sorting that reduces food waste. Processors documenting waste-reduction metrics gain preferential access to sustainability-linked credit facilities and retail procurement programs. Nut and seed applications in the Netherlands and Denmark lead adoption as these markets face combined regulatory pressure and retailer audit intensity.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale produce packers. Third-party financing vehicles now underwrite sorter deployments against throughput-based performance guarantees, transferring obsolescence risk from processor to OEM. California's Central Valley vegetable cooperatives and Spain's Almería greenhouse clusters exhibit the fastest contract penetration where seasonal cash flow volatility discourages lump-sum investment.
Food Sorting Machines Market Segmentation
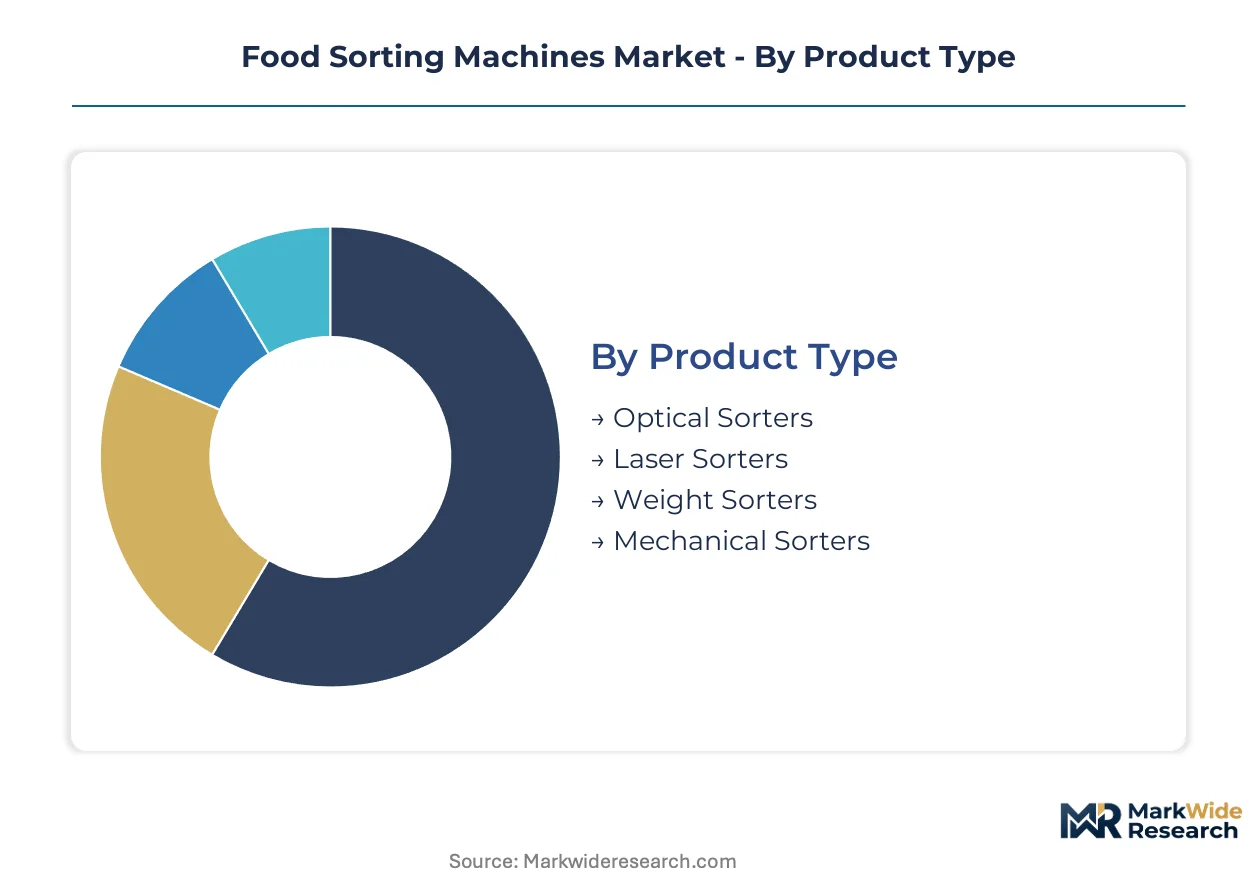
Segmentation reveals how processor requirements diverge across contamination risk profiles, throughput demands, and regulatory exposure. Equipment specification priorities shift dramatically between a grain elevator facing volume economics and a meatpacking plant managing liability thresholds.
Product Type:
Capital allocation intensity separates configurations, with premium systems commanding three to five times the upfront outlay of mechanical alternatives.
- Optical Sorters:These systems deploy CCD or CMOS sensors paired with pneumatic ejection mechanisms to remove discolored, misshapen, or foreign objects from product streams. Demand concentrates in grain elevators across the US Midwest and Canadian prairies, where FSMA preventive controls mandate documented intervention points and volume throughput justifies capital deployment.
- Laser Sorters:Specialized diode arrays detect bone fragments, glass shards, and high-density contaminants in protein processing environments. Poultry processors in the US Southeast and pork packers in Denmark deploy these systems where liability exposure from foreign material claims drives specification toward detection sensitivity over capital cost.
- Weight Sorters:Load-cell arrays classify items by mass for grading and portion control applications. Fresh produce packers in California's Central Valley and Spain's Almería region favor these systems for export-grade citrus and stone fruit operations.
- Mechanical Sorters:Sieves, diverters, and density-based separators persist in low-margin commodity processing where capital constraints outweigh detection precision requirements. Regional grain cooperatives in India and Brazil continue operating legacy installations below failure thresholds.
Volume sits with Optical Sorters; growth tilts toward Laser Sorters.
Technology:
Detection architecture maturity creates a performance gradient that processors navigate based on product value density and contamination consequence severity.
- Vision Systems:Color and shape recognition algorithms classify fresh produce by cosmetic grade, dimensional uniformity, and defect presence. These systems dominate apple and potato packing operations in Washington State and Idaho, where retail procurement specifications enforce strict appearance standards.
- Infrared Technology:Near-infrared spectroscopy identifies chemical composition variations including moisture content, protein levels, and aflatoxin contamination signatures. Oilseed crushers in the Netherlands and nut processors in California deploy these systems to prevent premium downgrades and food safety recalls.
- Electromagnetic Systems:Coil-based metal detection targets ferrous and non-ferrous contaminants in ground meat and processed protein streams. Meatpacking facilities across Germany and Australia integrate these at critical control points mandated by EFSA hazard analysis frameworks.
- AI-Based Sorting:Convolutional neural networks trained on defect libraries reduce false-reject rates below legacy threshold algorithms. This architecture is expanding most quickly among mid-scale processors in China where SAMR audit intensity accelerates automation investment.
Installed base concentrates in Vision Systems; capability investment flows toward AI-Based Sorting.
End User:
Regulatory proximity and brand exposure determine automation urgency, with consumer-facing segments deploying intervention systems earlier in the value chain.
- Agriculture:Post-harvest handling operations at grain elevators, cotton gins, and produce consolidation points deploy sorters to meet elevator grading standards and export phytosanitary requirements. Operations across Australia's wheat belt and Argentina's soybean regions prioritize throughput over detection sophistication.
- Food Processing:Intermediate manufacturers transforming raw agricultural commodities into ingredients and intermediate products face the most intensive foreign material control mandates. US-based flour millers and EU oilseed crushers represent the core demand concentration for multi-stage sorting lines.
- Retail:Private-label packers and ready-to-eat meal assemblers deploy final-stage sorters immediately upstream of consumer packaging. UK supermarket supply chains and Japanese convenience food manufacturers specify detection capabilities that exceed regulatory minima to protect brand equity.
- Packaged Foods:Branded consumer goods manufacturers with national distribution networks integrate sorting at multiple process stages. Multinational snack food and breakfast cereal producers in Switzerland and the US deploy capital most aggressively to defend against recall liability.
Deployment density peaks in Food Processing; specification intensity climbs fastest in Packaged Foods.
Application:
Product physical properties and contamination risk profiles dictate sensor selection, with fragile or irregular items demanding gentler handling architectures.
- Fruits & Vegetables:Soft, irregular, and moisture-variable products require belt-fed gentle handling systems with color and blemish detection. California lettuce processors and Italian tomato paste manufacturers lead adoption of hyperspectral-plus-vision integrated lines.
- Grains:Homogeneous, high-density, and free-flowing characteristics enable gravity-fed chute sorters with high throughput rates. Wheat and corn processors across the US Great Plains and Black Sea region represent the largest addressable equipment base.
- Nuts & Seeds:Shell fragment detection and aflatoxin screening drive specification toward near-infrared and X-ray integration. Almond handlers in California's Central Valley and pistachio processors in Iran deploy the most sophisticated multi-sensor configurations.
- Meat Products:Bone, cartilage, and foreign material detection in fresh and frozen protein streams commands the highest detection sensitivity specifications. Poultry further-processors in Thailand and Brazil and beef packers in Australia drive demand for laser and X-ray systems.
Equipment population centers on Grains; technology upgrade urgency concentrates in Meat Products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates equipment procurement as domestic manufacturers scale production capacity to match imported system performance. The United States and Germany anchor premium technology adoption through regulatory enforcement. Brazil and India represent emerging deployment frontiers where capital constraints are easing.
China
Domestic food safety audits by SAMR accelerate automation investment across nut processing and oilseed crushing facilities. Local equipment makers in Jiangsu and Shandong provinces now match near-infrared detection specifications previously imported from European suppliers. Yangtze River Delta processors deploy AI-based sorters at critical control points to satisfy export phytosanitary requirements for almond and pistachio shipments.
United States
FSMA preventive controls mandate documented foreign-material intervention points across grain elevators and meatpacking plants. Poultry processors in Georgia and Arkansas specify laser-based bone detection systems ahead of depreciation schedules for mechanical alternatives. California's Central Valley vegetable cooperatives pilot equipment-as-a-service contracts to manage seasonal cash flow volatility.
Germany
EFSA hazard analysis frameworks converge with EU Green Deal targets to reward precision sorting that reduces food waste. Oilseed refiners in Hamburg and oil mills in Bavaria integrate hyperspectral imaging for real-time protein mapping. Baden-Württemberg equipment fabricators supply multi-sensor configurations to nut processors across the Netherlands and Denmark.
Brazil
Federal agricultural inspection intensification drives sorter deployment at soybean export terminals in Mato Grosso. Meatpackers in São Paulo and Paraná states face liability exposure from foreign material claims in EU-bound beef shipments. Regional grain cooperatives in Rio Grande do Sul defer full automation where legacy mechanical systems operate below failure thresholds.
India
FSSAI enforcement expansion into secondary cities creates first-mover opportunities in spice and pulse processing clusters. Turmeric and cumin graders in Gujarat and Rajasthan deploy optical sorters to satisfy export quality specifications. Maharashtra-based packaged food manufacturers integrate electromagnetic detection systems at critical control points mandated by preventive control rules.
Food Sorting Machines Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology leadership concentrating among Swiss and Norwegian precision engineering groups while regional fabricators capture mid-range volume. The vendor base organizes into three strategic archetypes: integrated food processing equipment conglomerates, pure-play optical detection specialists, and regional stainless-steel fabrication houses. Competitive dynamics center on M&A activity targeting AI detection capabilities and strategic partnerships linking component suppliers to system integrators.
Among European precision engineering groups, Buhler AG and TOMRA occupy positions exemplifying integrated technology leadership, with Buhler leveraging milling-equipment heritage and TOMRA sustaining near-infrared detection specialization. Raytec Vision SpA represents Italian optical systems expertise concentrated in fresh produce applications. Sesotec Inc. anchors electromagnetic detection capabilities for protein processing environments. These three archetypes—integrated conglomerate, optical specialist, and contaminant-detection focused—structure competitive positioning across premium and mid-range configuration tiers.
| Leading Market Players |
|---|
| Buhler AG |
| Raytec Vision SpA |
| TOMRA |
| Pellenc ST |
| Aweta G & P BV |
| Sesotec Inc. |
| Key Technology Inc. |
| Newtec |
| Satake Corporation |
| Others |
Supply Flow & Price Mechanics
Convolutional neural network integration into detection architectures is simultaneously compressing hardware cost curves and concentrating procurement power among OEMs with captive AI development capabilities. Stainless steel enclosure specifications and high-resolution CMOS sensor sourcing now determine margin structures across premium and mid-range system tiers.
Pricing Analysis
Volume concentrates in optical sorter configurations where economies of scale compress unit economics; margins concentrate in laser and hyperspectral systems where detection sensitivity commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled multi-sensor platforms from threshold-based optical units and legacy mechanical alternatives. Pricing pressure stems from Chinese domestic equipment makers scaling production capacity and matching European near-infrared specifications at reduced cost points. Regional grain cooperatives and mid-scale produce packers exhibit highest price sensitivity; multinational packaged food manufacturers prioritize detection performance over capital outlay.
Supply Chain Analysis
Certification gating through FDA preventive control documentation and EFSA hazard analysis frameworks restricts component sourcing to qualified suppliers with validated washdown protocols and traceable material certifications. High-resolution CMOS arrays and specialized laser diodes draw from Japanese and German component suppliers, creating single-source vulnerability for optical detection subsystems. Grade 304 and 316 stainless steel feeds from Chinese and Indonesian nickel processing, exposing enclosure fabrication to commodity price volatility. Distribution runs through OEM direct sales for premium integrated lines and regional fabrication houses for mid-range mechanical configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food sorting equipment is transitioning from threshold-based mechanical systems to AI-enabled detection architectures, compressing replacement cycles and rewiring competitive advantage toward data-science capabilities and software-defined performance guarantees.
For Market Incumbents: Lock in technology leadership through backward integration into AI model training infrastructure and sensor calibration capabilities. Acquire specialist computer vision engineering teams before autonomous vehicle and medical imaging sectors exhaust available talent pools. Defend installed base relationships by offering equipment-as-a-service contracts that transfer obsolescence risk from processors to OEM balance sheets. For New Entrants and Emerging Players: Mid-scale spice and pulse processors in India's secondary cities represent an underserved buyer archetype with accelerating FSSAI enforcement and limited incumbent penetration. Target equipment-as-a-service financing vehicles to overcome seasonal cash flow constraints among California vegetable cooperatives and Spanish greenhouse clusters. Position around rapid commissioning capabilities and legacy PLC integration middleware to capture brownfield retrofit opportunities. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated food processing equipment conglomerates seeking AI detection capabilities and regional fabrication capacity. Long-term viability favors vendors with software-defined architectures capable of over-the-air model updates and performance-based contracting. Monitor SAMR audit intensity and FSSAI enforcement expansion as demand inflection indicators signaling automation investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Detection Model Development | Convolutional neural networks reduce false-reject rates below legacy threshold algorithms, defending premium positioning. |
| Equipment-as-a-Service Launch | Throughput-based performance guarantees transfer obsolescence risk and capture recurring revenue from seasonal processors. |
| Hyperspectral Imaging Integration | Real-time chemical composition mapping collapses quality-control cycle times from laboratory testing to inline milliseconds. |
| Regional Fabrication Expansion | Jiangsu and Shandong province production capacity matches European near-infrared specifications at reduced procurement cost. |
| Legacy System Integration Middleware | Custom SCADA connectivity accelerates brownfield commissioning timelines and reduces processor disruption during retrofit. |
Methodological Framework
Independent corroboration across equipment OEM technical directors, food processing plant engineers, and component supplier product managers underwrites the qualitative findings. Primary interviews with maintenance directors at grain elevators, quality assurance leads at nut processing facilities, and procurement teams at packaged food manufacturers combined with secondary validation from FDA FSMA guidance documents, EFSA hazard analysis frameworks, and SAMR food safety audit protocols. Bottom-up triangulation across installed base estimates and top-down validation against capital expenditure disclosures anchored segmentation outputs.
Comparable-period anchoring to historical replacement cycles for mechanical sorters and AI adoption curves in adjacent inspection equipment calibrated the forecast window. The analytical framework modeled demand across product type, detection technology, end-user segment, and application category throughout the projection horizon. CAGRs derived from regression analysis against regulatory enforcement intensity, capital availability indices, and technology substitution rates. Industry-specific inputs included stainless steel price volatility indices and machine vision engineer supply constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between hazard-analysis mandates and sustainability reporting obligations, component supply concentration risks, and talent scarcity in production-grade detection model development. Forecasts reflect documented assumptions regarding enforcement continuity and technology cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Edible Oil Extracting Machine Market