
 Aseptic Processing Market | 2026-2036
Aseptic Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Processing Market Analysis
Modular isolator-based filling lines is hardening as the dominant configuration pattern for sterile drug manufacturing, replacing traditional cleanroom suites across biopharma capital budgets. Robert Bosch GmbH leverages its German automation heritage to dominate high-speed vial filling systems. GEA Group anchors European demand with integrated freeze-dry and fill-finish platforms. Syntegon Technology specializes in compact, single-use isolator designs for emerging biotech customers.
Aseptic processing denotes the sterilization and handling of drug products, medical devices, or food items in sealed environments where ISO 5 air quality, HEPA filtration, and positive pressure differentials prevent microbial contamination throughout filling, sealing, and packaging operations. Its primary purpose is to deliver terminally sterilized or preservative-free products—particularly biologics with heat-labile active ingredients—without compromising sterility assurance levels. Injectable drugs command the largest application share due to chronic disease biologic portfolios, while cell therapy represents the fastest-expanding segment as personalized medicine strains existing cleanroom infrastructure. Heat sterilization retains technology leadership for terminal sterilization of stable small molecules, though filtration is displacing legacy approaches for temperature-sensitive biologics.
The FDA enforces current Good Manufacturing Practice (cGMP) requirements through sterile drug inspection programs that mandate continuous environmental monitoring and validated cleaning protocols. The European Medicines Agency (EMA) applies Annex 1 manufacturing guidelines, which now require barrier isolation technology for all new aseptic processing installations across EU member states. The International Organization for Standardization (ISO) publishes ISO 14644 cleanroom classifications that equipment vendors must certify against for global market access. Stakeholders should monitor whether FDA enforcement discretion on legacy cleanroom operations tightens ahead of anticipated guideline revisions, as this would trigger accelerated capital redeployment toward isolator-based infrastructure.
Market Dynamics
Modular isolator technology is compressing facility construction timelines from years to months while forcing biopharma capital allocation away from traditional cleanroom infrastructure toward sealed barrier systems.
Growth Catalysts
- EMA Annex 1 Revision:The European Union's updated manufacturing guidelines now mandate barrier isolation for all new aseptic installations, compelling facility upgrades across member states.
- Cell Therapy Manufacturing:Personalized medicine production requires patient-specific batch processing that only flexible isolator configurations can accommodate at commercial scale.
- German Precision Engineering:Stuttgart and Munich industrial clusters supply advanced robotics and sensor systems that enable next-generation filling line automation.
Market Restraints
- Stainless Steel Supply Concentration:High-grade 316L stainless steel for isolator fabrication depends on concentrated European and Japanese metallurgical suppliers, creating input cost volatility.
- Validation Timeline Compression:FDA sterile drug inspection protocols extend commissioning periods for new isolator lines, delaying revenue recognition.
- Terminal Sterilization Persistence:Heat-stable small molecule injectables retain cost advantages over aseptic processing for generic portfolios, limiting technology displacement.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru seek isolator retrofits to serve export markets under EMA-equivalent standards.
- Single-Use Convergence:Integration of disposable fluid path technologies with fixed isolator shells reduces changeover downtime for multi-product facilities.
- Continuous Processing Mandates:FDA quality-by-design initiatives reward real-time release testing implementations that isolator-based lines enable.
Industry Challenges
- Contamination Control Expertise Gap:Facilities struggle to recruit personnel with combined microbiology and automation competencies for isolator operation.
- Legacy Cleanroom Stranded Assets:Biopharma sites face write-down pressure on conventional suite infrastructure that cannot be economically converted to barrier technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Processing Market |
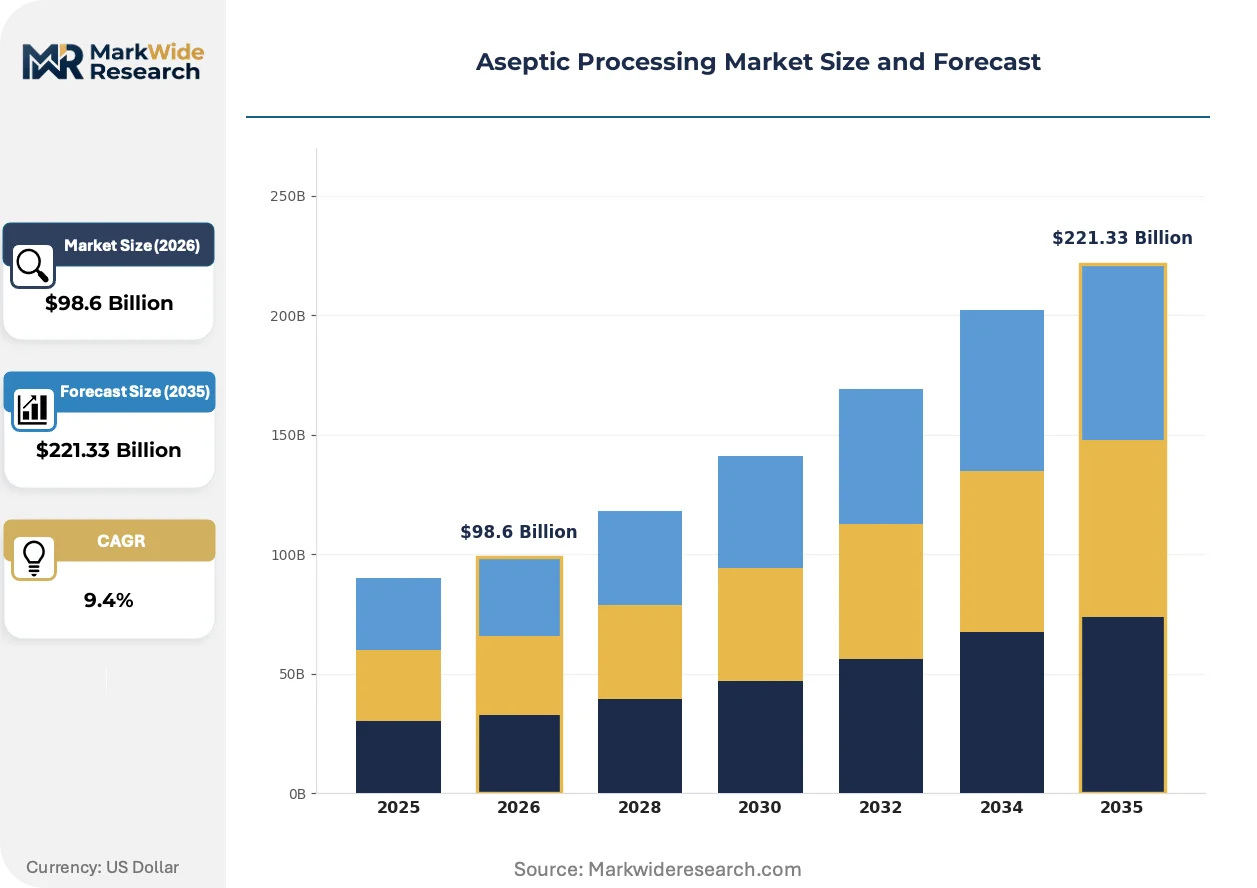
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $221.33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Vials, Bottles, Ampoules Technology: Filtration, Heat Sterilization, Irradiation, Chemical Sterilization End User: Pharmaceutical Companies, Biotechnology Firms, Research Organizations, Hospitals Application: Injectable Drugs, Nutritional Products, Vaccines, Cell Therapy |
| Companies Covered | Robert Bosch GmbH, Tetra Laval, SPX FLOW, DuPont, IMA Group, GEA Group, Amcor, Becton Dickinson, Syntegon Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Processing Market Emerging Trajectories
Automation architecture is bifurcating between high-throughput fixed installations and rapidly deployable modular units, with regulatory pressure accelerating the obsolescence of intermediate configurations.
Restricted access barrier systems are modularizing around standardized skids that ship pre-validated from German and Swiss manufacturing centers. Mid-sized biotechs in Boston and San Francisco now specify 12-week deployment timelines versus 18-month traditional builds. This compression is enabling virtual pharmaceutical companies to retain manufacturing control without facility ownership.
EMA's 2022 Annex 1 update eliminated the distinction between cleanroom and isolator-based aseptic processing for new facilities, effectively mandating sealed barrier technology. Legacy suite operators in Italy and Spain face accelerated depreciation schedules as national inspectors align with Brussels guidance. The regulation is concentrating upgrade investment in fill-finish assets rather than upstream bioreactor capacity.
Biopharma procurement departments now unbundle equipment purchase from validation service contracts, forcing vendors to compete on lifecycle cost rather than capital expenditure alone. This shift favors European suppliers with captive service networks over Asian equipment manufacturers lacking regional technical presence. The pattern is most pronounced among German and Swiss pharmaceutical firms with centralized engineering procurement functions.
Aseptic Processing Market Segmentation
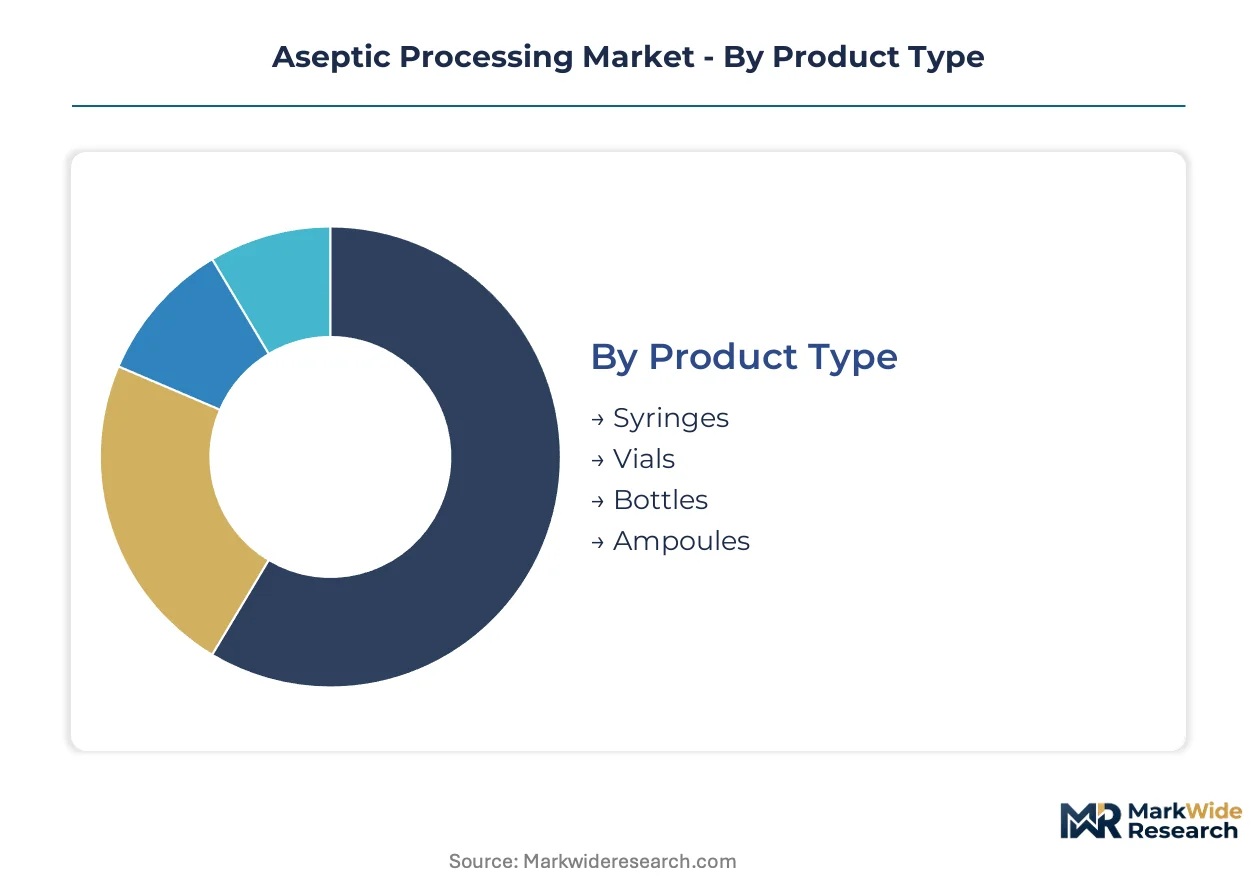
Aseptic processing equipment configurations vary dramatically by product format, sterilization method, and end-user scale. Capital allocation decisions across these dimensions determine facility throughput, validation complexity, and regulatory compliance posture.
Product Type:
Capital intensity escalates with container complexity and closure integrity requirements. Vial filling systems demand the highest upfront investment due to multi-step handling and stoppering automation.
- Vials:Borosilicate glass containers with rubber stoppers and aluminum seals dominate biologic storage. German precision engineering clusters in Stuttgart supply high-speed rotary filling systems for monoclonal antibody portfolios.
- Syringes:Pre-filled delivery formats integrate plunger assembly and needle attachment within barrier isolators. Demand concentrates at Massachusetts biotechs developing autoinjector-compatible formats for chronic disease administration.
- Bottles:Larger volume containers serve ophthalmic and respiratory solutions. Blow-fill-seal technology reduces capital requirements versus isolator-based alternatives.
- Ampoules:Single-dose glass containers with flame-sealed necks retain niche application for emergency medicine and anesthetics. European generic manufacturers maintain legacy lines for cost-sensitive markets.
Vials absorb the bulk of installed capacity; cell therapy applications are expanding most quickly.
Technology:
Technology selection hinges on active ingredient thermal stability and terminal sterility requirements. Heat-labile biologics drive filtration infrastructure investment despite higher operating costs.
- Filtration:Membrane-based sterilization through 0.22-micron rated filters preserves protein structure for monoclonal antibodies and cell therapy suspensions. Biotechnology firms in Boston and San Francisco specify single-use filtration trains integrated with isolator shells.
- Heat Sterilization:Moist and dry heat methods achieve terminal sterilization for stable small molecules. Generic injectable manufacturers in India retain autoclave-based lines for cost-competitive portfolios.
- Irradiation:Gamma and electron beam methods penetrate sealed packaging for terminal sterilization of medical devices and combination products. Contract manufacturers in Switzerland operate centralized irradiation facilities serving European pharma.
- Chemical Sterilization:Ethylene oxide and vaporized hydrogen peroxide address heat-sensitive and moisture-sensitive materials. Medical device packaging applications dominate this segment.
Heat sterilization retains the largest installed base; filtration is climbing the fastest as biologic pipelines expand.
End User:
End-user scale determines automation level and regulatory inspection intensity. Multi-product facilities prioritize flexibility; dedicated sites maximize throughput.
- Pharmaceutical Companies:Large-cap firms operate integrated fill-finish networks with captive isolator lines. German and Swiss headquarters centralize engineering procurement for global facility standardization.
- Biotechnology Firms:Mid-sized developers deploy modular isolator skids for clinical-to-commercial transitions. California and Massachusetts clusters specify 12-week deployment timelines from Syntegon and GEA.
- Research Organizations:Academic and government laboratories utilize bench-scale isolators for early-phase formulation. Lower throughput requirements permit manual intervention protocols.
- Hospitals:Compounding pharmacies operate under USP 797 guidelines for patient-specific preparations. Outsourcing trends reduce hospital-based aseptic processing volume.
Pharmaceutical companies command the majority of capital deployment; biotechnology firms are gaining share fastest.
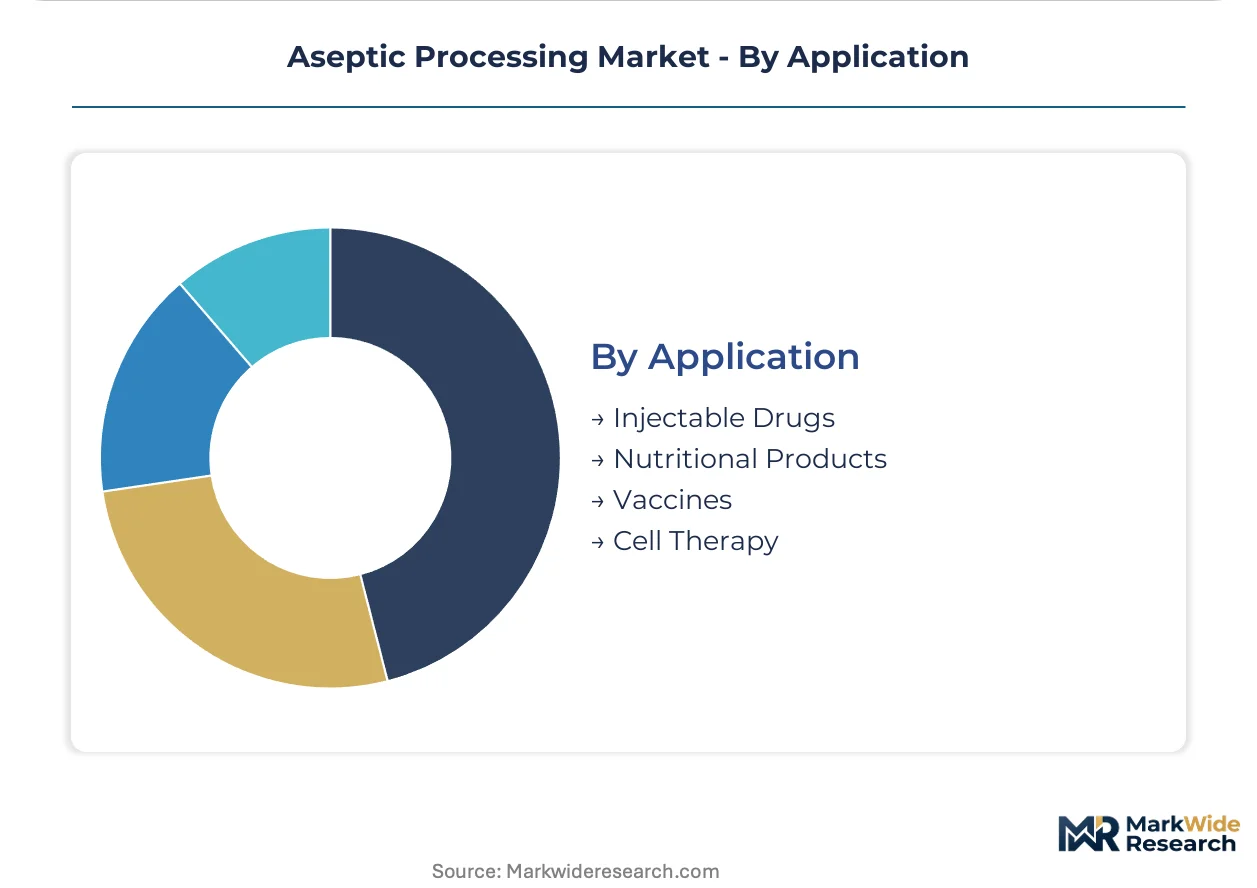
Application:
Application segmentation reflects therapeutic modality and sterility assurance level requirements. Injectable biologics set the technical benchmark for contamination control.
- Injectable Drugs:Parenteral formulations including monoclonal antibodies, insulin, and anticoagulants require ISO 5 environments with continuous monitoring. Chronic disease portfolios at Roche, Novo Nordisk, and Sanofi drive recurring capacity expansion.
- Cell Therapy:Patient-specific autologous products demand flexible batch processing within closed isolator systems. CAR-T manufacturing in Pennsylvania and Maryland strains existing cleanroom infrastructure.
- Vaccines:Pandemic preparedness programs and routine immunization sustain fill-finish demand. Multi-dose vial formats reduce per-dose processing costs.
- Nutritional Products:Enteral and parenteral nutrition solutions serve critical care and home infusion markets. Lower regulatory scrutiny permits less complex barrier configurations.
Injectable drugs anchor current capacity; cell therapy shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in German precision engineering clusters, while biopharma consumption spreads across North American and European drug development hubs. This geographic split shapes trade flows and regulatory alignment priorities.
United States
FDA sterile drug inspection programs and cell therapy manufacturing expansion drive isolator demand. The agency's quality-by-design initiatives reward real-time release testing implementations. Pennsylvania and Maryland host CAR-T manufacturing sites straining existing cleanroom infrastructure.
Germany
EMA Annex 1 barrier isolation mandates and domestic biopharma capital budgets sustain equipment production. Stuttgart and Munich industrial clusters supply advanced robotics for next-generation filling line automation. Bosch and GEA anchor European supply from Baden-Württemberg and North Rhine-Westphalia facilities.
Switzerland
Swissmedic enforcement of EU-equivalent standards and contract manufacturing concentration create premium equipment demand. The country's pharmaceutical headquarters centralize engineering procurement for global facility standardization. Basel and Zug host centralized irradiation facilities serving European pharma.
India
CDSCO export compliance requirements and Hyderabad-Bengaluru CDMO expansion drive isolator retrofits. The country's national pharmaceutical regulator aligns inspection protocols with EMA-equivalent standards for global market access. Telangana and Karnataka clusters seek barrier technology to serve international clients.
China
NMPA biologic approval acceleration and domestic monoclonal antibody pipeline growth expand sterile fill-finish capacity. The national medical products administration harmonizes GMP inspections with international standards. Yangtze River Delta biotech clusters import European isolator systems for commercial manufacturing.
Aseptic Processing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment tiers. Market structure shows moderate consolidation around German automation heritage and European precision engineering. Three archetypes dominate: integrated engineering conglomerates with captive pharmaceutical divisions, standalone filling equipment specialists, and packaging material suppliers extending into barrier systems. Competitive moves center on validation service bundling and modular skid pre-certification to compress customer deployment timelines.
Among German-based engineering conglomerates, Robert Bosch GmbH and GEA Group exemplify the integrated archetype, combining precision automation with lifecycle service networks. Syntegon Technology occupies a position among compact isolator specialists serving emerging biotech customers with rapid deployment configurations. These three anchors represent distinct strategic postures: scale-driven full-line integration, mid-market flexibility, and emerging-customer accessibility.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Tetra Laval |
| SPX FLOW |
| DuPont |
| IMA Group |
| GEA Group |
| Amcor |
| Becton Dickinson |
| Syntegon Technology |
| Others |
Supply Flow & Price Mechanics
Large-cap pharmaceutical companies with centralized engineering procurement functions command volume-based contract structures that compress vendor margins across European and North American equipment markets. Their consolidated purchasing power forces suppliers to compete on lifecycle service bundling rather than capital expenditure alone.
Pricing Analysis
Margin tightening in mid-tier isolator systems reflects German precision engineering clusters absorbing stainless steel input volatility while maintaining EMA Annex 1 compliance certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates validated high-speed rotary lines from compact single-use skids and refurbished legacy configurations. Pricing pressure stems from biotechnology firms unbundling equipment purchase from validation contracts. Generic injectable manufacturers in India exhibit highest price sensitivity; Swiss and German pharmaceutical headquarters show lowest sensitivity due to captive lifecycle cost modeling.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's import substitution policies are reshaping sourcing patterns for high-grade 316L stainless steel and precision robotics components. Fabrication draws from German, Swiss, and Japanese metallurgical suppliers for isolator shells and sensor systems. Critical dependencies include HEPA filtration media, servo motor assemblies, and borosilicate glass vials. Single-source vulnerability concentrates in European stainless steel mills serving barrier isolation infrastructure. Distribution runs through direct vendor-to-facility contracts with captive installation and validation service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized containment engineering talent scarcity props pricing power for vendors with validated service networks, creating durable returns for incumbents with captive technical workforces.
For Market Incumbents: Deploy backward integration into precision sensor manufacturing to secure component supply against Japanese and German robotics supplier concentration. Consolidate validation service capabilities through regional technical center expansion in Hyderabad and Boston biotech clusters. EMA Annex 1 enforcement tightening threatens legacy cleanroom operators with accelerated depreciation exposure. For New Entrants and Emerging Players: CDMO procurement departments in Telangana and Karnataka represent the most penetrable buyer segment for rapid-deployment modular isolator skids. Target 12-week commissioning timelines as the primary go-to-market wedge against established European vendors with 18-month traditional build cycles. Single-use convergence with fixed isolator shells offers white-space positioning for clinical-to-commercial transition facilities. For Investors and Strategic Acquirers: The window for entry favors pure-play isolator specialists with pre-certified modular platforms over diversified engineering conglomerates. Long-term viability hinges on regulatory certification moats and service network density rather than manufacturing scale alone. Watch FDA enforcement discretion on legacy cleanroom operations as the inflection signal for accelerated capital redeployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Service Network Expansion | Captive technical presence in Massachusetts and Maryland biotech clusters locks in recurring revenue streams. |
| Single-Use Technology Integration | Disposable fluid path convergence with fixed isolator shells reduces multi-product facility changeover downtime. |
| EMA Annex 1 Pre-Certification | Pre-validated modular skids from Stuttgart and Munich compress customer deployment timelines to 12 weeks. |
| Precision Robotics Backward Integration | In-house sensor production insulates margin structures from concentrated Japanese component supplier pricing. |
| India CDMO Channel Partnership | Hyderabad and Bengaluru facility retrofits under CDSCO export compliance open high-growth service attach opportunities. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured interviews with fill-finish engineering directors, regulatory affairs leads at biopharma firms, CDMO procurement managers, and isolator validation specialists. FDA sterile drug inspection databases, EMA manufacturing authorization registers, ISO 14644 certification listings, and German mechanical engineering association shipment statistics supplied quantitative foundations. Bottom-up equipment installation tracking and top-down biopharma capital expenditure analysis enabled triangulation across data sources.
Granularity-level modeling operated at product type, technology, end user, and application dimensions across the analysis window, with additional disaggregation by regional regulatory cluster and facility scale tier. CAGRs derived from weighted average of historical shipment trajectories and forward-looking capital budget surveys. Forecast inputs incorporated EMA Annex 1 implementation timelines, cell therapy manufacturing capacity buildout announcements, and stainless steel price index projections.
Several conditions sit outside the modeled scope, including pandemic-driven demand discontinuities, trade policy shocks affecting precision component flows, and breakthrough sterilization technologies displacing barrier isolation architectures. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and biopharma merger activity levels. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Automatic Liquid Dispenser Machine Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Commercial Mixer Market