
 Air Hoist Market | 2026-2036
Air Hoist Market Size, Share, and Industry Trends Forecast 2026-2036
Air Hoist Market Analytics
China's eastern manufacturing corridor is fragmenting as domestic suppliers expand pneumatic hoist capacity to serve local shipbuilders and steel processors. J.D. Neuhaus leverages its explosion-proof engineering heritage to dominate offshore oil and gas applications. Konecranes anchors its position through integrated crane-hoist systems for automated ports. Ingersoll Rand sustains brand loyalty in North American heavy manufacturing through its Red Seal certified service network.
An air hoist is a pneumatically powered lifting device that converts compressed air into mechanical force through a vane motor or piston drive, typically achieving lifting capacities from 125 kg to over 100 tonnes with variable speed control via pendant or remote operation. Chain hoists occupy the largest installed base due to their durability in dirty, high-cycle environments, while wire rope hoists capture premium applications requiring longer lift heights and precise load positioning. Heavy-duty capacity units generate the strongest margin pools, as foundries and forging operations demand reinforced frames, heat-resistant components, and extended duty cycles that command pricing premiums over standard construction models.
FAA regulations govern air hoist use in aircraft maintenance hangars, while OSHA 1910.179 standards mandate periodic inspection and load testing for overhead hoists in general industry. The EU Machinery Directive 2006/42/EC requires CE marking, risk assessment documentation, and conformity with harmonized EN standards for hoists sold in member states. Stakeholders must monitor evolving carbon border adjustment mechanisms that could penalize imports from regions with less stringent foundry emissions controls, reshaping supplier geography decisions.
Market Dynamics
Pneumatic lifting equipment faces intensifying certification requirements as OSHA workplace safety mandates and the EU Machinery Directive tighten inspection protocols for overhead hoists in heavy manufacturing environments.
Growth Catalysts
- OSHA 1910.179 Standards:Periodic inspection mandates for overhead hoists in US general industry are accelerating fleet replacement cycles among automotive and aerospace maintenance facilities.
- Explosion-Proof Engineering:Offshore oil and gas platforms require certified pneumatic hoists for hazardous zone operations, driving specification upgrades in North Sea and Gulf of Mexico installations.
- China's Coastal Industrial Zones:Shipyards in Dalian and Ningbo and steel mills in Tangshan are procuring heavy-capacity units for bulk material handling operations.
Market Restraints
- Compressed Air Infrastructure:Foundries and forging operations in developing manufacturing economies lack reliable plant air systems, limiting pneumatic hoist deployment despite operational advantages over electric alternatives.
- Component Supply Concentration:Precision vane motors and heat-resistant sealing compounds concentrate among specialized European and Japanese suppliers, creating vulnerability to logistics disruptions.
- Electric Hoist Substitution:Variable-frequency drive electric hoists are capturing applications requiring precise load positioning, compressing pneumatic share in assembly-line environments.
Strategic Opportunities
- Carbon Border Adjustment Mechanisms:Evolving EU trade instruments will penalize imports from regions with weak foundry emissions controls, creating first-mover advantage for European-certified hoist manufacturers.
- Automated Port Integration:Crane-hoist system convergence enables bundled procurement contracts with terminal operators seeking unified maintenance protocols.
- Remote Monitoring Convergence:IoT sensor integration with pneumatic control systems allows predictive maintenance offerings that differentiate service revenue from equipment sales.
Industry Challenges
- Red Seal Certification Pipeline:North American heavy manufacturing faces acute shortages of technicians qualified to service high-cycle pneumatic lifting equipment, extending downtime windows.
- CE Marking Documentation:EU Machinery Directive conformity assessment requires extensive risk analysis files that delay market entry for new product variants by six to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Hoist Market |
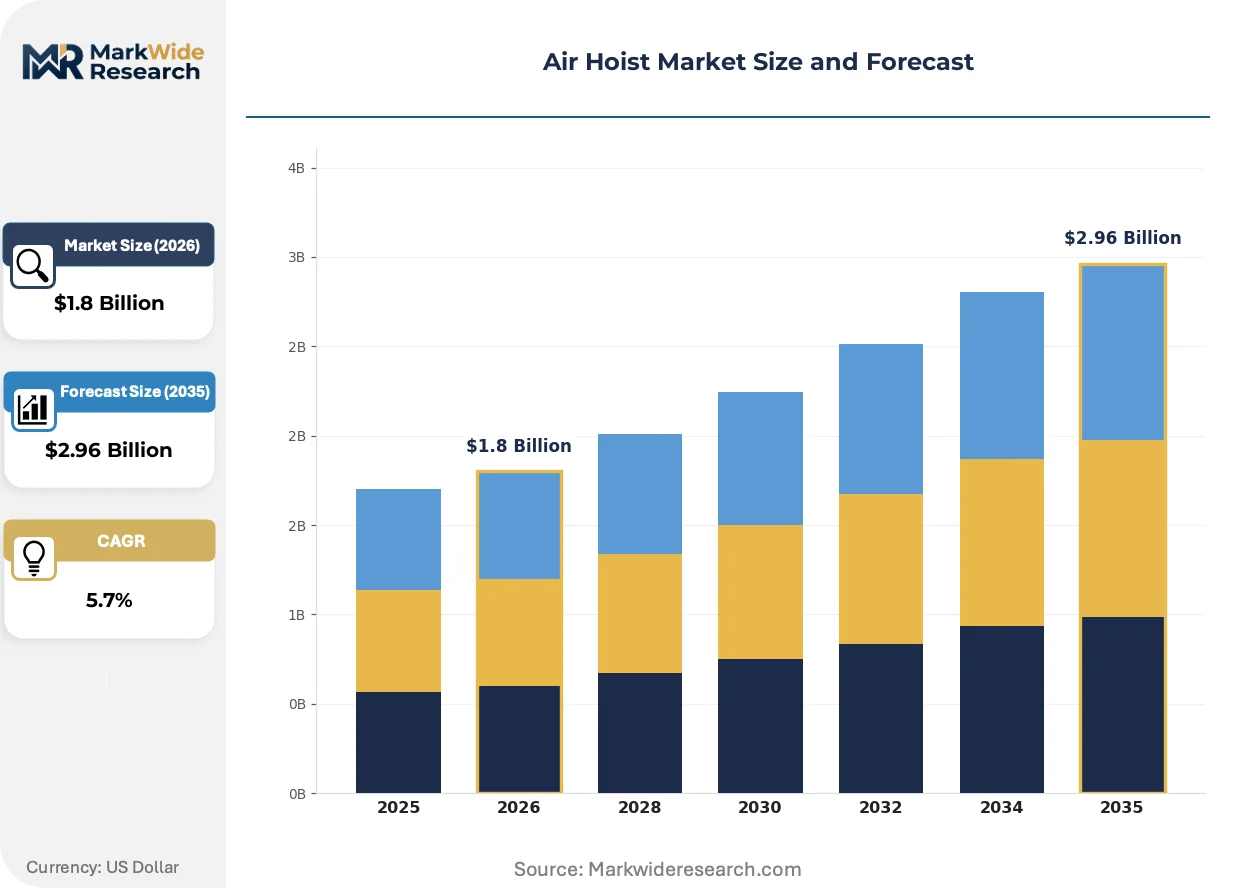
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chain Hoists, Wire Rope Hoists, Mini Hoists, Specialized Hoists Application: Construction, Manufacturing, Warehousing, Marine End User: OEMs, Contractors, Logistics Providers, Maintenance Services Capacity: Light Duty, Medium Duty, Heavy Duty, Extra Heavy Duty |
| Companies Covered | J.D. Neuhaus, Konecranes, Ingersoll Rand, Demag, Red Rooster Lifting, KITO Corporation, Harrington Hoists, Yale Hoists, Columbus McKinnon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Hoist Market Evolving Landscape
Compressed air control systems are converging with digital monitoring platforms, reshaping how heavy-lifting equipment is specified, maintained, and monetized across industrial verticals.
Vane motor technology is migrating from fixed-speed pneumatic drives to variable-displacement designs with electronic position feedback. Automotive stamping plants in Germany and powertrain facilities in the US Midwest are piloting these systems for precise die-handling operations. The technology is migrating from niche aerospace applications toward mainstream heavy manufacturing, compressing the performance gap between pneumatic and servo-electric alternatives.
The EU Machinery Directive 2006/42/EC is tightening conformity assessment requirements for hoists sold in member states, mandating updated risk documentation and harmonized EN standard compliance. Industrial consequence includes elevated certification costs that favor established suppliers with dedicated compliance teams. Offshore oil and gas operators in the North Sea are responding by consolidating procurement around explosion-proof specialists with pre-validated CE marking packages.
Maintenance contract unbundling is accelerating as fleet operators separate equipment ownership from service provision. Heavy manufacturing buyers in China's eastern corridor are shifting from bundled capex-service agreements toward third-party maintenance specialists. This pattern is most visible among steel processors in Jiangsu province, where independent service networks now capture overhaul work previously retained by original equipment channels.
Air Hoist Market Segmentation
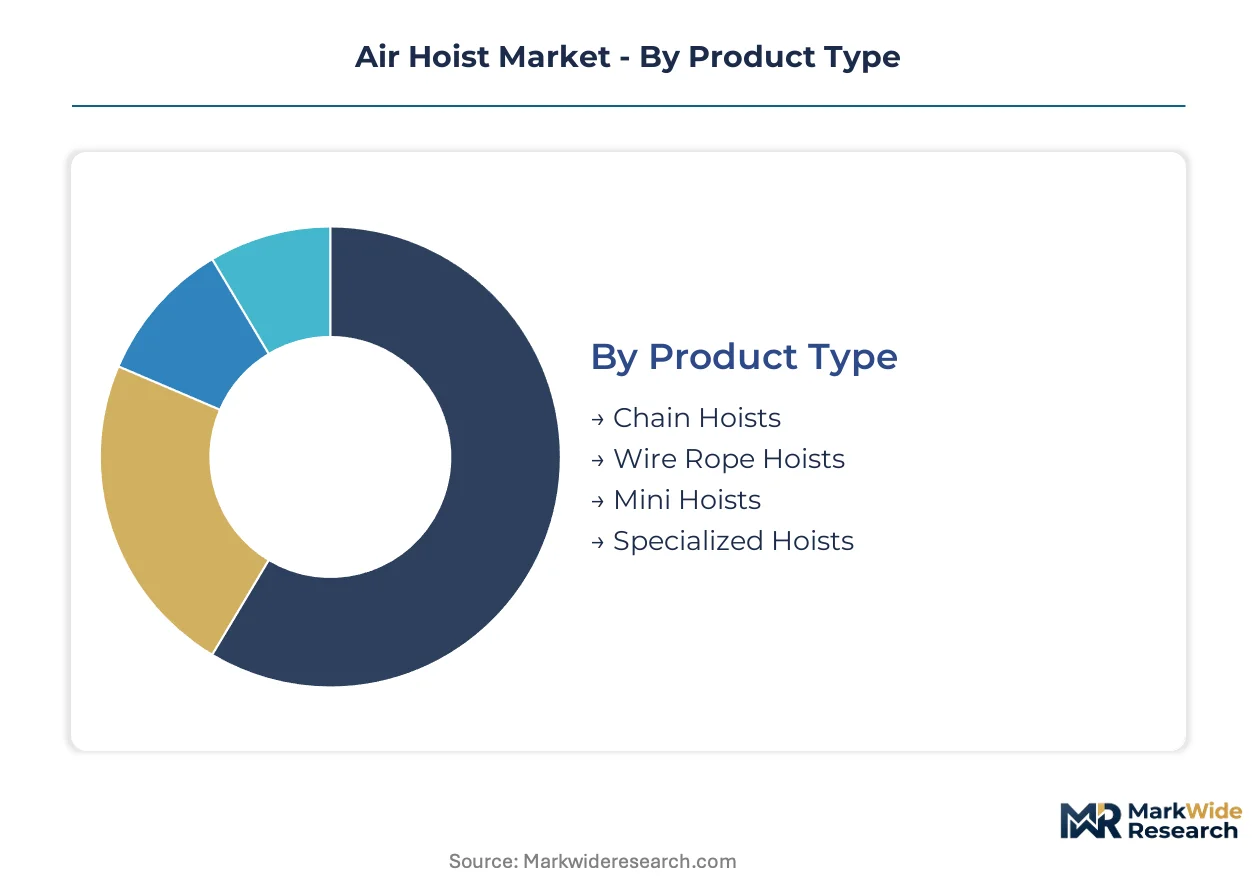
Air hoist procurement patterns diverge sharply across operational environments, with duty cycles, contamination exposure, and load precision requirements dictating technology selection. Manufacturers structure product portfolios around these friction points to capture margin pools in high-stakes verticals.
Product Type:
Equipment selection traces a spectrum from dirty, high-cycle foundry floors to clean-room aerospace hangars where contamination control dominates specifications.
- Chain Hoists:These units deploy hardened steel link chains through a pocket wheel mechanism, achieving durability in abrasive environments where particulate contamination destroys wire rope integrity. Demand concentrates in German automotive stamping plants and Chinese steel mills, where 24/7 duty cycles and metal dust exposure favor chain construction over alternatives. Heat-treated alloy chains resist elongation under shock loading from forging drop hammers.
- Wire Rope Hoists:Multiple-strand wire ropes wound on grooved drums enable longer lift heights and precise load positioning through variable-speed control. Offshore oil platforms in the North Sea specify these for subsea equipment deployment where 50-meter lift paths are standard. The drum geometry allows finer positioning resolution than chain pocket wheels.
- Mini Hoists:Compact pneumatic units under 500 kg capacity serve maintenance bays and assembly stations with limited headroom.
- Specialized Hoists:Explosion-proof variants with sealed vane motors and spark-resistant coatings target chemical processing and paint booth applications.
Established volume favors chain hoists; emerging adoption favors wire rope configurations in precision-dependent environments.
Application:
Site conditions determine specification intensity, with outdoor exposure and corrosive atmospheres demanding upgraded sealing and coating systems.
- Construction:Temporary installation patterns and weather exposure drive demand for portable, rapid-deployment units with galvanized finishes. Infrastructure projects in China's coastal provinces procure heavy-capacity pneumatic hoists for precast concrete segment handling, where dust and humidity accelerate corrosion.
- Manufacturing:Fixed production lines with compressed air infrastructure favor permanent-mount hoists integrated into overhead crane systems. German powertrain facilities specify variable-speed units with electronic feedback for die-changing operations, compressing changeover windows.
- Warehousing:Moderate-duty cycle requirements and standardized lift paths favor cost-optimized configurations with pendant control.
- Marine:Salt spray corrosion and dynamic vessel motion demand stainless steel construction and anti-sway load stabilization.
Manufacturing claims the deepest installed base; marine applications command the steepest specification premiums.
End User:
Procurement authority sits differently across organizational types, with capital ownership patterns shaping service contract structures.
- OEMs:Original equipment manufacturers integrate hoists into production machinery and material handling systems sold to downstream operators. These buyers demand design documentation packages for EU Machinery Directive conformity, extending supplier engineering obligations.
- Contractors:Project-based construction firms prioritize rental availability and rapid field service response over capital efficiency. Fleet utilization rates fluctuate with infrastructure spending cycles.
- Logistics Providers:Third-party warehouse operators standardize on interoperable control systems across multi-site networks.
- Maintenance Services:Independent repair specialists now capture overhaul work previously retained by equipment channels, particularly in China's Jiangsu province steel corridor.
OEMs anchor specification standards; maintenance services are capturing the fastest-expanding revenue pool in aftermarket provision.
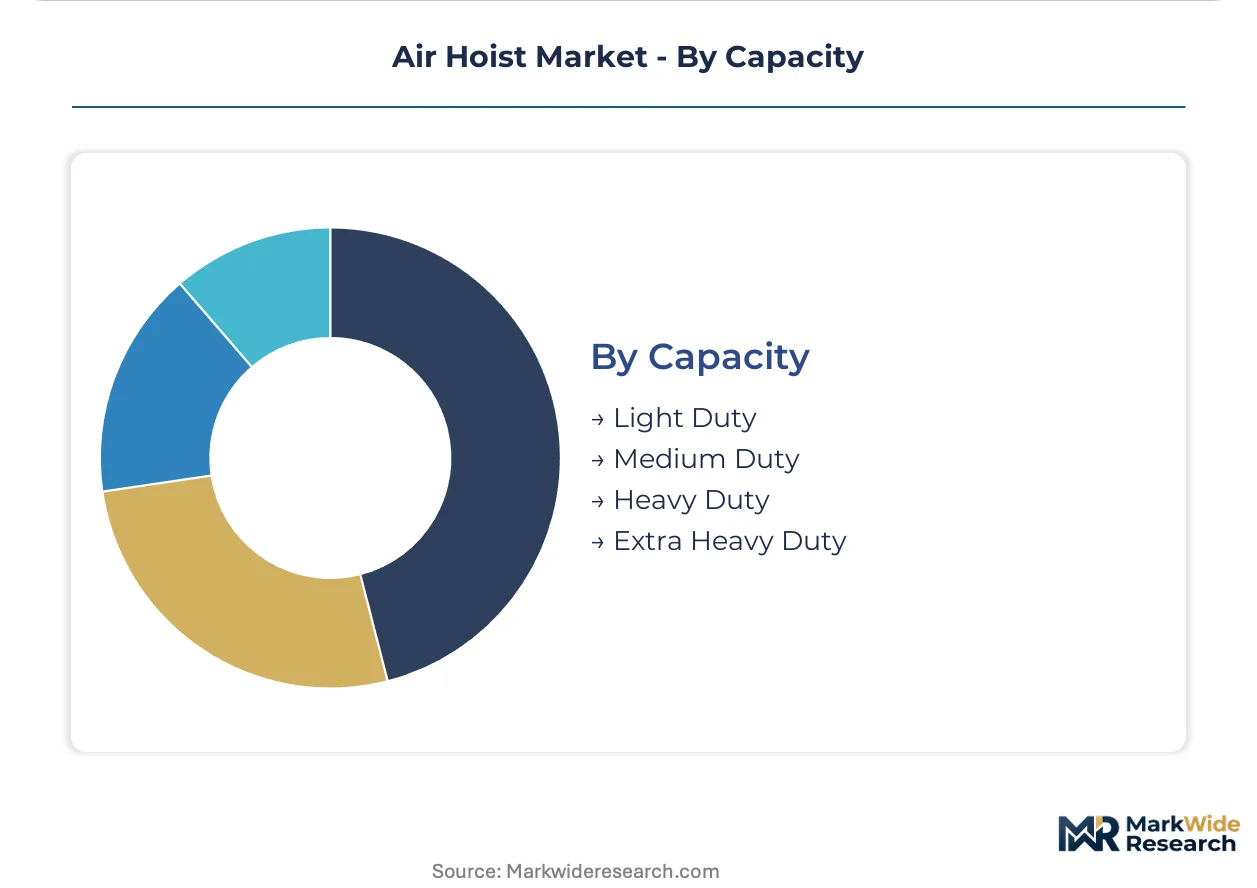
Capacity:
Frame reinforcement and component grading separate price tiers, with heat resistance and extended duty ratings commanding substantial premiums.
- Heavy Duty:Reinforced frames, oversized brakes, and thermally upgraded vane motors withstand continuous operation in foundries and forging plants. These units generate the strongest margin pools as operators prioritize uptime over capital cost. Tangshan steel processors specify this tier for ladle handling where failure consequences are catastrophic.
- Extra Heavy Duty:Custom-engineered systems exceeding 50 tonnes capacity serve specialized applications including shipyard block assembly and offshore platform module installation. Dalian shipbuilders procure these for hull section mating operations.
- Light Duty:Standard construction for intermittent use in maintenance and assembly environments.
- Medium Duty:Upgraded components for moderate-cycle manufacturing without continuous operation demands.
Heavy duty dominates revenue concentration; extra heavy duty represents the steepest expansion trajectory in capital-intensive industrial verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision vane motor and heat-resistant sealing supply concentrates among specialized European and Japanese component fabricators. This concentration shapes final assembly location decisions for hoist manufacturers serving regulated industrial markets. Demand patterns diverge sharply between established automotive corridors and emerging shipbuilding clusters.
United States
OSHA 1910.179 inspection mandates accelerate fleet replacement cycles across automotive stamping plants and aerospace maintenance hangars. FAA regulations govern pneumatic lifting equipment in aircraft hangar environments, requiring redundant braking systems and load verification protocols. Detroit-area powertrain facilities and Gulf Coast offshore service bases drive specification intensity for explosion-proof configurations.
Germany
Heavy-duty manufacturing facilities expand pneumatic lifting fleets to meet automotive production line throughput demands. EU Machinery Directive 2006/42/EC conformity assessment requires extensive risk documentation files, elevating certification costs that favor established suppliers. Baden-Württemberg stamping plants and Bavarian foundry clusters specify variable-speed units with electronic feedback for die-handling precision.
China
Coastal industrial zones in Dalian, Ningbo, and Tangshan drive bulk procurement of heavy-capacity units for shipyard and steel mill operations. GB standards and MIIT industrial equipment regulations establish conformity frameworks for overhead lifting equipment sold domestically. Jiangsu province steel processors are shifting from bundled capex-service agreements toward third-party maintenance specialists for overhaul work.
Japan
JIS standards and METI industrial safety guidelines establish rigorous certification requirements for pneumatic lifting equipment in manufacturing environments. Precision component fabricators concentrate in Nagoya-area industrial corridors, supplying vane motors and heat-resistant sealing compounds to global hoist assemblers. Automotive tier-one suppliers in Toyota City and Yokohama specify high-cycle units for just-in-time production line integration.
United Kingdom
North Sea offshore oil and gas platforms require certified pneumatic hoists for hazardous zone operations, consolidating procurement around explosion-proof specialists. HSE workplace safety regulations mandate periodic inspection and load testing protocols for overhead lifting equipment. Aberdeen-based offshore service contractors and Teesside chemical processing clusters drive specification premiums for spark-resistant coatings and sealed motor construction.
Air Hoist Market Competitive Landscape
Integrated crane-hoist system providers and specialized pneumatic lifting fabricators split the market along application complexity lines. Consolidation pressure favors suppliers with pre-validated CE marking packages and dedicated compliance engineering teams. Two archetypes dominate: diversified industrial conglomerates with unified maintenance protocol offerings, and niche explosion-proof engineering specialists with hazardous zone certification heritage. Competitive moves center on strategic partnerships for automated port integration and predictive maintenance service unbundling.
Among German-based industrial equipment conglomerates, J.D. Neuhaus and Demag occupy positions exemplifying the explosion-proof engineering archetype, with heritage certification packages for offshore oil and gas applications. Konecranes anchors the integrated system provider tier, representing bundled procurement convergence with terminal operators. Ingersoll Rand sits within the North American service-network archetype, with Red Seal certified infrastructure sustaining brand loyalty in heavy manufacturing verticals.
| Leading Market Players |
|---|
| J.D. Neuhaus |
| Konecranes |
| Ingersoll Rand |
| Demag |
| Red Rooster Lifting |
| KITO Corporation |
| Harrington Hoists |
| Yale Hoists |
| Columbus McKinnon |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese coastal foundries is compressing margin pools for standard-construction pneumatic hoists while reinforcing pricing power for European-certified heavy-duty units. This utilization divergence shapes supplier behavior toward tiered certification investments and selective geographic withdrawal.
Pricing Analysis
EU Machinery Directive 2006/42/EC dictates the pricing tier structure through CE marking documentation burdens that favor established suppliers with dedicated compliance teams. Three-tier pricing structure across premium, standard, and economy levels separates explosion-proof certified units for North Sea offshore platforms from general-industry configurations and basic maintenance-bay models. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in economy-tier chain hoists is intensifying because domestic Chinese suppliers are expanding pneumatic capacity for local shipbuilders. Contractors in developing manufacturing economies exhibit the highest price sensitivity; offshore oil and gas operators show the least due to catastrophic-failure cost calculus.
Supply Chain Analysis
Extended payment terms from Japanese and German precision-component fabricators are tightening working capital requirements for final assemblers. Geographic supply concentrates in Germany for heat-resistant sealing compounds, Japan for vane motors, and China for standard chain and frame fabrication. Raw material dependencies draw from specialty alloy steels, fluorocarbon elastomers, and precision-machined aluminum castings. Single-source vulnerability in explosion-proof motor sealing creates procurement risk for hazardous-zone certification maintenance. Distribution runs through OEM-integrated crane-hoist system providers and independent aftermarket service networks capturing overhaul work in China's Jiangsu province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified Red Seal technicians for high-cycle pneumatic maintenance are scarcer than manufacturing capacity, creating a capability bottleneck that reshapes competitive advantage around service-network depth rather than unit production scale.
For Market Incumbents: Insulate margin pools by deepening backward integration into precision vane motor production and capturing third-party maintenance contracts in China's eastern steel corridor. Electric hoist substitution with variable-frequency drive technology threatens pneumatic share in assembly-line environments; counter through predictive maintenance service bundling with IoT sensor integration. Certification investment in pre-validated CE marking packages accelerates market entry for product variants against six-to-eighteen-month documentation delays. For New Entrants and Emerging Players: India's heavy manufacturing infrastructure gap presents the most penetrable white-space target, as foundries and forging operations lack reliable compressed air systems despite operational advantages over electric alternatives. Target automated port integration partnerships in Southeast Asian terminal expansion projects where bundled crane-hoist procurement favors unified maintenance protocols. A go-to-market angle through supply-chain finance facilities for extended component payment terms addresses working capital constraints that burden established European and Japanese fabricators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among explosion-proof engineering specialists with hazardous-zone certification heritage and pre-validated regulatory packages. Long-term viability favors suppliers with integrated service networks capable of predictive maintenance monetization separate from equipment sales. The acquisition target archetype combines CE marking compliance infrastructure with IoT-enabled remote monitoring capabilities. Watch for carbon border adjustment mechanism implementation signals as an inflection indicator that would penalize imports from regions with weak foundry emissions controls.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Validation | Reduces EU market entry delays from eighteen months to standard product cycles. |
| IoT Sensor Integration | Enables predictive maintenance revenue separation from equipment sales for service networks. |
| Backward Integration into Vane Motors | Secures supply of precision components concentrated among Japanese and German fabricators. |
| Automated Port System Partnerships | Captures bundled procurement contracts with terminal operators seeking unified protocols. |
| Explosion-Proof Certification Expansion | Consolidates procurement around specialists for North Sea and Gulf of Mexico hazardous zones. |
Research Methodology
Cross-validation between maintenance director interviews at German automotive stamping plants and customs data from Chinese pneumatic equipment imports anchors the qualitative findings. Primary fieldwork engaged plant engineers at Tangshan steel processors, aftermarket service heads in Jiangsu province, OEM procurement teams at offshore platform fabricators, and crane-hoist integration specialists at automated port terminals. Secondary validation drew from EU Machinery Directive conformity assessment filings, OSHA inspection violation databases, MIIT industrial equipment registration records, and SEC 10-K disclosures from listed industrial conglomerates. Bottom-up unit demand estimates triangulated against top-down capital expenditure patterns across heavy manufacturing verticals.
Calibration against historical replacement cycle data and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application environment, end-user procurement authority, and capacity tier with duty-cycle grading. CAGRs were derived from installed base aging profiles and compliance-driven fleet refresh mandates. Industry-specific forecast inputs incorporated carbon border adjustment mechanism implementation timelines and compressed air infrastructure buildout rates in emerging manufacturing economies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated crane-hoist system providers or electric hoist manufacturers with servo-precision capabilities would shift outcomes. Macroeconomic deviation in industrial capital expenditure, regulatory acceleration in emissions border adjustments, or technological breakthrough in battery-powered lifting alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Vibrating Feed Conveyors Market