
 Japan Conveyor Belt Market | 2026-2036
Japan Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Conveyor Belt Market Intelligence
Modular conveyor system bundling is consolidating buyer preference as Japanese manufacturers seek flexible, reconfigurable production lines. Daifuku Co., Ltd. leverages its intralogistics expertise to anchor large-scale automotive installations. Bridgestone Corporation sustains dominance in heavy-duty rubber belt fabrication through captive polymer research. Murata Machinery, Ltd. competes on precision timing and clean-room compatibility for electronics handling.
A conveyor belt is a continuous moving surface of elastomeric, polymeric, or metallic construction, typically reinforced with textile or steel cord carcasses, engineered to transport bulk or unitized materials at speeds ranging from 0.5 to 10 meters per second across fixed paths. Its primary industrial purpose is to reduce manual handling labor, synchronize production tempo, and enable just-in-time material flow in repetitive manufacturing environments. Flat belts occupy the largest installed base due to versatility across light-to-medium load applications, while modular belts represent the fastest-expanding configuration because their linkable plastic segments simplify sanitation protocols in food processing plants. Rubber material formulations retain margin concentration in mining and heavy industrial segments, though polyurethane compounds gain traction where abrasion resistance and chemical inertness command specification premiums.
METI's Smart Factory initiative, JIS B 8803 conveyor safety standards, and PMDA food-contact material regulations collectively shape equipment specification and supplier qualification pathways in Japan. These frameworks mandate traceable component sourcing, emergency stop integration, and hygienic surface finishes that elevate compliance costs for imported alternatives. Stakeholders must monitor evolving prefectural energy-efficiency codes and workforce density regulations that could accelerate pneumatic-to-electric technology transitions in densely populated manufacturing zones.
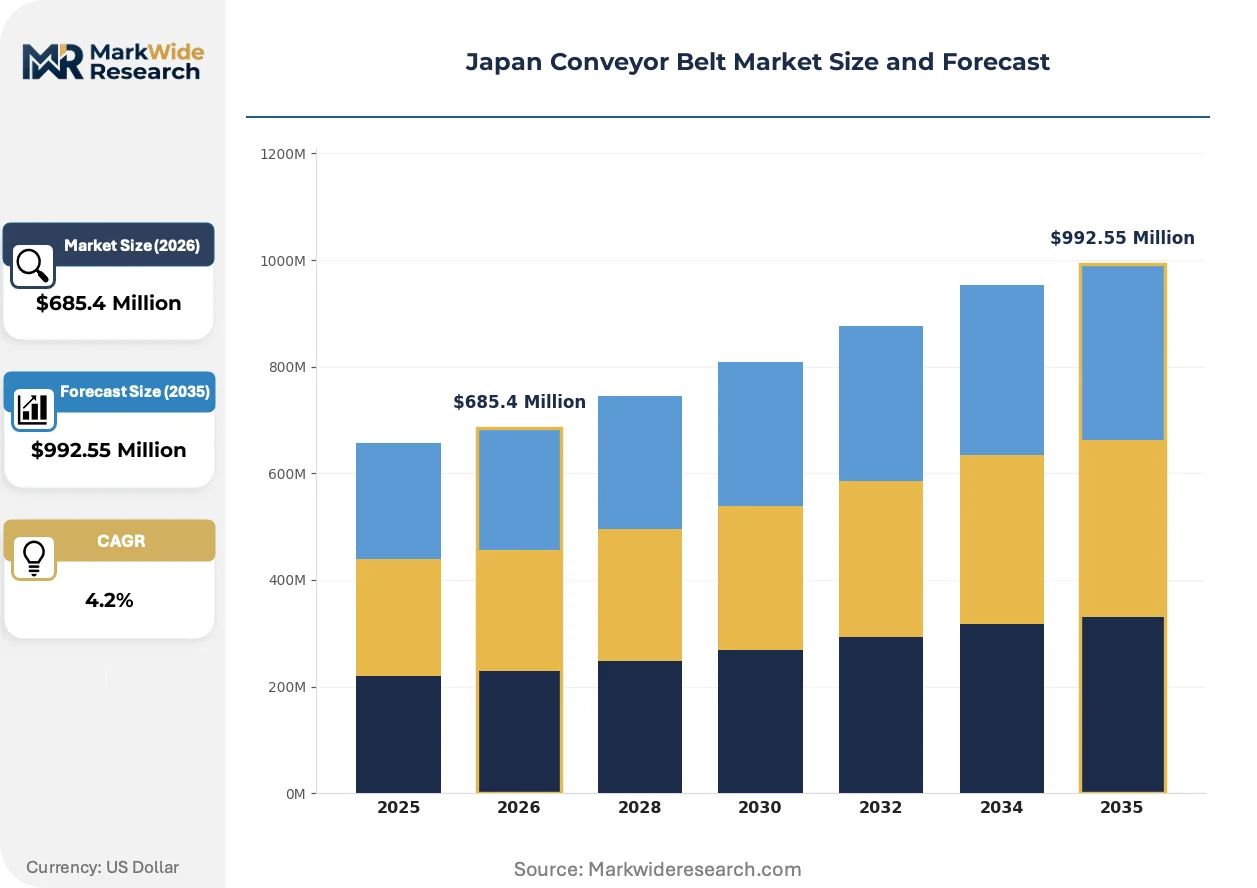
Market Dynamics
Modular conveyor architectures are compressing replacement cycles across Japanese food processing plants as facilities prioritize washdown compatibility over fixed rubber installations. METI's Smart Factory subsidies accelerate this hardware refresh, concentrating procurement authority among tier-one automotive and electronics OEMs.
Growth Catalysts
- Smart Factory Subsidies:METI's automation incentives defray capital outlays for conveyor system upgrades in precision manufacturing corridors.
- Food Safety Mandates:PMDA contact-material regulations drive stainless steel and modular plastic belt conversions in dairy and ready-meal processing.
- Kanto Industrial Density:Tokyo-Kanagawa-Saitama manufacturing clusters generate concentrated demand for synchronized material handling infrastructure.
Market Restraints
- Steel Cord Supply Concentration:Heavy-duty belt fabricators face input cost volatility from consolidated Asian steel cord suppliers.
- Import Certification Friction:JIS B 8803 safety compliance timelines delay European and Korean equipment market entry by 8-14 months.
- Pneumatic System Entrenchment:Legacy compressed-air conveying in bulk powder handling resists electric motor retrofit economics.
Strategic Opportunities
- Pharmaceutical Clean-Room Expansion:Osaka-Tokyo biologics manufacturing corridors require ISO 14644-compliant conveyor modules with minimal particle generation.
- Secondary Battery Materials Handling:Cathode and anode powder conveying demands explosion-proof electric drive systems in Nagoya industrial zones.
- Prefectural Energy Codes:Tokyo and Kanagawa efficiency mandates create regulatory tailwinds for regenerative-drive conveyor retrofits.
Industry Challenges
- Mechatronics Skill Scarcity:Conveyor system integrators compete for PLC programming and servo tuning talent against robotics and semiconductor sectors.
- Legacy Architecture Integration:Brownfield automotive plants require custom mechanical adapters to marry modular belt segments with 1980s-era frame structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Conveyor Belt Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Belts, Modular Belts, Bucket Elevators, Roller Bed Belts End User: Manufacturing, Food Processing, Packaging, Automotive Material: Rubber, PVC, Polyurethane, Metal Technology: Electric, Pneumatic, Hybrid, Gravity |
| Companies Covered | Daifuku Co., Ltd., Murata Machinery, Ltd., Toyota Industries Corporation, Hitachi, Ltd., Mitsubishi Electric Corporation, Yaskawa Electric Corporation, Taikisha Ltd., Bridgestone Corporation, Yokohama Rubber Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Conveyor Belt Market Strategic Shifts & Innovations
Digital thread integration and predictive maintenance architectures are redefining conveyor lifecycle economics. Japanese end-users now specify sensor-embedded belts as standard, shifting supplier competition toward data-service bundling rather than pure hardware durability.
Polyurethane-coated steel cord belts are unifying abrasion resistance with chemical inertness for semiconductor wafer transport applications. Electronics OEMs in Kumamoto and Hiroshima prefectures specify these compounds for clean-room compatibility. This material convergence is unifying previously separate premium and standard product tiers into single specification platforms.
JIS B 8803 emergency-stop and guarding mandates are tightening compliance verification for imported modular systems. Third-party certification bodies in Yokohama and Osaka now require documented traceability for all polymer contact surfaces. Food processing facilities in the Chubu region are responding by qualifying domestic fabricators with established testing laboratory relationships.
Buyer consolidation among tier-one automotive assemblers is compressing supplier negotiation cycles from annual frameworks to quarterly price-volume reviews. Tier-two component manufacturers now face accelerated switching decisions as parent OEMs mandate synchronized conveyor refresh schedules. This concentration is most visible in Aichi prefecture's Toyota supply basin, where single-source agreements dominate intralogistics procurement.
Japan Conveyor Belt Market Segmentation
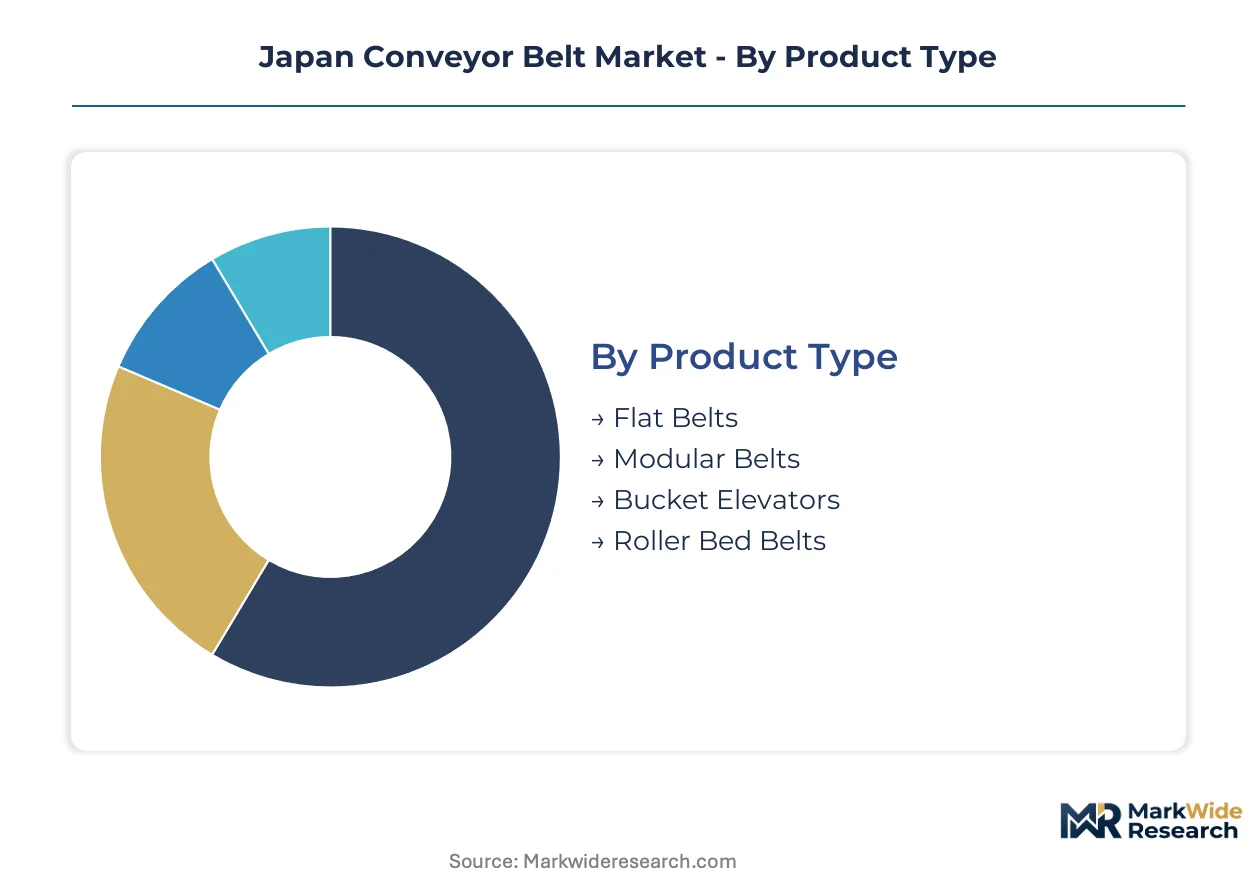
Conveyor belt specification in Japan diverges sharply across production environments. Food safety mandates, clean-room protocols, and automotive precision requirements each demand distinct material and architectural configurations.
Product Type:
Replacement cycles vary dramatically by belt architecture, with washdown compatibility now dictating food plant upgrade priorities.
- Flat Belts:Elastomeric or polymeric continuous surfaces reinforced with textile carcasses dominate light-to-medium load handling. Automotive assembly lines in Aichi prefecture specify these for synchronized component delivery under METI Smart Factory timelines.
- Modular Belts:Interlocking plastic segments enable rapid reconfiguration and simplified sanitation. Dairy and ready-meal processors across Chubu and Kanto regions prioritize these for PMDA compliance, compressing replacement cycles from ten-year rubber installations to five-year plastic refresh schedules.
- Bucket Elevators:Vertical bulk material handling for grain and powder processing facilities.
- Roller Bed Belts:Reduced friction designs for heavy pallet loads in distribution centers.
Volume placements concentrate in Flat Belts; the faster expansion belongs to Modular Belts.
End User:
Customer procurement authority clusters around tier-one OEMs with synchronized refresh mandates.
- Manufacturing:Electronics and precision machinery producers in Kumamoto and Hiroshima specify clean-room compatible systems. Semiconductor wafer transport demands polyurethane-coated configurations with minimal particle generation.
- Food Processing:PMDA contact-material regulations drive stainless steel and modular plastic conversions. Dairy processors face accelerated compliance deadlines compared to legacy rubber installations.
- Packaging:Secondary battery material handling for cathode and anode powders requires explosion-proof electric drives in Nagoya industrial zones.
- Automotive:Toyota supply basin concentration in Aichi prefecture generates single-source intralogistics agreements with quarterly price-volume reviews.
Procurement volume tilts toward Manufacturing; Food Processing climbs fastest on regulatory compulsion.
Material:
Material selection tracks abrasion resistance needs against chemical inertness requirements.
- Rubber:Heavy-duty formulations with steel cord reinforcement retain dominance in mining and bulk industrial segments. Bridgestone's captive polymer research sustains margin concentration despite input cost volatility from Asian steel cord suppliers.
- Polyurethane:Abrasion-resistant compounds with chemical inertness command specification premiums in semiconductor applications. Electronics OEMs specify these for clean-room compatibility, unifying previously separate premium and standard tiers.
- PVC:Cost-effective general purpose belting for light industrial applications.
- Metal:Stainless steel configurations for extreme temperature and hygienic processing environments.
Rubber retains the largest installed base; Polyurethane gains share fastest on electronics specification.
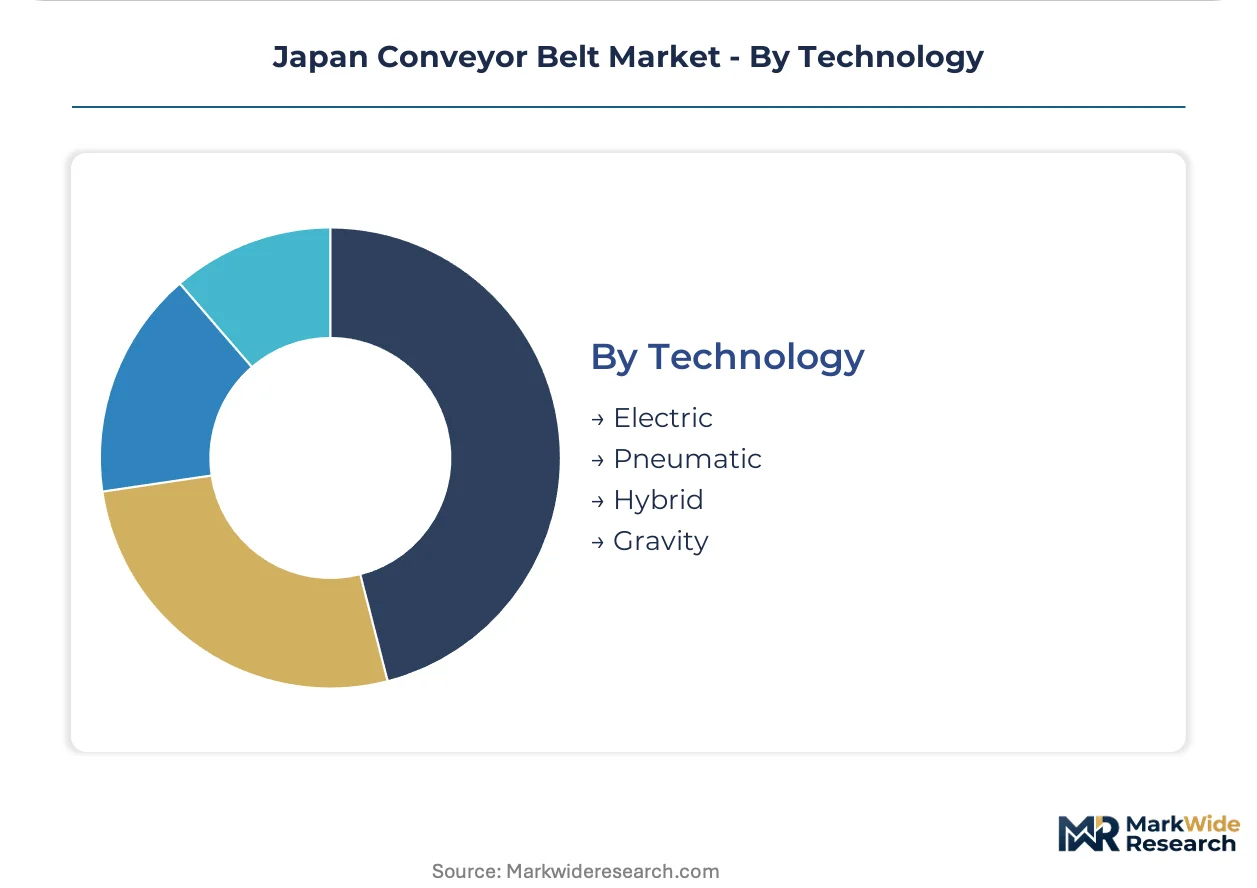
Technology:
Drive system selection reflects energy efficiency mandates and legacy infrastructure constraints.
- Electric:Servo-controlled and regenerative-drive systems align with Tokyo and Kanagawa prefectural energy codes. Predictive maintenance architectures with sensor-embedded belts now come standard in tier-one automotive specifications.
- Pneumatic:Compressed-air conveying persists in bulk powder handling where retrofit economics resist electric motor conversion. Legacy brownfield plants require custom mechanical adapters for modular belt integration.
- Hybrid:Combined electric-pneumatic configurations for flexible production lines.
- Gravity:Non-powered roller systems for cost-sensitive distribution applications.
Electric systems capture new installation preference; Hybrid architectures expand most quickly on flexibility demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's conveyor belt production concentrates in industrial corridors while consumption spreads across manufacturing zones. Domestic fabricators supply precision systems for electronics and automotive sectors. Import penetration remains limited by JIS certification timelines.
Kanto
Tokyo-Kanagawa-Saitama manufacturing clusters generate synchronized material handling demand from precision machinery producers. METI's Smart Factory subsidies accelerate capital deployment across this corridor. Automotive assembly plants in Kanagawa prefecture specify servo-controlled conveyor modules for just-in-time component delivery.
Kansai
Osaka-Kyoto biologics manufacturing corridors require ISO 14644-compliant conveyor systems with minimal particle generation. PMDA pharmaceutical regulations mandate traceable polymer contact surfaces for clean-room installations. Electronics OEMs in Osaka prefecture specify polyurethane-coated configurations for semiconductor wafer transport.
Chubu
Nagoya industrial zones drive demand for explosion-proof electric drive systems in secondary battery material handling. Toyota supply basin concentration generates single-source intralogistics agreements with quarterly procurement reviews. Aichi prefecture fabricators qualify domestic suppliers with established JIS B 8803 testing laboratory relationships.
Kyushu
Kumamoto and Hiroshima electronics producers specify clean-room compatible conveyor architectures for precision component assembly. Prefectural energy-efficiency codes accelerate pneumatic-to-electric technology transitions in densely populated manufacturing zones. Local system integrators compete for PLC programming talent against semiconductor sector employers.
Hokkaido
Food processing facilities in northern Japan prioritize modular plastic belt conversions for PMDA dairy compliance. Legacy rubber installations face accelerated replacement cycles compared to national averages. Regional fabricators leverage domestic polymer research for cold-climate belt formulations.
Japan Conveyor Belt Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Japan's conveyor belt landscape. Tier-one automotive and electronics OEMs concentrate procurement authority, compressing supplier negotiation cycles. Three strategic archetypes dominate: integrated material handling system providers, heavy-duty rubber belt fabricators, and precision timing specialists. Competitive moves center on modular architecture development and predictive maintenance service bundling.
Among Japan-based fabricators, Daifuku Co., Ltd., Murata Machinery, Ltd., and Bridgestone Corporation occupy distinct positioning tiers. Daifuku represents the integrated system provider archetype with intralogistics expertise anchoring large-scale installations. Murata Machinery exemplifies precision timing specialization for electronics handling applications. Bridgestone anchors the heavy-duty rubber segment through captive polymer research capabilities. Each sits within a defensible niche shaped by end-user certification requirements and JIS compliance pathways.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Murata Machinery, Ltd. |
| Toyota Industries Corporation |
| Hitachi, Ltd. |
| Mitsubishi Electric Corporation |
| Yaskawa Electric Corporation |
| Taikisha Ltd. |
| Bridgestone Corporation |
| Yokohama Rubber Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Asian steel cord price benchmarks cascade through Japanese conveyor belt supply chains, compressing margins for heavy-duty rubber fabricators while elevating specification premiums for polyurethane and modular plastic alternatives. Tier-one automotive OEMs exploit concentrated procurement authority to extract quarterly price-volume concessions from domestic suppliers.
Pricing Analysis
Margin tightening in standard rubber belting reflects volatile steel cord input costs and consolidated Asian metallurgical supply. Three-tier pricing structure across premium polyurethane, standard rubber, and economy PVC tiers separates certification-grade semiconductor transport systems from general industrial applications. Pricing pressure intensifies in modular plastic segments as food processors accelerate PMDA-driven refresh cycles. Tier-two component manufacturers exhibit highest price sensitivity; electronics OEMs with captive metrology specifications show least.
Supply Chain Analysis
JIS B 8803 certification gating restricts European and Korean equipment entry, privileging domestic fabricators with established Yokohama and Osaka laboratory relationships. Raw material sourcing draws from South Korean steel cord suppliers, German polymer research institutes, and domestic Japanese polymer compounding facilities. Single-source vulnerability concentrates in Asian steel cord metallurgy for heavy-duty mining applications. Distribution runs through tier-one automotive OEM procurement centers and electronics contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japanese conveyor belt markets operate under supply-constrained conditions where JIS certification bottlenecks prop pricing premiums for qualified domestic fabricators.
For Market Incumbents: Extend predictive maintenance service bundling to capture recurring revenue streams beyond hardware replacement cycles. Deepen backward integration into polymer compounding to defend margin position against Asian steel cord volatility. Prioritize ISO 14644 clean-room certification investment to anchor pharmaceutical biologics corridor demand in Osaka-Tokyo. For New Entrants and Emerging Players: Capture secondary battery materials handling white space in Nagoya industrial zones where explosion-proof electric drive demand outpaces established supplier capacity. Target Hokkaido dairy processing retrofit cycles where PMDA compliance deadlines compress procurement timelines for modular plastic systems. Pursue qualification partnerships with established JIS testing laboratories to bypass 8-14 month certification friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision timing specialists with clean-room compatibility credentials in Kumamoto-Hiroshima electronics clusters. Long-term viability hinges on sensor-embedded belt architectures and data-service revenue models. Watch METI Smart Factory subsidy renewal negotiations as inflection indicator for capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive polymer research insulates Bridgestone from Asian steel cord volatility. |
| Predictive Maintenance Service Bundling | Sensor-embedded belts shift competition from hardware durability to data analytics. |
| ISO 14644 Clean-Room Certification | Pharmaceutical biologics manufacturing in Osaka demands particle-minimal conveyor modules. |
| Explosion-Proof Electric Drive Development | Secondary battery cathode-anode handling in Nagoya requires certified hazardous environment systems. |
| JIS B 8803 Testing Laboratory Partnerships | Yokohama and Osaka certification relationships accelerate European competitor market entry timelines. |
Research Approach
Trade association filings, METI subsidy disbursement records, and JIS certification registries formed the secondary backbone for market sizing and competitive mapping. Primary interviews with plant engineers at tier-one automotive OEMs, procurement leads at electronics contract manufacturers, aftermarket service heads at distribution centers, and technical directors at domestic fabricators validated demand assumptions. Bottom-up installation base analysis and top-down industrial output correlation established volume triangulation.
Historical trendline analysis across belt architecture transitions, material substitution patterns, and drive technology migrations informed projection modeling. Segmentation dimensions span product architecture, end-use industry vertical, material compound specification, and drive system technology. CAGRs derive from regression against industrial production indices and automation penetration curves. Forecast inputs incorporate METI Smart Factory subsidy trajectories and prefectural energy-efficiency code evolution.
The model holds under stable JIS certification timelines and continued METI automation incentives; deviation in trade policy or subsidy cancellation would shift replacement cycle assumptions. Forecasts reflect documented assumptions regarding steel cord supply continuity and electronics capital expenditure momentum. A model refresh is warranted upon material change in semiconductor fabrication equipment spending or pharmaceutical clean-room construction permits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Truck Mounted Loader Cranes Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Compactor Market