
 Hybrid Excavator Market | 2026-2036
Hybrid Excavator Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Excavator Market Foresight
Tier-four-final emissions compliance is rotating demand toward diesel-electric hybrid architectures with regenerative braking and capacitor-assisted load cycles. Caterpillar leverages captive powertrain engineering to anchor North American rental channel penetration. Komatsu sustains technology leadership through integrated motor-generator systems that recover swing braking energy. Volvo Construction Equipment differentiates via connected fleet telemetry bundled with hybrid performance guarantees.
A hybrid excavator combines an internal combustion engine with an electric motor and energy storage subsystem to reduce fuel consumption during intermittent load cycles, typically achieving recuperation through boom-down gravity recovery and swing deceleration. The machine serves earthmoving, trenching, and material handling operations where duty cycles create substantial regenerative opportunity. Standard excavators dominate unit volume due to universal site applicability, while electric hybrid technology captures the fastest expansion as lithium-ion pack costs decline and on-site charging infrastructure spreads. Rental companies represent a concentrated margin pool because fleet utilization rates justify premium hybrid acquisition costs through fuel savings amortization.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine downsizing and after-treatment integration that hybrid architectures accommodate more cost-effectively than conventional diesel alone. Japan's METI sets domestic carbon intensity benchmarks that favor domestic manufacturers with localized hybrid supply chains. Stakeholders must monitor battery second-life valuation and remanufacturing economics as early hybrid fleets approach component replacement thresholds.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions frameworks are compressing conventional diesel excavator economics while elevating hybrid architectures that accommodate engine downsizing and after-treatment integration more cost-effectively. Equipment rental channels and urban infrastructure contractors face accelerated fleet replacement cycles as regulatory deadlines harden.
Growth Catalysts
- Regulatory Compression:Japan's METI carbon intensity benchmarks compel domestic contractors to accelerate electric hybrid adoption ahead of compliance deadlines.
- Energy Recovery Engineering:Integrated motor-generator systems that capture swing braking energy and boom-down gravity recuperation now deliver measurable fuel savings during intermittent load cycles.
- Site Electrification:Lithium-ion pack cost declines and spreading on-site charging infrastructure reduce operational friction for electric hybrid units in urban construction clusters.
Market Restraints
- Battery Input Volatility:Lithium and nickel price swings inflate powertrain costs and compress hybrid premium recovery timelines for fleet operators.
- Supply Concentration:Critical rare earth processing for high-efficiency motors concentrates in China's refining infrastructure, creating geopolitical exposure for non-domestic manufacturers.
- Technical Limitation:Energy density constraints in capacitor-assisted systems restrict continuous high-load operation without thermal derating.
Strategic Opportunities
- Second-Life Valuation:Early hybrid fleets approaching battery replacement thresholds create remanufacturing and component resale economics that extend asset lifecycles.
- Channel Innovation:Performance-guarantee leasing bundled with connected fleet telemetry enables rental companies to monetize fuel savings through outcome-based contracts.
- Regulatory Tailwind:China's dual carbon goals through MEE protocols tighten diesel hybrid certification standards, favoring suppliers with localized supply chains.
Industry Challenges
- Certification Timeline Compression:KBA construction equipment standards in Germany demand accelerated homologation cycles that strain engineering bandwidth.
- Skill Gap:Maintenance of integrated electric powertrains requires technician retraining on high-voltage systems and energy storage diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Excavator Market |
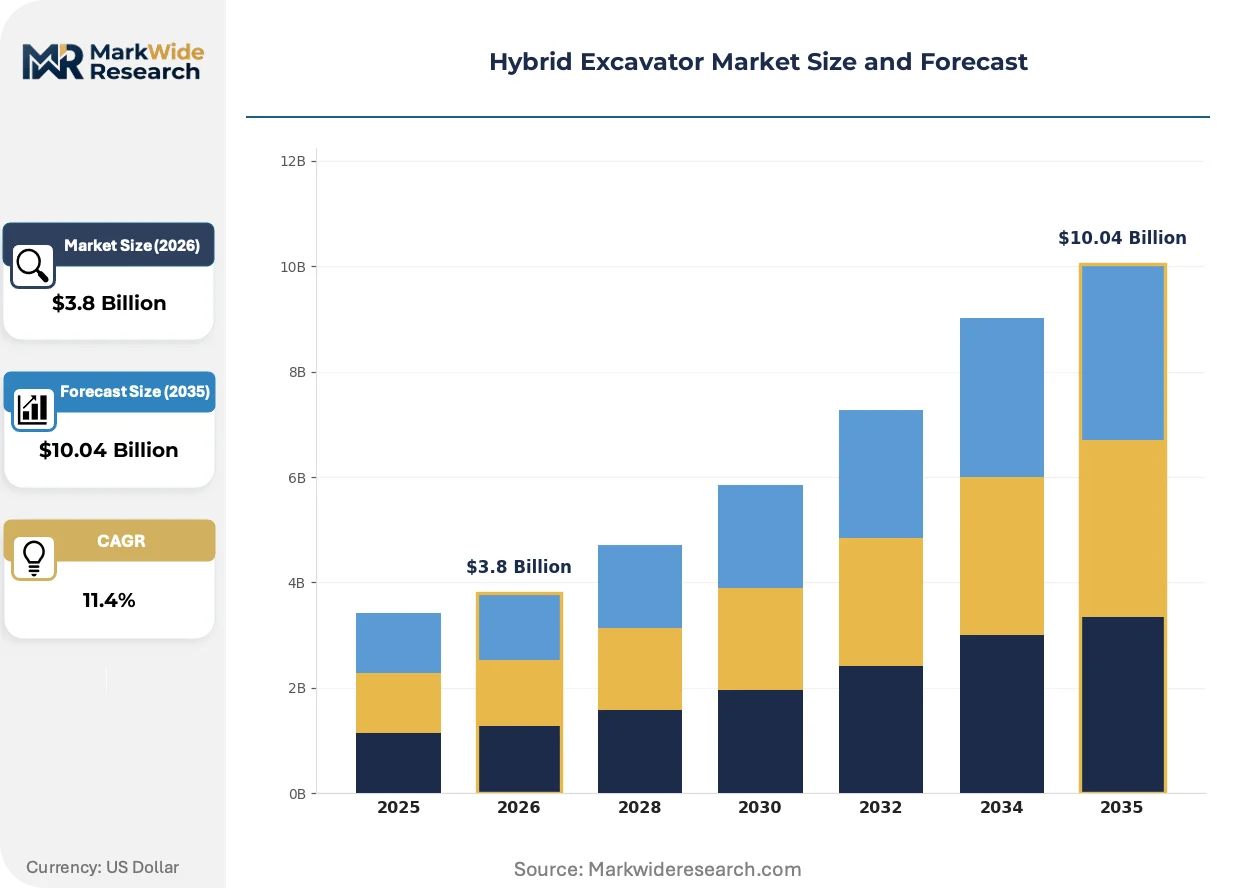
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Excavators, Midi Excavators, Standard Excavators, Large Excavators Technology: Hydraulic Hybrid, Electric Hybrid, Diesel Hybrid, Plug-in Hybrid Application: Construction, Mining, Demolition, Landscaping End User: Contractors, Rental Companies, Government, Utility Providers |
| Companies Covered | Hitachi Construction Machinery, Doosan Infracore, Caterpillar, Kobelco Construction Machinery, JCB, Volvo Construction Equipment, Liebherr Group, DEVELON, Komatsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Excavator Market Shifts & Advancements
Equipment intelligence and energy management architectures are reshaping how hybrid excavators compete on total cost of ownership rather than upfront acquisition price. Three interconnected developments are redefining competitive positioning.
Capacitor-assisted load cycle technology is fragmenting the performance tier structure in hybrid excavators. Urban infrastructure contractors in Japan are deploying these systems for high-frequency swing operations where rapid charge-discharge cycles outperform battery-only configurations. The technology is fragmenting vendor differentiation strategies between energy density-focused and power density-focused product lines.
EU Stage V emissions frameworks are mandating real-world emissions monitoring through portable measurement systems rather than laboratory certification alone. This industrial consequence elevates hybrid architectures that demonstrate consistent in-field performance across variable duty cycles. German rental fleets are responding by specifying telematics-enabled units that document compliance during municipal tender processes.
Rental channel consolidation is compressing equipment procurement decision cycles and elevating fuel-guarantee clauses in lease agreements. Traditional distributor networks face displacement by direct manufacturer fleet management contracts that bundle maintenance, telemetry, and energy optimization. This shift is most visible in North American metropolitan construction markets where national rental chains centralize hybrid acquisition decisions.
Hybrid Excavator Market Segmentation
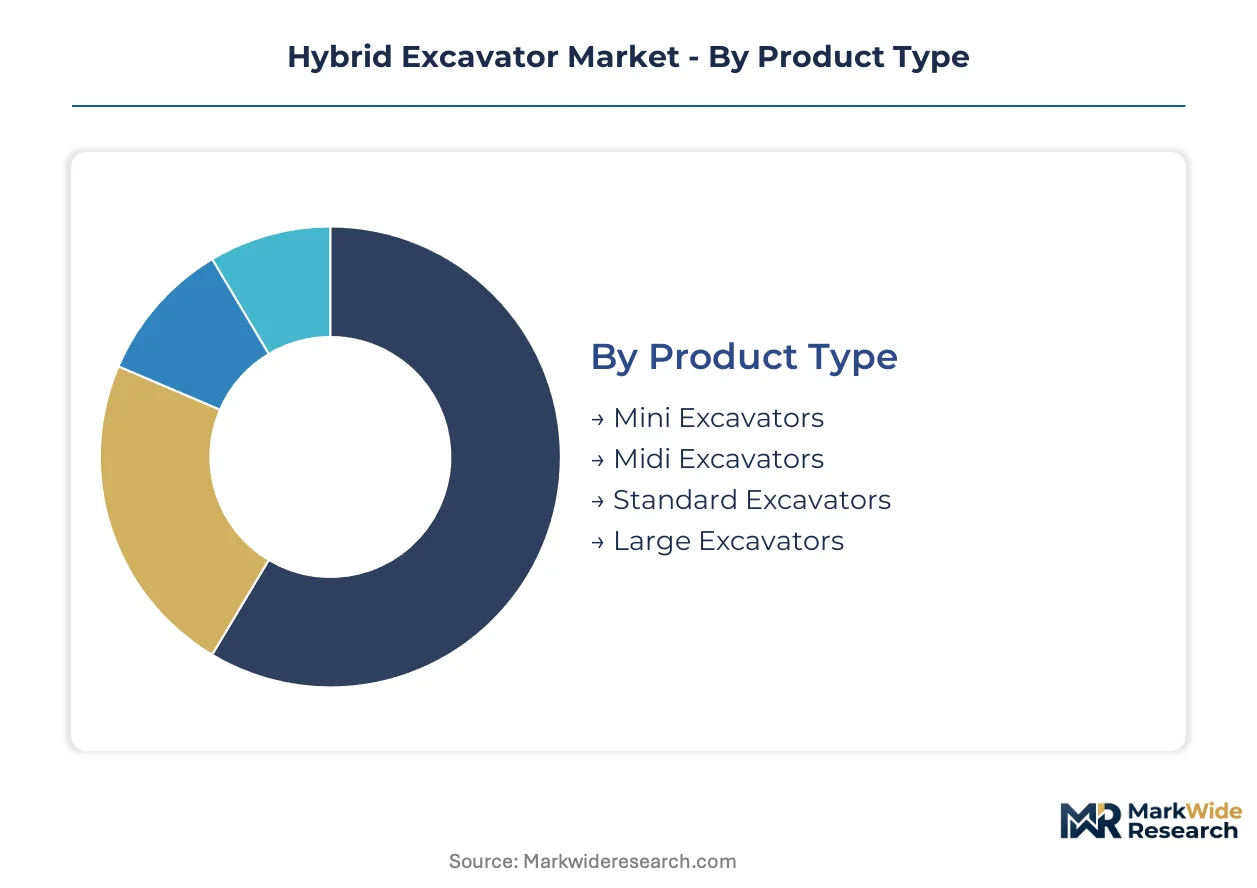
Hybrid excavator procurement patterns diverge sharply across product size classes and powertrain architectures. Fleet operators select configurations based on site electrification readiness, duty cycle intensity, and fuel cost exposure in specific operating environments.
Product Type:
Mini and midi units dominate domestic Japanese and German urban fleets, while standard and large configurations serve export-heavy mining and infrastructure corridors.
- Mini Excavators:Compact machines under 6 metric tons deploy electric hybrid powertrains for confined urban trenching and utility work. Municipal contractors in Tokyo and Osaka specify these for zero-emission zones where METI benchmarks apply.
- Midi Excavators:Mid-size units from 6 to 10 metric tons balance swing energy recovery with transportability. German rental fleets concentrated around Munich and Hamburg favor these for mixed residential-commercial sites where KBA emissions documentation is mandatory.
- Standard Excavators:The workhorse 10-20 metric ton class serves general construction with diesel-electric architectures.
- Large Excavators:Mining-focused units above 20 metric tons deploy hydraulic hybrid systems for continuous high-load duty cycles.
Standard excavators command the established base. The steepest expansion runs through mini excavators.
Technology:
Cost tiers separate premium electric hybrids from mid-market diesel hybrids and entry hydraulic configurations, with power density specifications driving price stratification.
- Hydraulic Hybrid:Accumulator-based systems store boom-down gravitational energy for immediate reuse. These dominate Chinese surface mining operations where MEE certification requirements favor proven mechanical architectures over battery-dependent alternatives.
- Electric Hybrid:Lithium-ion packs paired with downsized diesel engines enable sustained electric-only operation. Japanese metropolitan infrastructure contractors specify these for emissions-sensitive districts where METI carbon intensity thresholds are tightening.
- Diesel Hybrid:Integrated motor-generator units without plug-in capability serve cost-conscious fleet operators.
- Plug-in Hybrid:Grid-chargeable battery systems support full-shift electric operation at urban construction clusters.
Diesel hybrid systems command the established base. The steepest expansion runs through electric hybrid architectures.
Application:
Volume concentration varies by project duration and fuel cost exposure, with intermittent-duty segments favoring regenerative payback and continuous operations prioritizing power density.
- Construction:General building and civil works deploy all hybrid architectures across project scales. German urban contractors face accelerated replacement cycles as KBA standards harden verification requirements for municipal tenders.
- Mining:Surface extraction operations demand hydraulic hybrid durability under sustained loading. Chinese operators prioritize MEE-compliant diesel hybrid certification for domestic coal and mineral extraction licenses.
- Demolition:Selective dismantling and site clearance create intermittent high-torque demands suited to capacitor-assisted recovery.
- Landscaping:Residential and commercial grounds maintenance favors compact electric hybrids for noise-restricted zones.
Construction commands the established base. The steepest expansion runs through mining applications.
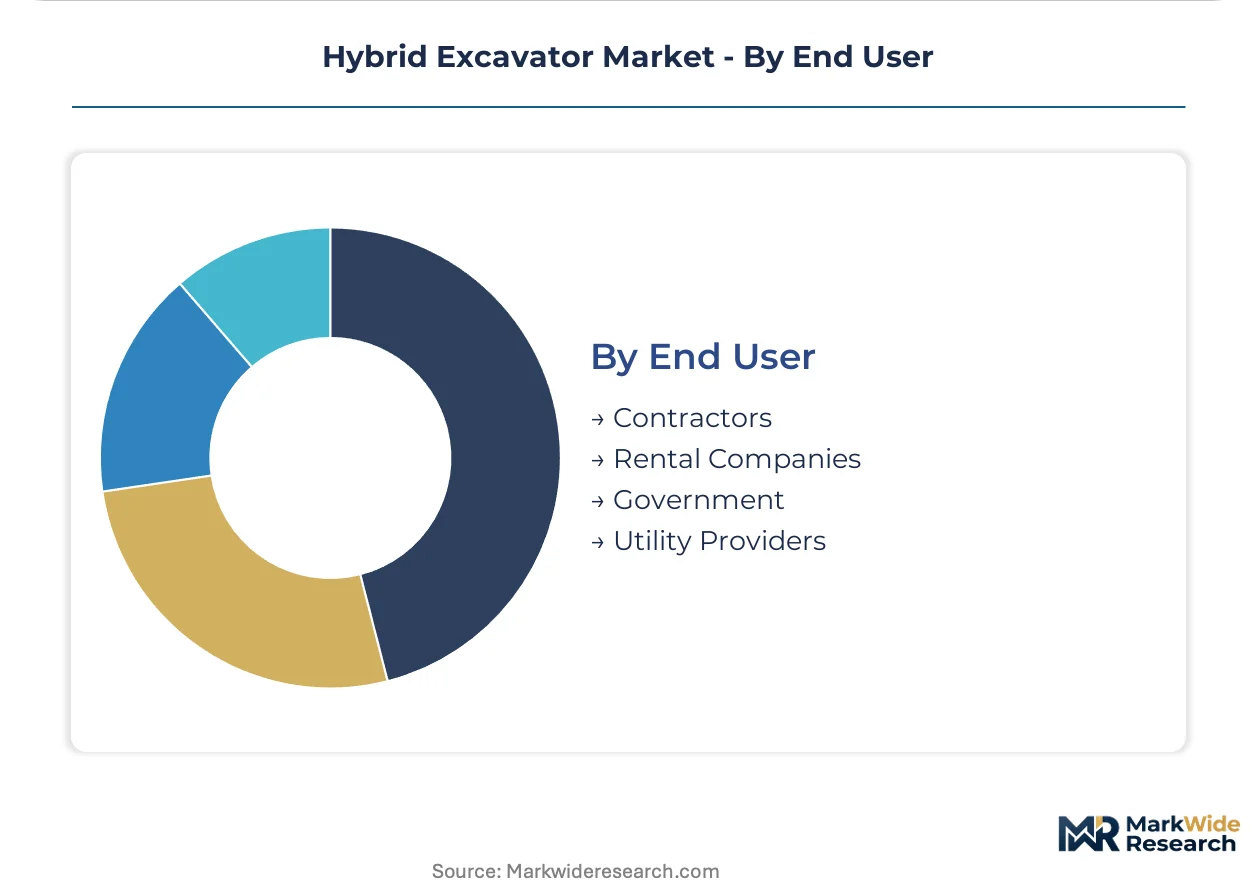
End User:
Customer type determines procurement scale and financing structure, with rental channels consolidating specifications and government buyers mandating compliance documentation.
- Contractors:Privately held construction firms purchase or lease based on project pipeline visibility. Japanese infrastructure specialists are expanding electric hybrid fleets ahead of METI enforcement timelines.
- Rental Companies:National and regional equipment lessors centralize acquisition decisions around fuel-guarantee economics. North American metropolitan rental chains bundle telemetry-enabled hybrids with outcome-based performance contracts.
- Government:Public works agencies specify emissions-compliant units for infrastructure stimulus programs.
- Utility Providers:Power generation and distribution operators maintain excavator fleets for trenching and vegetation management.
Contractors command the established base. The steepest expansion runs through rental companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German engineering clusters concentrate hybrid powertrain manufacturing, while Chinese mineral extraction demand and North American rental channel consolidation reshape procurement geography. Regulatory deadlines in Tokyo, Berlin, and Beijing are accelerating fleet replacement cycles ahead of enforcement timelines.
Germany
KBA construction equipment standards mandate real-world emissions documentation for municipal tender eligibility. Fleet operators in Munich and Hamburg are specifying telematics-enabled units to demonstrate compliance during urban infrastructure bidding. Bavarian rental chains centralize hybrid acquisition decisions around fuel-guarantee economics.
Japan
METI carbon intensity benchmarks compel domestic contractors to expand electric hybrid fleets ahead of enforcement deadlines. Tokyo and Osaka municipal authorities specify mini excavators for zero-emission zones under tightening domestic protocols. Kanto region infrastructure specialists lead fleet electrification among metropolitan construction firms.
China
MEE protocols tighten diesel hybrid certification standards for domestic coal and mineral extraction licenses. Surface mining operators in Shanxi and Inner Mongolia prioritize MEE-compliant hydraulic hybrid architectures. Yangtze River Delta urban construction clusters deploy plug-in hybrid units where on-site charging infrastructure spreads.
United States
EPA Tier 4 Final frameworks compress conventional diesel excavator economics in metropolitan construction markets. North American rental channel consolidation elevates fuel-guarantee clauses in national fleet procurement contracts. Texas and California metropolitan construction corridors concentrate hybrid adoption among infrastructure contractors facing emissions scrutiny.
Hybrid Excavator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated motor-generator engineering separates premium-positioned manufacturers from mid-market diesel hybrid assemblers. The field organizes around three archetypes: captive powertrain specialists, rental-channel optimizers, and mining-duty durability providers. Consolidation pressure is intensifying through direct manufacturer fleet management contracts and backward integration into battery supply chains.
Among Japanese-headquartered machinery producers, Komatsu and Hitachi Construction Machinery occupy positions exemplifying integrated powertrain development, while Volvo Construction Equipment represents the European connected-fleet telemetry archetype. These three anchors illustrate how regional engineering traditions translate into differentiated hybrid architectures.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| Doosan Infracore |
| Caterpillar |
| Kobelco Construction Machinery |
| JCB |
| Volvo Construction Equipment |
| Liebherr Group |
| DEVELON |
| Komatsu |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Japanese manufacturers and lithium suppliers lock in battery cell access while capping price volatility exposure for electric hybrid powertrain production. These arrangements bind METI-aligned contractors to predictable cost structures as carbon intensity benchmarks tighten procurement specifications.
Pricing Analysis
EU Stage V dictates the pricing tier structure across European markets, separating telematics-enabled compliance documentation units from standard configurations. Three-tier pricing structure across premium certified, connected fleet, and base diesel hybrid levels reflects KBA homologation investment and after-sales telemetry bundling. Cost compression in mid-market diesel hybrids is intensifying because rental channel consolidation centralizes procurement decisions around fuel-guarantee economics. Municipal contractors in Germany exhibit lowest price sensitivity due to tender compliance mandates, while independent Japanese construction firms face acute pressure from METI enforcement timelines.
Supply Chain Analysis
China and Japan anchor rare earth processing and lithium-ion cell manufacturing for hybrid excavator powertrains. High-efficiency motor magnets draw from Chinese refining infrastructure, while Japanese producers control integrated motor-generator system assembly. Single-source vulnerability concentrates in dysprosium and terbium separation capacity, creating geopolitical exposure for non-domestic equipment manufacturers. Distribution runs through manufacturer-direct fleet management contracts that displace traditional distributor networks in North American and European metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric hybrid architectures are disrupting earthmoving equipment procurement as lithium pack cost declines intersect with tightening emissions frameworks across Japan, Germany, and China.
For Market Incumbents: Secure captive battery supply agreements through backward integration into cell manufacturing or long-term offtake partnerships with Chinese and South Korean producers. Defend against rental channel displacement by embedding connected fleet telemetry as standard equipment rather than premium optionality, locking in fuel-guarantee contract renewals through performance data ownership. For New Entrants and Emerging Players: Differentiate on capacitor-assisted load cycle technology for high-frequency swing operations where rapid charge-discharge cycles outperform battery-only configurations. Target Japanese metropolitan infrastructure contractors facing METI deadline pressure with mini excavator configurations purpose-built for zero-emission zones. Pursue direct municipal tender relationships in Osaka and Tokyo that bypass established distributor relationships. For Investors and Strategic Acquirers: Component remanufacturing specialists with established battery diagnostics capabilities represent the most attractive acquisition profile as early hybrid fleets approach replacement thresholds. Long-term viability hinges on second-life valuation economics and technician training infrastructure for high-voltage system maintenance. Watch MEE protocol enforcement intensity in Chinese surface mining licenses as inflection indicator for hydraulic hybrid demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive lithium-ion capacity insulates Japanese manufacturers from nickel price volatility and METI compliance deadlines. |
| Connected Fleet Telemetry Platform Launch | Real-time fuel consumption documentation satisfies KBA municipal tender requirements for German rental operators. |
| Capacitor-Assisted Powertrain Development | Rapid charge-discharge engineering targets high-frequency swing operations in Tokyo urban construction zones. |
| Second-Life Battery Remanufacturing Scale-Up | Component resale economics extend asset lifecycles as early electric hybrid fleets reach replacement thresholds. |
| Direct Municipal Fleet Management Contracting | Outcome-based performance agreements displace traditional distributors in North American metropolitan rental channels. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with equipment procurement directors, rental fleet managers, and powertrain engineering leads; and secondary validation through SEC equipment manufacturer filings, customs trade records for lithium and rare earth flows, and EPA Tier 4 Final compliance databases. Bottom-up unit shipment estimates triangulated against top-down construction equipment spend analysis across Japanese, German, Chinese, and North American markets.
Across the analysis window, volume and value outputs reflect segmented modeling across product size class, powertrain architecture, application intensity, and end-user procurement structure. CAGRs derived from regression analysis of historical fleet replacement cycles against regulatory deadline schedules, with lithium pack cost curves and on-site charging infrastructure penetration as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained lithium cost declines or accelerated MEE enforcement would require recalibration. Forecasts reflect documented assumptions regarding technician training pipeline expansion and second-life battery valuation market development. Recalibration cycles align with material shifts in METI benchmark enforcement, KBA homologation timeline compression, and rare earth processing capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Jackhammer Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Tower Crane Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Snow Removal Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Wheeled Excavators Market