
 Hot-Rolling Mill and Cold-Rolling Mill Market | 2026-2036
Hot-Rolling Mill and Cold-Rolling Mill Market Size, Share, and Industry Trends Forecast 2026-2036
Hot-Rolling Mill and Cold-Rolling Mill Market Insights
The EU Carbon Border Adjustment Mechanism is restructuring procurement priorities across European steel-consuming industries, compelling mill operators to demonstrate embedded carbon transparency. SMS Siemag leverages its hydraulic automation portfolio to capture retrofit demand from legacy European flat-rolling lines. Danieli sustains competitive intensity through continuous casting-to-rolling integration know-how anchored in Italian engineering heritage. Primetals Technologies dominates digital twin deployments for process optimization across Asian greenfield installations.
Hot-rolling mills and cold-rolling mills are metal-forming installations that reduce slab or billet thickness through compressive forces applied by rotating work rolls, with hot rolling operating above recrystallization temperature (typically exceeding 900°C for carbon steel) and cold rolling performed at ambient temperature to achieve tighter dimensional tolerances and superior surface finish. These systems produce coils, plates, strips, and structural sections that serve as feedstock for automotive body panels, appliance enclosures, pipeline segments, and construction frameworks. Tandem rolling configurations command the largest installed base due to throughput advantages in high-volume flat steel production, while skin pass lines concentrate margin pools through value-added surface texture control for exposed automotive applications. Mill automation technology is expanding fastest as operators pursue yield improvements and energy recovery across reverse rolling and continuous process types.
The US EPA enforces emissions benchmarks under the Clean Air Act that constrain reheating furnace configurations, while China's MEE implements dual carbon goals that accelerate electric drive retrofits in provincial steel clusters. India's BIS mandates dimensional and metallurgical certification for structural rolled products, shaping domestic equipment procurement specifications. Stakeholders must monitor evolving carbon accounting protocols and automation readiness gaps to align capital deployment with tightening product standards and buyer qualification requirements.
Market Dynamics
The EU Carbon Border Adjustment Mechanism is restructuring procurement priorities across European steel-consuming industries, compelling mill operators to demonstrate embedded carbon transparency and redirect capital toward low-emission configurations.
Growth Catalysts
- Automotive OEM demand:Germany and Japan are expanding orders for advanced high-strength steel flat products, requiring precision rolling capabilities that favor tandem mill investments.
- Carbon accounting mandates:The EU CBAM redirects procurement toward low-emission mill configurations, creating retrofit demand for reheating furnace upgrades and electric drive systems.
- India's western industrial corridor:JSW Steel and Tata Steel are commissioning new integrated rolling complexes, concentrating equipment demand in Gujarat and Maharashtra states.
Market Restraints
- Scrap price volatility:Electric arc furnace feedstock costs fluctuate with global ferrous scrap flows, compressing margin visibility for mini-mill rolling investments.
- Chinese equipment oversupply:Domestic mill builders in Hebei and Jiangsu provinces carry excess capacity, exporting at price points that erode Western OEM profitability.
- Reheating furnace emissions limits:The US EPA Clean Air Act constrains burner configurations, extending compliance timelines for brownfield hot-rolling upgrades.
Strategic Opportunities
- Digital twin integration:Process optimization platforms are converging with AI-driven predictive maintenance, opening margin pools for automation-first mill suppliers.
- India's PLI scheme:The production-linked incentive framework for specialty steel is accelerating greenfield cold-rolling capacity in Odisha and Karnataka.
- Hydrogen-ready furnace retrofits:Pilot installations in Rotterdam and Hamburg are validating hydrogen combustion for reheating, positioning early movers for EU Green Deal alignment.
Industry Challenges
- Automation engineering scarcity:Mill operators face shortages of hydraulic systems specialists and model predictive control programmers, delaying commissioning timelines for tandem mill upgrades.
- Legacy DCS integration:Brownfield installations require protocol bridging between 1990s-era distributed control systems and modern IoT architectures, inflating project risk.
- BIS certification timelines:India's dimensional and metallurgical certification for structural rolled products extends equipment qualification cycles, constraining working capital for domestic mill builders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot-Rolling Mill and Cold-Rolling Mill Market |
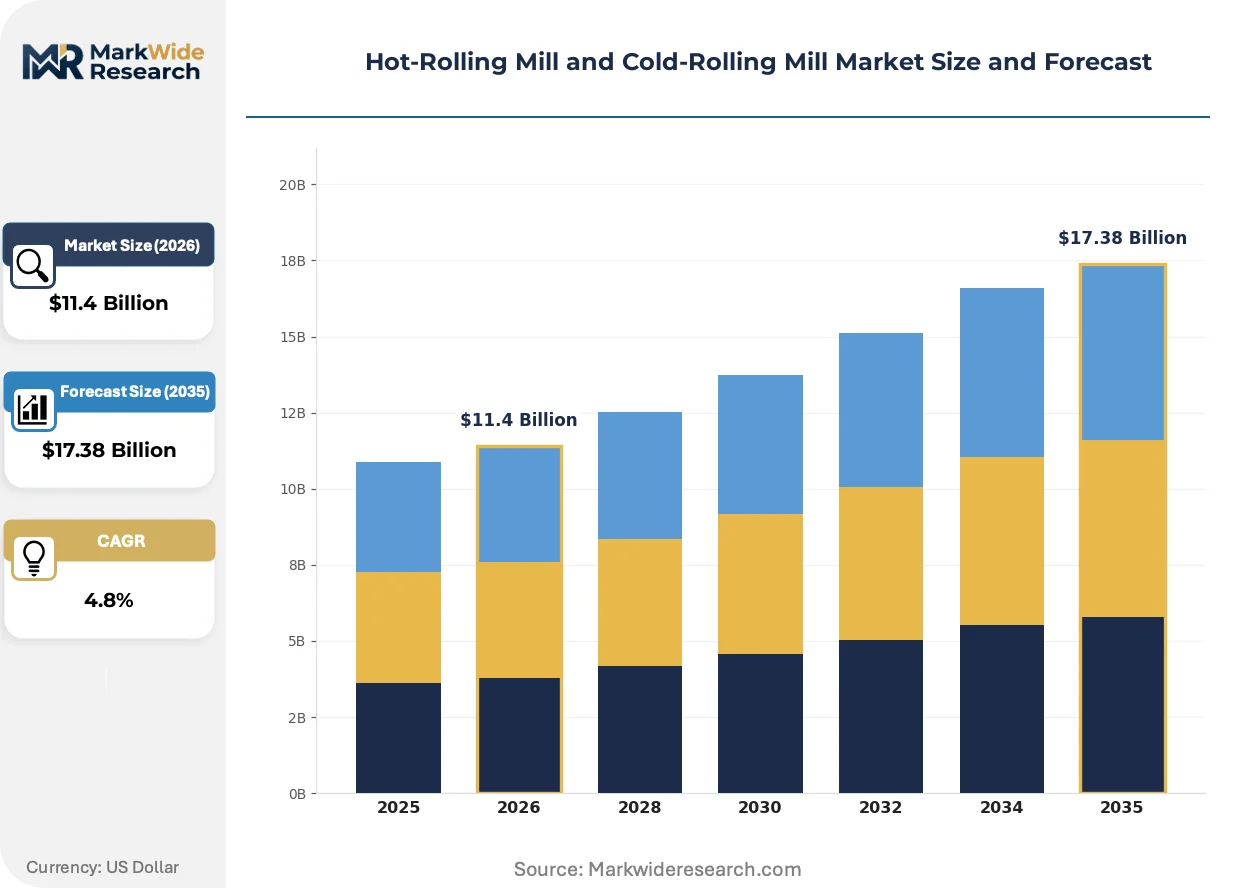
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Hot-Rolling, Cold-Rolling, Tandem Rolling, Reverse Rolling, Skin Pass Technology: Hydraulic, Mechanical, Electric, Universal, Continuous, Mill Automation Application: Pipeline Manufacturing, Wire Production, Metal Fabrication, Structural Components, Packaging Foils End User Industry: Shipbuilding, Heavy Machinery, Construction Equipment, Consumer Appliances, Aerospace |
| Companies Covered | ANDRITZ, Fives Group, Danieli, China National Erzhong Group, China First Heavy, SMS Siemag, Achenbach Buschhütten GmbH & Co. KG, Cisdi Group, Primetals Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot-Rolling Mill and Cold-Rolling Mill Market Trends and Innovations
Process intelligence layers are absorbing operational data streams to compress yield loss and energy intensity, while regulatory carbon accounting and buyer procurement centralization reshape competitive positioning.
Edge-deployed digital twins are absorbing real-time thermomechanical data from finishing mills to predict strip profile deviations before they propagate downstream. Automotive OEMs in Germany and Japan are demanding this capability as a qualification threshold for high-strength steel supply contracts. The technology is absorbing margin from conventional thickness gauge feedback systems that require post-coil correction.
The EU Carbon Border Adjustment Mechanism imposes embedded emissions reporting on imported steel products, forcing mill operators to instrument supply chains with verified carbon accounting. European flat-rolling lines are retrofitting reheating furnaces with hydrogen-ready burners and electric induction alternatives to preserve market access. Asian exporters to the EU are accelerating Scope 3 data collection to avoid tariff exposure.
Automotive OEM procurement departments are consolidating rolling mill qualification around single-source digital platforms that integrate quality certification, carbon footprint verification, and logistics tracking. Tier-1 steel distributors in the US Midwest are losing intermediation value as Detroit-based OEMs direct-contract mill operators with API-compliant digital interfaces. This pattern concentrates order volume with integrated producers capable of end-to-end data transparency.
Hot-Rolling Mill and Cold-Rolling Mill Market Segmentation
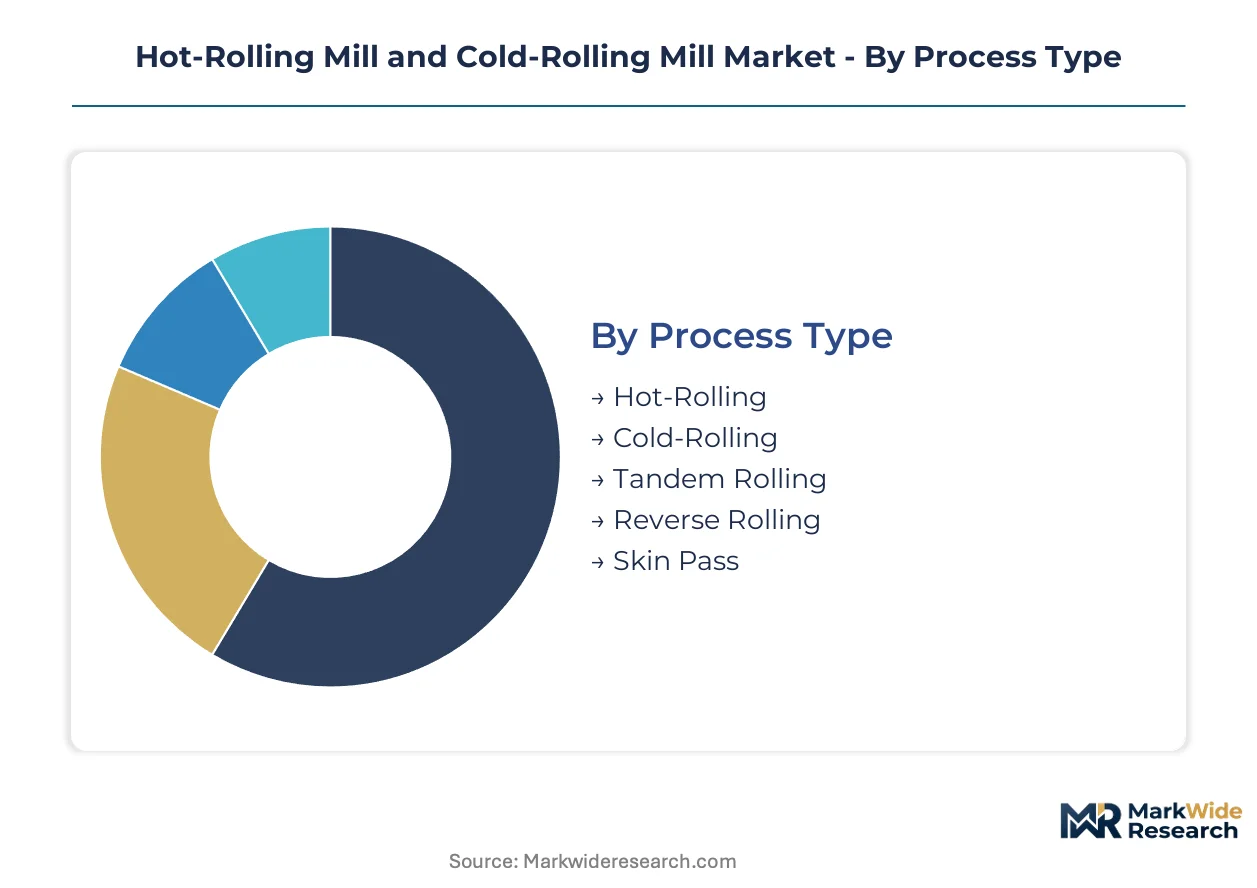
Mill configuration decisions cascade through capital intensity, energy consumption, and product qualification requirements. Procurement patterns diver sharply between high-volume commodity producers and precision-oriented specialty steel suppliers.
Process Type:
Thermomechanical pathways determine yield rates, surface quality, and downstream processing requirements for finished flat products.
- Hot-Rolling:Slabs pass through work rolls above recrystallization temperature, typically exceeding 900°C for carbon steel grades. Demand concentrates in India's western industrial corridor, where JSW Steel and Tata Steel are commissioning new integrated complexes to serve domestic construction and infrastructure markets.
- Cold-Rolling:Ambient-temperature reduction delivers tighter dimensional tolerances and superior surface finish for exposed automotive applications. Germany and Japan are expanding orders for advanced high-strength steel flat products, requiring precision tandem mill configurations that favor this process.
- Tandem Rolling:Sequential mill stands enable high-throughput continuous reduction with inter-stand tension control.
- Reverse Rolling:Single-stand configurations with reversing material flow suit lower-volume specialty grades and prototype development.
- Skin Pass:Light reduction lines concentrate margin pools through value-added surface texture control for exposed automotive panels and appliance enclosures.
Mature deployment sits with tandem rolling. Newer deployment is concentrated in skin pass configurations serving premium automotive qualification requirements.
Technology:
Actuation and control architectures differentiate capital cost structures, maintenance regimes, and automation upgrade pathways.
- Mill Automation:Edge-deployed digital twins absorb real-time thermomechanical data to predict strip profile deviations before downstream propagation. Automotive OEMs in Germany and Japan demand this capability as a qualification threshold for high-strength steel supply contracts.
- Hydraulic:High-force precision positioning systems dominate retrofit demand from legacy European flat-rolling lines seeking improved gauge control without full mechanical replacement.
- Mechanical:Screw-down and eccentric mechanisms persist in emerging market installations where capital constraints favor proven designs.
- Electric:Servo-electric drive systems are gaining share fastest in provincial Chinese steel clusters accelerating electric drive retrofits under MEE dual carbon goals.
- Universal:Configurable roll arrangements accommodate multiple product geometries within single asset footprints.
- Continuous:Casting-to-rolling integration eliminates reheating stages, preserving energy intensity advantages for integrated producers.
Established infrastructure favors hydraulic and mechanical systems. Accelerating investment flows toward electric and automation layers.
Application:
End-product specifications dictate metallurgical requirements, dimensional precision, and surface quality thresholds.
- Pipeline Manufacturing:Heavy-gage plate rolling for longitudinally welded line pipe requires controlled thermomechanical processing to achieve API specification toughness. Demand anchors in energy infrastructure projects across North American shale corridors and Middle East export terminals.
- Structural Components:Wide-flange beams and columns for commercial construction require India's BIS-mandated dimensional and metallurgical certification, extending equipment qualification cycles for domestic mill builders.
- Wire Production:Rod mill downstream processing feeds drawing and stranding operations for tire cord, bridge cable, and electrical conductor applications.
- Metal Fabrication:General-purpose flat products serve job shops and original equipment manufacturers with moderate tolerance requirements.
- Packaging Foils:Ultra-thin cold-rolled strip for food and pharmaceutical barrier applications demands specialized Sendzimir mill configurations.
Volume concentration remains with structural and fabrication grades. Margin expansion concentrates in pipeline and packaging foil specifications.
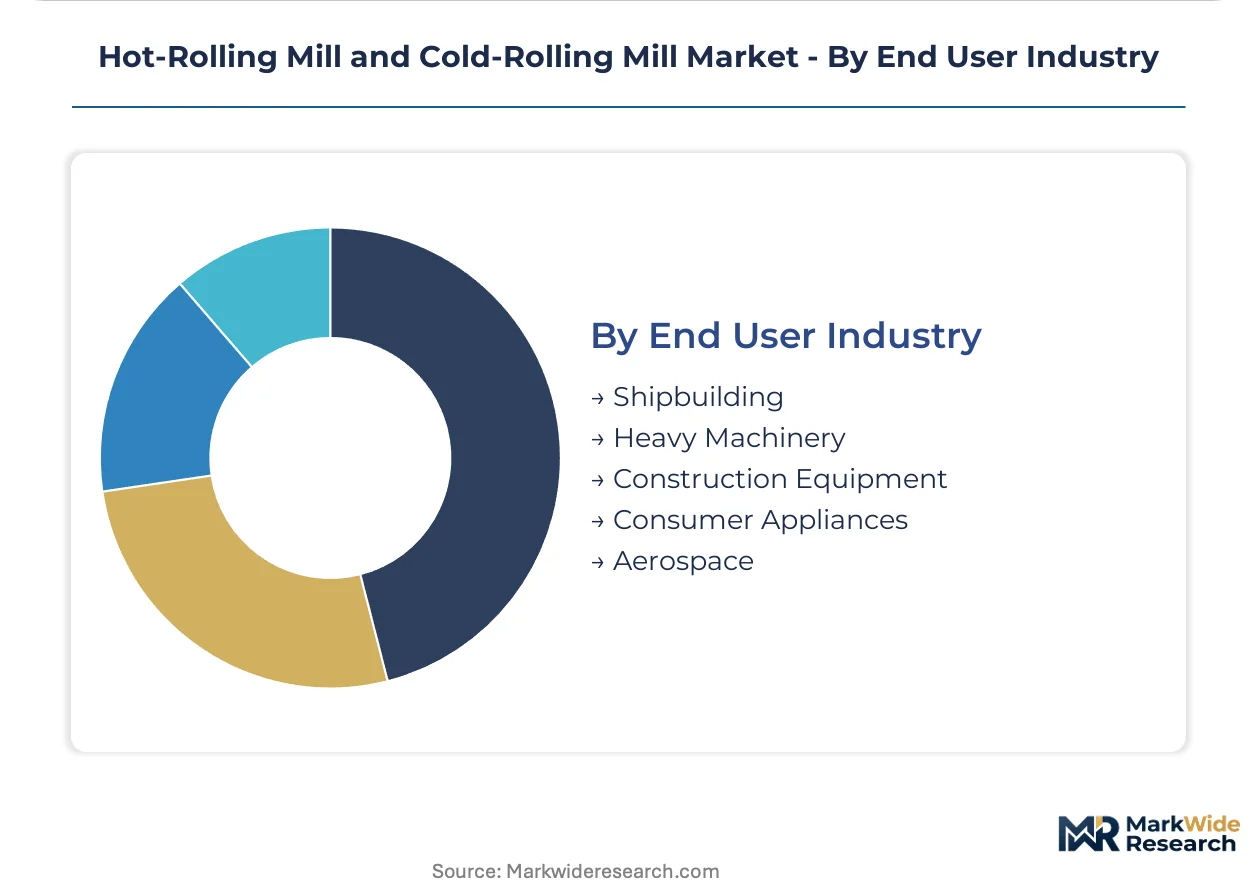
End User Industry:
Customer qualification regimes, certification documentation, and order predictability vary substantially across industrial sectors.
- Construction Equipment:High-strength plate and structural sections for excavators, cranes, and mining machinery require impact toughness verification. Procurement concentrates with integrated producers capable of end-to-end carbon footprint transparency under tightening OEM sustainability mandates.
- Consumer Appliances:Exposed panel surfaces demand skin-passed cold-rolled coil with controlled roughness and cosmetic defect thresholds.
- Shipbuilding:Classification society rules from Lloyd's Register and DNV govern plate certification for hull and deck structures.
- Heavy Machinery:Forgings and weldments for industrial presses and power generation equipment require through-thickness property assurance.
- Aerospace:Titanium and specialty alloy rolling for airframe and engine components represents the most stringent qualification regime, with AS9100 and NADCAP requirements limiting qualified supplier pools.
Contract stability characterizes construction equipment and shipbuilding relationships. Qualification intensity peaks with aerospace specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's western industrial corridor concentrates India's most aggressive rolling mill capacity expansion, with JSW Steel and Tata Steel commissioning integrated complexes that reshape regional equipment procurement patterns.
United States
Pipeline manufacturing for North American shale corridors drives heavy-gage plate rolling demand. The US EPA enforces Clean Air Act emissions benchmarks that constrain reheating furnace configurations and extend compliance timelines for brownfield hot-rolling upgrades. Detroit-based automotive OEMs are consolidating mill qualification around single-source digital platforms, concentrating order volume with integrated producers capable of end-to-end data transparency.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are expanding orders for advanced high-strength steel flat products requiring precision tandem mill capabilities. The EU Carbon Border Adjustment Mechanism compels mill operators to demonstrate embedded carbon transparency and redirect capital toward low-emission configurations. SMS Siemag leverages its hydraulic automation portfolio to capture retrofit demand from legacy European flat-rolling lines in the Ruhr industrial region.
China
Provincial steel clusters in Hebei and Jiangsu provinces carry excess domestic mill builder capacity, exporting at price points that erode Western OEM profitability. The MEE implements dual carbon goals that accelerate electric drive retrofits across these industrial concentrations. Danieli sustains competitive intensity through continuous casting-to-rolling integration know-how anchored in Italian engineering heritage, competing for greenfield Asian installations.
India
JSW Steel and Tata Steel are commissioning new integrated rolling complexes in Maharashtra and Gujarat states, concentrating equipment demand in the western industrial corridor. India's BIS mandates dimensional and metallurgical certification for structural rolled products, shaping domestic equipment procurement specifications and extending qualification cycles. The production-linked incentive framework for specialty steel is accelerating greenfield cold-rolling capacity in Odisha and Karnataka.
Japan
Automotive OEMs in the Nagoya and Osaka industrial zones demand edge-deployed digital twin capabilities as qualification thresholds for high-strength steel supply contracts. METI industrial policy supports precision manufacturing investments that favor tandem mill configurations with advanced automation layers. Primetals Technologies dominates digital twin deployments for process optimization across these Asian greenfield installations.
Hot-Rolling Mill and Cold-Rolling Mill Market Competitive Landscape
The competitive structure tilts toward integrated technology conglomerates with cross-border project execution capabilities. Equipment supply concentrates among firms with proprietary automation portfolios and continuous casting integration expertise. Three archetypes dominate: European engineering houses with hydraulic retrofit specializations, Asian state-backed heavy machinery conglomerates with cost-advantaged scale, and automation-first specialists with digital twin competencies. Competitive moves center on hydrogen-ready furnace technology licensing and strategic partnerships for carbon accounting platform integration.
Among European engineering houses, Danieli and SMS Siemag exemplify the automation-centric archetype, occupying positions defined by hydraulic precision and digital integration capabilities. China National Erzhong Group and China First Heavy represent the state-backed scale tier, anchoring cost-competitive supply for emerging market greenfield projects. Primetals Technologies sits within the digital-first specialization vector, capturing premium positioning through predictive maintenance and process optimization platforms demanded by automotive OEM qualification regimes.
| Leading Market Players |
|---|
| ANDRITZ |
| Fives Group |
| Danieli |
| China National Erzhong Group |
| China First Heavy |
| SMS Siemag |
| Achenbach Buschhütten GmbH & Co. KG |
| Cisdi Group |
| Primetals Technologies |
| Others |
Pricing and Supply Chain Analysis
Mill automation engineering talent clusters in Germany's Ruhr region and Japan's Nagoya corridor, where labor-cost differentials between these precision hubs and emerging-market assembly centers sustain three-tier equipment pricing spreads across premium digital-native configurations, mid-tier hydraulic retrofits, and economy mechanical systems.
Pricing Analysis
Outcome-based pricing tied to guaranteed yield improvement and energy recovery performance anchors premium tier positioning for automation-first mill suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked and AS9100-compliant systems commanding substantial premia over BIS-baseline configurations. Pricing pressure stems from Chinese equipment oversupply in Hebei and Jiangsu provinces exporting at cost-advantaged price points. Emerging market greenfield buyers exhibit highest price sensitivity, while German and Japanese automotive OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle automotive qualification demand, while distributor networks serve construction equipment and structural steel segments. Manufacturing concentration rests in Germany, Italy, and China, with SMS Siemag and Danieli anchoring European precision supply and China First Heavy feeding cost-sensitive emerging market demand. Critical dependencies include forged work rolls from Japan and South Korea, high-grade bearing assemblies from Germany, and advanced hydraulic servo valves from Italy. Single-source vulnerability concentrates in specialized mill automation software stacks. Distribution runs through EPC contractors for integrated greenfield complexes and direct mill builder relationships for brownfield retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Carbon Border Adjustment Mechanism transforms this market into a cost-of-compliance story, where embedded carbon transparency requirements erect barrier-to-entry moats favoring incumbents with verified Scope 3 data infrastructure and hydrogen-ready furnace technology.
For Market Incumbents: Cement market position through hydrogen-ready furnace retrofit licensing partnerships with Rotterdam and Hamburg pilot installations, and deepen backward integration into digital twin software stacks to defend against automation-specialist encroachment from Primetals Technologies. Prioritize certification investment for EU Green Deal alignment as Chinese state-backed competitors lack embedded carbon accounting capabilities. For New Entrants and Emerging Players: Capture white-space opportunity in India's Odisha and Karnataka cold-rolling capacity expansion under the PLI scheme for specialty steel, where domestic mill builders face BIS certification timeline constraints. Target aftermarket service and legacy DCS protocol bridging for 1990s-era European flat-rolling lines, positioning through API-compliant digital interfaces as Detroit-based OEMs consolidate mill qualification platforms. For Investors and Strategic Acquirers: Re-rating potential sits with automation-first specialists given automotive OEM digital twin qualification thresholds reshaping competitive positioning. Long-term viability favors firms with predictive maintenance platforms and continuous casting-to-rolling integration know-how. Watch hydrogen combustion validation milestones in EU pilot installations as inflection indicator for green premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Furnace Retrofit | EU CBAM compliance preserves market access for European flat-rolling lines. |
| Digital Twin Platform Deployment | Automotive OEMs in Germany and Japan demand this capability for qualification. |
| Backward Integration into Automation Software | Proprietary control stacks defend margin against specialist encroachment. |
| PLI-Aligned Greenfield Capacity | India's specialty steel incentive accelerates cold-rolling investment in Odisha. |
| Legacy DCS Protocol Bridging | Brownfield European installations require integration with 1990s-era architectures. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and EPC contractors across Germany, Japan, India, and China. Secondary validation drew from EPA Clean Air Act enforcement records, EU CBAM implementation guidance, MEE dual carbon policy documents, and BIS certification timelines. Bottom-up equipment shipment tallies and top-down steel production capacity modeling enabled cross-verification.
Data-stream reconciliation across process type, technology layer, end-use application, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling against steel production forecasts and automotive OEM capacity expansion announcements. Industry-specific inputs included reheating furnace emissions compliance cost curves and digital twin adoption rates among tier-1 steel distributors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU CBAM tariff calibration, hydrogen infrastructure buildout pace, and Chinese equipment export financing availability. Forecasts reflect documented assumptions on scrap price volatility bands and automotive lightweighting penetration curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
United States Hand Holes Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Crane Mats Market