
 Cable Conduit Market | 2026-2036
Cable Conduit Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Conduit Market Outlook
Utility-scale solar developers are collapsing the traditional buyer mix that once favored residential electrical contractors. Atkore International Group Inc. leverages its integrated steel and PVC manufacturing footprint to control input costs across North American distribution channels. Legrand S.A. anchors European demand through specialized cable management systems that comply with evolving CE marking requirements under the EU Construction Products Regulation.
Cable conduit comprises rigid or flexible tubing systems manufactured from PVC, galvanized steel, aluminum, or HDPE, engineered to protect electrical wiring from mechanical damage, moisture ingress, and electromagnetic interference in commercial and industrial environments. The fabrication process typically involves extrusion for thermoplastic variants or roll-forming and welding for metallic types, with wall thickness and corrosion resistance as critical performance parameters. Metal conduit sustains premium positioning in heavy industrial and hazardous location applications where impact resistance and grounding continuity are non-negotiable, while HDPE is displacing legacy materials in underground telecom and renewable energy installations due to superior flexibility and moisture immunity. Installation method segmentation reveals that underground deployment commands the highest project values despite longer lead times, whereas surface mount raceways dominate renovation and retrofit volumes in commercial buildings.
NFPA 70 National Electrical Code in the United States, the EU Construction Products Regulation with CE marking obligations, and China's GB standards administered by SAMR collectively define product compliance thresholds that determine market access and procurement eligibility. These frameworks increasingly mandate halogen-free and low-smoke formulations in public infrastructure and high-occupancy structures, directly steering R&D investment toward advanced polymer compounds. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps as specification standards tighten.
Market Dynamics
Data center construction is compressing procurement cycles for high-density cable management systems, forcing manufacturers to synchronize production schedules with hyperscale facility buildouts across multiple continents simultaneously.
Growth Catalysts
- NFPA 70 National Electrical Code revisions:Tightened fire-resistance standards in the United States are mandating upgraded conduit specifications for commercial installations, pulling premium metal and halogen-free polymer products into new construction.
- Grid modernization in China:Tier-one city infrastructure projects under SAMR-administered GB standards are expanding underground cable protection requirements across transmission and distribution networks.
- HDPE flexibility advantages:Utility-scale solar developers are specifying corrugated high-density polyethylene conduit for trenchless directional drilling applications, reducing installation labor hours compared to rigid alternatives.
Market Restraints
- Steel input cost volatility:Galvanized steel coil prices fluctuate with scrap metal availability and energy costs, compressing margins for metallic conduit producers serving industrial segments.
- Concentrated resin supply:PVC and HDPE pellet production clusters in the US Gulf Coast and Middle East create geographic vulnerability to weather disruptions and export restrictions.
- Halogen-free formulation complexity:Low-smoke zero-halogen polymer compounds require specialized compounding capabilities that limit supplier pool depth for public infrastructure projects.
Strategic Opportunities
- Telecom fiber densification:5G small cell backhaul and rural broadband initiatives in India under TRAI guidelines are creating demand for microduct conduit bundles.
- EU Green Deal alignment:CE marking requirements under the Construction Products Regulation are steering R&D toward recyclable thermoplastic formulations with embedded post-consumer content.
- Modular data center pre-fabrication:Off-site electrical skids are opening specification channels for pre-bundled conduit assemblies that reduce on-site termination labor.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction testing for fire-resistance ratings under UL, IEC, and GB protocols extends product launch cycles by 8-14 months.
- Legacy raceway integration:Surface mount installations in commercial renovation projects require mechanical compatibility with obsolete conduit diameters and thread standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Conduit Market |
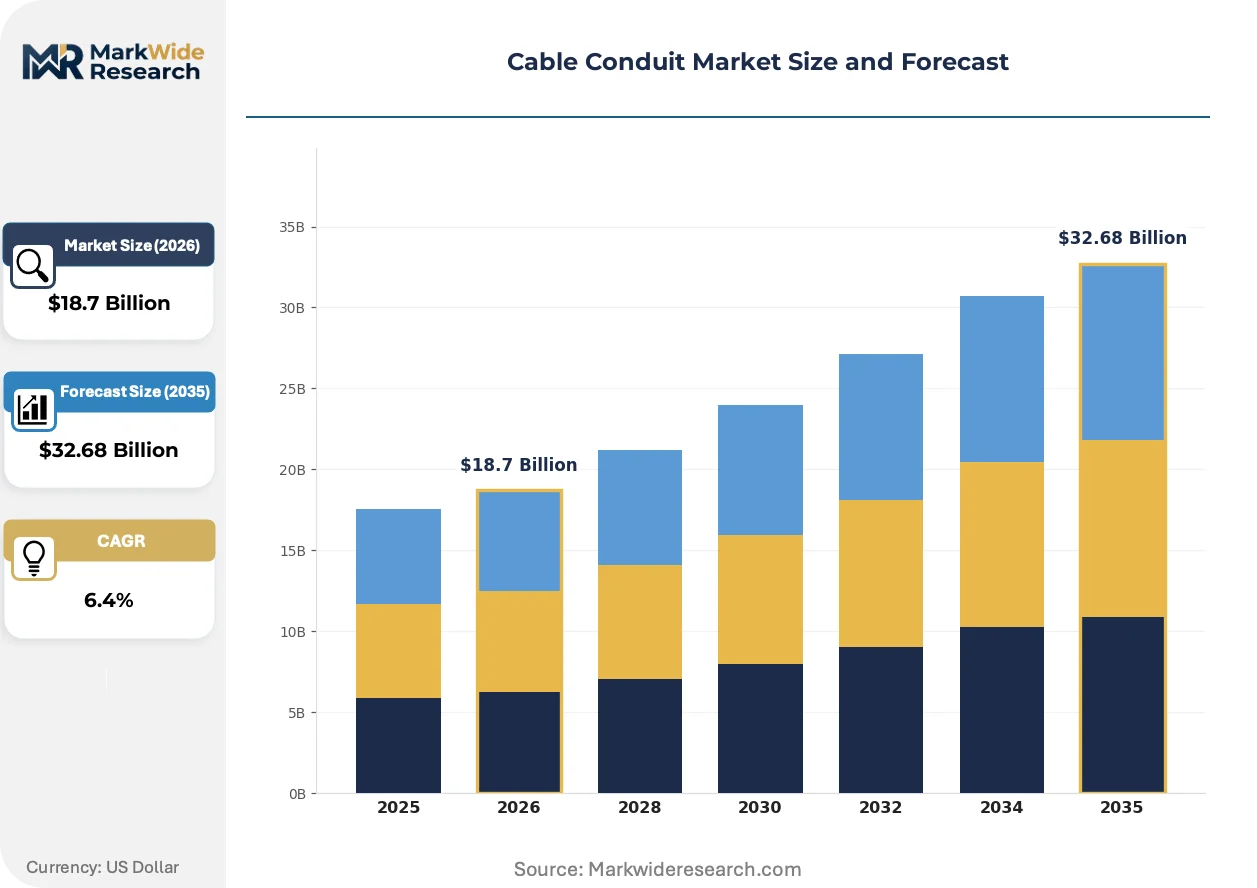
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, Metal, Fiber, HDPE Installation Method: Surface Mount, Underground, Suspended, Conduit Raceways Application: Residential, Commercial, Industrial, Telecommunication End User: Contractors, Electrical Firms, Manufacturers, Others |
| Companies Covered | Atkore International Group Inc., Hubbell Incorporated, Legrand S.A., Schneider Electric SE, ABB Ltd., Eaton Corporation plc, HellermannTyton Group PLC, Aliaxis Group, Electri-Flex Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Conduit Market Strategic Shifts
Material substitution and regulatory chemistry mandates are rewriting specification criteria across electrical infrastructure, compressing the window between laboratory formulation and field deployment.
Corrugated HDPE conduit with integrated pull tape is supplanting traditional PVC schedule 40 in underground telecom and renewable energy installations. Directional drilling contractors favor its flexibility for navigating rocky substrate without fracture. The shift is compressing demand for rigid thermoplastic variants in applications where bending radius tolerance outweighs crush resistance requirements.
REACH restrictions on halogenated flame retardants in the European Union are forcing reformulation of PVC compounds used in public infrastructure. Compounders must validate alternative mineral fillers through extended smoke toxicity testing. German rail and airport projects now specify exclusively halogen-free systems, creating a certification barrier for imports lacking ECHA-registered additive packages.
Consolidated procurement by hyperscale data center operators is collapsing the traditional distributor channel for large-diameter metal conduit. Amazon Web Services and Microsoft Azure facilities now source directly through mill-certified programs, bypassing electrical wholesalers. This concentration is most visible in Northern Virginia and Frankfurt, where multi-gigawatt campus developments command dedicated production lines from major suppliers.
Cable Conduit Market Segmentation
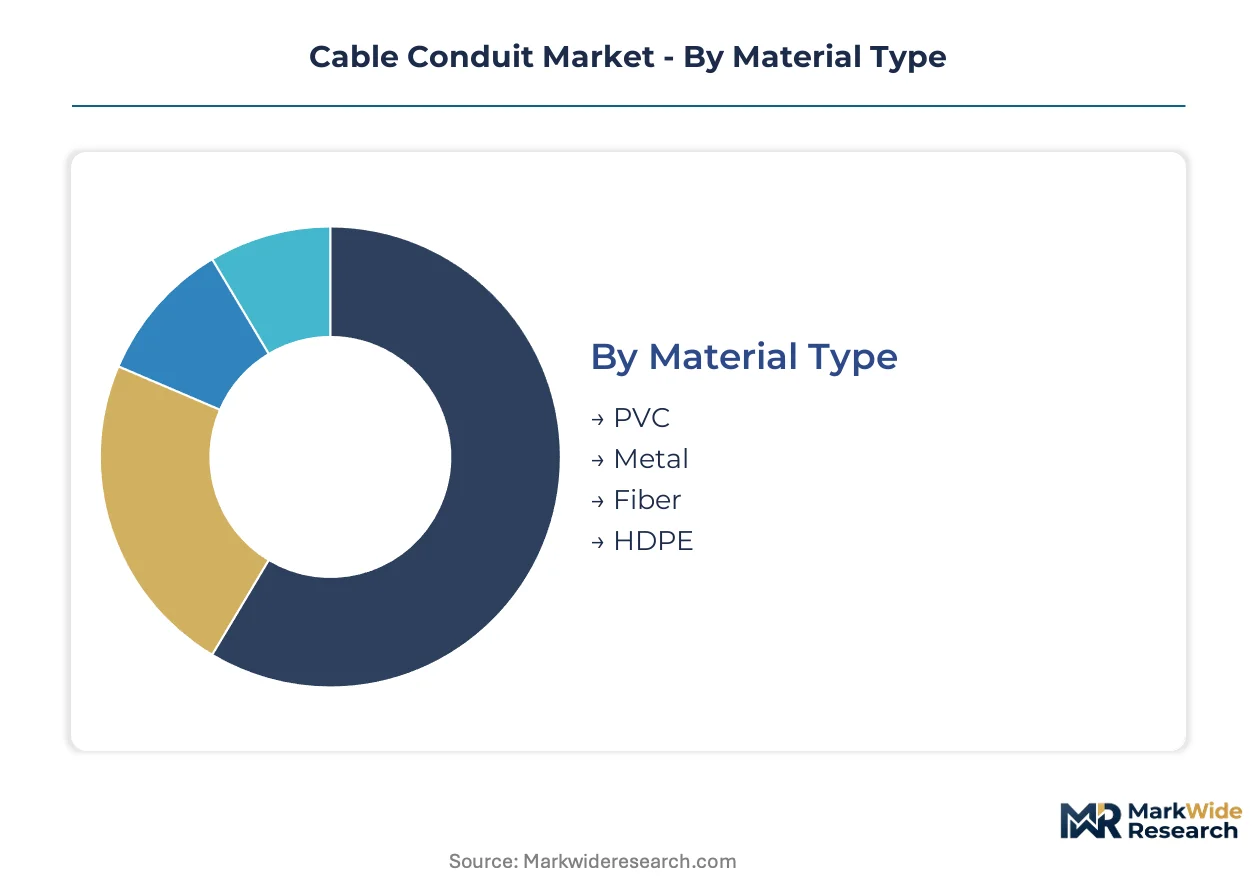
Cable conduit procurement channels vary sharply by material rigidity and installation complexity. Electrical wholesalers stock surface-mount raceways for renovation contractors, while HDPE and metal conduit for infrastructure projects flow through direct mill relationships.
Material Type:
Channel mix splits between stocked commodity grades and project-specified engineered materials. Distributors carry PVC and standard metal conduit for maintenance electricians. HDPE and specialty formulations ship direct to utility-scale developers.
- Metal:Galvanized steel and aluminum conduit deliver crush resistance and electromagnetic shielding for industrial machinery and hazardous locations. Data center construction in Northern Virginia and Frankfurt is pulling dedicated production lines from major suppliers through mill-direct procurement. By volume, metal leads. By growth pace, HDPE is expanding most quickly.
- HDPE:Corrugated high-density polyethylene conduit withstands moisture ingress and accommodates tight bending radii for trenchless directional drilling. Utility-scale solar developers in India and Australia specify HDPE for reduced installation labor hours compared to rigid alternatives.
- PVC:Schedule 40 and 80 thermoplastic conduit serves residential and light commercial surface installations through electrical wholesale channels.
- Fiber:Composite fiber-reinforced conduit offers corrosion immunity for coastal and chemical processing environments where metallic alternatives degrade.
Metal commands the highest project values per linear foot. HDPE gains share fastest in underground renewable energy and telecom deployments.
Installation Method:
Application environment dictates labor intensity and specification authority. Surface installations allow contractor discretion, while buried infrastructure requires engineer-stamped submittals.
- Underground:Directional drilling and open-trench burial of HDPE and PVC conduit protects transmission cables from mechanical damage and environmental exposure. Grid modernization in China's tier-one cities is expanding underground cable protection requirements across distribution networks. By volume, underground leads. By margin contribution, suspended installations are ahead.
- Surface Mount:Exposed raceway systems dominate commercial renovation where concealed routing is impractical. NFPA 70 revisions are tightening fire-resistance standards for these visible installations.
- Suspended:Overhead conduit runs in manufacturing facilities and warehouses command premium labor rates and specialized support hardware.
- Conduit Raceways:Pre-wired channel systems reduce on-site termination labor for modular data center pre-fabrication.
Underground deployment absorbs the longest lead times and highest engineering oversight. Surface mount generates the highest transaction frequency through distributor stocking.
Application:
End-use sector determines regulatory exposure and specification complexity. Public infrastructure carries halogen-free mandates; private commercial allows broader material latitude.
- Industrial:Heavy manufacturing and petrochemical facilities demand metal conduit with explosion-proof ratings and grounding continuity. REACH restrictions on halogenated flame retardants are forcing reformulation of PVC compounds for European public infrastructure.
- Telecommunication:5G small cell backhaul and rural broadband initiatives in India under TRAI guidelines are creating demand for microduct conduit bundles.
- Commercial:Office and retail construction balances fire-code compliance with cost optimization across mixed material specifications.
- Residential:Single-family and multi-family housing relies on standardized PVC and metal conduit through builder contractor relationships.
Industrial applications sustain premium pricing through certified hazardous location ratings. Telecommunication infrastructure is climbing fastest as fiber densification accelerates.
End User:
Procurement authority concentrates with entities controlling project scale and specification standards. Large developers bypass traditional distribution; small contractors depend on local electrical supply houses.
- Contractors:Licensed electrical contractors select from stocked inventory for maintenance, renovation, and small-scale new construction. Consolidated procurement by hyperscale data center operators is collapsing the traditional distributor channel for large-diameter metal conduit.
- Electrical Firms:Engineering-procurement-construction firms specify engineered conduit systems for infrastructure and industrial projects under engineer-stamped submittals.
- Manufacturers:Original equipment manufacturers integrate conduit into pre-wired electrical skids and modular assemblies for off-site fabrication.
- Others:Government agencies, utilities, and telecom carriers issue tender-based procurement for transmission and distribution infrastructure.
Contractors generate the highest transaction volume through distributor relationships. Electrical firms control the largest project values through direct specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators in Northern Virginia and Frankfurt now source large-diameter metal conduit through mill-direct procurement, bypassing traditional electrical wholesalers and compressing regional channel structures.
United States
NFPA 70 National Electrical Code revisions mandate upgraded fire-resistance specifications for commercial installations across Texas and Florida construction corridors. Data center clusters in Loudoun County, Virginia command dedicated production lines from major suppliers serving Amazon Web Services and Microsoft Azure campus developments.
China
SAMR-administered GB standards govern cable protection requirements across grid modernization projects in Beijing and Shanghai tier-one cities. Underground distribution network expansion in the Yangtze River Delta absorbs corrugated HDPE conduit for moisture-immune transmission infrastructure.
Germany
REACH restrictions on halogenated flame retardants force PVC compound reformulation for rail and airport projects in Bavaria and North Rhine-Westphalia. ECHA-registered additive packages create certification barriers for imports lacking EU-registered chemistry documentation.
India
TRAI guidelines for 5G small cell backhaul and rural broadband generate microduct conduit bundle demand across Maharashtra and Karnataka telecom corridors. Utility-scale solar developers in Rajasthan specify HDPE for trenchless directional drilling applications.
Australia
Corrugated HDPE conduit displaces rigid alternatives in Queensland and Western Australia renewable energy installations. Directional drilling contractors favor flexibility for navigating rocky substrate without fracture in remote solar farm developments.
Cable Conduit Market Competitive Environment
Player mix skews toward integrated steel and polymer manufacturers with captive raw material positions. Consolidation pressure intensifies as hyperscale procurement concentrates specification authority with fewer end-users. Three archetypes dominate: diversified electrical infrastructure conglomerates, specialized cable management system providers, and regional metal fabrication specialists. Capacity expansion and backward integration into resin and steel coil production represent the primary competitive vectors.
Among North American integrated manufacturers, Atkore International Group Inc. exemplifies the steel-PVC hybrid archetype with cross-material cost control capabilities. European specialists Legrand S.A. and Schneider Electric SE occupy positions within the premium cable management tier, anchoring CE marking compliance expertise under the EU Construction Products Regulation. These three entities represent distinct geographic and structural approaches to specification-driven procurement.
| Leading Market Players |
|---|
| Atkore International Group Inc. |
| Hubbell Incorporated |
| Legrand S.A. |
| Schneider Electric SE |
| ABB Ltd. |
| Eaton Corporation plc |
| HellermannTyton Group PLC |
| Aliaxis Group |
| Electri-Flex Company |
| Others |
Value Chain & Pricing Dynamics
NFPA 70 National Electrical Code revisions in the United States gate both supplier qualification and price differentiation simultaneously, as UL fire-resistance certification becomes mandatory for commercial installations while halogen-free polymer compounds command premium positioning against standard PVC alternatives.
Pricing Analysis
Cost-plus contracts with steel coil indexation dominate large-diameter metal conduit procurement for data center developers, insulating suppliers from scrap metal volatility while compressing margins on non-indexed PVC grades. Price differentiation hinges on UL certification tier and volume scale, with mill-direct hyperscale contracts securing lowest unit costs. Cost compression in standard PVC runs through concentrated resin supply clusters on the US Gulf Coast. Residential electrical contractors exhibit highest price sensitivity, whereas hyperscale data center operators prioritize specification compliance over unit economics.
Supply Chain Analysis
Inventory cycles stretch longest for engineered HDPE conduit bound for underground renewable energy installations, where project-specific bending radius requirements delay standardization. Raw material supply concentrates in the United States, China, and Germany for steel coil, polymer resin, and specialty compounding respectively. The industry draws from galvanized steel scrap, HDPE pellet feedstock, and mineral flame-retardant fillers. Single-source vulnerability clusters around US Gulf Coast resin production exposed to weather disruption. Distribution runs through electrical wholesalers for stocked commodity grades, with direct mill relationships capturing infrastructure project volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat anchored in regulatory entrenchment, where multi-jurisdiction certification requirements under UL, IEC, and GB protocols create switching costs that lock in incumbent positions across decade-long infrastructure procurement cycles.
For Market Incumbents: Secure captive resin and steel coil supply through backward integration into US Gulf Coast polymer production and domestic scrap metal processing. Expand mill-direct certification programs for hyperscale data center operators before channel consolidation accelerates. Metal conduit producers face margin compression from steel input volatility; vertical integration into scrap collection networks mitigates this exposure. For New Entrants and Emerging Players: ECHA-registered additive packages for halogen-free compounds offer fast-track entry into German rail and airport projects where REACH restrictions exclude uncertified imports. Target India's TRAI-guided 5G small cell backhaul corridor for microduct conduit bundles, where specification standards remain fluid and local production capacity lags demand. Partner with directional drilling contractors to demonstrate HDPE flexibility advantages in rocky substrate applications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialty polymer compounding as REACH-compliant additive packages require dedicated R&D infrastructure and extended smoke toxicity validation. Long-term viability favors integrated manufacturers with captive raw material positions and multi-certification portfolios. Monitor hyperscale data center procurement concentration in Northern Virginia and Frankfurt as inflection indicator for distributor channel compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive HDPE supply secures margin control against Gulf Coast weather disruptions. |
| Multi-Jurisdiction Certification Investment | Simultaneous UL, IEC, and GB approval accelerates product launch cycles for global infrastructure. |
| Mill-Direct Channel Development | Bypassing electrical wholesalers captures hyperscale data center specification authority. |
| Halogen-Free Compound R&D | ECHA-registered formulations unlock German public infrastructure procurement eligibility. |
| Modular Pre-Fabrication Partnerships | Pre-bundled conduit assemblies reduce on-site labor for off-site electrical skid manufacturers. |
Study Parameters
Initial hypotheses were tested against primary input from electrical contractor purchasing managers, utility procurement officers, data center construction directors, and polymer compounding technical leads, then refined through secondary validation against SEC filings, customs trade databases, NFPA code revision dockets, and ECHA registration records. Bottom-up demand modeling triangulated with top-down supply capacity assessments across material type and installation method segments.
Variance decomposition across the projection horizon isolates volume drivers by material rigidity, installation complexity, and end-use regulatory exposure. Segmentation dimensions span metal versus polymer composition, underground versus surface deployment, and industrial versus telecommunication application. CAGRs derive from installed base replacement cycles and new construction pipeline analysis, with data center capex trajectories and grid modernization spend curves as industry-specific inputs.
Underlying assumptions cover resin price stability, certification timeline standardization, and hyperscale procurement concentration, with deviation risk concentrated in steel coil volatility and REACH regulatory expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Truck Mounted Loader Cranes Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Belt Scales Market