
 Retractable Lift Market | 2026-2036
Retractable Lift Market Size, Share, and Industry Trends Forecast 2026-2036
Retractable Lift Market Intelligence
The EU Machinery Directive is decoupling retractable lift procurement from basic compliance toward certified safety architecture. Jungheinrich AG leverages its German engineering heritage to dominate premium indoor installation segments. KION Group sustains broad portfolio coverage across hydraulic and electric product types. Toyota Industries Corporation anchors Asia-Pacific supply through captive manufacturing scale.
A retractable lift is a vertically traversing platform system employing telescoping mast assemblies, typically with load capacities from 500 kg to 10,000 kg and lift heights reaching 12 meters, designed to transfer goods or personnel between fixed levels in constrained spatial envelopes. Electric retractable lifts are capturing share from hydraulic alternatives as facility operators prioritize energy efficiency and reduced maintenance intervals. Warehouse applications generate the deepest margin pools due to volume procurement by logistics companies, while entertainment venues represent the fastest-growing application segment driven by temporary staging requirements.
OSHA standards govern worker safety protocols for retractable lift operation in US facilities, while the EU Machinery Directive mandates CE marking and conformity assessment for European market access. China's SAMR enforces GB standards for mechanical safety that shape product design for manufacturers targeting domestic deployment. Stakeholders must monitor evolving energy efficiency regulations and electrification mandates across these jurisdictions to align R&D roadmaps with compliance timelines.
Market Dynamics
Electrification mandates across logistics hubs are compressing the replacement cycle for hydraulic retractable lift fleets, forcing capital deployment toward energy-efficient architectures ahead of regulatory deadlines.
Growth Catalysts
- EU Machinery Directive CE marking:Certified safety architecture is becoming a procurement prerequisite in German distribution centers, elevating compliance spending into a competitive differentiator for qualified suppliers.
- Automated storage and retrieval systems:Warehouse operators in China are integrating retractable lifts with robotic pallet handling, creating synchronized demand for precision positioning capabilities.
- Entertainment staging:Temporary event infrastructure in the United States is driving short-term rental volumes for compact electric units with rapid deployment features.
Market Restraints
- Steel and aluminum input volatility:Telescoping mast fabrication depends on rolled steel pricing that fluctuates with energy costs, compressing margin predictability for mid-tier manufacturers.
- Hydraulic fluid supply concentration:Specialized hydraulic oil formulations concentrate among European chemical suppliers, exposing non-integrated lift producers to input bottlenecks.
- Load capacity ceiling:Electric motor torque limitations restrict heavy-duty applications above 8,000 kg, preserving hydraulic dominance in industrial material handling.
Strategic Opportunities
- India warehouse modernization:Cold chain infrastructure expansion under the PLI scheme is creating first-mover advantage for retractable lift vendors establishing local assembly partnerships.
- 5G-enabled predictive maintenance:Sensor integration with telematics platforms is expanding into fleet-managed logistics contracts, enabling recurring revenue streams beyond equipment sales.
- OSHA silica exposure rules:Indoor air quality mandates in US manufacturing are accelerating electric lift adoption to eliminate hydraulic fluid vapor emissions in enclosed facilities.
Industry Challenges
- Certified technician scarcity:CE marking conformity assessment requires specialized auditors whose availability bottlenecks European market entry timelines for new product lines.
- Legacy warehouse retrofit integration:Older facilities with 3-meter door heights cannot accommodate 12-meter extended mast configurations without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retractable Lift Market |
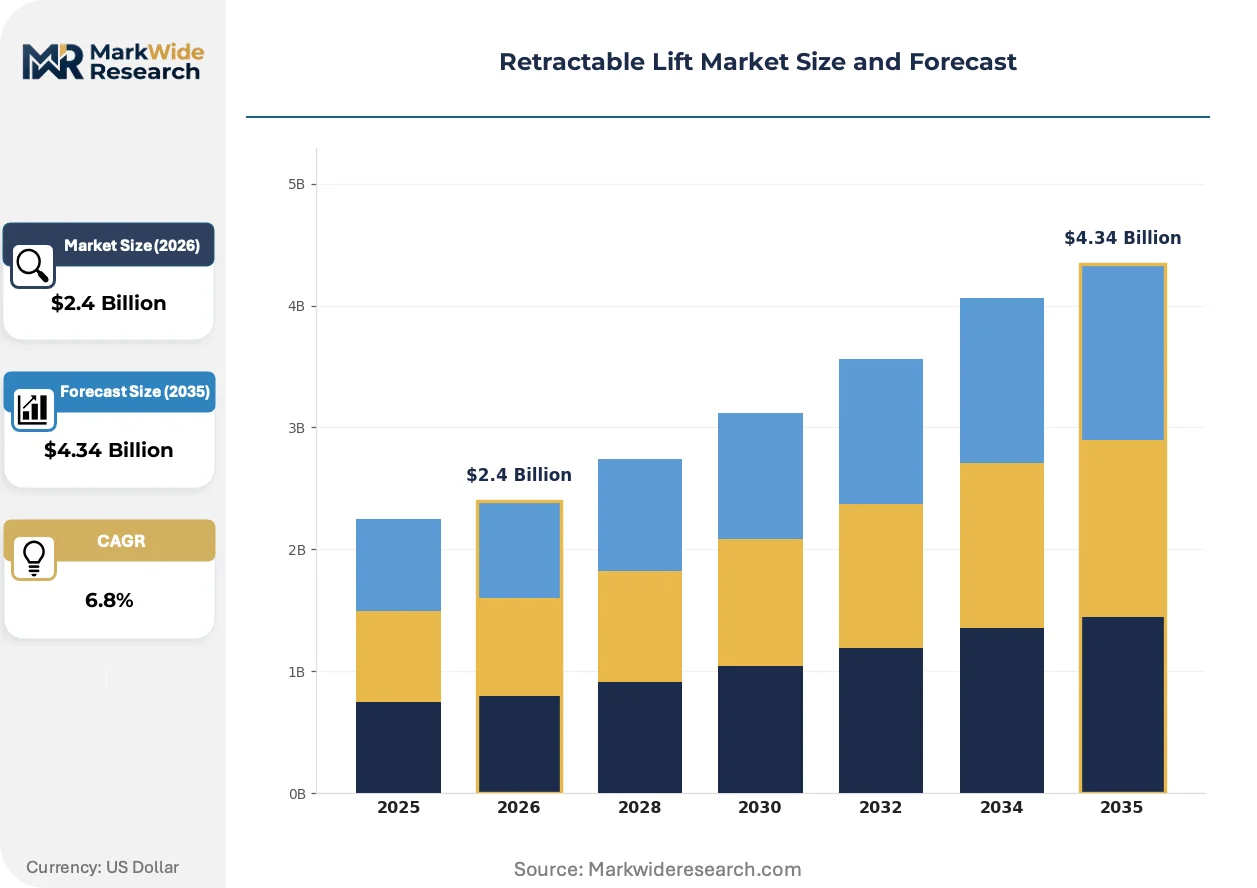
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Retractable Lifts, Electric Retractable Lifts, Pneumatic Retractable Lifts, Mechanical Retractable Lifts Application: Residential Buildings, Commercial Complexes, Warehouses, Parking Facilities, Entertainment Venues Installation Type: Indoor Installations, Outdoor Installations, Above Ground, Below Ground End User: Property Management Firms, Facility Operators, Logistics Companies, Event Management Agencies |
| Companies Covered | Toyota Industries Corporation, KION Group, Jungheinrich AG, Crown Equipment, Mitsubishi Nichiyu Forklift, Hyster-Yale Materials Handling, Anhui Forklift Truck, Doosan Industrial Vehicle, Hangcha Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retractable Lift Market Strategic Shifts & Innovations
Lithium-ion battery architectures are compressing total cost of ownership calculations for electric retractable lifts, redirecting R&D investment away from hydraulic efficiency improvements toward solid-state energy storage.
Brushless DC motor systems with regenerative braking are expanding into high-cycle warehouse applications where duty ratings exceed 20 lifts per hour. Third-party logistics operators in the Netherlands are standardizing on these configurations to qualify for municipal energy rebates. The technology is expanding into rental fleet procurement specifications, compressing residual values for conventional AC motor inventories.
OSHA's updated Powered Industrial Trucks standard is mandating operator visibility enhancements and stability monitoring for new equipment certifications. US distribution centers are retrofitting existing fleets with camera systems and load moment indicators to preempt compliance deadlines. The regulation is reshaping product development roadmaps, with control system integration now consuming 15-20% of engineering hours.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized logistics operators seeking to convert fixed assets into operating expenditures. German automotive suppliers are piloting usage-based pricing tied to actual lift cycles rather than calendar periods. This shift is most visible in the Rhine-Ruhr industrial corridor where facility consolidation has concentrated buyer negotiating power.
Retractable Lift Market Segmentation
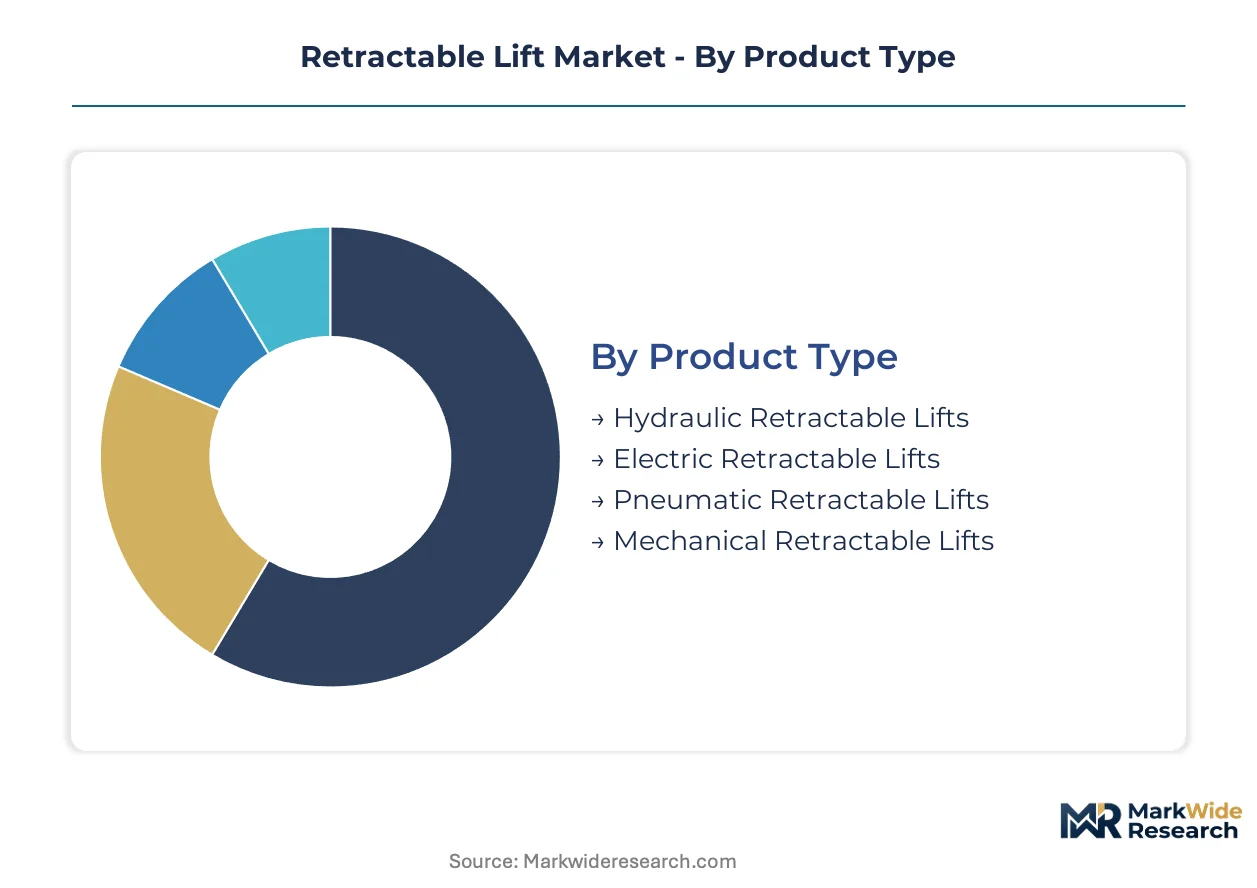
Retractable lift procurement patterns diverge sharply across facility types and power architectures. Understanding these segment boundaries reveals where specification requirements tighten and where commoditization pressures dominate.
Product Type:
Customization intensity spans from fully specified hydraulic systems to standardized electric platforms, with pneumatic and mechanical variants occupying niche positions.
- Electric Retractable Lifts:Brushless DC motor systems with regenerative braking deliver duty cycles exceeding 20 lifts per hour. Dutch third-party logistics operators specify these configurations to qualify for municipal energy rebates, compressing residual values for conventional AC motor inventories.
- Hydraulic Retractable Lifts:Telescoping mast assemblies utilizing specialized fluid formulations achieve load capacities above 8,000 kg where electric torque limits restrict deployment. European chemical suppliers concentrate hydraulic oil production, exposing non-integrated manufacturers to input bottlenecks.
- Pneumatic Retractable Lifts:Compressed air actuation suits explosion-sensitive environments in chemical processing facilities where spark elimination overrides efficiency considerations.
- Mechanical Retractable Lifts:Screw-jack and rack-and-pinion architectures serve low-cycle maintenance applications in municipal infrastructure with minimal power requirements.
Most installed capacity flows through Electric Retractable Lifts. Expansion is steepest in Pneumatic Retractable Lifts.
Application:
Margin structures correlate directly with procurement volume scale and specification complexity across facility categories.
- Warehouses:Automated storage and retrieval system integration demands precision positioning capabilities synchronized with robotic pallet handling. Chinese distribution centers generate the deepest margin pools through volume procurement by logistics companies.
- Entertainment Venues:Temporary staging requirements in the United States drive short-term rental volumes for compact electric units with rapid deployment features.
- Commercial Complexes:Mixed-use developments in German urban centers specify CE-marked safety architecture as a procurement prerequisite, elevating compliance spending into a competitive differentiator.
- Parking Facilities:Below-grade installations in dense metropolitan districts require corrosion-resistant mast coatings and sealed electrical enclosures.
- Residential Buildings:Accessibility retrofits in aging housing stock favor compact footprints with minimal structural modification requirements.
Procurement volumes concentrate in Warehouses. Specification complexity is expanding most quickly in Entertainment Venues.
Installation Type:
Site preparation costs and regulatory pathways diverge substantially between enclosed and exposed mounting configurations.
- Indoor Installations:Jungheinrich AG leverages German engineering heritage to dominate premium segments where OSHA silica exposure rules and EU air quality mandates accelerate electric adoption to eliminate hydraulic fluid vapor emissions.
- Outdoor Installations:Weatherproofing requirements for telescoping mast seals and control enclosure ratings add specification layers absent from climate-controlled environments.
- Above Ground:Standard anchoring and lateral bracing protocols apply across warehouse and commercial applications with established installation contractor networks.
- Below Ground:Pit construction, drainage systems, and confined space entry protocols escalate project complexity in parking and industrial material handling applications.
Contractor capacity concentrates in Above Ground deployments. Project complexity is escalating fastest in Below Ground configurations.
End User:
Capital deployment models and replacement cycle timing vary systematically across buyer organizational types.
- Logistics Companies:Fleet standardization drives procurement of 5G-enabled predictive maintenance platforms with telematics integration, enabling recurring revenue streams beyond equipment sales for vendors.
- Property Management Firms:Equipment-as-a-service contracting displaces capital purchase models among mid-sized operators seeking to convert fixed assets into operating expenditures.
- Facility Operators:German automotive suppliers pilot usage-based pricing tied to actual lift cycles rather than calendar periods, visible in the Rhine-Ruhr industrial corridor where facility consolidation has concentrated buyer negotiating power.
- Event Management Agencies:Rental fleet procurement specifications prioritize rapid deployment features and compact transport dimensions for temporary infrastructure requirements.
Contract value concentrates with Logistics Companies. Payment model innovation is advancing most quickly among Property Management Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering traditions established retractable lift manufacturing standards during post-war industrial reconstruction. Japanese automotive logistics networks refined electric traction architectures for high-cycle warehouse deployment. Chinese state-directed infrastructure investment now drives volume scaling across Asia-Pacific distribution corridors.
Germany
Automotive supplier consolidation in the Rhine-Ruhr corridor sustains premium procurement volumes for CE-marked safety architectures. The EU Machinery Directive mandates conformity assessment procedures that elevate compliance spending into vendor selection criteria. Jungheinrich AG leverages Baden-Württemberg manufacturing heritage to dominate indoor installation segments requiring certified technician networks.
United States
Third-party logistics operators standardize on 5G-enabled predictive maintenance platforms to convert fixed assets into operating expenditures. OSHA's updated Powered Industrial Trucks standard mandates operator visibility enhancements and stability monitoring for new equipment certifications. Distribution centers in the Chicago-Milwaukee corridor retrofit existing fleets with camera systems and load moment indicators ahead of compliance deadlines.
China
SAMR-enforced GB standards for mechanical safety shape product design for manufacturers targeting domestic warehouse automation. State-led cold chain infrastructure expansion under industrial policy directives concentrates demand in Yangtze River Delta logistics hubs. Hangcha Group and Anhui Forklift Truck anchor regional supply through captive manufacturing scale serving robotic pallet handling integration.
Japan
METI energy efficiency guidelines accelerate electric motor adoption in high-cycle applications exceeding twenty lifts per hour. Kanto region automotive parts distribution networks specify brushless DC systems with regenerative braking to qualify for municipal energy rebates. Mitsubishi Nichiyu Forklift occupies the precision-positioning tier for automated storage and retrieval system synchronization.
India
PLI scheme incentives for cold chain infrastructure expansion create first-mover advantage for vendors establishing local assembly partnerships. The country's national industrial safety regulator enforces mechanical equipment standards that elevate certification requirements for imported systems. Maharashtra and Gujarat warehouse modernization projects concentrate procurement volumes for compact electric units with rapid deployment features.
Retractable Lift Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and energy-architecture dimensions. The vendor base organizes into three tiers: German-engineered CE-certified specialists, Japanese-scale electric traction leaders, and Chinese cost-optimized volume fabricators. Strategic moves concentrate on M&A for regional service network expansion and backward integration into lithium-ion battery supply.
Within the premium-certified tier, Jungheinrich AG exemplifies German engineering heritage positioning for indoor safety-critical installations. Toyota Industries Corporation anchors Asia-Pacific supply scale through integrated manufacturing footprints. KION Group occupies the broad-portfolio archetype spanning hydraulic and electric product architectures. These three entities represent distinct competitive vectors: heritage certification, captive scale, and portfolio breadth.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| KION Group |
| Jungheinrich AG |
| Crown Equipment |
| Mitsubishi Nichiyu Forklift |
| Hyster-Yale Materials Handling |
| Anhui Forklift Truck |
| Doosan Industrial Vehicle |
| Hangcha Group |
| Others |
Cost & Logistics Intelligence
Certified technician concentration in Baden-Württemberg and the Rhine-Ruhr corridor amplifies labor-cost spreads between CE-marked premium tiers and uncertified economy offerings. This workforce geography forces procurement officers to weight compliance premiums against retrofit risks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-certified German-engineered systems from mid-tier Asian electric platforms and commodity hydraulic units. Price differentiation hinges on certification grade and after-sales service bundling, with OEMs commanding premiums for technician network coverage. Cost compression in economy tiers is intensifying because Chinese manufacturers are scaling lithium-ion integration without legacy hydraulic R&D overhead. Logistics companies exhibit lowest price sensitivity due to fleet standardization requirements, while event rental agencies prioritize acquisition cost over lifecycle economics.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Chicago, and Shanghai anchor hub-and-spoke patterns for telescoping mast assemblies and control system modules. Manufacturing concentrates in Germany, China, and Japan, with rolled steel and aluminum extrusions drawing from European and East Asian mills. Supply chain risk centers on single-source vulnerability for specialized hydraulic fluid formulations concentrated among European chemical suppliers. Distribution runs through OEM-direct channels for large fleet orders and specialized industrial distributors for fragmented commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Machinery Directive CE marking deadlines are compounding procurement urgency, converting compliance spending from cost center to competitive moat. This regulatory compounder favors prepared vendors and penalizes laggards.
For Market Incumbents: Hedge against electric motor commoditization by deepening backward integration into lithium-ion cell supply and locking long-term service contracts with German automotive suppliers. Defend certification-grade positioning through accelerated CE marking investments ahead of notified body capacity constraints. Threat substitution from Chinese cost-optimized platforms demands channel control reinforcement in European aftermarket service networks.
For New Entrants and Emerging Players: Capture white-space in Indian cold chain warehouse modernization under PLI scheme incentives, where local assembly partnerships unlock tariff-advantaged positioning. Target below-ground parking facility retrofits in dense Japanese and European metropolitan districts, where corrosion-resistant specifications deter commodity competition. Go-to-market leverage rests on rapid-deployment electric units sized for 3-meter door height constraints.
For Investors and Strategic Acquirers: Logistics technology integrators are the most active acquirer in this space, seeking fleet telematics capabilities to bundle with autonomous material handling platforms. Long-term viability favors vendors with captive battery supply and certified technician networks spanning multiple regulatory jurisdictions. Acquisition target archetype: mid-scale electric lift specialists with 5G-enabled predictive maintenance IP and established CE marking pathways. Watch OSHA silica exposure rule enforcement timelines as inflection indicator for electric adoption velocity in US manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium-Ion Supply | Captive battery sourcing insulates margins from raw material volatility in Chinese cell markets. |
| CE Marking Acceleration | Early conformity assessment locks notified body relationships before European auditor scarcity worsens. |
| 5G Telematics Platform Launch | Sensor integration enables recurring revenue streams beyond equipment sales for Dutch logistics operators. |
| Local Assembly Partnership in India | PLI scheme qualification requires domestic manufacturing presence for cold chain infrastructure tenders. |
| Certified Technician Network Expansion | Service density in Rhine-Ruhr corridor defends premium positioning against Asian cost competitors. |
Research Approach
Coverage spans Germany, the United States, China, Japan, and India, with primary inputs from each market. The analysis combines structured interviews with warehouse operations directors, OEM procurement teams, aftermarket service heads, and regulatory compliance officers with secondary validation. Secondary sources include OSHA enforcement databases, EU Machinery Directive notified body registers, SAMR GB standard filings, and customs trade records for telescoping mast component flows. Bottom-up installation data triangulates against top-down logistics infrastructure investment tracking.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation across power architecture, installation type, application vertical, and end-user capital deployment model. CAGRs derive from logistic curve fitting to warehouse automation adoption patterns and electrification mandate compliance timelines. Industry-specific forecast inputs include robotic pallet handling integration rates and municipal energy rebate program expansions.
Steel and aluminum input volatility, hydraulic fluid supply concentration, and certified technician scarcity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory enforcement pacing and logistics capital expenditure continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Global Conveyor System Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Industrial Mezzanines Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Stacker Market