
 Compact Loaders Market | 2026-2036
Compact Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Loaders Market Analysis
Skilled equipment operator availability is collapsing across North American and European construction zones, forcing contractors toward compact loaders with simplified controls and telematics-assisted operation. Caterpillar Inc. leverages its dealer network density to sustain aftermarket parts revenue and operator training programs. Deere & Company anchors its position through backward integration into precision agriculture attachments that extend loader utility across planting and harvest cycles. Komatsu Ltd. differentiates via its Smart Construction telematics platform, which competes on fleet uptime metrics rather than upfront equipment pricing.
Compact loaders are self-propelled, engine-powered machines with rated operating capacities typically spanning 500 kg to 4,000 kg, utilizing rigid or articulated frames with either wheeled or tracked undercarriages to perform material lifting, digging, and loading tasks in confined work envelopes. Skid steer loaders dominate rental fleet composition due to their universal quick-attach systems, while compact track loaders command premium positioning where soil disturbance restrictions apply on landscaping and residential sites. Electric drive variants currently occupy a niche in indoor demolition and material handling applications, though battery energy density constraints limit run-time for dirt moving cycles.
EPA Tier 4 Final regulations in the United States and EU Stage V standards enforced by ECHA member authorities mandate diesel particulate filter and selective catalytic reduction integration, adding cost and engineering complexity to compact loader powertrains. OSHA excavation safety directives and ISO 14397 load rating standards shape operator protection structure design and market access certification requirements across jurisdictions. Stakeholders must monitor battery-electric platform maturity and attachment interoperability standards as these factors will determine fleet replacement timing and residual value calculations.
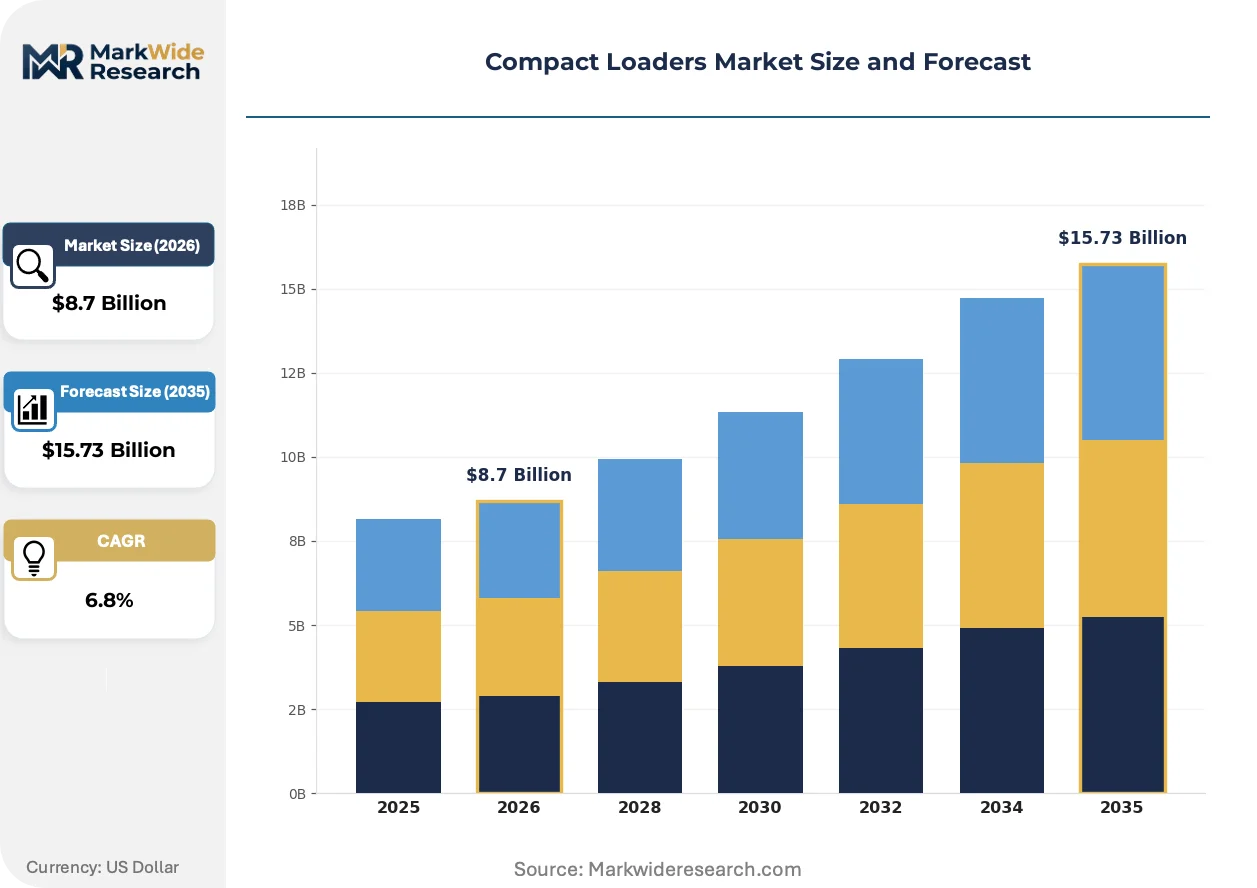
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are compressing diesel engine supplier margins while accelerating electric powertrain development timelines across compact loader manufacturing bases.
Growth Catalysts
- Urban green space expansion:Municipal infrastructure crews in Sun Belt states are scaling compact loader fleets to maintain utility corridors and park systems, creating sustained equipment demand.
- Telematics integration:Fleet uptime monitoring platforms are reducing unplanned downtime for construction contractors, justifying premium positioning for connected machines.
- OSHA excavation safety directives:Stricter operator protection requirements are shortening equipment replacement cycles as older machines fail certification standards.
Market Restraints
- Battery energy density constraints:Lithium-ion cell chemistry limitations restrict electric compact loader run-time to 4-6 hours for dirt-moving cycles, confining adoption to indoor demolition.
- Steel and hydraulic component volatility:Input cost swings for high-strength alloys and precision pumps compress OEM margins during contract-heavy bidding seasons.
- Skilled operator scarcity:North American construction zones face collapsing availability of certified equipment operators, capping fleet utilization rates regardless of machine availability.
Strategic Opportunities
- Attachment interoperability standards:Universal quick-attach systems are opening aftermarket revenue streams for precision agriculture and specialty construction tools.
- Residential landscaping electrification:Noise-sensitive subdivisions in California and Florida are creating first-mover advantage for battery-electric compact track loader deployments.
- IRA clean equipment incentives:US federal tax credits for zero-emission commercial vehicles are improving total cost of ownership calculations for electric fleet conversions.
Industry Challenges
- ISO 14397 load rating certification timelines:Third-party verification bottlenecks are delaying new model launches by 8-14 months, compressing revenue recognition windows.
- Legacy fleet telematics integration:Contractors with mixed-age equipment face data standardization gaps when merging older machines into unified fleet management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Loaders Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skid Steer Loaders, Compact Track Loaders, Wheel Loaders, Mini Loaders End User: Construction, Agriculture, Landscaping, Forestry Technology: Hydraulic Drive, Electric Drive, Diesel Engine, Hybrid Application: Dirt Moving, Material Handling, Site Preparation, Demolition |
| Companies Covered | Caterpillar Inc., CNH Industrial N.V., Deere & Company, Doosan Bobcat, Komatsu Ltd., Kubota Corporation, Volvo Construction Equipment, Hitachi Construction Machinery Co. Ltd., JCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Loaders Market Emerging Trajectories
Electrification architectures and autonomous operation assistance are rewriting equipment specification criteria, with buyers prioritizing connectivity over horsepower ratings in procurement decisions.
Telematics-enabled predictive maintenance is supplanting scheduled service intervals as the dominant fleet management protocol. Large landscaping contractors in Texas and Arizona are adopting uptime-guarantee contracts that penalize dealers for unplanned downtime. This shift is compressing aftermarket parts pricing power and forcing distributors to carry higher inventory buffers for critical hydraulic components.
EU Stage V standards enforced by ECHA member authorities are mandating diesel particulate filter and selective catalytic reduction integration across all imported compact loaders. The engineering complexity has eliminated smaller engine suppliers from the certification race, concentrating powertrain sourcing among three European and Japanese manufacturers. Compact track loader segments face the steepest cost pass-through challenges due to higher engine displacement requirements.
Equipment-as-a-service contracting is fragmenting traditional dealer financing relationships. Mid-sized construction firms in Colorado and Georgia are leasing machines with bundled maintenance and telematics subscriptions rather than capitalizing purchases. This model shifts residual value risk to OEM captive finance arms and accelerates replacement cycles as lessees rotate into newer models at contract renewal.
Compact Loaders Market Segmentation
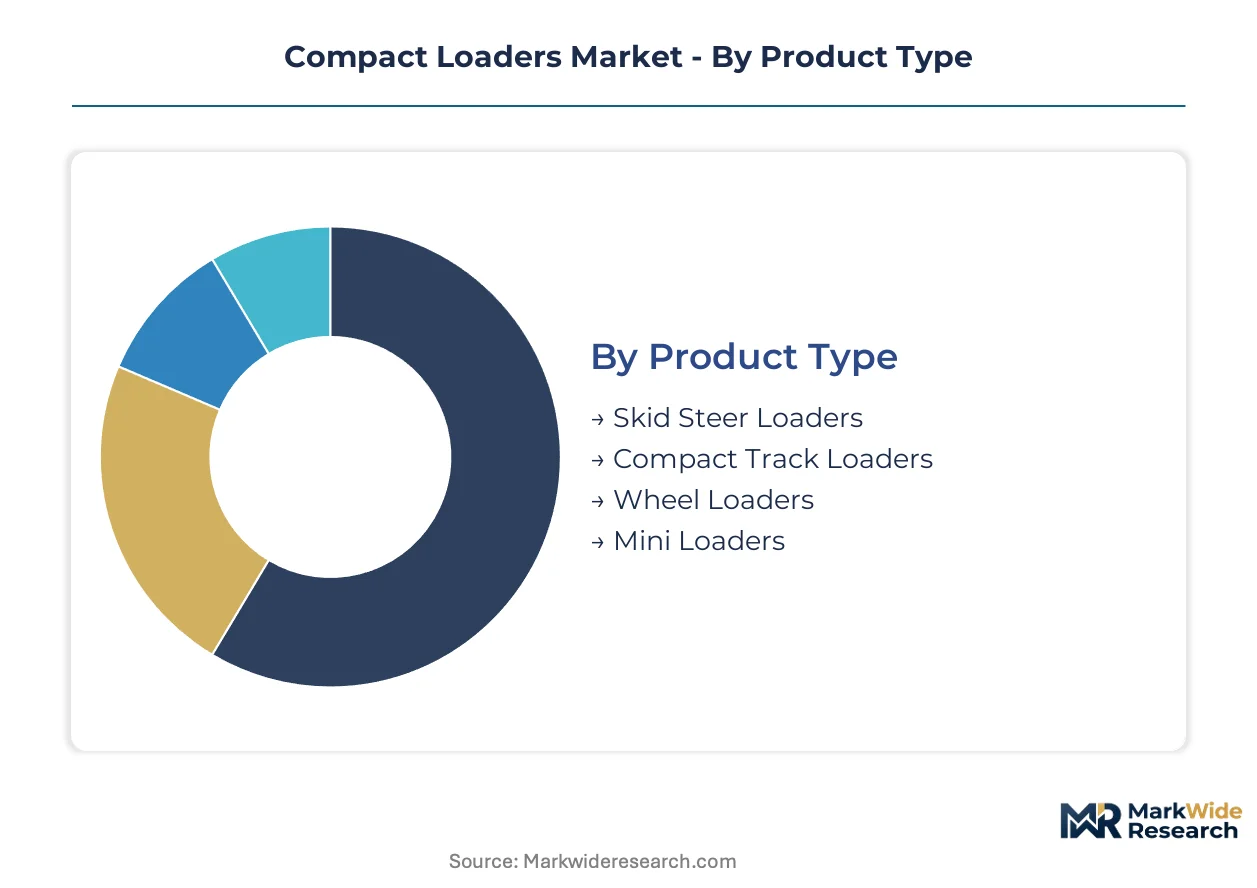
Compact loader procurement patterns diverge sharply across product architectures and powertrain technologies, with fleet managers calibrating specifications to soil conditions, emission zones, and duty cycle intensity. Understanding segment boundaries clarifies where pricing power concentrates and which configurations face substitution risk from electrification.
Product Type:
Skid steer loaders dominate domestic rental fleet composition across the United States, while compact track loaders command premium export positioning into European landscaping markets where surface preservation regulations apply.
- Skid Steer Loaders:Rigid-frame machines with universal quick-attach systems enabling rapid tool changes. Demand concentrates in Texas and Arizona equipment rental yards where contractors prioritize versatility over terrain flotation; OSHA operator protection mandates are accelerating fleet turnover.
- Compact Track Loaders:Rubber-tracked undercarriages distribute ground pressure below 4 psi for sensitive residential sites. European Union demand, particularly in Germany and France, is climbing fastest where EU Stage V emission zones restrict wheeled equipment on greenfield developments.
- Wheel Loaders:Articulated steering configurations suited for hard-surface material yards. Municipal fleets in Florida and California specify these for urban utility corridor maintenance.
- Mini Loaders:Sub-1,000 kg operating capacity units for confined indoor demolition. Battery-electric variants from Italian and Japanese manufacturers are penetrating noise-restricted European city centers.
Skid steer loaders hold the largest share; momentum sits with compact track loaders.
End User:
Cost tier stratification separates capital-intensive construction purchasing from seasonal agriculture leasing patterns, with landscaping contractors occupying a hybrid procurement middle ground.
- Construction:General contractors and specialty trades operating on bonded public infrastructure projects. Sun Belt states including Georgia and Colorado are scaling compact loader fleets for highway interchange and commercial pad development; uptime-guarantee contracts are compressing dealer margins.
- Agriculture:Precision farming operations integrating loaders into planting and harvest workflows. Midwest grain operations in Iowa and Illinois specify high-lift configurations for bin loading; attachment interoperability with existing tractor fleets drives specification decisions.
- Landscaping:Residential and commercial grounds maintenance contractors. California noise ordinances and Florida water management districts are creating regulatory segmentation between combustion and electric fleet zones.
- Forestry:Timber harvesting and biomass collection applications. Pacific Northwest operations in Oregon and Washington demand reinforced guarding for brush and debris impact protection.
Construction commands the highest absolute volume; landscaping is expanding most quickly.
Technology:
Application intensity determines powertrain selection, with dirt-moving cycles favoring diesel torque density and indoor material handling accepting battery-electric runtime constraints.
- Hydraulic Drive:Hydrostatic transmissions delivering variable speed control without mechanical gearboxes. Rental fleets in Pennsylvania and Ohio favor these for operator simplicity and reduced training burden amid skilled labor scarcity.
- Electric Drive:Battery-powered architectures with 4-6 hour runtime for light-duty cycles. Indoor demolition contractors in New York and Massachusetts are adopting these where EPA indoor air quality regulations restrict diesel particulate exposure.
- Diesel Engine:Compression-ignition powertrains with EPA Tier 4 Final aftertreatment. Heavy earthmoving contractors in Nevada and Utah specify these for high-torque dirt moving where battery energy density remains inadequate.
- Hybrid:Diesel-electric architectures capturing regenerative braking energy. European municipal fleets in Sweden and Norway are piloting these for emission-reduction compliance without full electrification range sacrifice.
Diesel engine configurations retain dominant share; electric drive is gaining share fastest.
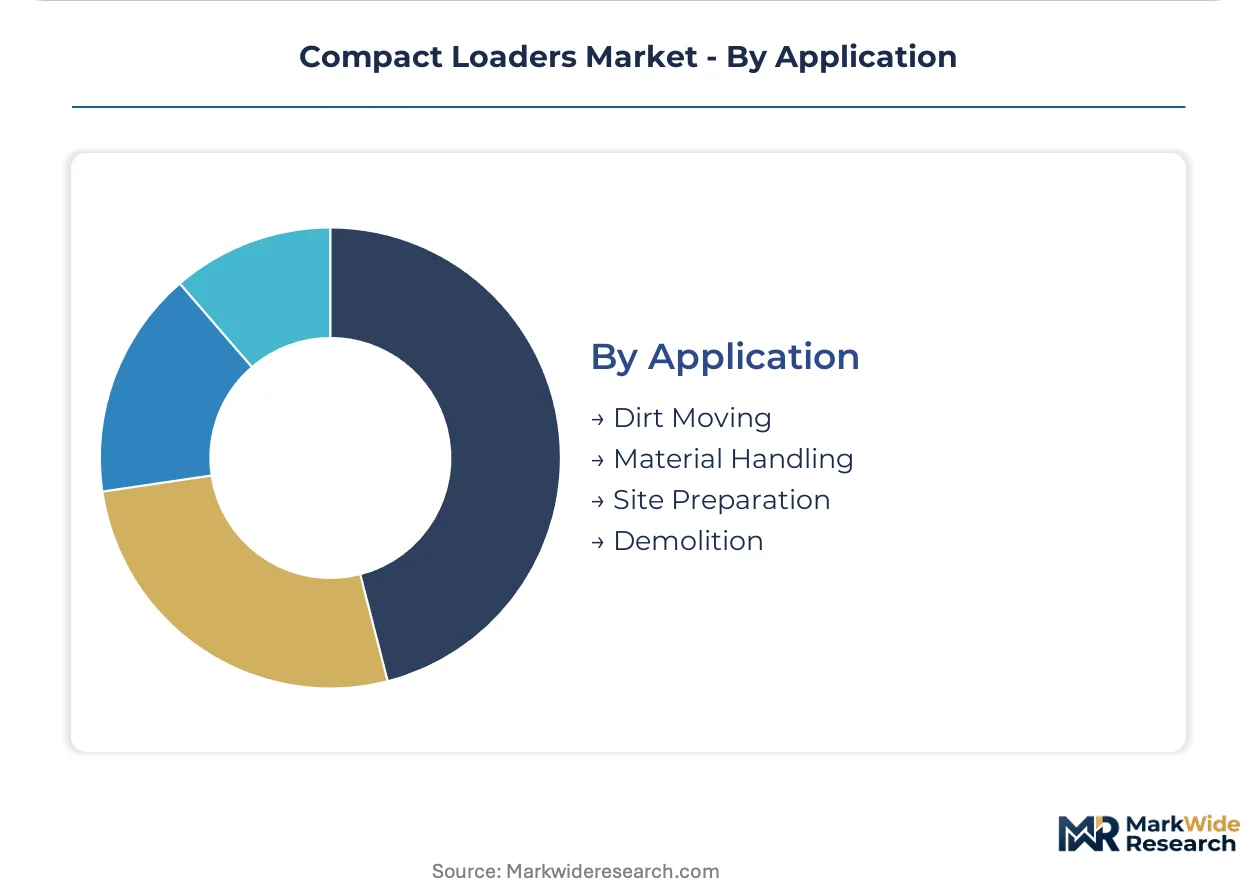
Application:
Volume concentration in dirt moving supports standardized fleet specifications, while demolition and site preparation create attachment-driven customization opportunities.
- Dirt Moving:Bulk earthwork operations including grading, trenching, and backfilling. Residential developers in Arizona and Texas specify high-flow hydraulic packages for soil conditioning attachments.
- Material Handling:Palletized load transport and stockpile management. Distribution centers in Illinois and Ohio are deploying electric compact loaders for indoor warehouse aisle navigation.
- Site Preparation:Land clearing, rough grading, and erosion control installation. Florida stormwater management contractors utilize these for retention basin construction.
- Demolition:Structural dismantling and debris sorting in confined spaces. California indoor renovation specialists specify reduced-tail-swing configurations for building interior work.
Dirt moving holds the largest share; material handling is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Sun Belt states in the United States prioritize diesel-powered fleet expansion for residential construction velocity, while European municipalities accelerate electrification pilots under emission zone mandates. Asian markets emphasize cost-efficient hydraulic architectures for infrastructure build-outs.
United States
Municipal infrastructure crews in Texas and Arizona are scaling compact loader fleets for utility corridor maintenance and park system management. EPA Tier 4 Final regulations mandate diesel particulate filter integration across all imported equipment, compressing supplier margins. Equipment rental yards in Houston and Phoenix report highest skid steer utilization rates amid skilled operator scarcity.
Germany
Landscaping contractors in Bavaria and Baden-Württemberg specify compact track loaders for surface-sensitive residential developments. EU Stage V standards enforced by ECHA member authorities require selective catalytic reduction systems, eliminating smaller engine suppliers from certification. Stuttgart-based municipal fleets pilot hybrid diesel-electric architectures for emission-reduction compliance.
China
Construction firms in Yangtze River Delta provinces deploy wheel loaders for urban utility corridor maintenance and material yard operations. GB standards and dual carbon goals issued by MEE accelerate battery-electric platform development timelines. Shanghai equipment manufacturers concentrate production of cost-optimized hydraulic drive units for domestic infrastructure projects.
Japan
Precision agriculture operations in Hokkaido and Tohoku integrate compact loaders into grain handling and livestock workflows. METI energy efficiency directives shape powertrain specification criteria for domestic manufacturers. Osaka-based equipment distributors emphasize attachment interoperability with existing tractor fleets.
India
Road construction contractors in Maharashtra and Gujarat specify compact loaders for highway interchange development and commercial site preparation. BIS certification requirements and PLI scheme incentives for domestic manufacturing reshape procurement patterns. Mumbai equipment leasing firms report climbing demand from mid-sized construction firms adopting equipment-as-a-service contracting models.
Compact Loaders Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier commands captive finance arms and dense dealer networks that sustain aftermarket revenue streams. Three archetypes dominate: diversified industrial conglomerates with construction equipment divisions, dedicated agricultural machinery specialists backward integrated into precision attachments, and pure-play compact equipment manufacturers competing on fleet uptime metrics. Strategic moves concentrate on telematics platform integration and attachment interoperability standard-setting.
Within the diversified industrial tier, Caterpillar Inc. and Deere & Company exemplify integrated leaders leveraging dense distribution infrastructure. Komatsu Ltd. occupies a position emphasizing connected fleet management platforms over equipment pricing. Among specialized compact equipment fabricators, Doosan Bobcat and Kubota Corporation represent mid-scale specialists with concentrated regional positioning. Volvo Construction Equipment anchors European premium-tier positioning through emission-compliant powertrain engineering. JCB and Hitachi Construction Machinery Co. Ltd. sit within the diversified construction machinery archetype with broad product portfolio coverage. CNH Industrial N.V. exemplifies agricultural-industrial hybrid structures with cross-cycle equipment utility.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| CNH Industrial N.V. |
| Deere & Company |
| Doosan Bobcat |
| Komatsu Ltd. |
| Kubota Corporation |
| Volvo Construction Equipment |
| Hitachi Construction Machinery Co. Ltd. |
| JCB |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final certification gates both supplier qualification and price differentiation simultaneously, concentrating powertrain sourcing among three European and Japanese manufacturers while forcing tiered pricing based on emission compliance tier rather than mechanical performance alone. OEMs pass through selective catalytic reduction and diesel particulate filter costs unevenly across product lines, with compact track loaders bearing steepest premiums due to higher engine displacement requirements.
Pricing Analysis
Long-term offtake contracts dominate municipal fleet procurement in Texas and Arizona, while spot-market transactions prevail in equipment rental yards where utilization volatility compresses pricing power. Three-tier pricing structure across premium, standard, and economy levels separates EU Stage V-compliant machines from Tier 4 Final units and pre-certified legacy inventory. Cost compression in standard-tier configurations is intensifying because steel and hydraulic component volatility squeezes OEM margins during contract-heavy bidding seasons. Landscaping contractors in California noise-restricted zones show least price sensitivity for battery-electric variants, while Midwest agricultural operations drive hardest bargains on attachment bundles.
Supply Chain Analysis
Strategic stockpiling of high-strength alloy plate and precision hydraulic pumps characterizes OEM procurement strategies, buffering against contract-season input cost spikes. Manufacturing concentrates in Japan, Germany, and the United States for engine and drivetrain components, with final assembly distributed across Mexico, China, and India for cost-optimized units. Supply chains draw from South Korean battery cell suppliers for electric architectures and Swedish specialty steel mills for chassis fabrication. Single-source vulnerability sits with selective catalytic reduction catalyst substrates from limited European foundries. Distribution runs through captive dealer networks for aftermarket parts revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards operators who control scarce telematics engineering talent and dense service infrastructure, not merely manufacturing scale. Fleet uptime guarantee contracting is displacing traditional equipment financing relationships and concentrating margin capture among integrated OEMs.
For Market Incumbents: Shield aftermarket revenue streams by deepening captive parts distribution networks before independent telematics platforms disintermediate dealer relationships. Prioritize backward integration into hydraulic component manufacturing to offset steel alloy volatility compressing margins on standard-tier machines. Invest in ISO 14397 certification pre-approval programs to compress new model launch timelines against emerging competitors. For New Entrants and Emerging Players: Differentiate on attachment interoperability standards to penetrate the precision agriculture segment where Deere and CNH Industrial face regulatory friction integrating third-party tools. Target California and Florida residential landscaping zones with battery-electric compact track loaders where noise ordinances create protected demand pockets. Pursue equipment-as-a-service contracting models to bypass incumbent dealer financing relationships and accelerate fleet rotation cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric platform development as cell chemistry R&D and thermal management engineering consume disproportionate resources versus diesel powertrain refinement. Viable acquisition targets include mid-scale specialists with concentrated regional positioning and proven telematics platform integration. Watch EPA indoor air quality enforcement thresholds as the inflection signal determining electric fleet conversion acceleration versus diesel replacement extension.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Komatsu's Smart Construction platform demonstrates fleet uptime metrics commanding premium positioning over upfront equipment pricing. |
| Attachment Interoperability Standard-Setting | Universal quick-attach systems open aftermarket revenue streams for precision agriculture tools across planting and harvest cycles. |
| Battery-Electric Platform Development | Shanghai manufacturers concentrate cost-optimized hydraulic drive units while European pilots test hybrid architectures for emission compliance. |
| Equipment-as-a-Service Contracting | Mid-sized Colorado and Georgia construction firms lease machines with bundled maintenance, shifting residual value risk to OEM captive finance arms. |
| Dealer Network Densification | Caterpillar leverages distribution infrastructure to sustain aftermarket parts revenue and operator training programs amid skilled labor scarcity. |
Methodological Framework
Desk research of customs trade databases, SEC equipment manufacturer filings, and municipal procurement records preceded structured interviews with fleet maintenance directors, OEM procurement teams, aftermarket service heads, and landscaping contractor operations managers. Primary fieldwork combined telephone and video interviews with secondary validation against equipment registration databases and rental fleet utilization surveys. Bottom-up unit shipment estimates triangulated against top-down construction spending allocation models across the analysis window.
Variance decomposition across product type, powertrain technology, end-use sector, and regional regulatory cluster shaped the analytical framework. CAGRs derived from logistic diffusion curves for electric powertrain adoption spliced with replacement cycle elasticity estimates for diesel fleets. Modeled inputs included attachment shipment ratios, telematics penetration rates, and municipal infrastructure budget allocations by state.
The analysis sits within stated boundaries; outcomes outside sustained EPA Tier 4 Final enforcement and current battery energy density constraints would require recalibration. Forecasts reflect assumptions regarding skilled operator scarcity persistence and steel alloy price volatility within historical bands. Revision becomes warranted when IRA clean equipment incentive thresholds cross uptake acceleration points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Cold Planers Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Amphibious Excavator Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Part Feeder Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market