
 Rubble Sacks Market | 2026-2036
Rubble Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Rubble Sacks Market Analytics
Builders merchant channels is rewriting procurement patterns for site consumables across the United Kingdom. Elite Plastics leverages direct-to-contractor digital platforms to bypass traditional distribution markups. Leedan Packaging Ltd anchors its position through specialty store partnerships with national hardware chains. Centurion Industrial Packaging competes on manufacturing scale, operating high-throughput extrusion lines that service wholesale distributor networks across northern England.
Rubble sacks are woven or extruded containment vessels, typically fabricated from polypropylene tapes with load ratings between 25 kg and 50 kg, designed for the collection, transport, and disposal of construction debris, soil, and demolition waste. Heavy-duty polypropylene variants dominate commercial volumes due to tear resistance and reusability on commercial building sites. Lightweight sacks serve landscaping end users where transport costs and manual handling constraints favor reduced material gauges. Waterproof PVC formulations command premium positioning in environmental services applications involving wet spoil or contaminated runoff containment.
UK Construction Products Regulation and EU REACH compliance frameworks govern chemical content in woven polypropylene substrates, while EPA landfill diversion rules in the United States shape demand for durable multi-use containment. BIS certification requirements in India restrict import of non-standard load-rated products, creating protected market access for domestic converters. Stakeholders must monitor evolving extended producer responsibility schemes that will determine whether single-use or returnable sack formats capture regulatory preference.
Market Dynamics
EU Construction Products Regulation mandates now force specification-grade containment for hazardous demolition debris, compressing demand toward certified woven polypropylene formats and away from commodity alternatives.
Growth Catalysts
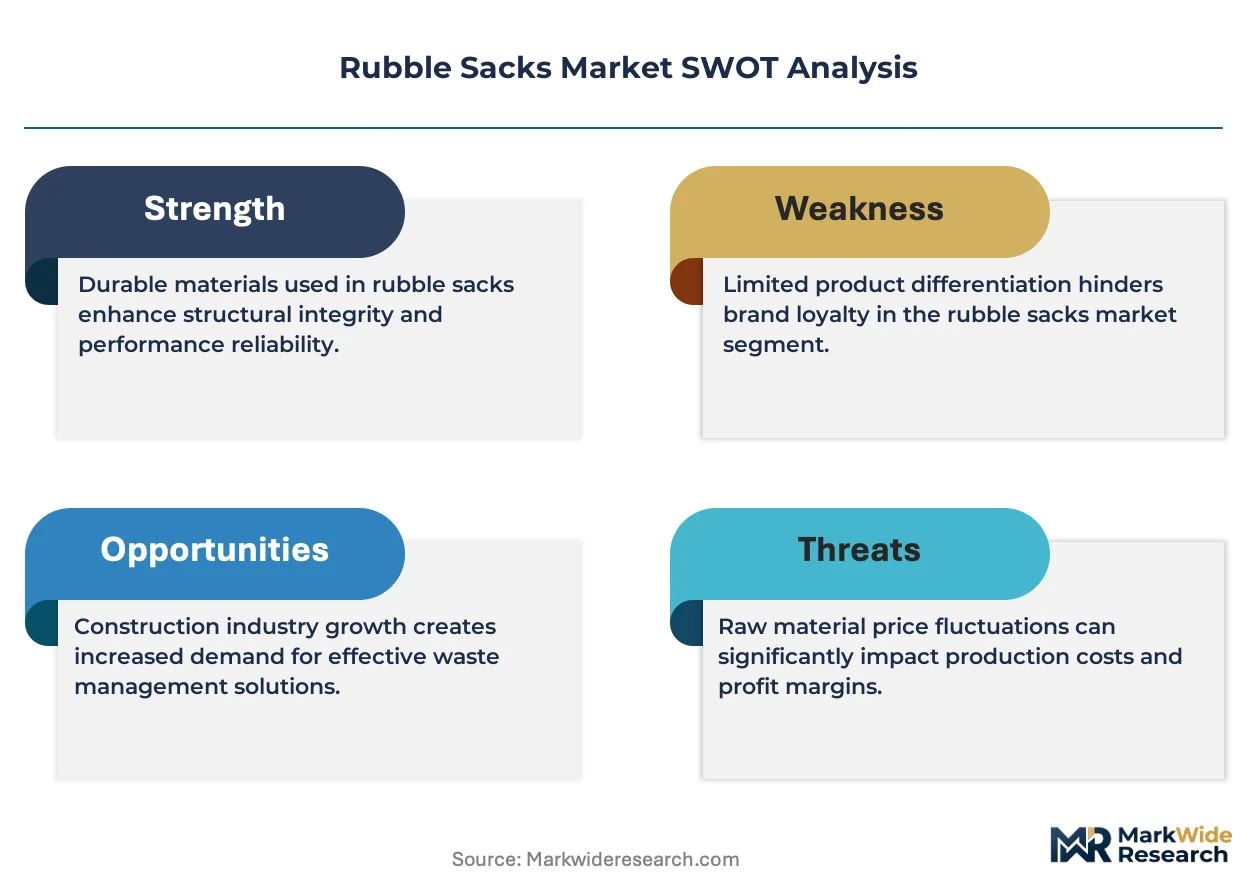
- REACH chemical compliance:European ECHA substance restrictions on heavy metals in woven substrates accelerate certified sack substitution for unregulated imports.
- Infrastructure renewal clusters:Germany's Ruhr corridor generates concentrated bulk demand for 50 kg load-rated containment during deindustrialization site remediation.
- Multi-shift reusability:Heavy-duty polypropylene tear resistance enables five-to-ten use cycles on commercial building sites, reducing per-tonne containment cost.
Market Restraints
- Propylene feedstock volatility:Crude-linked polypropylene resin costs swing 15-30% quarterly, squeezing converter margin on fixed-price municipal contracts.
- Chinese extrusion overcapacity:Zhejiang and Shandong province low-cost woven bag exports flood spot markets, compressing regional pricing power.
- Biodegradable starch substitutes:Compostable bag formats for non-hazardous landscaping spoil threaten lightweight polypropylene volume in garden center channels.
Strategic Opportunities
- India BIS certification gap:Domestic converter capacity shortfalls against mandatory load-rating standards create protected market access for compliant regional producers.
- Environmental services wet containment:Waterproof PVC formulations for contaminated runoff capture command premium positioning in remediation contracting.
- Direct-to-contractor digital platforms:Bypassing builders merchant markups via site-delivered bulk ordering captures margin from fragmented UK construction procurement.
Industry Challenges
- Extended producer responsibility uncertainty:Pending EU packaging waste directives create investment paralysis over single-use versus returnable format commitment.
- Extrusion line reconfiguration capex:Shifting between 25 kg lightweight and 50 kg heavy-duty gauge production requires die and loom changeover downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubble Sacks Market |
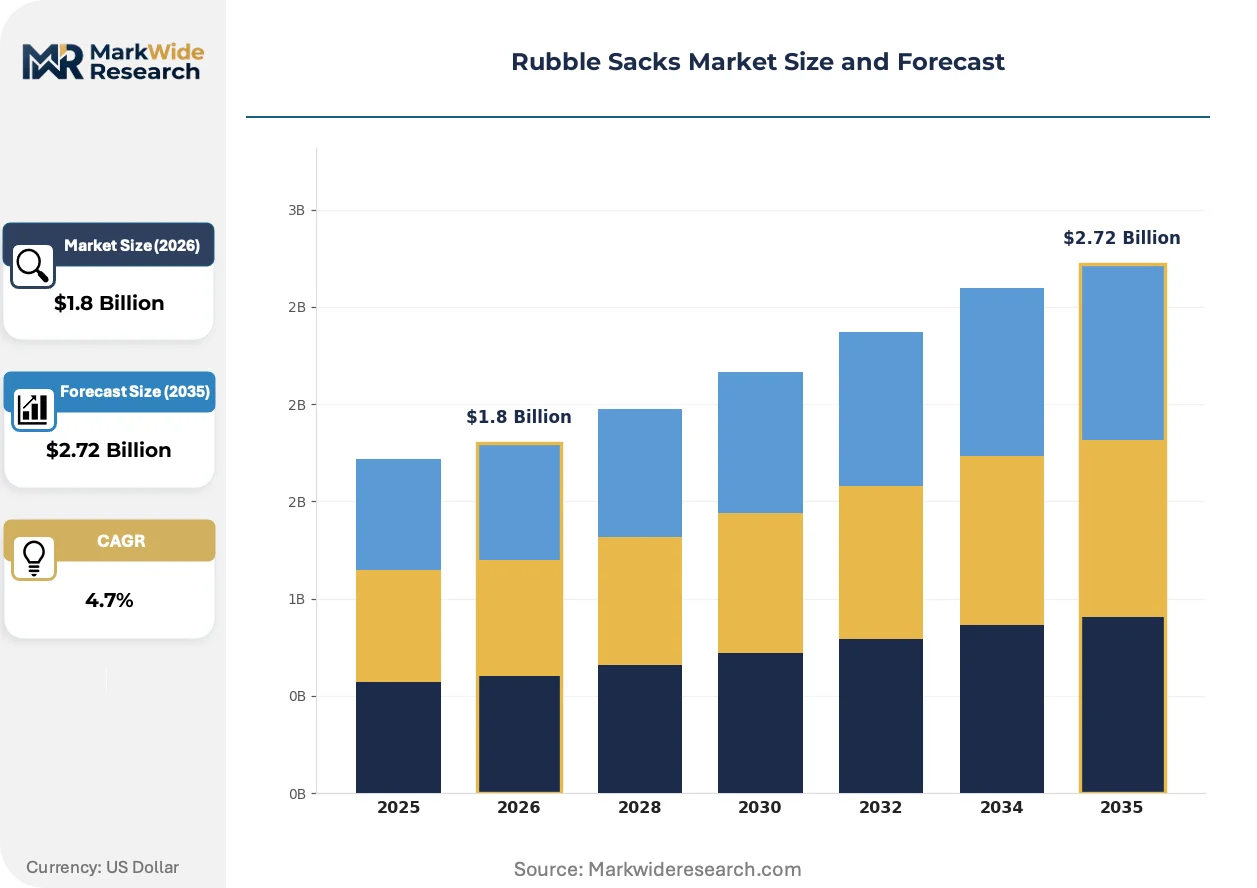
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Sacks, Lightweight Sacks, Waterproof Sacks, Biohazard Sacks Material: Polypropylene, Burlap, Jute, PVC End User: Construction Industry, Landscaping, Environmental Services, Waste Management Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Elite Plastics, Leedan Packaging Ltd, Centurion Industrial Packaging, Proguard, HIPPO, NDC Polipak, Wickes, Faithfull Tools, Polaris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubble Sacks Market Evolving Landscape
Material science advances and regulatory precision are compressing product lifecycles while digital procurement platforms restructure traditional distribution hierarchies in construction consumables.
Co-extruded multilayer barrier films with embedded RFID traceability tags are rendering obsolete manual batch-tracking systems for hazardous waste chain-of-custody documentation. Major remediation contractors in the Netherlands and Belgium now specify chip-enabled sacks for asbestos-containing debris. The technology is rendering obsolete third-party audit dependencies by embedding compliance verification directly into containment substrate.
EPA landfill diversion rules in the United States now mandate 75% construction debris recovery rates in designated metropolitan zones, forcing general contractors toward durable multi-use sack formats. Heavy-duty polypropylene specifications dominate federal infrastructure bidding documents. Municipal waste authorities in California and New York are responding with preferred vendor lists that exclude single-use polyethylene alternatives.
Site managers now bundle containment procurement with waste haulage services, unbundling the traditional separation between sack supply and debris removal. Integrated service contracts consolidate vendor relationships for mid-sized commercial developers. The United Kingdom exhibits the most visible compression of standalone product purchasing, with national housebuilders consolidating site consumables under single-source facilities management agreements.
Rubble Sacks Market Segmentation
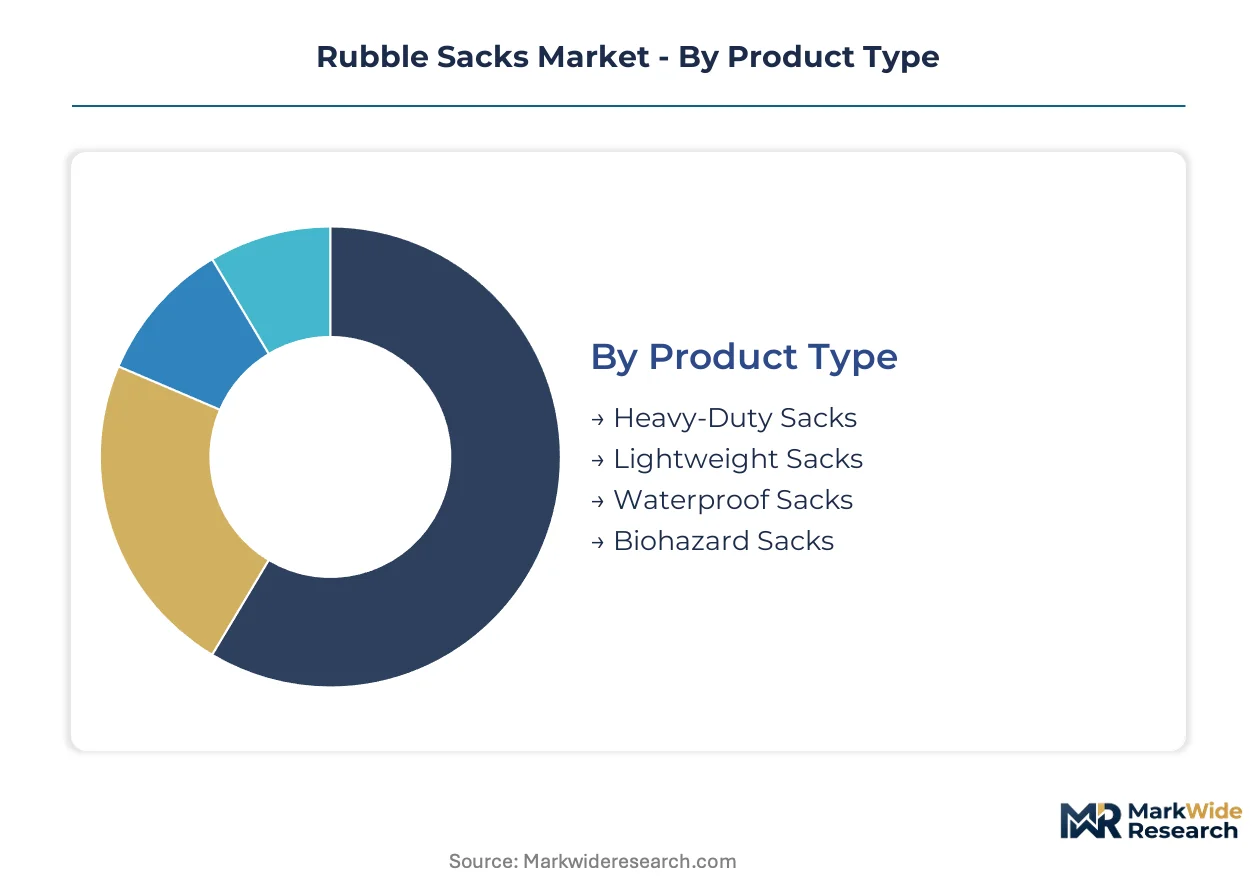
Segmentation in the rubble sacks market exposes sharp divergences in material specifications, load ratings, and procurement channels that separate commodity bulk buyers from premium specification purchasers. Understanding these fault lines enables targeted positioning against the regulatory compliance tiers and reuse-cycle economics that now govern contractor purchasing decisions.
Product Type:
Cost tier differentiation separates single-use disposable formats from premium multi-cycle containment systems with embedded compliance documentation.
- Heavy-Duty Sacks:Woven polypropylene tapes rated for 50 kg loads with reinforced hem stitching and UV stabilizers for outdoor exposure. Demand concentrates in Germany's Ruhr corridor infrastructure renewal projects where five-to-ten use cycles reduce per-tonne containment costs under municipal deindustrialization contracts.
- Lightweight Sacks:Reduced-gauge extruded polypropylene rated for 25 kg loads prioritizing manual handling ergonomics and transport cube efficiency. Landscaping contractors in the United Kingdom favor these formats for garden spoil collection where labor costs exceed material durability concerns.
- Waterproof Sacks:PVC-coated or co-extruded barrier films for wet spoil and contaminated runoff containment.
- Biohazard Sacks:Color-coded certified formats with chain-of-custody documentation for asbestos and hazardous demolition debris.
Heavy-Duty Sacks commands the established base. The steepest expansion runs through Waterproof Sacks.
Material:
Application requirements dictate substrate selection between synthetic durability and natural fiber biodegradability.
- Polypropylene:Dominant commercial substrate utilizing tape extrusion and circular loom weaving for tear-resistant containment. REACH chemical compliance mandates from ECHA now restrict heavy metal content in European-sourced tapes, accelerating certified domestic substitution for unregulated imports.
- PVC:Calendered or plastisol-coated formulations delivering impermeable barriers for environmental services wet containment applications. Remediation contractors in Belgium and the Netherlands specify these for contaminated site dewatering operations.
- Burlap:Natural jute fiber weave for erosion control and biodegradable landscaping applications.
- Jute:Unprocessed bast fiber format for agricultural and heritage restoration projects requiring compostable disposal pathways.
Polypropylene holds volume leadership across commercial construction. PVC climbs fastest on environmental remediation specification growth.
End User:
Customer type determines performance specifications, compliance documentation requirements, and procurement relationship structures.
- Construction Industry:General contractors and specialist demolition firms requiring load-rated certification for hazardous debris containment. EPA landfill diversion rules in the United States now mandate durable multi-use formats for federal infrastructure bidding eligibility.
- Environmental Services:Remediation specialists managing contaminated soil, asbestos, and industrial runoff with embedded RFID traceability requirements. Dutch and Belgian contractors now specify chip-enabled sacks for hazardous waste chain-of-custody automation.
- Landscaping:Residential and commercial garden maintenance operations prioritizing lightweight manual handling and cost disposal.
- Waste Management:Municipal authorities and private haulage firms integrating containment supply with debris removal service bundling.
Construction Industry anchors procurement volume. Environmental Services gains share fastest on regulatory traceability mandates.
Distribution Channel:
Supply concentration and margin capture vary sharply between direct digital platforms and traditional merchant intermediaries.
- Direct Sales:Converter-to-contractor relationships bypassing distributor markups through site-delivered bulk ordering platforms. UK national housebuilders increasingly consolidate site consumables under single-source facilities management agreements.
- Wholesale Distributors:Regional inventory stocking for mid-sized commercial developers requiring just-in-time replenishment across multiple project sites.
- Online Retail:Digital procurement portals for small contractors and independent trades with fragmented purchasing patterns.
- Specialty Stores:Builders merchant and hardware chain partnerships for walk-up replacement purchasing and emergency stock.
Direct Sales commands margin expansion. Online Retail represents the fastest-growing trajectory as digital procurement penetrates mid-market construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction waste management mandates across European Union member states now require certified containment for hazardous demolition debris, accelerating specification-grade sack adoption in industrial corridors undergoing infrastructure renewal.
Germany
Industrial deindustrialization projects in the Ruhr corridor generate concentrated bulk demand for 50 kg load-rated containment. EU Construction Products Regulation mandates specification-grade woven polypropylene for hazardous debris. Düsseldorf-based remediation contractors now source multi-cycle sacks for municipal site rehabilitation contracts.
United Kingdom
National housebuilders consolidate site consumables procurement under single-source facilities management agreements. UK Construction Products Regulation governs chemical content in woven substrates. Northern England manufacturing clusters supply wholesale distributor networks serving mid-sized commercial developers across Manchester and Leeds project zones.
United States
EPA landfill diversion rules mandate 75% construction debris recovery rates in designated metropolitan zones. Federal infrastructure bidding documents specify heavy-duty polypropylene formats. California and New York municipal waste authorities maintain preferred vendor lists excluding single-use polyethylene alternatives.
India
BIS certification requirements restrict import of non-standard load-rated products, creating protected market access for domestic converters. Central government infrastructure programs drive specification-grade demand. Gujarat and Maharashtra industrial corridors host extrusion capacity serving domestic commercial construction growth.
Netherlands
Remediation contractors specify chip-enabled sacks with embedded RFID traceability for asbestos-containing debris chain-of-custody automation. ECHA REACH substance restrictions on heavy metals accelerate certified domestic substitution. Rotterdam environmental services clusters drive waterproof PVC formulation demand for contaminated site dewatering operations.
Rubble Sacks Market Competitive Landscape
On the supply side, the industry is moderately fragmented with distinct tiering between specification-grade certified producers and commodity extrusion operators. Three strategic archetypes dominate: direct-to-contractor digital platforms bypassing traditional distribution, specialty fabricators serving regulated hazardous waste segments, and high-throughput converters competing on manufacturing scale. Geographic expansion through regional extrusion partnerships and portfolio diversification into waterproof barrier formulations represent the dominant competitive moves reshaping positioning.
Among UK-based specialists, Elite Plastics exemplifies the direct-to-contractor digital platform archetype, while Leedan Packaging Ltd occupies a position within specialty store partnership channels. Centurion Industrial Packaging represents the scale-driven manufacturing tier with extrusion line concentration in northern England. These three anchors illustrate how procurement channel fragmentation creates parallel competitive vectors rather than direct head-to-head rivalry.
| Leading Market Players |
|---|
| Elite Plastics |
| Leedan Packaging Ltd |
| Centurion Industrial Packaging |
| Proguard |
| HIPPO |
| NDC Polipak |
| Wickes |
| Faithfull Tools |
| Polaris |
| Others |
Value Network & Pricing Analysis
Propylene feedstock volatility determines both pricing tier spreads and supply chain shape across the rubble sacks market, squeezing converter margins on fixed-price municipal contracts while forcing geographic sourcing diversification away from crude-linked resin concentrations.
Pricing Analysis
Certification level under EU Construction Products Regulation and BIS load-rating standards creates the primary spread between premium specification-grade woven polypropylene and commodity extruded alternatives. Three-tier pricing structure across premium certified, standard commercial, and economy import tiers separates REACH-compliant domestic production from Zhejiang and Shandong low-cost exports. Pricing pressure stems from Chinese extrusion overcapacity flooding spot markets and compressing regional pricing power. Municipal contractors exhibit highest price sensitivity due to fixed-budget deindustrialization contracts, while environmental services remediation specialists accept premium positioning for waterproof PVC and RFID-embedded traceability formats.
Supply Chain Analysis
Tariff exposure between China and Western procurement markets dominates supply chain risk calculus for converters dependent on polypropylene resin and circular loom equipment. Manufacturing gravity centers on Germany's Ruhr corridor, northern England extrusion clusters, and Gujarat domestic capacity serving BIS-certified demand. Raw material dependencies encompass crude-linked polypropylene resin, UV stabilizer additives, and PVC plastisol coatings. Single-source vulnerability concentrates in propylene feedstock supply from petrochemical complexes. Distribution runs through builders merchant networks, direct-to-contractor digital platforms, and wholesale distributor channels serving mid-sized commercial developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU extended producer responsibility packaging waste directives constitute a regulatory inflection accelerating format commitment decisions and consolidating procurement relationships around compliant specification-grade producers.
For Market Incumbents: Entrench position through backward integration into polypropylene resin sourcing and extrusion line capacity expansion in BIS-protected Indian markets. Certification investment for REACH-compliant heavy-duty formats defends against Zhejiang low-cost import substitution. Channel control via direct-to-contractor digital platforms captures margin from fragmented UK construction procurement.
For New Entrants and Emerging Players: Build out specialty fabrication capabilities for waterproof PVC environmental services applications in Belgium and Netherlands remediation clusters. White-space availability concentrates in RFID-embedded traceability formats for asbestos chain-of-custody automation. Go-to-market execution targets Dutch environmental services contractors through integrated containment-plus-haulage service bundling.
For Investors and Strategic Acquirers: Extended producer responsibility directive finalization reshapes the acquisition landscape toward specification-grade certified producers with multi-cycle format portfolios. Long-term viability favors converters with extrusion flexibility between lightweight and heavy-duty gauge production. Acquisition target archetype: regional specialists with BIS certification and Ruhr corridor municipal contract relationships. Signal to monitor: EU packaging waste directive implementation timeline for single-use versus returnable format preference determination.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polypropylene sourcing insulates margins from crude-linked volatility swings. |
| RFID Traceability Format Launch | Dutch asbestos remediation contractors now specify chip-enabled sacks for compliance automation. |
| BIS Certification Investment | Mandatory Indian load-rating standards create protected domestic market access. |
| Direct-to-Contractor Platform Expansion | UK national housebuilders consolidate site consumables under single-source agreements. |
| Waterproof PVC Capacity Addition | Belgian environmental services clusters drive premium contaminated runoff containment demand. |
Research Methodology
Desk research of customs trade data, EU Construction Products Regulation filings, and BIS certification registries preceded structured interviews with extrusion plant managers, procurement leads at national housebuilders, remediation contracting executives, and builders merchant category buyers. Primary fieldwork combined with secondary validation against EPA landfill diversion documentation and ECHA REACH substance restriction databases. Bottom-up volume modeling across product type, material substrate, end-user segment, and distribution channel triangulated against top-down macro construction spend indicators.
Assumptions held fixed include EU regulatory enforcement continuity and polypropylene resin supply chain functionality, while propylene feedstock pricing and Chinese export tariff trajectories were varied across sensitivity bands. Segmentation dimensions encompassed load rating tier, material specification, end-use compliance requirements, and procurement channel structure. CAGRs derived from regression analysis of construction output correlations and infrastructure renewal project pipelines, incorporating municipal deindustrialization contract award velocity and environmental services remediation backlog indicators.
Stress conditions across propylene cost volatility bands, Chinese export tariff escalations, and EU extended producer responsibility implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or feedstock supply disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Metal Roofing Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Vegetal Concrete Market