
 Data Integration Software/Tool Market | 2026-2036
Data Integration Software/Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Data Integration Software/Tool Market Outlook
Modular API-first bundling is recalibrating how enterprises evaluate data integration vendors. IBM leverages its hybrid cloud platform to anchor multi-environment deployments for regulated industries. Microsoft extends its Power Platform ecosystem to compete on low-code connectivity, while Informatica specializes in metadata-driven automation for data governance workflows.
Data integration software/tool encompasses platforms that extract, transform, and load data across heterogeneous systems using in-memory processing engines, API connectors, and schema mapping protocols to enable unified analytics and operational decision-making. ETL Tools remain the mature revenue base, though Cloud Integration is displacing legacy batch architectures as enterprises migrate workloads to distributed environments. Real-time Integration captures expanding margin pools where event-streaming latency requirements compress from minutes to sub-second thresholds.
FDA 21 CFR Part 11 and HIPAA in the United States impose audit-trail and data-integrity requirements that shape healthcare sector procurement specifications. The EU AI Act and GDPR mandate explainable data lineage and purpose-limitation controls, forcing vendors to embed policy enforcement engines within integration pipelines. Stakeholders must monitor whether emerging sector-specific AI regulations in Germany, France, and the United Kingdom fragment compliance requirements or converge toward unified data governance standards.
Market Dynamics
Cloud-native data integration architectures are compressing deployment cycles from quarters to weeks, forcing vendors to abandon monolithic ETL stacks in favor of containerized, API-driven pipelines that federate across hybrid environments.
Growth Catalysts
- HIPAA and FDA 21 CFR Part 11:Healthcare providers in the United States must maintain immutable audit trails for patient data, driving procurement of lineage-enabled integration platforms that automate compliance documentation.
- Real-time event streaming:Financial services firms deploy Apache Kafka and Flink-based connectors to compress latency from batch minutes to sub-second thresholds for fraud detection and algorithmic trading.
- EU AI Act enforcement:European enterprises embed purpose-limitation controls and explainability modules directly into data pipelines to avoid penalties for non-compliant AI training data.
Market Restraints
- Specialized talent scarcity:Data engineers with expertise in distributed stream processing and schema registry management command premium compensation, inflating implementation costs for mid-market buyers.
- Cloud egress fees:AWS, Azure, and Google Cloud impose charges on data movement between regions and services, creating friction for multi-cloud integration strategies.
- Legacy mainframe entrenchment:Large insurers and government agencies retain COBOL-based systems with proprietary data formats, requiring expensive custom connector development.
Strategic Opportunities
- Edge-to-cloud federation:Manufacturing and logistics operators in Germany deploy lightweight integration agents on factory floors to preprocess IoT streams before cloud transmission, reducing bandwidth costs.
- Data mesh architectures:Domain-oriented decentralization enables business units to own pipeline development, creating demand for self-service tooling with embedded governance guardrails.
- India's Digital Personal Data Protection Act:Cross-border data transfer restrictions compel multinationals to localize integration infrastructure, opening market entry for domestic platform providers.
Industry Challenges
- Schema drift management:Upstream SaaS applications modify APIs without notice, breaking downstream pipelines and requiring continuous monitoring and automated remapping.
- Multi-cloud credential sprawl:Security teams struggle to maintain least-privilege access controls across dozens of service accounts and API keys distributed across AWS, Azure, GCP, and Snowflake environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Integration Software/Tool Market |
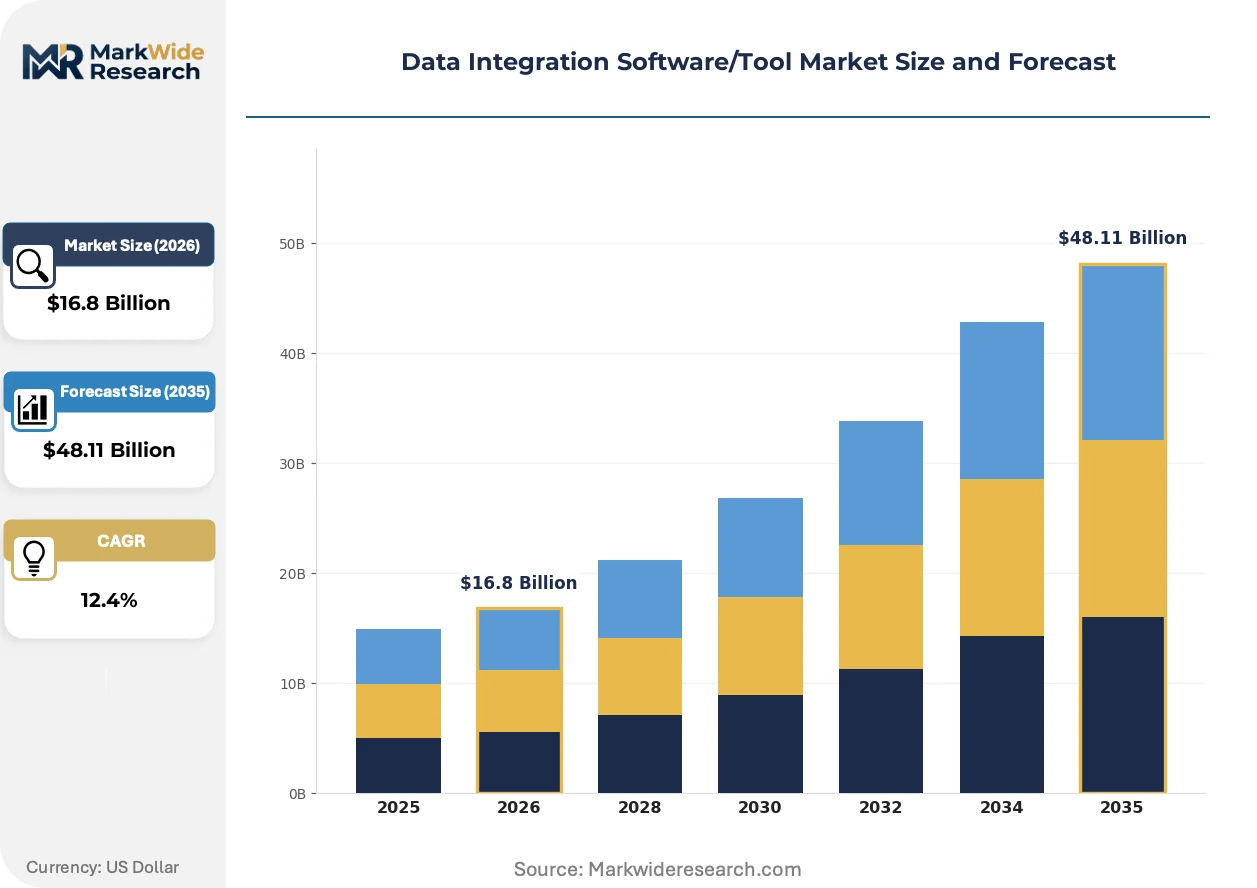
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $48.11 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ETL Tools, Data Quality Tools, Data Virtualization, Cloud Integration Technology: In-memory Processing, Real-time Integration, Batch Processing, API Management End User: Enterprises, SMEs, Government Agencies, Educational Institutions Deployment: On-premises, Cloud-based, Hybrid, Managed Services |
| Companies Covered | Informatica, IBM, Oracle, SAP, Microsoft, SAS Institute, Talend, SnapLogic, Fivetran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Integration Software/Tool Market Strategic Shifts
Semantic layer platforms are collapsing the traditional boundary between data engineering and business intelligence, enabling analysts to define reusable metrics without writing SQL or managing pipeline orchestration.
Data fabric architectures are unifying metadata, governance, and integration logic into a single abstraction layer. Healthcare systems at Kaiser Permanente and Intermountain Health deploy these fabrics to expose patient records across Epic, Cerner, and homegrown systems through a common query interface. The technology is unifying previously siloed analytics teams under centralized data product ownership models.
GDPR Article 30 record-keeping requirements and the EU AI Act's risk classification system are mandating automated data provenance documentation. European pharmaceutical manufacturers now embed lineage capture at ingestion points to satisfy EMA pharmacovigilance audits and demonstrate algorithmic transparency for AI-driven drug discovery pipelines.
Buyer procurement patterns are compressing vendor evaluation cycles from twelve months to ninety days as low-code connectivity templates reduce proof-of-concept complexity. Mid-market retailers in France and the Netherlands bypass traditional RFP processes, purchasing directly through cloud marketplaces where pre-negotiated terms accelerate deployment. This channel shift favors vendors with native AWS Marketplace and Azure Marketplace listings over legacy direct-sales organizations.
Data Integration Software/Tool Market Segmentation
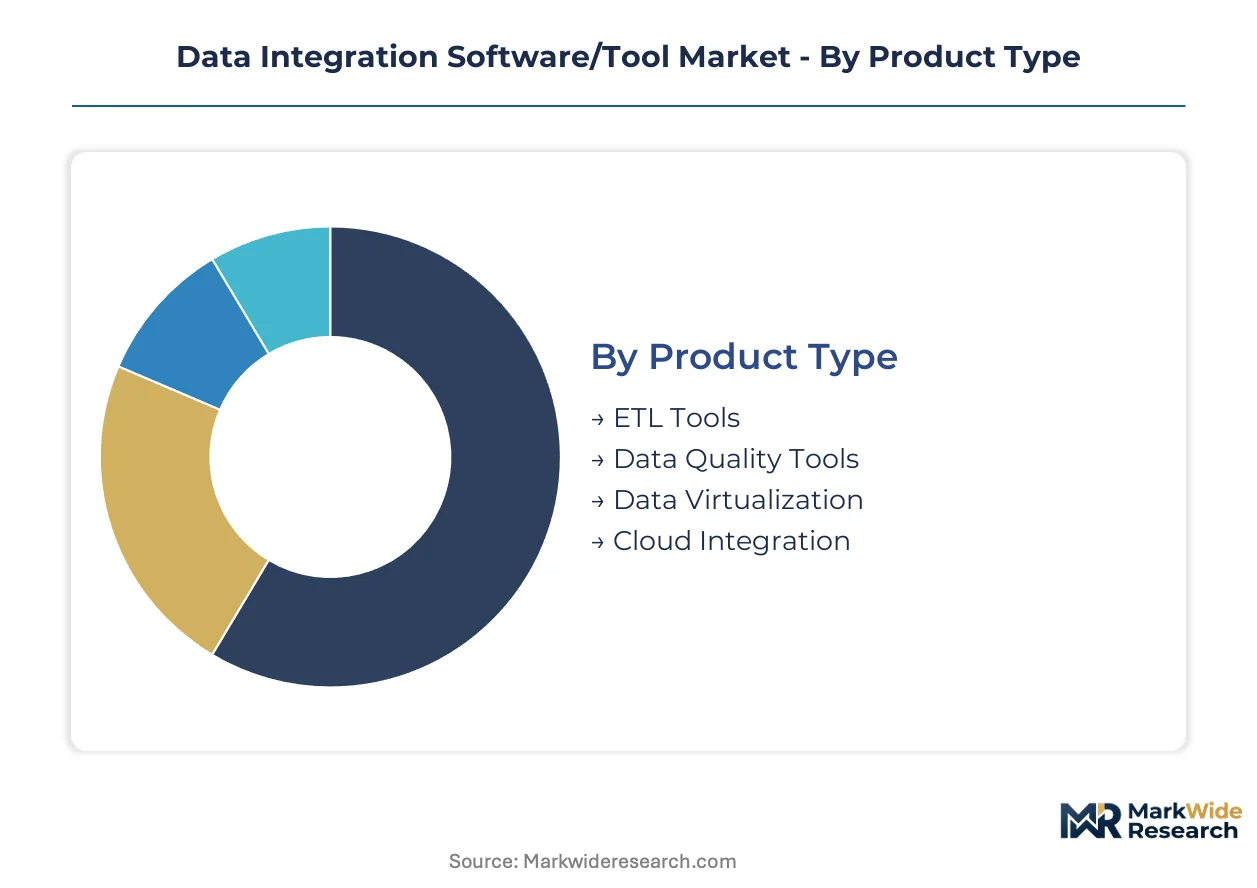
Segmentation in data integration software reveals how procurement priorities diverge between legacy modernization and cloud-native adoption. Buyers select architectures based on latency tolerance, governance requirements, and existing infrastructure investments rather than one-size-fits-all platforms.
Product Type:
Standardization dominates ETL and cloud categories where vendor consolidation has produced interoperable standards, while data virtualization and quality tools retain customization depth for specialized compliance workflows.
- ETL Tools:Extract-transform-load platforms process structured datasets through predefined pipelines with schema mapping and dependency orchestration. Financial services firms in the United States deploy these for regulatory reporting under SEC and FINRA mandates, though batch latency limits their use in algorithmic trading environments.
- Cloud Integration:Native cloud platforms federate data across AWS, Azure, and GCP environments using containerized connectors and serverless execution. Healthcare providers in Germany accelerate deployment of these tools to satisfy GDPR Article 30 documentation requirements while unifying patient records across distributed clinics.
- Data Quality Tools:Profiling and cleansing modules enforce consistency rules across master data repositories.
- Data Virtualization:Query federation layers expose unified views without physical data movement, reducing storage proliferation.
Leading the category by volume: ETL Tools. Expanding most quickly: Cloud Integration.
Technology:
Processing architecture selection maps directly to cost tier — in-memory and real-time command premium pricing for sub-second latency, while batch processing serves cost-sensitive volume workloads.
- Real-time Integration:Event-streaming engines capture and propagate data changes within millisecond windows using distributed commit logs and exactly-once processing semantics. Fraud detection systems at payment processors in the United Kingdom deploy Apache Kafka and Flink connectors to satisfy FCA transaction monitoring rules.
- In-memory Processing:Data grids hold working datasets in RAM to eliminate disk I/O bottlenecks during transformation operations. Capital markets firms in France leverage these engines for pre-trade risk calculations under ESMA MiFID II latency requirements.
- API Management:Gateway platforms enforce rate limiting, authentication, and protocol translation across microservices.
- Batch Processing:Scheduled ETL jobs handle large-volume historical analytics with relaxed latency constraints.
Dominating revenue share: In-memory Processing. Gaining share fastest: Real-time Integration.
End User:
Customer type determines deployment complexity — enterprises demand multi-domain governance, while SMEs prioritize speed-to-insight over architectural completeness.
- Enterprises:Multi-divisional organizations operate hundreds of concurrent pipelines across hybrid estates with centralized data offices enforcing lineage standards. Pharmaceutical manufacturers in Switzerland deploy governed integration fabrics to satisfy Swissmedic pharmacovigilance audit requirements.
- Government Agencies:Public sector buyers mandate FedRAMP or equivalent certifications with immutable audit trails for procurement transparency.
- SMEs:Mid-market buyers favor low-code templates and pre-built connectors to compress implementation cycles.
- Educational Institutions:Universities and research consortia prioritize open-source compatibility and grant-funded pricing structures.
Highest absolute spend: Enterprises. Steepest adoption climb: Government Agencies.
Deployment:
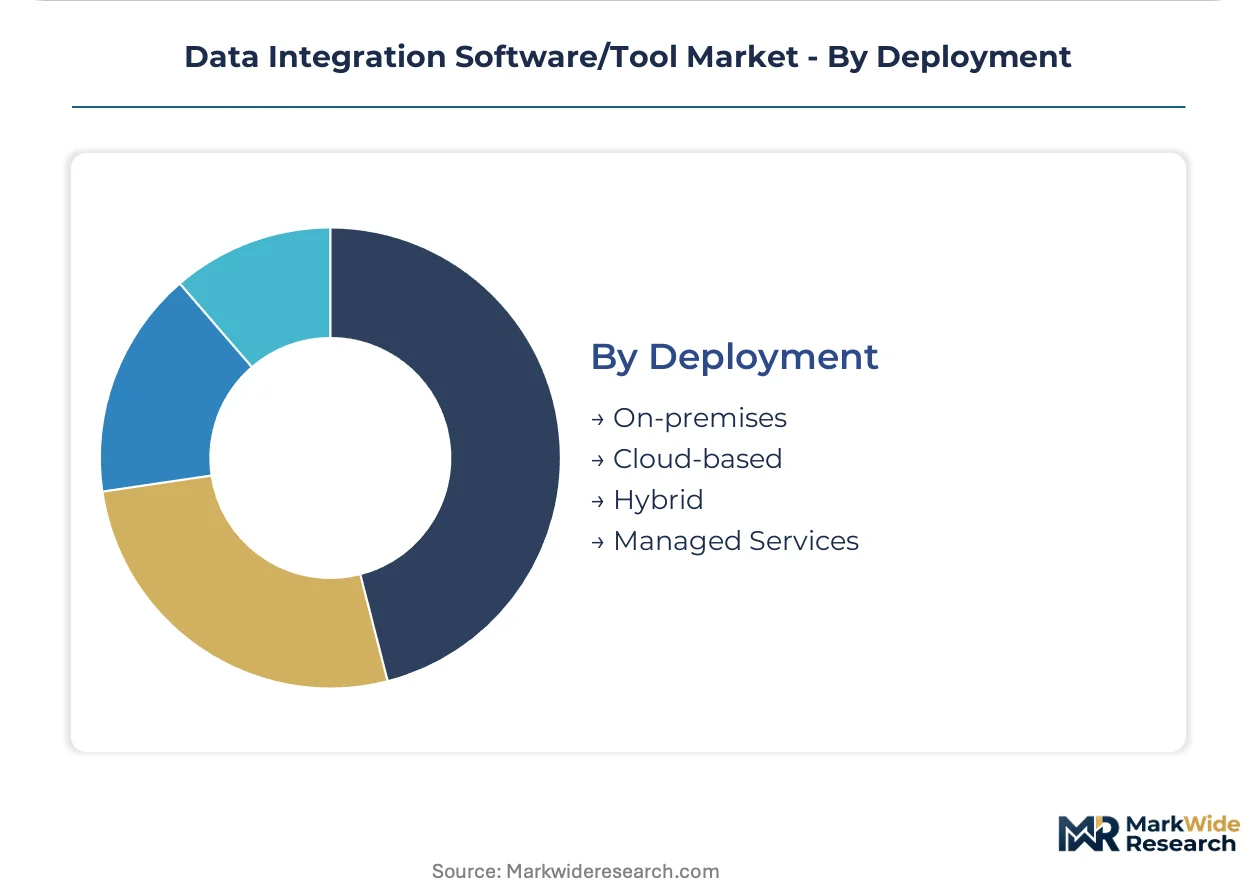
Infrastructure location reflects data sovereignty pressures — regulated industries retain on-premises control for sensitive workloads while cloud-native options capture net-new analytics initiatives.
- Cloud-based:Fully managed SaaS platforms abstract infrastructure provisioning and auto-scale compute resources based on pipeline concurrency. Retailers in the Netherlands bypass capital expenditure approvals by purchasing through AWS Marketplace with pre-negotiated GDPR-compliant terms.
- Hybrid:Split architectures process sensitive data on-premises while bursting transformation workloads to cloud environments. Insurance groups in the United States maintain HIPAA-controlled patient records locally while leveraging cloud analytics for population health models.
- On-premises:Self-managed installations satisfy air-gapped security requirements in defense and intelligence sectors.
- Managed Services:Third-party operators assume pipeline operations responsibility under SLA-governed contracts.
Capturing majority share: Cloud-based. Accelerating most rapidly: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in the United States and Western Europe, while consumption spreads across healthcare and financial services clusters in Asia-Pacific and the Middle East. Cloud infrastructure investments in Germany and India are accelerating faster than North American deployment rates.
United States
Federal interoperability mandates and HIPAA audit requirements drive healthcare providers toward governed integration platforms. The FDA's 21 CFR Part 11 imposes immutable data lineage standards on pharmaceutical manufacturers. Boston's biotech corridor and New York's financial services cluster deploy real-time streaming architectures for algorithmic trading and clinical trial data management.
Germany
Industrial IoT deployments in automotive and manufacturing sectors demand edge-to-cloud federation capabilities. GDPR Article 30 documentation requirements and the EU AI Act's risk classification system compel vendors to embed automated provenance tracking. The Stuttgart automotive cluster and Munich industrial technology corridor lead adoption of lightweight integration agents for factory-floor preprocessing.
United Kingdom
FCA transaction monitoring rules push payment processors toward sub-second latency streaming infrastructure. Open banking regulations mandate API-first connectivity between legacy institutions and fintech challengers. London's financial services district and Manchester's emerging health tech cluster invest heavily in semantic layer platforms to unify analytics teams.
India
The Digital Personal Data Protection Act's cross-border transfer restrictions force multinationals to localize integration infrastructure. Domestic platform providers capture market entry opportunities as global vendors reconfigure deployment architectures. Bangalore's software services corridor and Mumbai's financial district drive demand for hybrid cloud connectors serving regulated industries.
Japan
METI's data free flow with trust initiatives shape enterprise procurement of cross-border pipeline governance tools. Pharmaceutical manufacturers prepare for PMDA pharmacovigilance audits requiring embedded lineage capture. Tokyo's financial district and Osaka's manufacturing belt prioritize in-memory processing engines for pre-trade risk calculations under compressed latency requirements.
Data Integration Software/Tool Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures favor vendors with hybrid cloud platforms and low-code connectivity ecosystems. Three archetypes dominate: legacy enterprise software incumbents with metadata-driven automation, cloud-native challengers with API-first architectures, and vertical specialists embedding compliance engines for regulated industries. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into semantic layer and data fabric capabilities.
Within the legacy incumbent tier, IBM and Oracle occupy positions anchored by hybrid cloud platforms and enterprise database integration. Microsoft exemplifies the ecosystem-driven archetype, extending low-code connectivity through its Power Platform. Informatica represents the governance-specialist vector, embedding policy enforcement engines for HIPAA and GDPR compliance workflows. These three vendors illustrate how market positioning stratifies between infrastructure breadth, developer experience, and regulatory automation depth.
| Leading Market Players |
|---|
| Informatica |
| IBM |
| Oracle |
| SAP |
| Microsoft |
| SAS Institute |
| Talend |
| SnapLogic |
| Fivetran |
| Others |
Value Chain & Pricing Dynamics
Cloud compute unit economics cascade through data integration software pricing tiers, compressing margins for batch-processing vendors while real-time streaming platforms capture premium positioning. Talent acquisition costs in distributed systems engineering propagate downstream, forcing mid-market buyers toward SaaS consumption models that externalize infrastructure overhead.
Pricing Analysis
Margin tightening in the mid-market tier reflects hyperscaler marketplace commissions and customer acquisition cost inflation. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by latency guarantees and HIPAA/FDA 21 CFR Part 11 certification depth. Cost-down pressure on self-managed deployments accelerates because cloud-native alternatives eliminate capital expenditure approval cycles. Government agencies exhibit lowest price sensitivity due to compliance-mandated procurement specifications, while retail SMEs prioritize per-connector pricing transparency.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor partner-led implementation networks for enterprise deployments. Software development draws from open-source committer communities in Eastern Europe, Indian engineering corridors, and Silicon Valley talent pools. Single-source vulnerability concentrates in Apache Kafka and Flink core committer networks for streaming infrastructure. Distribution runs through hyperscaler marketplaces and systems integrator channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into metadata governance engines is reshaping competitive positioning, with incumbents acquiring lineage-tracking specialists to differentiate against API-first challengers.
For Market Incumbents: Deploy hybrid cloud platform extensions to defend against cloud-native entrants. Acquire real-time streaming specialists to close latency gaps with Apache Kafka ecosystem providers. Fortify channel control through exclusive hyperscaler marketplace listings that lock out point-solution competitors. For New Entrants and Emerging Players: Launch via AWS Marketplace and Azure Marketplace direct procurement channels to bypass twelve-month enterprise sales cycles. Target India's domestic platform opportunity created by Digital Personal Data Protection Act localization mandates. Pursue edge-to-cloud federation use cases in German automotive manufacturing clusters where lightweight agent deployment reduces bandwidth costs. For Investors and Strategic Acquirers: EU AI Act enforcement actions against non-compliant training data pipelines are the leading indicator that governance-automation specialists will command acquisition premiums. Five-to-ten-year viability favors vendors embedding policy enforcement engines rather than connectivity-only architectures. Monitor FDA 21 CFR Part 11 audit failure rates as signal for healthcare procurement consolidation toward lineage-enabled platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying metadata, governance, and integration logic collapses siloed analytics team structures at Kaiser Permanente-scale health systems. |
| Strategic Partnership | Exclusive hyperscaler marketplace listings accelerate procurement cycles for GDPR-compliant cloud integration in Dutch retail. |
| Acquisition of Specialist Firm | Real-time streaming expertise from Flink committer networks closes latency gaps against Apache Kafka ecosystem incumbents. |
| Geographic Expansion | Localized infrastructure deployment satisfies India's Digital Personal Data Protection Act cross-border transfer restrictions. |
| Product Launch | Semantic layer platforms enable business analysts to define reusable metrics without SQL expertise, collapsing data engineering bottlenecks. |
Study Parameters
Multi-period observation of HIPAA audit enforcement patterns, EU AI Act implementation timelines, and hyperscaler capex disclosures anchored the trend analysis, supplemented by interviews with CTOs, data platform engineers, healthcare compliance officers, and systems integration specialists. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA pharmacovigilance audit protocols, SEC filings of publicly traded software vendors, and hyperscaler marketplace transaction disclosures. Bottom-up pipeline deployment counts and top-down enterprise IT spend estimates were triangulated to calibrate market sizing.
Input-output matrices modeled deployment model, organization size, vertical industry, integration complexity tier, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from elasticity-adjusted adoption curves across the projection horizon. Forecast inputs incorporated cloud egress fee trajectories from AWS, Azure, and Google Cloud pricing disclosures alongside talent compensation inflation in distributed systems engineering roles.
Regulatory enforcement variance, hyperscaler pricing policy shifts, and open-source project governance disruptions are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Testing Tools Market
Software & Services
Generative Design Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Technology CAD Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Stock Footage Software Market
Software & Services
Global Back Testing Software Market
Software & Services
Team Collaboration Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
3D Animation Production Software Market
Software & Services
Global Database Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Photo Editing Software Market
Software & Services
Sales Compensation Software Market