
 Global Back Testing Software Market | 2026-2036
Global Back Testing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Back Testing Software Market Foresight
Institutional-grade back testing capability is rotating from a niche quant tool into a baseline requirement across sell-side and buy-side desks. Bloomberg L.P. leverages its terminal ecosystem to embed strategy validation directly into trader workflows. AlgoTrader GmbH anchors its position through open-architecture deployment across European proprietary trading firms. QuantConnect differentiates by offering cloud-native algorithmic testing with open-source accessibility.
Back testing software evaluates trading strategies against historical market data to simulate performance, validate risk parameters, and optimize execution logic before capital deployment. The platform ingests tick-level price feeds, applies user-defined algorithms across multi-year datasets, and generates statistical performance metrics including Sharpe ratios and maximum drawdowns. Cloud-Based deployment now captures the fastest growth trajectory as hedge funds and asset managers abandon on-premise server farms for elastic compute capacity. Strategy Validation solutions command premium pricing due to regulatory pressure on pre-trade risk controls. Algorithmic Testing remains the volume leader, though Performance Analytics is gaining share as pension funds demand deeper attribution modeling.
SEC oversight of algorithmic trading practices in the United States and FCA conduct rules in the United Kingdom mandate documented strategy validation before live deployment, directly expanding procurement of audit-ready back testing platforms. EU MiFID II transaction reporting requirements and ESMA guidelines on algorithmic trading further tighten compliance scope across European asset managers. Stakeholders must weigh vendor lock-in risks against the operational agility that API-Driven and Hybrid architectures provide as trading infrastructure evolves.
Market Dynamics
Cloud migration is compressing deployment cycles for back testing infrastructure as quantitative trading firms abandon fixed-capacity server farms for elastic compute. This structural shift is redistributing procurement power from traditional software vendors toward hyperscale cloud providers and API-native platforms.
Growth Catalysts
- SEC algorithmic trading oversight:Mandated pre-trade risk documentation drives institutional procurement of audit-ready validation platforms across US hedge funds and broker-dealers.
- Tick-level data ingestion:Advances in high-frequency data processing enable nanosecond-resolution back testing for latency-sensitive strategies.
- Singapore financial hub expansion:Monetary Authority of Singapore incentives for quantitative trading infrastructure deepen algorithmic testing demand in Asia-Pacific.
Market Restraints
- Historical data licensing costs:Exchange-imposed fees for tick-level archives compress margins for mid-tier quantitative research vendors.
- Cloud vendor concentration:Dependency on AWS, Azure, and Google Cloud creates single-point-of-failure risk for mission-critical trading simulations.
- Latency floor in cloud environments:Network jitter prevents cloud-native back testing from matching co-located hardware performance for ultra-HFT strategies.
Strategic Opportunities
- EU MiFID II regulatory tailwind:ESMA guidelines on algorithmic trading compliance create sustained demand for documented strategy validation across European asset managers.
- Crypto-derivative back testing:24/7 digital asset markets require specialized simulation engines absent from legacy equity-focused platforms.
- Retail quant platform convergence:Python-based open-source frameworks lower barriers for individual algorithmic traders seeking institutional-grade tools.
Industry Challenges
- Quantitative developer scarcity:Shortage of specialists fluent in both financial mathematics and cloud-native architecture constrains platform expansion timelines.
- Multi-asset integration complexity:Fragmented data formats across equities, fixed income, and derivatives complicate unified back testing pipeline construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Back Testing Software Market |
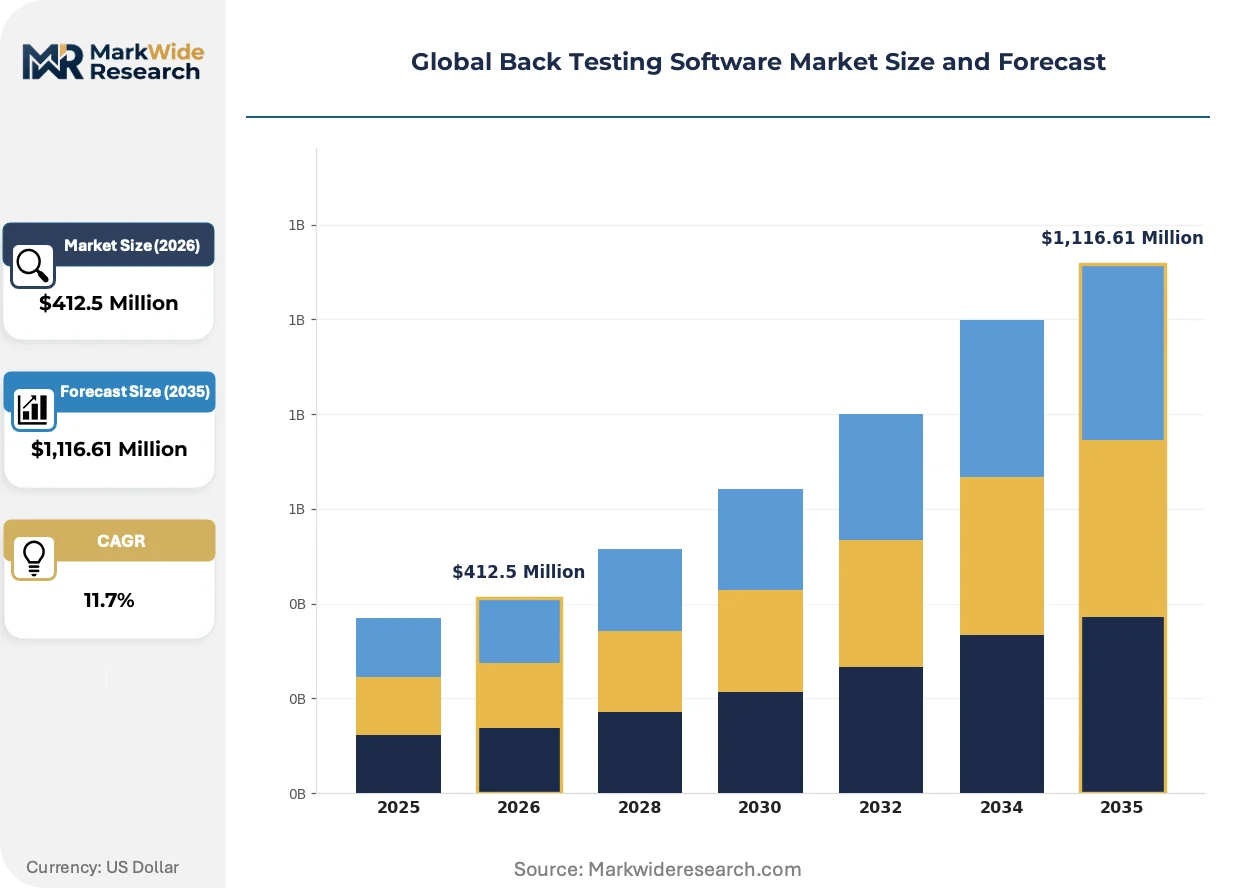
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,116.61 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, API-Driven Solution Type: Algorithmic Testing, Strategy Validation, Risk Analytics, Performance Analytics, Data Integration Application: Quantitative Research, Portfolio Management, Risk Management, Derivatives Trading, Asset Allocation End User: Hedge Funds, Pension Funds, Proprietary Trading Firms, Asset Managers, Wealth Advisors |
| Companies Covered | Bloomberg L.P., AlgoTrader GmbH, AmiBroker Ltd, Interactive Brokers LLC, MultiCharts, NinjaTrader Group, TradeStation Group, QuantConnect, TradingView, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Back Testing Software Market Shifts & Advancements
Containerized deployment models are restructuring how trading firms provision simulation capacity. This evolution spans infrastructure abstraction, regulatory automation, and procurement recalibration across the value chain.
Serverless computing architectures are supplanting provisioned virtual machines for burst-heavy back testing workloads. Mid-sized quantitative hedge funds in London and New York now deploy serverless functions for overnight strategy sweeps. This shift is compressing infrastructure costs for episodic compute demand while limiting customization depth.
EU AI Act risk classification requirements are extending documentation burdens to algorithmic trading strategies deemed high-risk. Asset managers must now maintain explainability logs for machine learning-driven back testing outputs. German and French quantitative desks are responding by embedding automated audit trails directly into simulation pipelines.
Subscription-based licensing is displacing perpetual seat models across institutional procurement. Buy-side technology committees now prioritize usage-elastic contracts over fixed-capacity agreements. This pattern is most visible among US pension funds reallocating technology budgets toward operational expenditure frameworks.
Global Back Testing Software Market Segmentation
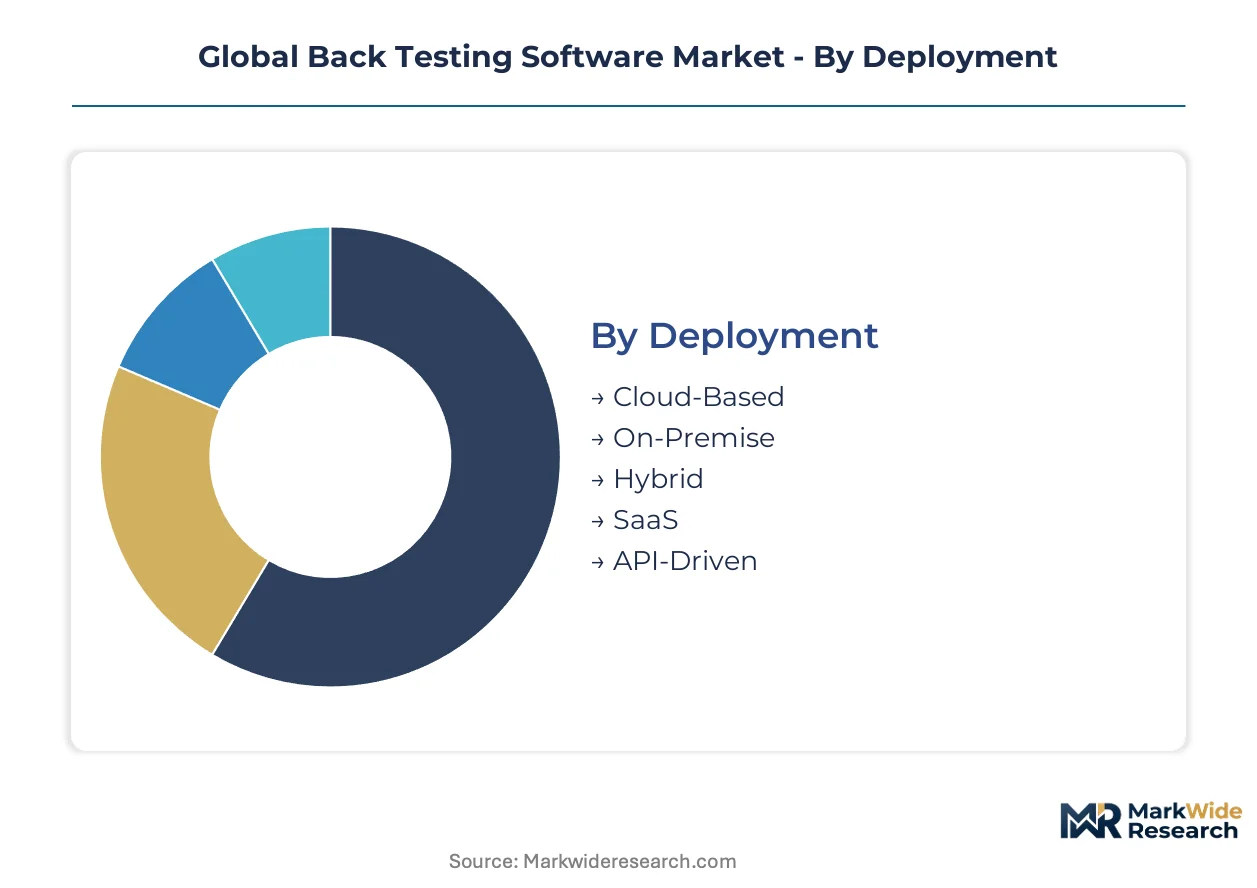
Back testing software procurement patterns diverge sharply across deployment models and user sophistication tiers. Regulatory mandates on audit trails and data residency reshape how quantitative teams evaluate platform architecture.
Deployment:
SEC and FCA documentation requirements create divergent compliance burdens across infrastructure models.
- Cloud-Based:Elastic compute pools scale simulation throughput for episodic strategy sweeps. Hedge funds in New York and London abandon fixed server farms for AWS and Azure instances, though network jitter constrains ultra-HFT latency requirements.
- On-Premise:Dedicated hardware clusters maintain sub-microsecond co-location proximity to exchange matching engines. Proprietary trading firms in Chicago and Frankfurt retain on-premise deployments for tick-level arbitrage strategies where cloud latency floors prove prohibitive.
- Hybrid:Split architectures isolate sensitive pre-trade logic on-premise while bursting historical analysis to cloud.
- SaaS:Subscription models lower capital barriers for mid-tier asset managers.
- API-Driven:Microservice integration enables modular simulation pipelines.
Cloud-Based handles the majority of throughput; API-Driven is the fastest mover on share.
Solution Type:
Cost tier differentiation separates institutional-grade validation suites from research-oriented testing modules.
- Algorithmic Testing:Core simulation engines ingest multi-year tick archives to validate execution logic across market regimes. Quantitative research teams at hedge funds and proprietary trading firms in Singapore drive concentrated demand for nanosecond-resolution playback.
- Strategy Validation:Audit-ready documentation suites satisfy SEC pre-trade risk mandates and ESMA algorithmic trading guidelines. Premium pricing reflects regulatory pressure on documented evidence trails before live capital deployment.
- Risk Analytics:Stress testing modules evaluate tail scenarios and drawdown profiles.
- Performance Analytics:Attribution modeling gains traction among pension funds seeking factor decomposition.
- Data Integration:Normalization pipelines harmonize fragmented exchange feeds.
Algorithmic Testing retains the largest installed base; Performance Analytics is expanding most quickly as institutional investors deepen attribution requirements.
Application:
Volume concentration tracks the maturity of quantitative infrastructure across financial centers.
- Quantitative Research:Systematic strategy development consumes the bulk of simulation cycles. Teams at hedge funds and proprietary trading firms in the United States, United Kingdom, and Singapore dominate compute consumption for alpha generation and signal validation.
- Portfolio Management:Multi-asset optimization requires cross-asset back testing capabilities. Asset managers in London and New York seek unified pipelines spanning equities, fixed income, and derivatives.
- Risk Management:Pre-trade controls and limit monitoring leverage simulation outputs.
- Derivatives Trading:Complex payoff structures demand specialized path-dependent simulation.
- Asset Allocation:Strategic rebalancing uses long-horizon historical scenarios.
Quantitative Research absorbs the dominant share of platform capacity; Portfolio Management is climbing the fastest as traditional asset managers adopt systematic techniques.
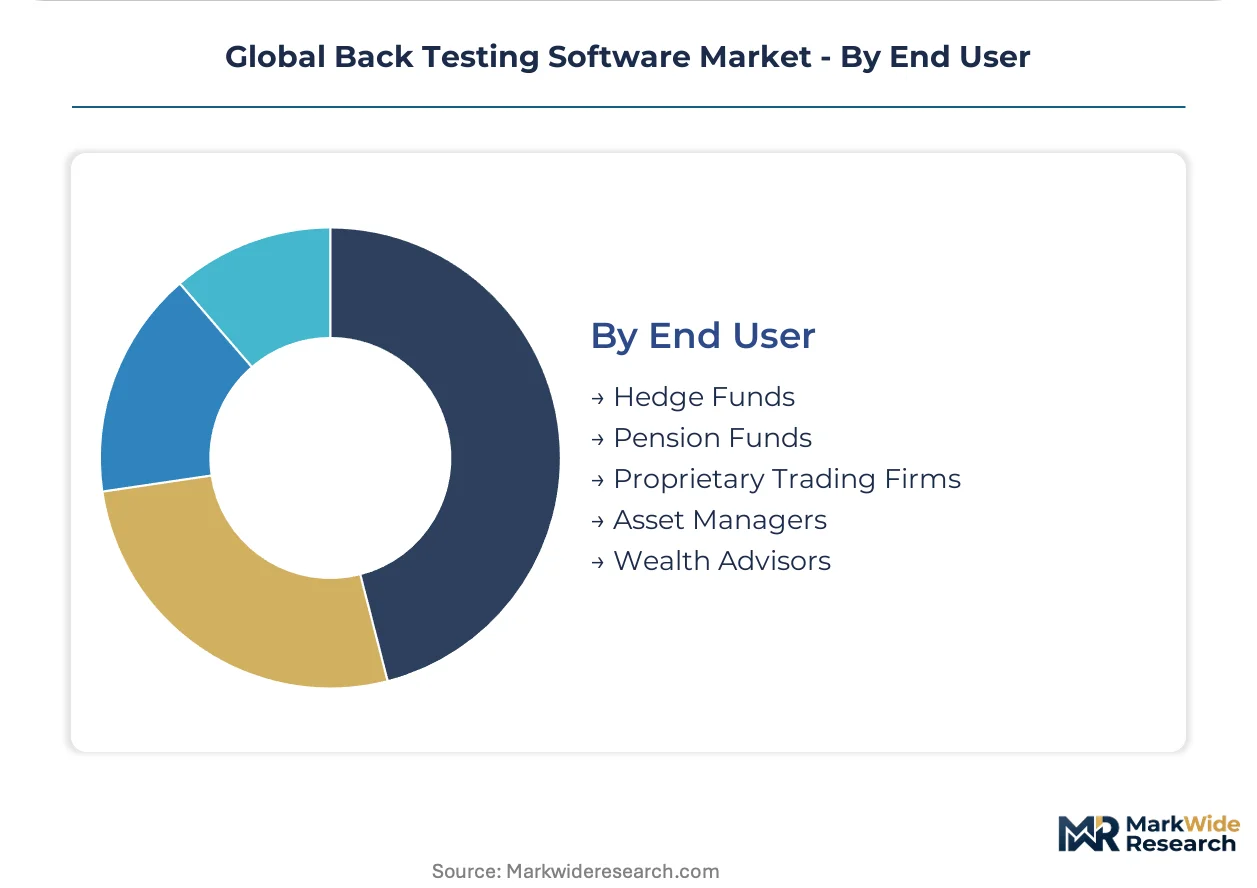
End User:
Customer type determines pricing elasticity and feature depth requirements across the procurement spectrum.
- Hedge Funds:Sophisticated quantitative teams demand tick-level granularity and custom execution logic. Firms in Greenwich, Connecticut and Mayfair, London procure premium-tier platforms with dedicated support and co-location integration.
- Pension Funds:Fiduciary oversight drives demand for documented audit trails and explainable outputs. Large US public pension systems in California and New York prioritize regulatory compliance modules over latency optimization.
- Proprietary Trading Firms:Speed-sensitive strategies prioritize hardware proximity and data feed optimization.
- Asset Managers:Multi-asset coverage requirements span traditional and alternative strategies.
- Wealth Advisors:Simplified interfaces target high-net-worth portfolio construction.
Hedge Funds command the deepest platform engagement; Pension Funds represent the steepest expansion trajectory as fiduciary technology budgets reallocate toward systematic validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Back testing software flows predominantly from the United States and United Kingdom toward Singapore and emerging Asian financial centers. Import dependency characterizes secondary markets seeking institutional-grade validation platforms. Regulatory divergence across SEC, FCA, and MAS jurisdictions shapes localized procurement specifications.
United States
Greenwich hedge funds and Manhattan prop trading desks drive concentrated demand for tick-level simulation engines. SEC algorithmic trading oversight mandates documented pre-trade risk validation, compelling institutional procurement of audit-ready platforms. Chicago's co-location corridors retain on-premise hardware clusters for latency-sensitive arbitrage strategies.
United Kingdom
Mayfair quantitative teams and Canary Wharf asset managers absorb substantial cloud-native testing capacity. FCA conduct rules on algorithmic trading documentation tighten compliance scope across buy-side and sell-side desks. London's fintech corridor accelerates API-first platform adoption among mid-tier systematic funds.
Singapore
Monetary Authority of Singapore incentives deepen quantitative trading infrastructure investment across regional hedge funds. MAS technology risk management guidelines elevate back testing to core operational requirements. Marina Bay financial district hosts expanding proprietary trading operations seeking nanosecond-resolution simulation capabilities.
Germany
Frankfurt asset managers and Munich quant specialists respond to EU MiFID II transaction reporting mandates with enhanced validation suites. ESMA algorithmic trading guidelines create sustained procurement pressure for documented strategy evidence trails. Baden-Württemberg industrial data centers support hybrid deployment architectures splitting sensitive logic from burst compute.
Japan
Tokyo systematic trading desks and Osaka derivatives specialists integrate back testing into multi-asset optimization workflows. METI financial technology promotion programs accelerate cloud migration among regional securities firms. Tokyo-Yokohama corridor concentrates demand for performance analytics modules serving pension fund attribution requirements.
Global Back Testing Software Market Competitive Landscape
Concentration sits with terminal-integrated incumbents and cloud-native challengers reshaping procurement hierarchies. Bloomberg L.P. leverages embedded terminal workflows to capture institutional validation spend. AlgoTrader GmbH anchors European prop trading penetration through open-architecture deployment. QuantConnect exemplifies the API-first archetype displacing traditional seat-license models. Competitive moves center on M&A absorption of specialized data integration layers and strategic partnerships with hyperscale cloud providers.
Within the terminal-integrated tier, Bloomberg L.P. occupies a position representing legacy ecosystem lock-in. Among European specialists, AlgoTrader GmbH exemplifies open-architecture penetration of proprietary trading workflows. QuantConnect anchors the cloud-native challenger archetype, representing accessibility-driven disruption of institutional procurement patterns. These three entities collectively illustrate the tripartite structure governing competitive dynamics.
| Leading Market Players |
|---|
| Bloomberg L.P. |
| AlgoTrader GmbH |
| AmiBroker Ltd |
| Interactive Brokers LLC |
| MultiCharts |
| NinjaTrader Group |
| TradeStation Group |
| QuantConnect |
| TradingView |
| Others |
Supply & Pricing Matrix
Elastic compute utilization curves at hyperscale cloud providers compress marginal costs for simulation throughput, concentrating procurement leverage among AWS, Azure, and Google Cloud while establishing subscription-based price floors that mid-tier quantitative research vendors struggle to undercut.
Pricing Analysis
Hedge fund technology committees anchor pricing stratification across premium, standard, and economy tiers, with audit-ready validation suites commanding premium subscriptions due to SEC pre-trade risk documentation mandates. Price differentiation hinges on tick-level data granularity and API integration depth. Pricing pressure stems from open-source Python frameworks lowering barriers for retail quant adoption. Pension funds exhibit highest price sensitivity, while Greenwich and Mayfair hedge funds prioritize latency optimization over cost.
Supply Chain Analysis
Trans-Pacific cable congestion and containerized software delivery latency reshape inbound logistics for cloud-native deployment, with Frankfurt, Singapore, and Ashburn data centers anchoring primary simulation capacity. Raw material dependencies span historical tick archives from CME Group and ICE, co-location rack space, and specialized GPU clusters. Single-source vulnerability concentrates in AWS for burst compute. Distribution runs through direct enterprise sales teams and API marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among quantitative hedge funds consolidating technology procurement committees, fragmenting vendor access as fewer institutions control larger simulation budgets.
For Market Incumbents: Compound terminal ecosystem lock-in by embedding strategy validation deeper into Bloomberg L.P. workflows before cloud-native challengers displace seat-license models. Defend against QuantConnect's API-first accessibility by investing in co-location integration for Chicago and Frankfurt proprietary trading firms. Vertical integration into tick-level data licensing secures margin protection against exchange fee compression. For New Entrants and Emerging Players: Anchor in crypto-derivative back testing white space, where 24/7 digital asset markets lack specialized simulation engines from legacy equity-focused platforms. Target Singapore's expanding Marina Bay financial district, where MAS incentives deepen quantitative infrastructure investment. Pursue open-source Python community engagement as primary go-to-market channel. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with API-driven deployment models, positioning them favorably across the analysis window. Acquisition focus should center on specialized data integration layers that harmonize fragmented exchange feeds. Watch for inflection when pension fund technology budgets shift from capital expenditure to operational expenditure frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Microservice architectures enable modular simulation pipelines for AWS and Azure deployment. |
| Tick-Level Data Partnership | Exchange feed agreements with CME Group and ICE secure nanosecond-resolution playback capability. |
| Serverless Architecture Migration | Lambda and Azure Functions compress infrastructure costs for episodic overnight strategy sweeps. |
| EU Regulatory Compliance Module | Automated audit trails satisfy ESMA algorithmic trading guidelines for German and French asset managers. |
| Open-Source Community Expansion | Python framework accessibility lowers barriers for retail quant adoption against incumbent seat licenses. |
Research Methodology
The analysis maps cloud-based deployment, on-premise hardware clusters, and hybrid architectures, each validated through quantitative research heads at hedge funds, CTOs at proprietary trading firms, and technology procurement officers at pension funds. Primary interviews with these stakeholders combined with secondary validation from SEC regulatory filings, FCA conduct rule updates, MAS technology risk guidelines, and hyperscaler capex disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, application workflow, and end-user sophistication tier. CAGRs derive from historical trajectory analysis and forward-looking adoption curve projection. Industry-specific inputs encompass regulatory mandate timelines and cloud migration velocity among systematic trading desks.
Material uncertainties — regulatory enforcement intensity shifts, hyperscale cloud pricing volatility, and quantitative developer labor scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions about SEC and FCA documentation requirement permanence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Airline Route Profitability Software Market
Software & Services
Global Forestry Software Market
Software & Services
India Software Services Export Market
Software & Services
Programmable Automation Controller (PAC) Programming Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Global Version Control Systems Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Driver Updater Software Market
Software & Services
Team Collaboration Tools Market
Software & Services
Live Software Market
Software & Services
Global ITSM Software Market
Software & Services
Photo Editor App Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Global Open Source Services Market
Software & Services
Global Claims Processing Software Market