
 Cloud Integration Software Market | 2026-2036
Cloud Integration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Integration Software Market Analysis
Container-native orchestration is realigning how enterprises provision integration middleware, replacing traditional virtual-machine-based deployments with Kubernetes-native runtime environments. MuleSoft leverages its Anypoint Platform to anchor API-led connectivity strategies across Salesforce-centric ecosystems. Dell Boomi competes through atom-based runtime architecture that sustains low-code integration velocity for mid-market buyers. IBM differentiates via Watson-augmented data mapping and mainframe-to-cloud bridging capabilities that dominate regulated verticals.
Cloud integration software comprises middleware, API gateways, and data transformation engines that enable interoperability between disparate SaaS, PaaS, and on-premises systems through standardized protocols such as REST, SOAP, and OData. Its primary commercial purpose is to eliminate data silos and automate business process flows across heterogeneous IT estates. Hybrid cloud deployment captures the largest addressable base as enterprises retain sensitive workloads on-premises while bursting transactional loads to public infrastructure. API management solutions lead solution-level margin pools, though workflow automation is expanding fastest as organizations orchestrate cross-application business logic without custom code.
FCC guidelines on telecommunications data handling, SEC disclosure rules for financial services cloud migrations, and HIPAA security standards for healthcare data interoperability collectively shape product certification requirements and procurement vetting cycles in the United States. GDPR and the EU AI Act impose cross-border data governance obligations that integration vendors must embed into their platform architectures to maintain European market access. Stakeholders should monitor how NIST's emerging AI risk management framework intersects with existing cloud security mandates to determine compliance roadmaps for next-generation integration deployments.
Market Dynamics
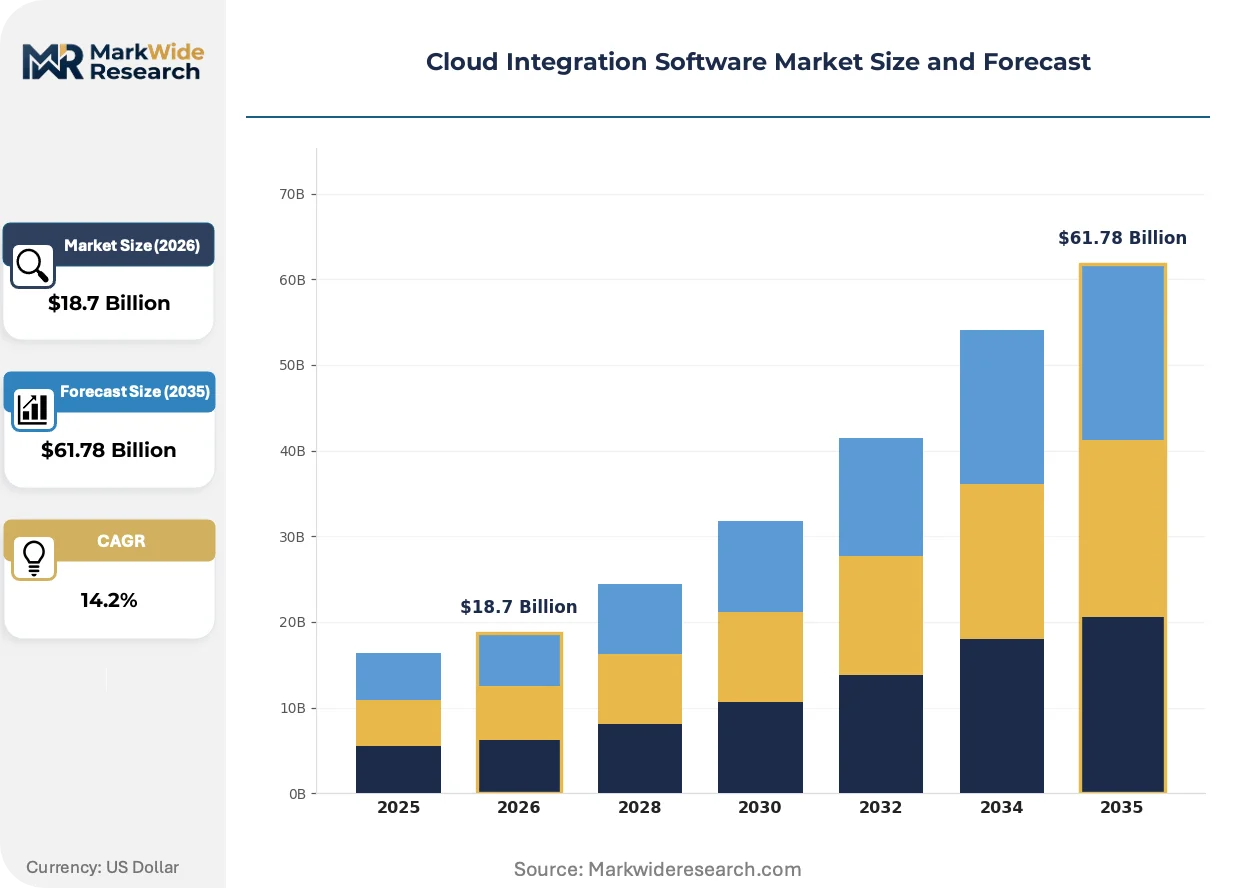
Container-native orchestration is compressing deployment timelines for integration middleware, as Kubernetes-native runtimes displace virtual-machine-based provisioning across enterprise IT estates. This architectural shift is redistributing competitive advantage toward vendors with declarative infrastructure-as-code capabilities.
Growth Catalysts
- Federal cloud-smart mandates:United States agencies are procuring hybrid integration platforms to satisfy data sovereignty requirements while enabling SaaS interoperability.
- Healthcare EHR unification:HIPAA-aligned data architectures are driving hospital systems toward API gateways that federate patient records across distributed care networks.
- Event-driven architecture adoption:Financial services firms are deploying stream-processing integration layers to enable real-time transaction reconciliation across core banking and fintech endpoints.
Market Restraints
- Specialized talent scarcity:Shortages of Kubernetes-certified integration architects are extending implementation timelines and inflating professional services costs.
- Cross-border data friction:GDPR's extraterritorial enforcement is constraining how multinationals route API traffic between European and non-European cloud regions.
- Legacy protocol persistence:Mainframe COBOL systems with fixed-width data formats resist standard REST transformation, requiring costly custom adapter development.
Strategic Opportunities
- EU AI Act compliance tooling:European enterprises need integration platforms with embedded lineage tracking to satisfy algorithmic audit requirements.
- Edge-to-cloud orchestration:Manufacturing sites are deploying lightweight integration runtimes to synchronize IoT telemetry with central ERP systems.
- API monetization marketplaces:Telecommunications carriers are building developer portals that expose network capabilities as productized service bundles.
Industry Challenges
- Multi-cloud credential sprawl:Security teams struggle to maintain least-privilege access controls across AWS, Azure, and GCP IAM policies simultaneously.
- Schema drift management:Frequent SaaS vendor API version changes break existing data mappings, forcing continuous regression testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Integration Software Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution: API Management, Data Integration, Workflow Automation, Platform Integration End User: SMBs, Large Enterprises, Government Agencies, Educational Institutions Service Type: Consulting, Implementation, Support, Managed Services |
| Companies Covered | MuleSoft, Dell Boomi, Informatica, SnapLogic, IBM, Microsoft, Oracle, TIBCO Software, Workato, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Integration Software Market Emerging Trajectories
Generative AI is embedding into integration development workflows, compressing the time required to construct data transformations and API specifications. This capability infusion is redrawing the boundary between professional developers and citizen integrators.
Event mesh architectures are absorbing transactional workloads that previously flowed through centralized enterprise service buses. Retailers with distributed fulfillment networks are deploying these decentralized brokers to maintain inventory consistency across edge warehouses. The technology is absorbing point-to-point integration debt by collapsing multiple bilateral connections into publish-subscribe topologies.
The EU AI Act is mandating algorithmic audit trails for automated decision systems, forcing integration vendors to embed provenance logging into data pipelines. Financial institutions deploying credit-scoring workflows must now demonstrate traceability from raw inputs to model outputs. European healthcare providers are responding by selecting platforms with native lineage capture rather than retrofitting compliance layers.
Consumption-based pricing for integration capacity is displacing perpetual license models among mid-market buyers. Channel partners are unbundling implementation services from software subscriptions, selling pure professional engagements alongside vendor-agnostic platform selections. This shift is most pronounced in Germany, where Mittelstand manufacturers prefer operational expenditure treatment for integration infrastructure.
Cloud Integration Software Market Segmentation
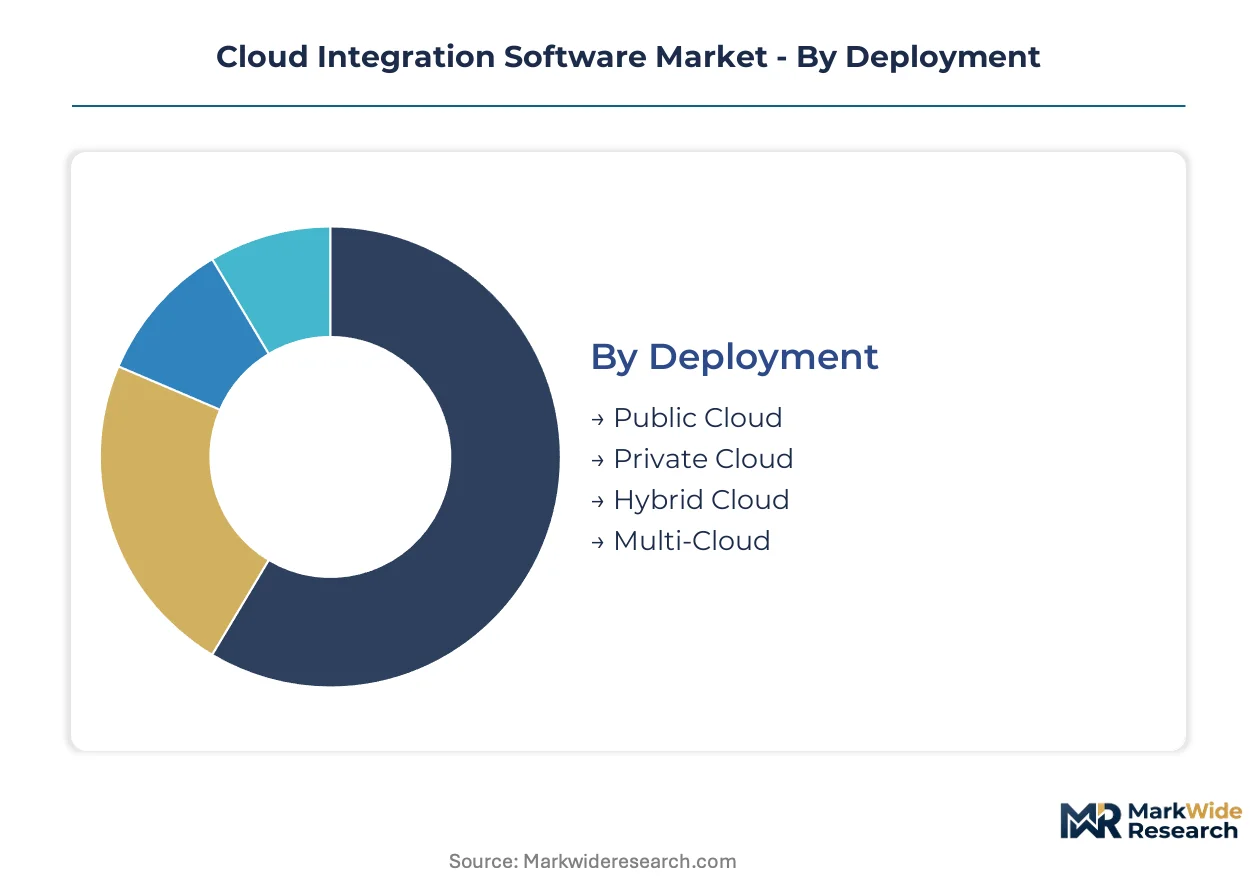
Deployment architecture determines integration latency, data sovereignty compliance, and operational expenditure profiles for cloud integration buyers. Solution type selection hinges on whether organizations prioritize API governance, batch data movement, or event-driven orchestration. End-user scale and service engagement models further stratify procurement patterns across the market.
Deployment:
Procurement teams weigh data residency mandates against elasticity requirements when selecting deployment topology.
- Hybrid Cloud:Combines on-premises runtime nodes with public cloud bursting capacity to satisfy HIPAA and GDPR data localization while enabling SaaS interoperability. United States federal agencies and German automotive manufacturers dominate demand here, driven by NIST 800-53 compliance requirements and the country's dual sovereignty concerns.
- Multi-Cloud:Distributes integration workloads across AWS, Azure, and GCP simultaneously to mitigate vendor lock-in and optimize regional latency. Financial services firms in Singapore and healthcare networks in Australia prioritize this architecture to satisfy their national regulators' cross-border data routing restrictions.
- Public Cloud:Delivers fully managed integration runtimes with consumption-based scaling for mid-market buyers lacking dedicated infrastructure teams.
- Private Cloud:Deploys integration middleware within dedicated tenant environments for defense contractors and classified government workloads.
Volume sits with Hybrid Cloud; growth tilts toward Multi-Cloud.
Solution:
Functional capability selection tracks the maturity of an organization's API strategy and data architecture complexity.
- API Management:Enforces rate limiting, authentication, and versioning across exposed service endpoints through gateway proxies and developer portal layers. European banks and telecommunications carriers in Spain concentrate demand here, compelled by EU AI Act audit trail mandates and the country's central bank operational resilience directives.
- Workflow Automation:Orchestrates cross-application business processes through visual design tools that minimize custom code requirements. Healthcare providers in the United Kingdom and retail distributors in Japan are expanding fastest, responding to NHS digital transformation targets and the country's labor shortage in integration specialists.
- Data Integration:Synchronizes batch and streaming data flows between ERP, CRM, and data warehouse endpoints with schema mapping and transformation engines.
- Platform Integration:Delivers unified middleware stacks combining API, data, and workflow capabilities for enterprises consolidating vendor relationships.
Revenue concentrates in API Management; expansion accelerates most steeply in Workflow Automation.
End User:
Organizational scale dictates integration complexity tolerance, internal skill availability, and preferred commercial terms.
- Large Enterprises:Operate heterogeneous IT estates spanning decades of technology investment, requiring mainframe-to-cloud bridging and complex governance frameworks. Demand concentrates among Fortune 500 manufacturers in the United States and energy conglomerates in the Netherlands, where SEC climate disclosure rules and the country's corporate governance code drive system consolidation imperatives.
- Government Agencies:Procure through certified vendor lists with stringent security accreditation requirements and fixed-budget appropriations.
- SMBs:Prioritize low-code interfaces and pre-built connectors over customization depth, favoring subscription pricing over capital expenditure.
- Educational Institutions:Deploy integration platforms to unify student information systems, learning management platforms, and research data repositories.
Deal value peaks with Large Enterprises; subscription velocity climbs fastest among SMBs.
Service Type:
Engagement model selection reflects internal integration competency and the strategic importance of time-to-value.
- Implementation:Encompasses platform configuration, connector development, and production cutover support for complex deployment scenarios. Demand clusters among Canadian provincial healthcare authorities and Brazilian financial institutions modernizing legacy core systems, shaped by Health Canada interoperability guidelines and the country's central bank instant payment infrastructure deadlines.
- Managed Services:Transfers ongoing platform operations, monitoring, and incident response to vendor or partner teams. Growth concentrates in France and South Korea, where IT outsourcing maturity and MFDS regulatory compliance burdens drive operational delegation preferences.
- Consulting:Delivers architecture assessment, vendor selection, and integration strategy definition without implementation execution.
- Support:Provides technical assistance, patch management, and escalation pathways for self-managed deployments.
Revenue weight rests with Implementation; expansion is sharpest in Managed Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal agencies and German automotive manufacturers command the largest procurement volumes for hybrid cloud integration platforms, driven by stringent data sovereignty mandates and legacy system modernization imperatives.
United States
Federal cloud-smart directives and HIPAA-aligned healthcare architectures dominate procurement patterns. NIST 800-53 compliance requirements shape vendor selection across civilian agencies and defense contractors. Hospital networks in Boston and financial services firms in New York deploy API gateways to federate patient records and enable real-time transaction reconciliation.
Germany
Mittelstand manufacturers prioritize operational expenditure treatment for integration infrastructure over capital-intensive deployments. GDPR and the EU AI Act compel enterprises toward platforms with embedded lineage tracking and algorithmic audit capabilities. Industrial clusters in Bavaria and Baden-Württemberg synchronize IoT telemetry from factory floors to central ERP systems through edge-to-cloud orchestration.
United Kingdom
NHS digital transformation targets accelerate workflow automation adoption among healthcare providers facing integration specialist shortages. The Information Commissioner's Office enforces cross-border data routing restrictions that favor hybrid deployment architectures. London-based financial services firms deploy stream-processing layers to reconcile transactions across core banking and fintech endpoints.
Singapore
Financial services regulators mandate multi-cloud distribution to mitigate vendor lock-in and optimize regional latency. The Monetary Authority of Singapore's technology risk management guidelines shape procurement vetting cycles for banking institutions. Technology clusters in the central business district deploy integration workloads across AWS, Azure, and GCP simultaneously.
Australia
Healthcare networks prioritize multi-cloud architectures to satisfy national cross-border data routing restrictions. The Therapeutic Goods Administration and Australian Prudential Regulation Authority impose certification requirements on integration vendors serving regulated verticals. Research institutions in Melbourne and Sydney unify student information systems with learning management platforms through cloud-native middleware.
Cloud Integration Software Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in API management and fragmented competition in workflow automation. Three strategic archetypes dominate: enterprise platform consolidators, low-code velocity specialists, and mainframe-to-cloud bridge providers. Competitive moves concentrate on M&A for capability expansion and strategic partnerships for vertical-specific connector ecosystems.
Within the enterprise platform tier, MuleSoft, IBM, and Dell Boomi exemplify divergent architectural philosophies. MuleSoft anchors API-led connectivity strategies across Salesforce-centric ecosystems. IBM occupies a position in regulated verticals through Watson-augmented data mapping capabilities. Dell Boomi represents the low-code velocity archetype for mid-market buyers through atom-based runtime architecture. These three entities collectively illustrate how vendor selection hinges on whether organizations prioritize ecosystem integration, compliance-heavy bridging, or rapid deployment velocity.
| Leading Market Players |
|---|
| MuleSoft |
| Dell Boomi |
| Informatica |
| SnapLogic |
| IBM |
| Microsoft |
| Oracle |
| TIBCO Software |
| Workato |
| Others |
Supply Flow & Price Mechanics
United States federal agencies and German Mittelstand manufacturers concentrate procurement volumes for hybrid cloud integration platforms, anchoring demand around consumption-based SaaS pricing models that displace perpetual licensing across mid-market buyers.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers while margin pools accumulate in API management add-ons and premium support packages. Three-tier pricing structure across enterprise, professional, and developer levels tracks organization size and integration complexity, with HIPAA and GDPR certification tiers commanding premiums. Pricing pressure stems from open-source alternatives and hyperscaler bundling, compressing standalone vendor margins. SMBs exhibit highest price sensitivity, favoring consumption-based scaling over committed capacity, while regulated enterprises prioritize compliance-grade tiers despite cost premiums.
Supply Chain Analysis
Shortages of Kubernetes-certified integration architects in the United States, Germany, and India extend implementation timelines and inflate professional services costs across deployment projects. Cloud infrastructure draws from AWS, Azure, and GCP data center networks, with runtime dependencies on container orchestration platforms and open-source middleware libraries. Single-source vulnerability concentrates in specialized talent pipelines rather than physical components, exposing projects to certification bottlenecks. Distribution runs through direct vendor sales, hyperscaler marketplaces, and systems integrator partnerships serving vertical-specific implementation demands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of Kubernetes-certified integration architects constrains delivery capacity, propping pricing power for vendors with established training pipelines and certification ecosystems.
For Market Incumbents: Acquire specialist workflow automation firms to fill capability gaps in event-driven orchestration and edge-to-cloud synchronization. Consolidate API management and data integration stacks into unified platforms to defend against hyperscaler bundling threats. Expand vertical-specific connector libraries through channel partnerships with ERP and CRM vendors. For New Entrants and Emerging Players: The premium-to-economy tier gap in healthcare workflow automation presents entry opportunity for low-code platforms with pre-built HIPAA-compliant templates. Target NHS trusts in the United Kingdom and mid-market hospital networks in Australia facing integration specialist shortages. Lead with consumption-based pricing and rapid deployment guarantees to displace incumbent professional services dependencies. For Investors and Strategic Acquirers: The window for entry favors platforms with embedded EU AI Act compliance tooling and native lineage tracking capabilities. Long-term viability hinges on Kubernetes-native architectures and mainframe-to-cloud bridging expertise. Monitor NIST AI risk management framework finalization as inflection indicator for federal procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies API, data, and workflow capabilities to reduce vendor sprawl in Fortune 500 IT estates. |
| Strategic Partnership | ERP and CRM vendor alliances accelerate vertical-specific connector development for healthcare and financial services. |
| Acquisition of Specialist Firm | Event-driven orchestration targets address real-time transaction reconciliation demands in banking. |
| Geographic Expansion | German and Singaporean market entry captures GDPR and MAS technology risk management compliance requirements. |
| Product Launch | Edge-to-cloud runtime releases synchronize IoT telemetry for manufacturing ERP integration. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and healthcare procurement databases formed the secondary backbone, supplemented by trade association reports from software industry consortia. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners validated demand patterns and pricing dynamics. Bottom-up and top-down triangulation reconciled vendor-reported bookings with end-user deployment surveys across deployment models and organization sizes.
Bottom-up modeling aggregated individual segment trajectories while top-down approaches validated against macroeconomic technology spending indicators across the projection horizon. Segmentation dimensions included deployment architecture, solution type, organization scale, and regional regulatory cluster. CAGRs derived from historical growth rate analysis adjusted for technology adoption S-curve positioning and compliance mandate implementation timelines. Forecast inputs incorporated federal cloud-smart procurement velocity and EU AI Act enforcement phase-in schedules.
Underlying measurement precision varies by segment; public cloud and workflow automation carry tighter precision than private cloud and platform integration due to vendor disclosure granularity. Forecasts reflect assumptions regarding Kubernetes adoption curves, regulatory enforcement intensity, and hyperscaler competitive positioning. Material deviation in federal procurement timelines, EU AI Act implementation delays, or open-source middleware maturity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Cloud Management for the Openstack Market
Cloud Computing
Cognitive Cloud Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
Government Cloud Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Italy Cloud Computing Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Cloud Systems Management Software Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Virtual Private Cloud (VPC) Market
Cloud Computing
Cloud Services Brokerage (CSB) Market