
 Computational Medicine and Drug Discovery Software Market | 2026-2036
Computational Medicine and Drug Discovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Computational Medicine and Drug Discovery Software Market Intelligence
Market Context with Strategic Players
Biotechnology firms is broadening as the fastest-expanding end-use vertical for computational drug discovery platforms, displacing traditional pharmaceutical R&D contracting models. Schrödinger, Inc. anchors its position through physics-based molecular simulation engines that command premium licensing terms across large-molecule programs. Exscientia leverages autonomous chemistry capabilities to sustain differentiated partnerships with tier-one biopharmas. Insilico Medicine competes through generative AI architectures purpose-built for novel target identification.
Technical Definition and Structural Segments
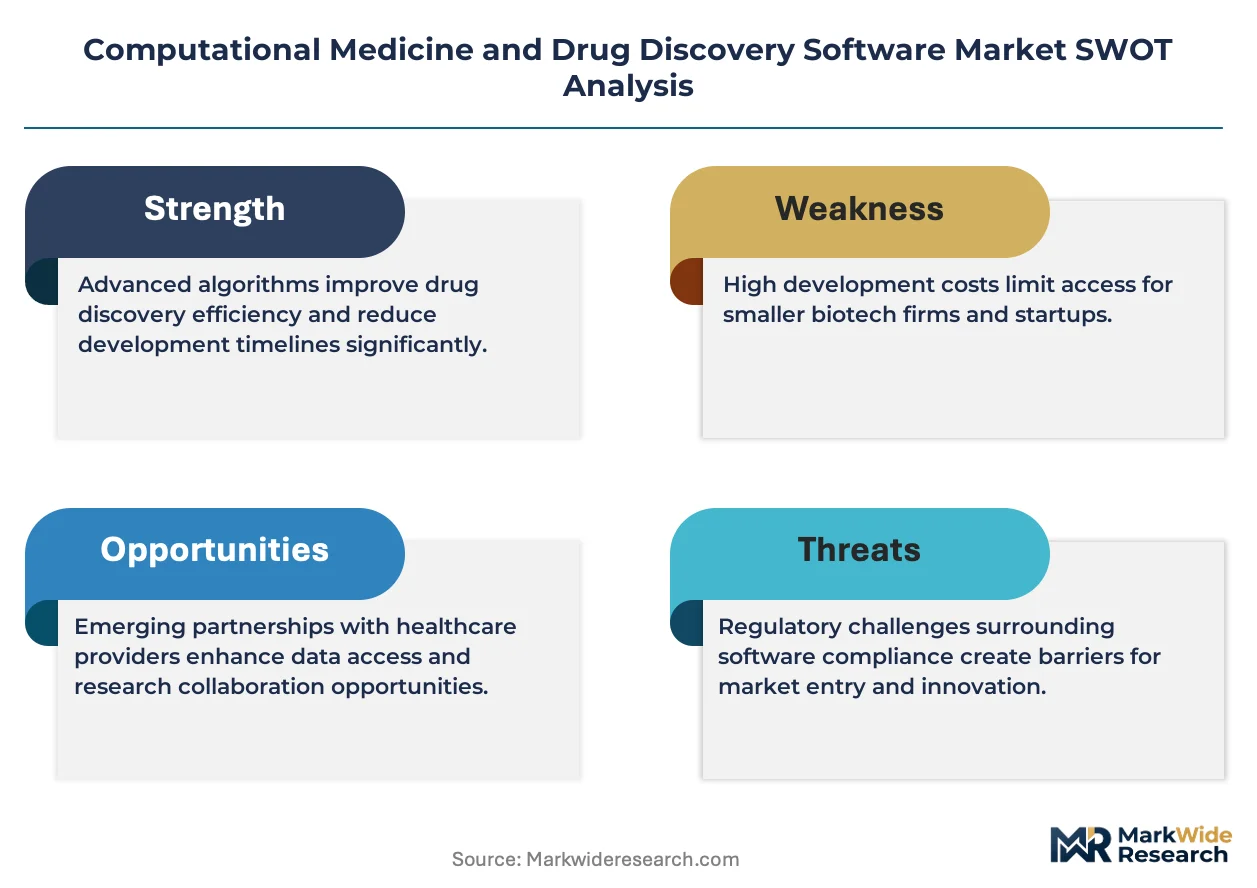
Computational medicine and drug discovery software encompasses algorithmic platforms that integrate cheminformatics, bioinformatics, and machine learning to predict molecular behavior, optimize lead compounds, and model disease pathways at scale. These systems process multi-omic datasets, protein structure data, and clinical outcomes to reduce wet-laboratory iteration cycles in therapeutic development. Machine Learning represents the dominant technology segment, though Network Pharmacology captures expanding interest for polypharmacology and combination therapy design. Cloud-Based delivery models are gaining fastest adoption among mid-sized biotechnology firms seeking elastic compute capacity without capital-intensive infrastructure. Integrated Platforms command the deepest margin pools by bundling predictive analytics, molecular modeling, and data mining into unified subscription architectures.
Regulatory Frame and Forward-Looking Close
FDA's evolving AI/ML-based Software as a Medical Device framework, EMA's qualification opinion pathways for novel methodologies, and ISO 14155 standards for clinical investigation of medicinal products collectively shape validation burdens and market access conditions for computational platforms. REACH and RoHS compliance in Europe adds material disclosure requirements for hardware-dependent deployment scenarios, while HIPAA governs patient data flows in U.S. academic-pharma collaborations. Stakeholders must monitor regulatory convergence between pharmaceutical quality standards and software lifecycle management protocols to anticipate compliance cost trajectories.
Market Dynamics
Generative AI architectures are compressing target identification timelines from years to months, forcing biopharmaceutical firms to restructure R&D contracting models and internal capability stacks around algorithmic prediction engines rather than traditional wet-lab iteration.
Growth Catalysts
- FDA AI/ML SaMD Framework:The FDA's evolving guidance for AI/ML-based Software as a Medical Device is creating validation pathways that accelerate regulatory clearance for predictive clinical tools.
- Cloud Elasticity:Mid-sized biotechnology firms are abandoning capital-intensive on-premise infrastructure for cloud-based delivery models that scale compute capacity with pipeline demands.
- NIH Precision Medicine Funding:Federal precision medicine initiatives in the United States are concentrating procurement clusters around academic-pharma collaborative platforms.
Market Restraints
- Specialized Talent Scarcity:The intersection of computational biology, cheminformatics, and machine learning engineering commands premium compensation that inflates platform operating costs.
- Hardware-Dependent Compliance:REACH and RoHS disclosure requirements in Europe add material certification burdens for deployment scenarios involving specialized GPU clusters.
- Validation Timeline Friction:ISO 14155 standards for clinical investigation of medicinal products create extended qualification periods for novel computational methodologies.
Strategic Opportunities
- EMA Qualification Pathways:The European Medicines Agency's novel methodology opinions offer regulatory tailwinds for platforms demonstrating predictive validity in polypharmacology applications.
- Network Pharmacology Convergence:Integration of multi-omic datasets with graph neural networks is automating combination therapy design for complex disease pathways.
- Academic Licensing Channels:Direct institutional subscriptions bypass traditional pharmaceutical R&D contracting, opening recurring revenue streams from research universities.
Industry Challenges
- Cross-Functional Integration Complexity:Computational platforms must interface with legacy laboratory information management systems that lack standardized API architectures.
- Data Governance Fragmentation:HIPAA compliance for patient data flows in U.S. collaborations conflicts with GDPR requirements in European multi-site trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computational Medicine and Drug Discovery Software Market |
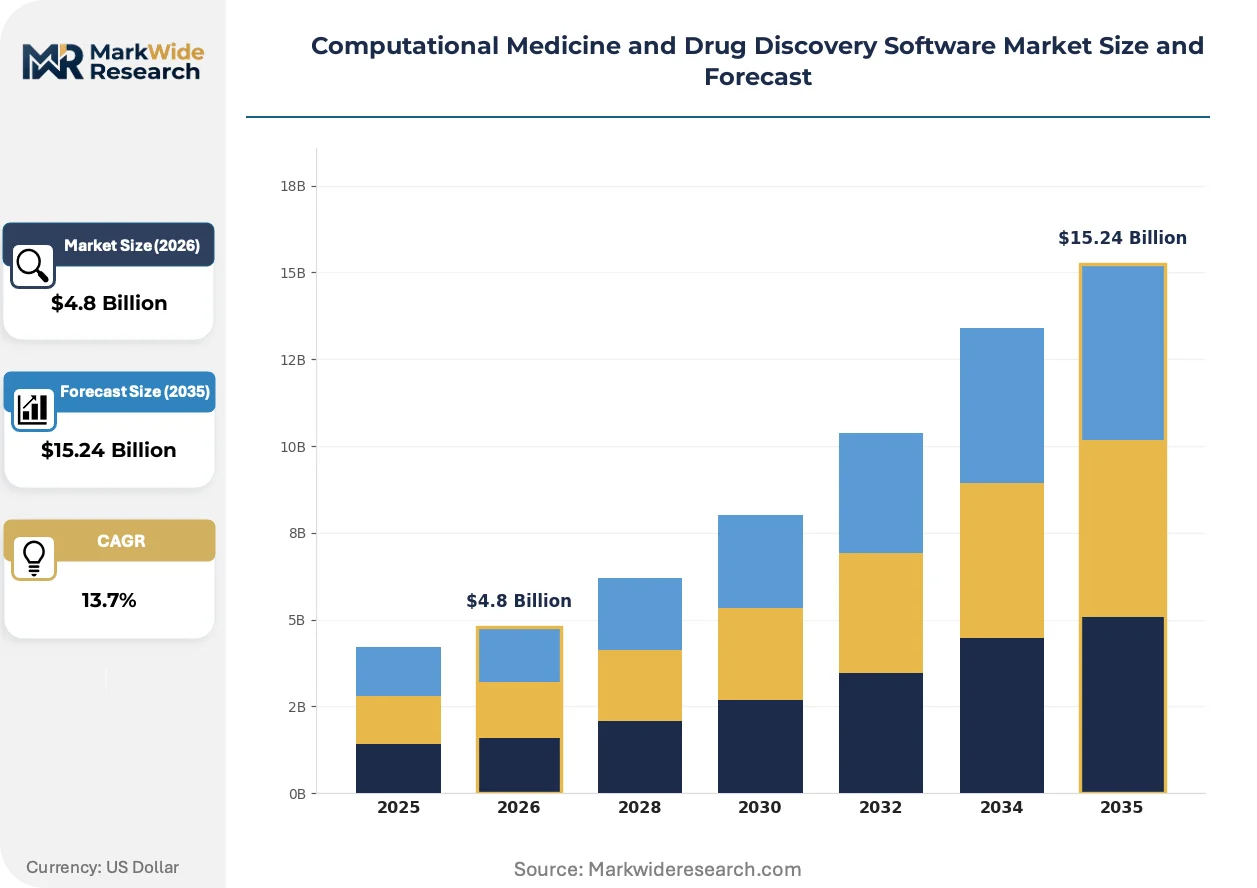
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Analytics, Molecular Modeling, Data Mining, Integrated Platforms Technology: Machine Learning, Genomic Sequencing, Virtual Screening, Network Pharmacology End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Biotechnology Firms Delivery Model: On-Premises, Cloud-Based, Hybrid, Software-as-a-Service |
| Companies Covered | Evotec, Deep Intelligent Pharma, Recursion Pharmaceuticals, XtalPi, Atomwise, Insilico Medicine, Schrödinger, Inc., Evogene Ltd., Exscientia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computational Medicine and Drug Discovery Software Market Strategic Shifts & Innovations
Algorithmic prediction engines are displacing empirical screening as the primary modality for molecular optimization, with platform vendors racing to bundle simulation, generative design, and clinical prediction into unified architectures.
Foundation models trained on protein structure databases are automating de novo therapeutic design for previously undruggable targets. Contract research organizations are adopting these engines to compress lead optimization timelines for sponsor biopharmas. The structural consequence is a shift from fee-for-service chemistry to outcome-validated platform licensing.
EMA's qualification opinion pathways for novel methodologies are forcing vendors to generate prospective validation datasets before commercial deployment. This industrial consequence elevates barriers for early-stage platforms lacking pharmaceutical partner networks. Oncology and rare disease applications face the steepest compliance burdens given the limited natural history data available.
Biopharmaceutical procurement departments are consolidating vendor relationships around integrated platforms rather than point solutions for molecular modeling or cheminformatics. Mid-cap biotechnology firms are driving this consolidation, seeking unified subscriptions that eliminate interoperability costs. The United States exhibits the most pronounced concentration, where NIH funding requirements favor platforms with established academic validation partnerships.
Computational Medicine and Drug Discovery Software Market Segmentation
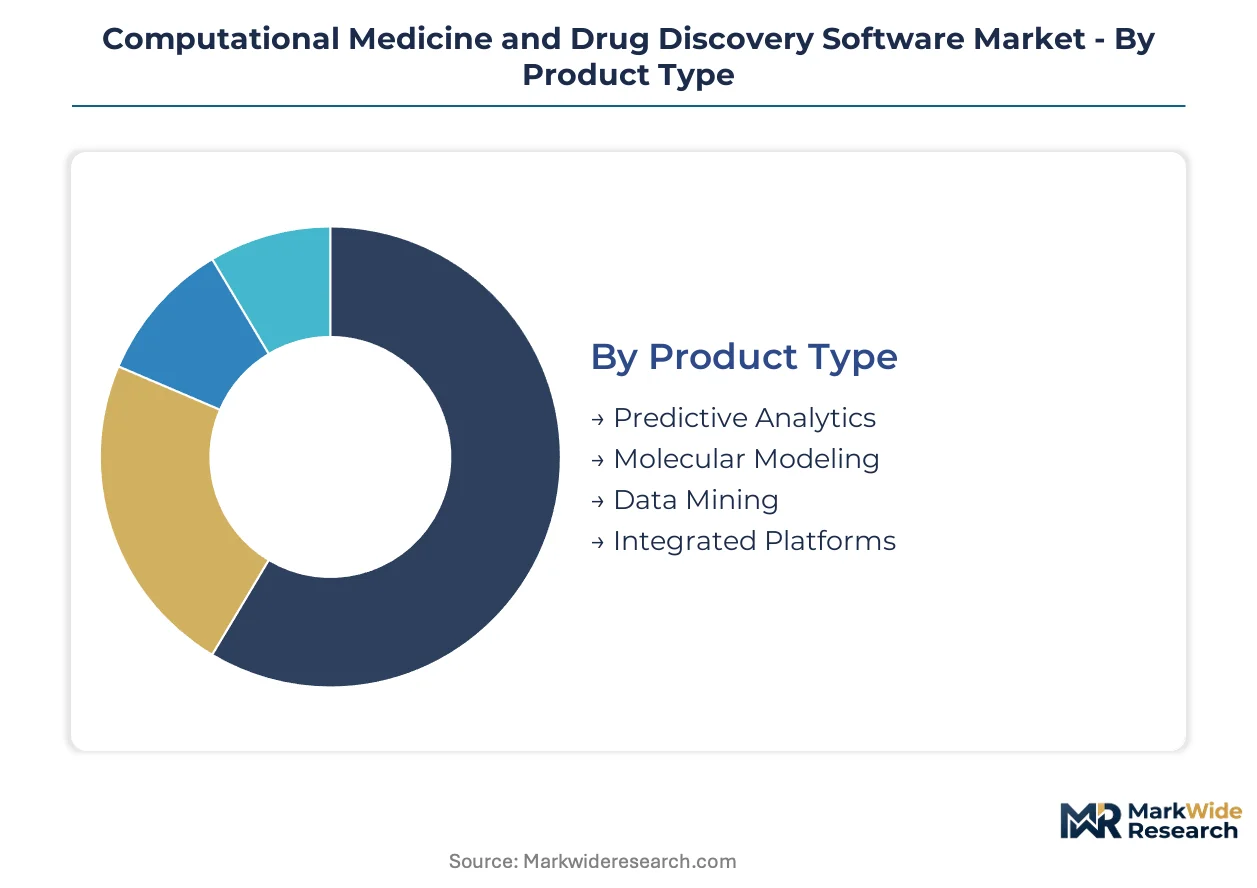
Computational drug discovery software segments reflect divergent buyer priorities across R&D maturity, regulatory burden, and infrastructure legacy. Procurement patterns cluster around unified architectures versus specialized point solutions, with delivery model choices increasingly tied to capital availability and data sovereignty requirements.
Product Type:
Buyer sophistication determines product tier selection, with integrated capabilities commanding premium positioning against modular alternatives.
- Integrated Platforms:Unified subscription architectures bundle predictive analytics, molecular modeling, and data mining into cohesive environments. Pharmaceutical companies in the United States concentrate procurement here, driven by NIH funding requirements that favor validated academic partnerships and reduced interoperability overhead.
- Predictive Analytics:Algorithmic engines process multi-omic datasets and clinical outcomes to forecast molecular behavior and disease pathway responses. Biotechnology firms represent the fastest-expanding demand source, displacing traditional pharmaceutical R&D contracting models with outcome-validated licensing structures.
- Molecular Modeling:Physics-based simulation engines for protein structure prediction and ligand binding affinity calculations.
- Data Mining:Pattern recognition systems extracting therapeutic insights from heterogeneous biomedical databases.
Volume sits with Integrated Platforms; growth tilts toward Predictive Analytics.
Technology:
Technical architecture selection hinges on target class complexity and available training data quality, with polypharmacology applications driving alternative methodology adoption.
- Machine Learning:Dominant algorithmic approach encompassing supervised and unsupervised methods for compound property prediction and target deconvolution. Mid-sized biotechnology firms in the United States drive elastic compute demand through cloud-based deployment, abandoning capital-intensive infrastructure.
- Network Pharmacology:Graph-based methods model drug-target-disease relationships for combination therapy design. Academic institutions concentrate adoption here, attracted by EMA qualification pathways for novel methodologies in complex disease applications.
- Genomic Sequencing:Variant calling and expression analysis pipelines for precision medicine target identification.
- Virtual Screening:Computational filtering of compound libraries against structural or pharmacophore models.
Machine Learning captures the deepest revenue pools; Network Pharmacology exhibits the steepest expansion trajectory.
End User:
Organizational scale and funding source shape procurement modality, with federal research investment creating concentrated demand clusters.
- Biotechnology Firms:Emerging as the fastest-expanding vertical, these organizations adopt cloud-native platforms to compress discovery timelines without legacy infrastructure burden. Federal precision medicine initiatives in the United States channel procurement toward algorithmic prediction engines.
- Pharmaceutical Companies:Large-molecule program sponsors maintain premium licensing relationships with physics-based simulation providers. Internal capability restructuring around generative AI architectures is displacing traditional wet-lab iteration.
- Academic Institutions:Research universities accessing direct institutional subscriptions for cheminformatics and bioinformatics training.
- Research Organizations:Contract research entities adopting platform licensing to shift from fee-for-service chemistry models.
Pharmaceutical Companies anchor current volume; Biotechnology Firms are gaining share fastest.
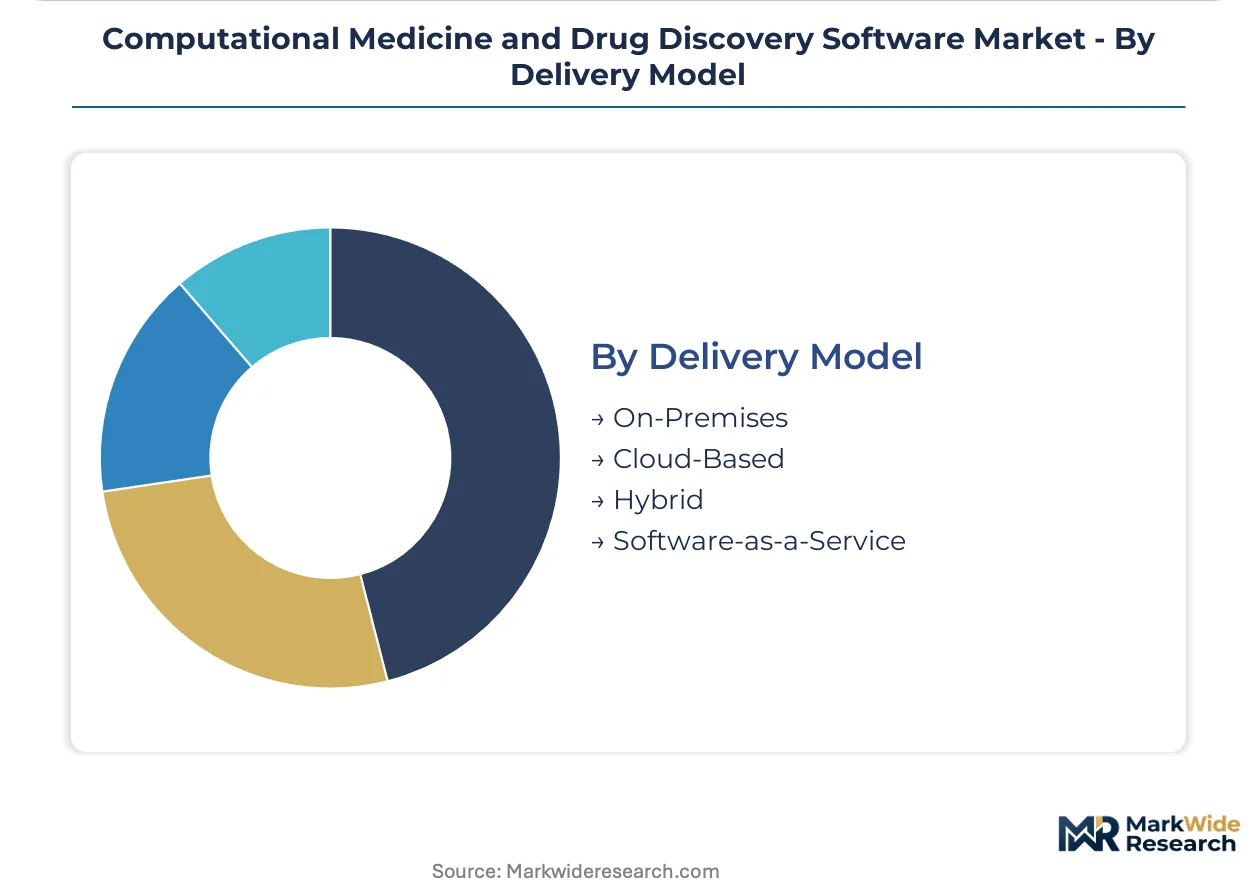
Delivery Model:
Infrastructure ownership preferences reflect capital constraints, data security requirements, and pipeline volatility exposure.
- Cloud-Based:Elastic compute capacity scaling with pipeline demands, eliminating hardware procurement cycles. Mid-sized biotechnology firms across the United States abandon on-premise infrastructure for this model, prioritizing operational flexibility over capital deployment.
- Software-as-a-Service:Subscription access to maintained platform environments with continuous algorithmic updates. HIPAA compliance requirements in U.S. academic-pharma collaborations favor vendors with established security certifications.
- On-Premises:Dedicated hardware deployments for data sovereignty and regulatory audit trail control.
- Hybrid:Mixed architectures segregating sensitive patient data on-premise while leveraging cloud compute for simulation workloads.
On-Premises retains incumbent volume; Cloud-Based demonstrates the most pronounced adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and Kendall Square in Massachusetts concentrate venture deployment for computational drug discovery, drawing talent from MIT, Harvard, and Duke University pipelines into platform development labs.
United States
NIH precision medicine funding channels procurement toward validated academic partnerships, with the Advanced Research Projects Agency for Health accelerating AI-native therapeutic programs. FDA's AI/ML-based Software as a Medical Device guidance reshapes validation requirements for predictive clinical tools. Boston-Cambridge and San Francisco Bay Area clusters host the densest concentration of generative AI platform vendors.
Germany
BioNTech and CureVac alumni populate a specialized talent pool driving autonomous chemistry adoption across mid-sized biotechnology firms. EMA qualification opinion pathways for novel methodologies attract platforms seeking regulatory tailwinds for polypharmacology applications. Munich and Heidelberg industrial corridors concentrate physics-based molecular simulation licensing relationships.
United Kingdom
Exscientia's Oxford headquarters anchors a generative AI ecosystem that supplies tier-one biopharmas with autonomous chemistry capabilities. MHRA's evolving stance on AI-enabled medicinal products creates provisional validation frameworks for prospective clinical datasets. London and Cambridge sub-regions cluster contract research organizations adopting platform licensing to displace fee-for-service models.
China
NMPA's accelerated review pathways for AI-assisted drug discovery compress timelines for domestic biotechnology firms seeking IND clearance. XtalPi's Shenzhen operations exemplify cloud-native deployment at scale for pharmaceutical sponsors. Shanghai and Beijing metropolitan zones concentrate venture capital deployment into network pharmacology platforms targeting combination therapy design.
Switzerland
Roche and Novartis procurement departments consolidate vendor relationships around integrated platforms rather than point solutions for molecular modeling. Swissmedic's alignment with EMA qualification standards reduces friction for novel methodology adoption. Basel and Zurich sub-regions host the deepest premium licensing relationships for large-molecule program sponsors.
Computational Medicine and Drug Discovery Software Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing recurring revenue while point-solution providers face consolidation pressure. The vendor base organizes around three archetypes: physics-based simulation specialists commanding premium licensing terms, generative AI platforms securing outcome-validated partnerships, and cloud-native entrants targeting mid-cap biotechnology elasticity needs. Dominant competitive moves include strategic partnerships with tier-one biopharmas for prospective validation datasets and portfolio diversification into network pharmacology applications.
Within the generative AI tier, Insilico Medicine and Exscientia occupy positions defined by autonomous target identification and chemistry capabilities respectively. Schrödinger, Inc. anchors the physics-based simulation segment through molecular modeling engines. XtalPi represents the cloud-native scale-driven archetype among China-based platform vendors.
| Leading Market Players |
|---|
| Evotec |
| Deep Intelligent Pharma |
| Recursion Pharmaceuticals |
| XtalPi |
| Atomwise |
| Insilico Medicine |
| Schrödinger, Inc. |
| Evogene Ltd. |
| Exscientia |
| Others |
Cost & Logistics Intelligence
Tier-one biopharma procurement departments concentrate demand around validated platform vendors, anchoring pricing power in outcome-validated licensing structures that displace legacy fee-for-service chemistry contracts. Subscription elasticity for cloud-native entrants reflects capital constraints among mid-sized biotechnology firms seeking to avoid hardware procurement cycles.
Pricing Analysis
Short lead-time deployment commands premium subscription tiers, while extended implementation windows unlock standard-economy pricing differentiation across delivery models. Three-tier pricing structure across premium, standard, and economy levels segments by validation depth, with FDA-cleared predictive tools capturing the widest spreads. Cost compression in cloud-native tiers is intensifying because GPU cluster commoditization erodes infrastructure moats. Mid-sized biotechnology firms exhibit the highest price sensitivity; pharmaceutical companies with NIH-mandated academic partnerships show the least.
Supply Chain Analysis
Direct-to-biopharma channels handle hyperscale buyer demand, bypassing traditional contract research organization intermediaries for platform-native licensing. Compute infrastructure concentrates in the United States, Germany, and China, with specialized GPU hardware drawing from Taiwan Semiconductor Manufacturing and NVIDIA supply allocations. Cloud service provider dependencies create single-source vulnerability for elastic capacity expansion. Distribution runs through vendor-direct sales organizations supplemented by academic institution subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA qualification opinion pathways are forcing consolidation among early-stage platforms lacking prospective validation datasets, eliminating vendors without pharmaceutical partner networks. Regulatory burden escalation favors incumbents with established compliance infrastructure.
For Market Incumbents: Hedge against generative AI commoditization by deepening physics-based simulation moats through specialized large-molecule program partnerships. Acquire cloud-native specialists in the United States to capture mid-cap biotechnology elasticity demand before platform-native entrants scale. Certification investment in FDA AI/ML SaMD frameworks protects pricing power against unvalidated open-source alternatives. For New Entrants and Emerging Players: The premium-economy tier gap in network pharmacology applications offers white-space entry for graph neural network platforms targeting combination therapy design. Academic licensing channels in European research universities present the most penetrable segment, bypassing pharmaceutical procurement consolidation. A direct institutional subscription go-to-market angle with EMA qualification pathway support accelerates initial traction. For Investors and Strategic Acquirers: Distressed-cycle entries favor physics-based simulation specialists with established large-molecule program relationships in Germany and Switzerland. Long-term viability across the analysis window rests on regulatory validation depth rather than algorithmic novelty alone. Watch FDA AI/ML SaMD clearance velocity as the primary inflection indicator for platform tier migration.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualification Opinion Pursuit | Regulatory tailwinds from EMA novel methodology opinions accelerate polypharmacology platform commercialization. |
| Academic Partnership Expansion | NIH-funded precision medicine collaborations in the United States create validated procurement channels for integrated platforms. |
| Cloud-Native Architecture Migration | Elastic compute capacity eliminates hardware procurement cycles for mid-sized biotechnology firms. |
| Network Pharmacology Integration | Graph neural network automation of combination therapy design captures complex disease application demand. |
| Generative AI Capability Buildout | Autonomous chemistry engines compress target identification timelines from years to months for tier-one biopharmas. |
Research Approach
Document review covered FDA AI/ML SaMD guidance documents, EMA qualification opinion pathways, and NIH precision medicine funding disclosures, complemented by interviews with computational biology platform executives, biopharma procurement directors, regulatory affairs specialists, and academic technology transfer officers. Secondary validation drew from SEC 10-K filings, ClinicalTrials.gov entries, and cloud infrastructure provider capex disclosures. Bottom-up segment sizing and top-down market reconciliation anchored triangulation across primary and secondary inputs.
Cross-referencing historical adoption curves against expert panel inputs shaped the analytical framework across the analysis window. Segmentation dimensions modeled include deployment model, organization size, therapeutic application area, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption trajectories. Industry-specific forecast inputs incorporated NIH funding allocation patterns and EMA novel methodology opinion issuance rates.
Inputs from FDA guidance repositories and EMA qualification databases were available through the study window; gaps in prospective clinical validation dataset disclosures introduce uncertainty bands around platform revenue projections. Forecasts reflect assumptions regarding regulatory convergence timelines and cloud infrastructure cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Point of Sale (Pos) Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Global Restaurant Management Software Market
Software & Services
Broadcast Scheduling Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Asia-Pacific Text to Speech (TTS) Software Market
Software & Services
Global Programming Software Market
Software & Services
Website Builder Tool Market
Software & Services
Adaptive Learning Software Market
Software & Services
Federal Government Software Market
Software & Services
Europe Business Software Market
Software & Services
Global Audience Response Software Market
Software & Services
ID Photo Software Market
Software & Services
Embedded Software and Tools Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Creative Software Market