
 Photo Editing Software Market | 2026-2036
Photo Editing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Photo Editing Software Market Outlook
Software distribution through traditional retail channels is fragmenting as vendors pivot to direct-to-consumer subscription models and app marketplace placements. Adobe anchors the premium segment through its Creative Cloud ecosystem, while Skylum differentiates through AI-native editing workflows that reduce manual intervention. PicsArt competes aggressively in mobile-first territories, leveraging freemium scale to capture hobbyist and influencer segments before upselling advanced features.
Photo editing software encompasses applications and platforms designed for digital image manipulation, correction, and enhancement through pixel-level operations, layer-based compositing, and algorithmic transformations such as RAW demosaicing and tone mapping. These tools serve commercial photography, digital marketing, and personal creative expression by transforming unprocessed captures into publication-ready assets. Desktop software retains the deepest feature sets for professional printing and high-resolution retouching, while mobile apps capture the fastest growth trajectory as smartphone camera quality converges with social media marketing demands. Online tools occupy an expanding middle ground, enabling collaborative retail marketing workflows without local installation overhead.
The Federal Trade Commission scrutinizes subscription billing practices and automatic renewal disclosures, pressuring vendors toward pricing transparency that shapes customer acquisition economics. California's Consumer Privacy Act and emerging state-level data governance frameworks constrain how cloud-based editing platforms process user-uploaded imagery, elevating compliance costs for online tools and AI-powered features. Stakeholders must weigh the pace of generative AI integration against evolving intellectual property frameworks and user consent requirements that could redefine competitive moats.
Market Dynamics
Cloud-based delivery and AI-powered editing tools are displacing traditional desktop-only workflows, forcing vendors to rearchitect pricing models and feature roadmaps around subscription retention rather than perpetual license margins.
Growth Catalysts
- EU AI Act compliance frameworks:European regulatory clarity on generative AI training data is accelerating enterprise procurement of auditable editing platforms with documented provenance chains.
- Social commerce photography:Small-business sellers on marketplace platforms require batch-editing tools for product imagery, expanding addressable demand beyond traditional creative professionals.
- Neural rendering engines:On-device machine learning in smartphone chipsets enables real-time computational photography that drives upgrade cycles in mobile editing applications.
Market Restraints
- GPU compute cost volatility:Cloud-based generative features depend on NVIDIA and AMD accelerator availability, exposing SaaS vendors to input cost swings that compress gross margins.
- Data localization mandates:China's PIPL and Russia's data sovereignty laws fragment cloud infrastructure, forcing redundant regional deployments that inflate operational overhead.
- Freemium substitution pressure:Mobile-native tools with zero-entry pricing capture hobbyist segments before vendors can establish paid conversion funnels.
Strategic Opportunities
- India's creator economy infrastructure:YouTube and Instagram penetration in tier-2 cities is outpacing editing tool adoption, creating whitespace for localized payment-integrated platforms.
- Generative fill workflows:Convergence of diffusion models with layer-based compositing opens professional retouching applications previously resistant to automation.
- App marketplace distribution:Apple's Small Business Program and Google Play's reduced commission tiers lower customer acquisition costs for independent developers.
Industry Challenges
- Computational photography talent scarcity:Vendors compete for engineers with expertise in RAW demosaicing and tone mapping algorithms, inflating compensation benchmarks.
- Legacy plugin architecture migration:Professional users dependent on third-party extension ecosystems resist platform transitions that break established workflow integrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photo Editing Software Market |
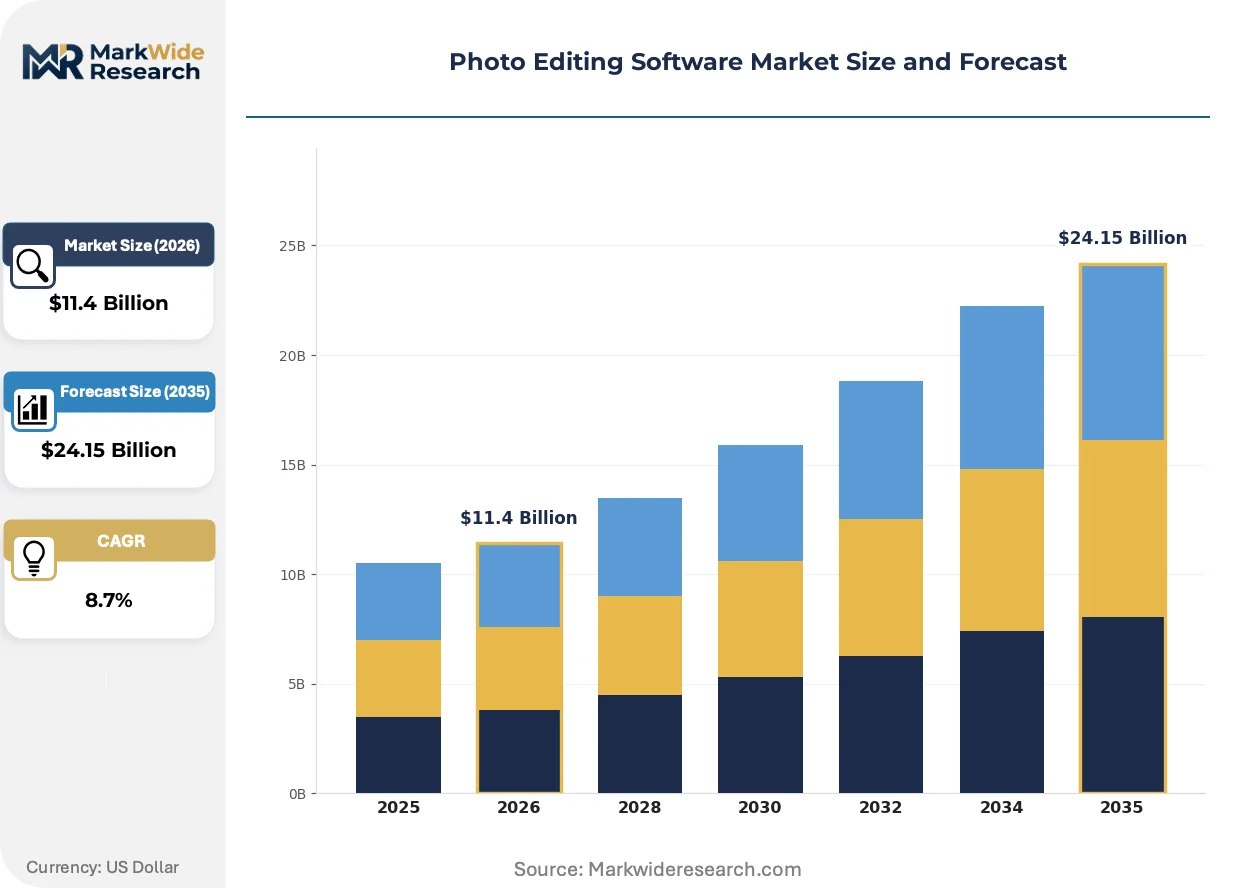
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Mobile Apps, Online Tools, Plug-ins End User: Professional Photographers, Graphic Designers, Hobbyists, Social Media Influencers Use Case: Retail Marketing, Social Media Marketing, Event Photography, Professional Printing Feature: Image Retouching, Color Correction, Filters, Batch Processing |
| Companies Covered | PicsArt, DxO Labs (DxO PhotoLab), Adobe (Photoshop, Lightroom), Topaz Labs, Affinity Photo (Canva), Skylum (Luminar Neo), ON1 Photo RAW, Prisma Labs (Lensa), Capture One, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photo Editing Software Market Strategic Shifts
Generative AI capabilities are compressing the boundary between capture and finished asset, enabling non-specialists to execute production-grade edits while forcing professional tool vendors to defend differentiation through precision control.
Neural network-based editing is hybridizing deterministic pixel operations with probabilistic generation, allowing one-click sky replacement and object removal that previously required manual masking. Wedding photographers and real estate marketers are adopting these features fastest, cutting post-production time by half. The technology is hybridizing subscription tiers as vendors bundle generative credits into premium plans, compressing willingness-to-pay for basic adjustment tools.
California's Consumer Privacy Act constrains how cloud platforms process user-uploaded imagery, requiring explicit consent flows for AI training data usage. Vendors serving enterprise marketing teams face procurement audits demanding documented data handling protocols. The regulation most affects online collaborative tools, which are responding by adding on-premise processing options and regional data residency guarantees.
Content creators are consolidating tool subscriptions as economic pressures force budget scrutiny, favoring all-in-one platforms over specialized point solutions. Influencer agencies now mandate standardized software stacks for contractor compliance, displacing individual preference-based purchasing. This consolidation is most visible in the United States, where creator economy infrastructure supports centralized procurement at talent management firms.
Photo Editing Software Market Segmentation
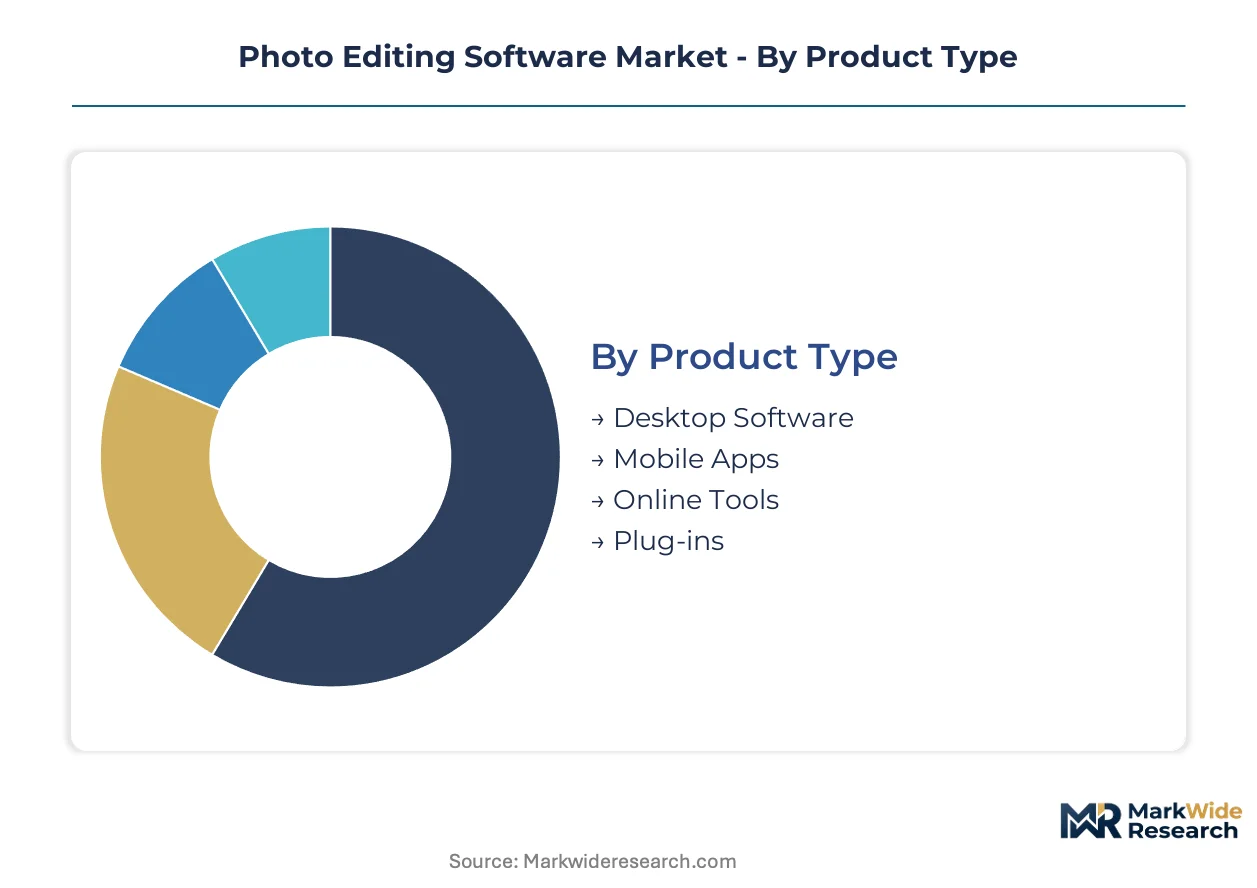
Segmentation reveals how vendor pricing power and retention economics vary across deployment modes and user sophistication levels. Each dimension exposes distinct competitive dynamics, from the subscription mechanics of desktop suites to the freemium conversion challenges of mobile-first tools.
Product Type:
After-sales service intensity diverges sharply across deployment modes, with desktop software demanding technical support and version migration assistance while mobile apps rely on community forums and automated onboarding flows.
- Desktop Software:Full-featured applications installed locally on workstations, offering RAW processing, layer-based compositing, and plugin extensibility for high-resolution output pipelines. Professional studios in the United States concentrate demand here, driven by color-accurate printing workflows and client deliverable standards that cloud rendering cannot yet match.
- Mobile Apps:Touch-optimized editing platforms leveraging on-device neural engines for real-time filters and automated enhancement. Social media influencers in India and Brazil represent the steepest expansion trajectory, as smartphone-first content creation professionalizes without legacy desktop tool investments.
- Online Tools:Browser-based platforms enabling collaborative editing without installation overhead, popular among distributed marketing teams.
- Plug-ins:Specialized extensions adding targeted functionality to host applications, serving niche retouching and effects workflows.
By volume, Mobile Apps leads. By growth pace, Online Tools is gaining share fastest as enterprise procurement shifts toward zero-install collaboration.
End User:
Customer lifetime value stratifies across skill levels, with professionals tolerating higher price points for precision control while hobbyists churn through free trials before converting.
- Professional Photographers:Commercial image creators requiring color-managed workflows, tethered capture support, and non-destructive editing histories for client revision cycles. Wedding and product specialists in Germany and Japan anchor this segment, where reputation-sensitive deliverables justify perpetual license or premium subscription investments.
- Social Media Influencers:Platform-native content creators prioritizing speed-to-publish and template-driven consistency over manual control. This cohort is expanding most quickly across Southeast Asian markets, where short-form video economics reward posting frequency over production polish.
- Graphic Designers:Visual communication professionals integrating photo manipulation with typography and layout workflows.
- Hobbyists:Casual users editing personal imagery with occasional creative projects, exhibiting highest price sensitivity and lowest retention.
Professional Photographers generate highest revenue per account. Social Media Influencers represent the steepest user base expansion.
Use Case:
Application context determines feature prioritization and pricing tolerance, with time-sensitive commercial workflows commanding premium tiers.
- Retail Marketing:E-commerce sellers and marketplace vendors producing standardized product imagery at volume, requiring batch processing and background removal automation. Small-business adoption in the United Kingdom and Australia drives this segment, where platform listing requirements mandate consistent visual presentation.
- Social Media Marketing:Brand and influencer content calibrated for platform-specific algorithms and aspect ratios, demanding rapid turnaround and trend-responsive templates. This application climbs the fastest as platform advertising budgets shift toward creator-driven distribution.
- Event Photography:Wedding, corporate, and sports photographers delivering time-critical galleries with selective retouching.
- Professional Printing:Fine art and commercial output requiring color space management and resolution optimization for physical reproduction.
Retail Marketing leads by transaction volume. Social Media Marketing expands most quickly as brand budgets migrate to creator partnerships.
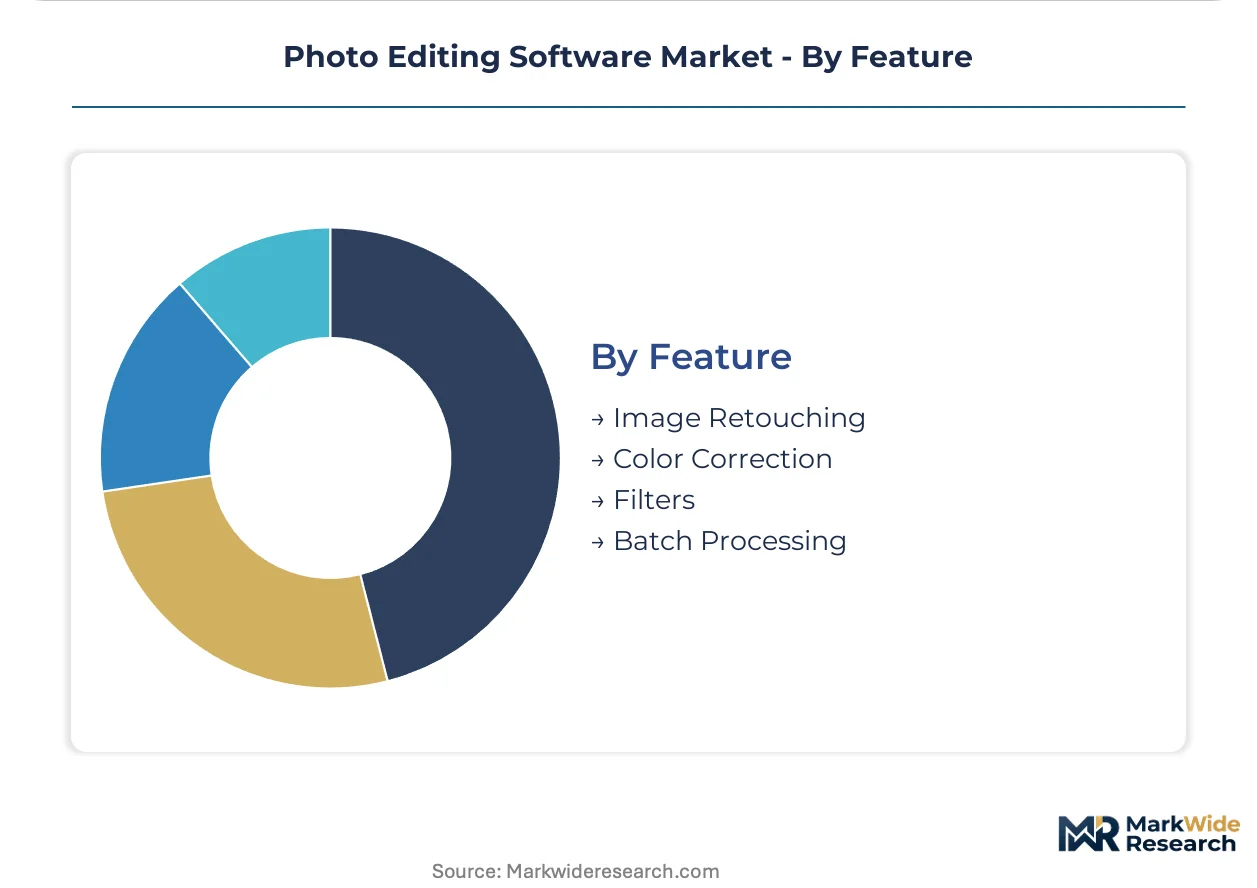
Feature:
Capability bundling shapes tier differentiation, with advanced functions reserved for premium plans while basic adjustments anchor free offerings.
- Image Retouching:Pixel-level manipulation including healing, cloning, and frequency separation for skin and surface correction. High-end portrait studios in France and South Korea concentrate demand here, where manual precision resists full automation despite generative AI advances.
- Batch Processing:Automated application of edits across image sets, essential for event workflows and product catalog production. This capability is gaining adoption fastest among e-commerce operations scaling visual asset production without proportional headcount growth.
- Color Correction:White balance, tone curve, and selective color adjustments for consistent aesthetic output.
- Filters:Preset-driven stylistic transformations requiring minimal user intervention.
Filters dominate by user engagement frequency. Batch Processing shows the steepest enterprise adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subscription pricing power concentrates in the United States while freemium conversion economics dominate emerging markets. Creator economy infrastructure density and venture capital availability explain this asymmetry. Regulatory fragmentation around data residency and AI training consent is forcing redundant platform architectures.
United States
Creator talent management firms in Los Angeles and New York now mandate standardized software stacks for contractor compliance, displacing individual purchasing decisions. The FTC scrutinizes automatic renewal disclosures and subscription billing transparency, pressuring vendors toward clearer pricing architectures. Austin and Seattle host the densest cluster of venture-backed editing platform development.
Germany
Wedding and commercial photography studios in Munich and Hamburg sustain demand for color-managed, print-calibrated workflows. The EU AI Act compliance frameworks accelerate enterprise procurement of auditable platforms with documented training data provenance. Berlin anchors the regional headquarters presence for several major vendors serving European markets.
India
YouTube and Instagram penetration in tier-2 cities like Jaipur and Lucknow outpaces editing tool adoption, creating whitespace for localized payment-integrated platforms. The Reserve Bank of India's recurring payment regulations shape subscription billing mechanics for international vendors. Bangalore and Mumbai concentrate domestic startup activity targeting influencer workflow automation.
China
Short-form video platform economics drive demand for mobile-first editing tools with real-time filter pipelines. The Personal Information Protection Law fragments cloud infrastructure by mandating domestic data residency, forcing redundant regional deployments. Shenzhen and Beijing host the primary engineering centers for computational photography chipset integration.
Brazil
Smartphone-first content creation in São Paulo and Rio de Janeiro professionalizes without legacy desktop tool investments, favoring mobile-native freemium platforms. ANVISA and consumer protection agencies examine subscription cancellation flows and trial-to-paid conversion disclosures. The São Paulo metropolitan area anchors Latin American marketing operations for several global vendors.
Photo Editing Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in narrow workflow functions. The market structure consolidates around three to four ecosystem players with subscription retention economics, while dozens of point-solution vendors compete on feature velocity. Two strategic archetypes dominate: full-stack creative suites bundling photo editing with adjacent design tools, and AI-native specialists automating previously manual retouching tasks. Competitive moves center on generative AI capability integration and mobile-first user acquisition through app marketplace optimization.
Within the full-stack tier, Adobe exemplifies ecosystem lock-in through Creative Cloud subscription bundling, while PicsArt occupies a position in mobile-first freemium scale. Skylum represents the AI-native specialist archetype, anchoring the segment of vendors reducing manual intervention through neural network-based workflows. These three companies collectively illustrate the competitive tension between comprehensive platform breadth and targeted automation depth.
| Leading Market Players |
|---|
| PicsArt |
| DxO Labs (DxO PhotoLab) |
| Adobe (Photoshop, Lightroom) |
| Topaz Labs |
| Affinity Photo (Canva) |
| Skylum (Luminar Neo) |
| ON1 Photo RAW |
| Prisma Labs (Lensa) |
| Capture One |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's dense concentration of computational photography engineering centers and AI accelerator foundries shapes downstream pricing power for generative editing features. Cloud-based vendors drawing from this cluster face margin compression when GPU allocation costs spike, while desktop software publishers retain pricing autonomy through perpetual license anchoring.
Pricing Analysis
The customization-premium spread between configured enterprise deployments and standard individual subscriptions reaches three-to-one in annual contract value. Three-tier pricing structure across premium, standard, and economy levels reflects bundling intensity of AI generative credits and collaborative workspace features. Price differentiation rests on integration depth with adjacent design tools and compliance certification for enterprise procurement audits. Cost compression in the mid-market tier is intensifying because mobile-native freemium platforms capture hobbyist segments before paid conversion funnels mature. Social media influencers exhibit highest price sensitivity, while wedding photography studios in Germany and Japan tolerate premium tiers for color-managed output pipelines.
Supply Chain Analysis
Contract-manufacturing concentration for AI training infrastructure centers on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity for neural processing units. Software distribution draws from engineering talent clusters in the United States, Estonia, and Poland for core algorithm development. Raw material dependencies span NVIDIA H100 accelerators, high-bandwidth memory modules, and cloud compute reservations. Single-source vulnerability around NVIDIA GPU allocation exposes SaaS vendors to input cost volatility that compresses gross margins. Distribution runs through direct-to-consumer app marketplaces and enterprise procurement platforms, displacing traditional retail channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription retention mechanics and generative credit consumption models represent the fastest-expanding recurring-revenue layer, outpacing perpetual license maintenance streams. Service-attach opportunities concentrate in enterprise compliance auditing and workflow integration consulting.
For Market Incumbents: Harden ecosystem lock-in through Creative Cloud-style bundling that increases switching costs for professional users dependent on plugin architectures. Defend against AI-native specialists by accelerating neural rendering integration into established layer-based compositing workflows. Prioritize certification investment for EU AI Act compliance to capture enterprise procurement requiring documented training data provenance.
For New Entrants and Emerging Players: Mid-tier commercial creators in India's tier-2 cities represent the most penetrable entry point, where YouTube and Instagram penetration outpaces editing tool adoption. Mobile-first payment-integrated platforms for short-form video creators in Southeast Asia offer whitespace before incumbent localization. Go-to-market through Apple's Small Business Program reduces customer acquisition costs and accelerates freemium scale.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI-native specialists automating manual retouching tasks previously resistant to workflow compression. Long-term viability across the next decade hinges on generative AI capability integration and mobile-first user acquisition infrastructure. Acquisition target archetype: vertical specialists with established neural network training pipelines for specific use cases like real estate marketing or wedding photography. Watch GPU compute cost volatility as the inflection signal for margin compression across cloud-dependent vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Integration | Diffusion model deployment in layer-based compositing compresses post-production time for wedding and real estate marketers. |
| Mobile-First Platform Launch | Touch-optimized editing with on-device neural engines captures influencer segments in India and Brazil before desktop migration. |
| Enterprise Compliance Certification | EU AI Act auditability opens procurement pipelines for marketing teams requiring documented data handling protocols. |
| Strategic Partnership with Chipset Vendors | Qualcomm and MediaTek neural engine optimization enables real-time computational photography on mid-tier smartphones. |
| Acquisition of Batch Processing Specialist | E-commerce seller workflow automation addresses retail marketing demand for standardized product imagery at volume. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with product managers at editing platform vendors, CTOs at influencer talent agencies, and procurement officers at enterprise marketing teams; and secondary validation through SEC filings, App Annie mobile download analytics, hyperscaler AI infrastructure capex disclosures, and EU regulatory filings. Bottom-up segmentation modeling triangulated against top-down market sizing from trade association estimates.
Forecast inputs across the projection horizon include deployment mode adoption curves, generative credit consumption intensity, and regional creator economy infrastructure maturity. Segmentation dimensions modeled encompass product type, end user sophistication, application context, and feature bundling tier. CAGRs derive from regression analysis of historical subscription pricing power and mobile app monetization trajectories, calibrated against neural rendering engine penetration rates and cloud compute cost elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in venture capital availability for creator economy platforms and GPU accelerator supply constraints would shift the trajectory. Forecasts reflect documented assumptions about freemium conversion rates and enterprise procurement cycle timing. Quarterly review of app marketplace ranking volatility and hyperscaler capex guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
On-Demand Wellness Software Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Test Management Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
Global Email Management Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Global PPC Software Market
Software & Services
Remote Desktop Software Market
Software & Services
K8s Market
Software & Services
Outsourced Software Testing Services Market
Software & Services
CAM Software Market
Software & Services
Global Demand Planning Software Market