
 Adaptive Learning Software Market | 2026-2036
Adaptive Learning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptive Learning Software Market Analysis
STEM teacher shortages across North American public school systems is bifurcating the addressable market into districts with sufficient instructional staff to deploy supplementary tools versus those seeking full-course replacement platforms. Pearson leverages its institutional procurement relationships and assessment heritage to sustain dominant positions in standardized testing-integrated offerings. McGraw-Hill Education anchors its competitive stance through curriculum-aligned adaptive pathways that reduce lesson-planning burdens for understaffed departments. DreamBox Learning specializes in elementary mathematics, occupying a narrow but defensible niche where pedagogical depth outweighs breadth.
Adaptive learning software constitutes algorithm-driven educational platforms that continuously assess learner performance through item response theory and knowledge-space modeling, automatically adjusting content difficulty, sequencing, and presentation modality in real time. These systems serve commercial and institutional purposes by reducing instructor workload while delivering measurable competency gains through personalized pacing. Cloud-based deployment configurations are capturing the fastest expansion as districts abandon capital-intensive on-premises infrastructure, though SaaS models concentrate margin pools through recurring subscription economics. K-12 solutions maintain volume leadership while corporate training systems represent the emerging growth frontier as reskilling mandates intensify across regulated industries. Machine learning and artificial intelligence technologies underpin differentiation, with data analytics capabilities increasingly table stakes rather than premium features.
FCC E-Rate funding allocations shape district technology procurement capacity in the United States, while the EU AI Act's transparency requirements for high-risk educational applications are forcing architectural redesigns among vendors seeking European market access. India's BIS cloud security standards and data localization directives under the Digital Personal Data Protection framework are creating compliance thresholds that favor established providers with dedicated legal-technical teams. Stakeholders must monitor how rapidly evolving algorithmic accountability regimes will redistribute competitive advantage between incumbents with compliance infrastructure and nimble challengers betting on regulatory arbitrage.
Market Dynamics
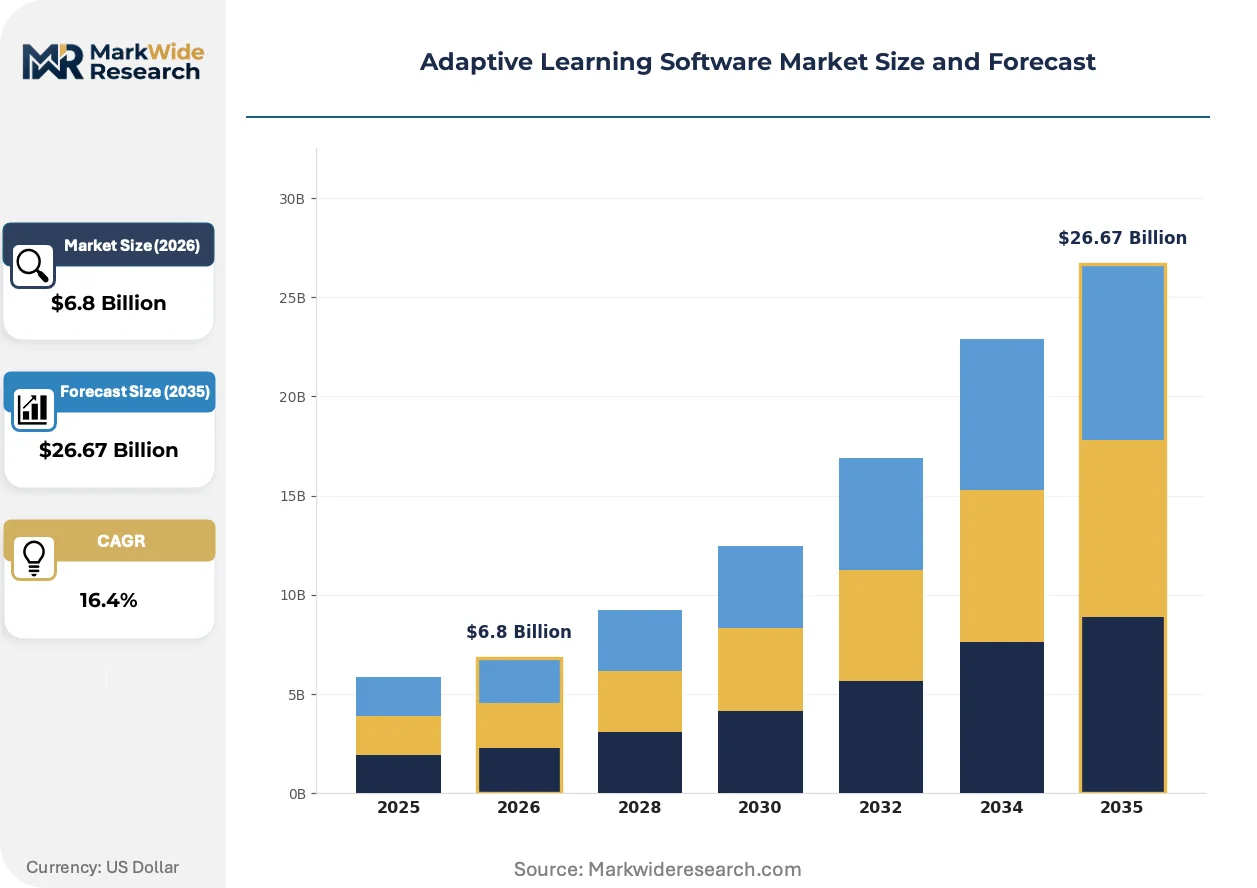
Cloud-based deployment architectures are compressing district procurement cycles while concentrating vendor margin pools through recurring subscription economics, fundamentally restructuring how K-12 institutions acquire and scale educational technology infrastructure.
Growth Catalysts
- FCC E-Rate funding:United States school districts leverage this program to subsidize broadband infrastructure and device procurement, expanding addressable budgets for intelligent tutoring platforms.
- EU AI Act transparency mandates:European educational algorithm deployments face new disclosure requirements that favor established vendors with dedicated compliance infrastructure.
- Knowledge-space modeling:Advanced psychometric engines enable real-time competency mapping that reduces instructor assessment burden while improving learner outcome precision.
Market Restraints
- Data localization compliance:India's Digital Personal Data Protection framework imposes storage restrictions that increase operational complexity for foreign-hosted platforms.
- STEM teacher scarcity:North American public school systems lack sufficient instructional staff to deploy supplementary tools effectively, forcing reliance on full-course replacement platforms.
- Algorithmic audit costs:Third-party validation requirements for high-risk educational applications under EU AI Act Article 52 inflate vendor R&D expenditure.
Strategic Opportunities
- Corporate reskilling mandates:Regulated industries in financial services and healthcare face intensifying workforce competency requirements, expanding demand beyond K-12 into enterprise learning systems.
- Tier-1 city convergence:Mumbai, Bangalore, and Delhi combine ed-tech infrastructure investment with national digital literacy campaigns, creating concentrated adoption clusters.
- Item response theory integration:Convergence with natural language processing enables adaptive assessment of open-ended responses, opening humanities and social sciences applications previously resistant to algorithmic personalization.
Industry Challenges
- Learning engineer scarcity:The specialized intersection of psychometrics, software architecture, and instructional design commands premium compensation that strains mid-market vendor hiring.
- Legacy SIS integration:Student information system heterogeneity across districts forces costly custom API development for gradebook synchronization and roster management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptive Learning Software Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Product Type: K-12 Solutions, Higher Education Tools, Corporate Training Systems, Learning Management Systems End User: Students, Educators, Enterprises, Educational Institutions Technology: Machine Learning, Artificial Intelligence, Data Analytics, Gamification |
| Companies Covered | Pearson, McGraw-Hill Education, D2L Corporation, DreamBox Learning, Curriculum Associates, Houghton Mifflin Harcourt, Knewton, Realizeit, Imagine Learning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptive Learning Software Market Emerging Trajectories
Algorithmic accountability frameworks and deployment model evolution are compressing vendor competitive cycles while elevating data governance capabilities from premium differentiators to baseline procurement requirements.
Edge computing architectures for adaptive learning are miniaturizing. District IT departments deploy lightweight inference engines directly on Chromebooks and tablets to reduce latency for real-time difficulty adjustment. This distributed processing model is compressing reliance on centralized cloud infrastructure while enabling personalized pacing in bandwidth-constrained environments.
EU AI Act risk classification for educational algorithms is reshaping architectural roadmaps. High-risk system designations trigger mandatory human oversight protocols and ex-ante conformity assessments. Vendors targeting European market access are reengineering feedback loops to embed instructor review checkpoints, particularly affecting mathematics and literacy platforms with automated grading components.
District purchasing departments now unbundle implementation services from software licenses, treating professional development and technical integration as separately negotiated line items. This disaggregation is most visible in United States public school systems where E-Rate reimbursement rules incentivize competitive bidding for each cost category, compressing bundled margin structures that previously subsidized customer success functions.
Adaptive Learning Software Market Segmentation
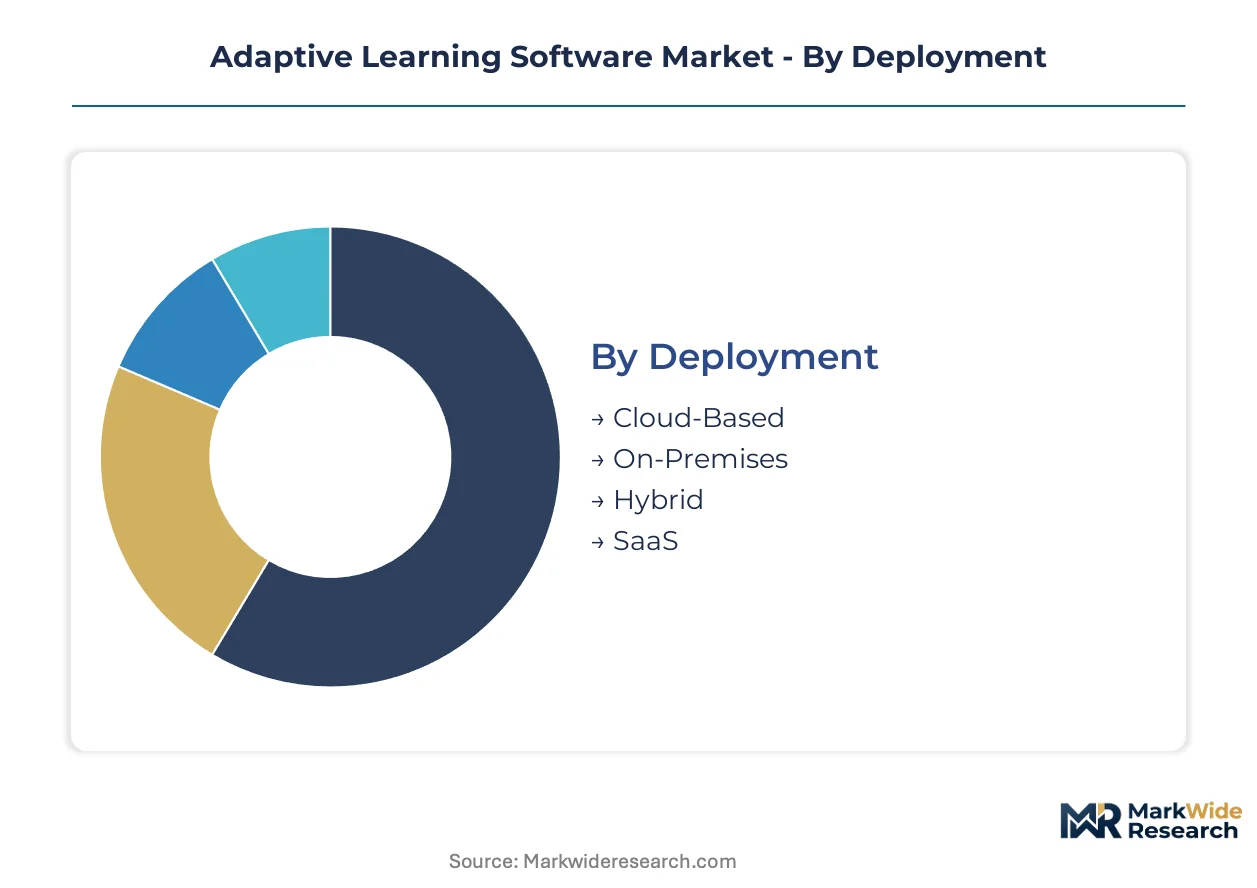
Segmentation in adaptive learning software reveals how algorithmic personalization, institutional procurement patterns, and deployment economics intersect to create distinct competitive battlegrounds. Understanding these divisions exposes where vendor margin pools concentrate and how regulatory pressures reshape segment trajectories.
Deployment:
Cloud-based configurations capture the deepest margin pools through recurring subscription economics and reduced customer acquisition costs.
- Cloud-Based:Fully hosted infrastructure eliminates capital expenditure barriers for budget-constrained districts. United States K-12 systems leverage FCC E-Rate subsidies to accelerate migration from legacy on-premises systems, compressing procurement cycles while locking vendors into multi-year SaaS contracts.
- SaaS:Subscription licensing models concentrate recurring revenue streams and enable rapid feature deployment without client-side infrastructure investment. India's tier-1 city school districts favor this model for its alignment with national digital literacy campaign timelines and minimal IT staffing requirements.
- On-Premises:Self-hosted installations persist in jurisdictions with strict data sovereignty requirements.
- Hybrid:Split architectures balance latency-sensitive inference with centralized analytics aggregation.
Cloud-Based holds installed capacity. SaaS is rotating up the share rankings.
Product Type:
Application-specific solutions generate differentiated pricing power through curriculum alignment depth and assessment integration.
- K-12 Solutions:Elementary and secondary platforms embed item response theory engines for mathematics and literacy competency mapping. North American districts with STEM teacher shortages deploy these as full-course replacements rather than supplementary tools, expanding contract values.
- Corporate Training Systems:Enterprise reskilling platforms address intensifying workforce competency mandates in financial services and healthcare. Regulated industries demand audit trails linking adaptive assessments to compliance documentation, creating premium pricing tiers.
- Higher Education Tools:Post-secondary platforms emphasize plagiarism detection integration and learning management system interoperability.
- Learning Management Systems:Broad platforms incorporate adaptive modules as feature differentiators against standalone specialists.
K-12 Solutions holds installed capacity. Corporate Training Systems is climbing the fastest.
End User:
Institutional procurement concentrates volume while enterprise buyers command customization premiums.
- Educational Institutions:Schools, colleges, and universities drive standardization through RFP processes that favor established vendors with assessment heritage and legacy system integration capabilities. EU AI Act transparency mandates reshape vendor selection criteria across European member states.
- Enterprises:Corporate learning and development departments prioritize skills gap analytics and credential portability. India's BIS cloud security standards and data localization requirements filter vendor eligibility for domestic headquarters procurement.
- Students:Direct-to-learner subscriptions remain niche, concentrated in test preparation verticals.
- Educators:Individual teacher purchases lack institutional purchasing power and integration support.
Educational Institutions holds installed capacity. Enterprises is expanding most quickly.
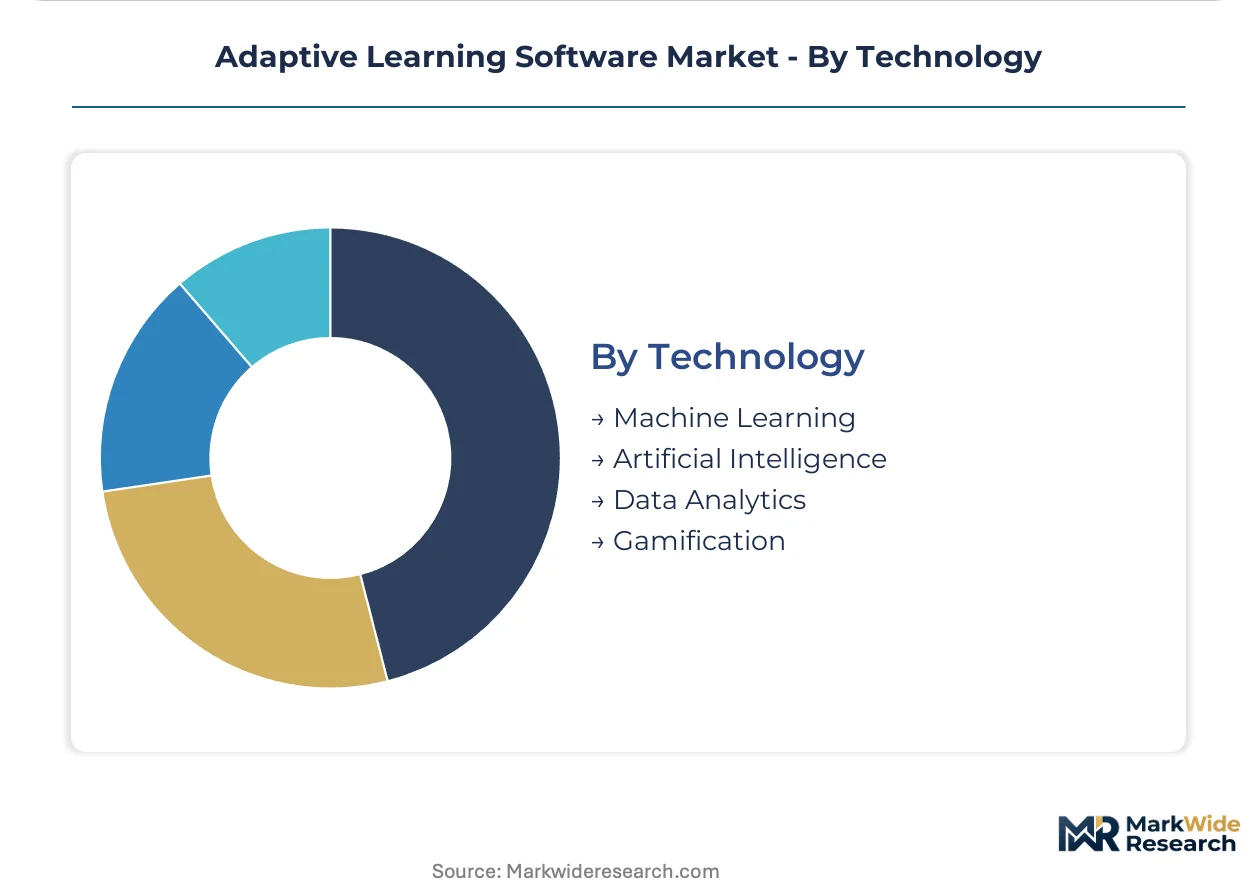
Technology:
Core algorithmic capabilities determine product differentiation and R&D intensity requirements.
- Artificial Intelligence:Deep learning architectures power natural language processing for open-ended response assessment, opening humanities and social sciences to adaptive personalization previously resistant to algorithmic methods. EU AI Act high-risk system designations trigger mandatory human oversight protocols for automated grading components.
- Data Analytics:Competency visualization dashboards and predictive dropout modeling have shifted from premium features to baseline procurement requirements. District purchasing departments now treat analytics maturity as a technical qualification threshold.
- Machine Learning:Supervised learning pipelines for difficulty adjustment represent table-stakes functionality.
- Gamification:Behavioral reinforcement mechanics supplement core pedagogy in elementary deployments.
Artificial Intelligence holds installed capacity. Data Analytics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC E-Rate funding allocations anchor procurement capacity in the United States, while the EU AI Act's transparency mandates reshape vendor compliance obligations across European member states. India's BIS cloud security standards and data localization directives create operational thresholds that favor established providers with dedicated legal-technical teams.
United States
K-12 school districts accelerate intelligent tutoring platform procurement through FCC E-Rate broadband infrastructure subsidies. District IT departments leverage these allocations to migrate from capital-intensive on-premises systems toward cloud-based SaaS configurations. STEM teacher shortages in California and Texas public school systems drive demand for full-course replacement platforms rather than supplementary tools.
Germany
Federal state education ministries prioritize curriculum-aligned adaptive pathways that reduce lesson-planning burdens for understaffed STEM departments. The EU AI Act's high-risk system designations trigger mandatory human oversight protocols for automated grading components. Berlin-Brandenburg and Bavaria concentrate pilot deployments of mathematics platforms with embedded instructor review checkpoints.
India
Tier-1 city school districts in Mumbai, Bangalore, and Delhi combine ed-tech infrastructure investment with national digital literacy campaign timelines. BIS cloud security standards and data localization requirements under the Digital Personal Data Protection framework filter vendor eligibility. Maharashtra and Karnataka state education boards favor SaaS models for minimal IT staffing requirements and rapid feature deployment.
United Kingdom
Department for Education procurement frameworks emphasize assessment heritage and legacy system integration capabilities for secondary mathematics and literacy platforms. GDPR compliance infrastructure serves as a technical qualification threshold in district RFP processes. Greater London and the Southeast concentrate adoption clusters where academy trusts standardize on multi-year SaaS contracts.
Japan
METI digital transformation subsidies support corporate reskilling platform procurement in financial services and healthcare sectors. Enterprise learning and development departments prioritize skills gap analytics and credential portability for regulated industry compliance documentation. Tokyo and Osaka metropolitan areas anchor demand for audit trail capabilities linking adaptive assessments to workforce competency mandates.
Adaptive Learning Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in adaptive learning software, with assessment heritage and curriculum alignment depth determining pricing power. The upper tier consolidates around vendors with institutional procurement relationships and standardized testing integration capabilities. Mid-market specialists occupy defensible niches through pedagogical depth in narrow subject domains. Dominant competitive moves include strategic partnerships with student information system providers and geographic expansion through regulatory-compliant cloud infrastructure.
Within the assessment-integrated tier, Pearson and McGraw-Hill Education exemplify vendors leveraging standardized testing heritage to sustain institutional procurement relationships. DreamBox Learning occupies a position among mathematics specialists where algorithmic personalization depth outweighs platform breadth. These three anchors represent divergent strategic postures: comprehensive curriculum alignment, assessment integration, and subject-specific pedagogical depth.
| Leading Market Players |
|---|
| Pearson |
| McGraw-Hill Education |
| D2L Corporation |
| DreamBox Learning |
| Curriculum Associates |
| Houghton Mifflin Harcourt |
| Knewton |
| Realizeit |
| Imagine Learning |
| Others |
Supply Flow & Price Mechanics
Multi-year SaaS subscription contracts lock in both supply access and price visibility for adaptive learning vendors, insulating recurring revenue streams from district procurement volatility while compressing upfront implementation margins across United States K-12 systems leveraging FCC E-Rate reimbursement cycles.
Pricing Analysis
Price spreads between North American and Indian deployments exceed threefold, reflecting divergent data localization compliance costs and IT staffing premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by assessment integration depth and curriculum alignment certification. Cost compression in the economy tier intensifies because cloud infrastructure commoditization erodes hardware differentiation. District purchasing departments in understaffed STEM departments exhibit highest price sensitivity, while enterprise reskilling platforms in regulated industries demonstrate lowest.
Supply Chain Analysis
The United States and India anchor adaptive learning software development, with Ireland and Singapore hosting regional cloud infrastructure for EU and Asia-Pacific data residency compliance. Core algorithmic engines draw from open-source machine learning frameworks, proprietary psychometric item banks, and natural language processing APIs. Single-source vulnerability concentrates in specialized learning engineer talent pools commanding premium compensation. Distribution runs through direct enterprise sales teams for corporate training systems and value-added resellers for K-12 institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive learning software functions as a service-attach opportunity where professional development and implementation consulting layers expand faster than core platform licensing, as districts unbundle implementation services and treat customer success as separately negotiated recurring revenue.
For Market Incumbents: Fortify compliance infrastructure against EU AI Act high-risk system designations by embedding mandatory human oversight protocols into automated grading components. Deepen curriculum alignment investments in mathematics and literacy to defend against full-course replacement platform substitutes. Prioritize API standardization with dominant student information system providers to reduce legacy integration friction. For New Entrants and Emerging Players: Anchor in corporate reskilling mandates across financial services and healthcare, where audit trail requirements for compliance documentation create premium pricing tolerance. Target tier-1 Indian cities combining ed-tech infrastructure investment with national digital literacy campaign timelines. Pursue partnership-led go-to-market strategies with established assessment heritage vendors lacking adaptive algorithmic depth. For Investors and Strategic Acquirers: Narrow pedagogical specialists with proven item response theory engines and defensible elementary mathematics niches represent attractive acquisition targets for platform breadth expansion. Long-term viability hinges on regulatory compliance infrastructure amortization across multiple jurisdictions. Watch FCC E-Rate funding allocation trajectories as inflection indicator for United States K-12 procurement capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Reduces legacy student information system friction for district IT departments. |
| Geographic Expansion | Captures tier-1 Indian city demand through BIS-compliant cloud infrastructure. |
| Strategic Partnership | Accelerates assessment heritage integration with standardized testing ecosystems. |
| Product Launch | Addresses corporate reskilling mandates in regulated financial services sectors. |
| Acquisition of Specialist Firm | Consolidates narrow pedagogical depth in elementary mathematics personalization. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, district procurement databases, and EU regulatory submissions, combining interviews with CTOs, IT procurement officers, platform engineers, and curriculum directors with bottom-up and top-down triangulation across deployment models and end-user segments.
Segmentation dimensions modeled span deployment configuration, product type, end-user category, and core technology stack, with value outputs derived across the analysis window through regression-based extrapolation of subscription renewal rates and implementation service attach ratios.
Underlying assumptions cover FCC E-Rate funding continuity, EU AI Act enforcement timelines, and cloud infrastructure cost curves, with deviation risk concentrated in data localization regulatory expansion and learning engineer talent pool constraints. Recalibration cycles align with material shifts in algorithmic accountability regime implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Middle East HR Payroll Software Market
Software & Services
Staffing Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Account Reconciliation Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Outsourced Software Testing Services Market
Software & Services
Global Gamification Software Market
Software & Services
RIP Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Global Diagram Software Market
Software & Services
PLM Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Meditation Software Market
Software & Services
APAC Interior Design Software Market
Software & Services
Performing Arts Software Market
Software & Services
Global UIUX Software Market