
 Digital Onboarding Platform Market | 2026-2036
Digital Onboarding Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Onboarding Platform Market Insights
Buyer concentration among financial institutions is hardening as regional banks and credit unions consolidate vendor relationships around fewer platforms with broader compliance coverage. Fenergo anchors its position through deep specialization in anti-money-laundry and know-your-customer workflows for banking clients. MANTL competes by dominating the credit union segment with native core banking integrations. Dock differentiates through API-first architecture that extends into embedded finance onboarding for fintech partners.
A digital onboarding platform orchestrates identity verification, document collection, risk scoring, and account provisioning through automated workflows that typically process customer intake in under four minutes while maintaining audit trails for regulatory examination. Integrated Platforms and AI-driven Solutions represent the fastest-expanding segments as enterprises prioritize unified data models over point solutions, while Cloud-based Software deployments capture the deepest margin pools through recurring SaaS revenue structures. Web-based Solutions retain volume leadership in regulated industries where desktop workflows still dominate agent-assisted onboarding.
Banking regulators including the US OCC and FDIC, the EU's EBA under PSD2 and AMLD frameworks, and India's RBI with its digital KYC guidelines collectively shape platform requirements around data residency, biometric consent, and transaction monitoring integration. The EU AI Act adds emerging compliance layers for automated decision-making in credit and identity verification workflows. Stakeholders must weigh the trade-off between proprietary AI model development and regulatory-ready third-party verification services as enforcement patterns solidify across jurisdictions.
Market Dynamics
Cloud migration and AI integration in banking compliance workflows are compressing procurement cycles as financial institutions consolidate around unified platforms with embedded regulatory coverage.
Growth Catalysts
- PSD2 and AMLD frameworks:European banks accelerate platform upgrades to satisfy Strong Customer Authentication mandates and real-time transaction monitoring requirements.
- Embedded finance expansion:Fintech partnerships with non-bank retailers and telecom operators create new onboarding volume requiring API-native infrastructure.
- India:RBI digital KYC guidelines enable video-based identity verification, reducing branch dependency for account opening in tier-2 and tier-3 cities.
Market Restraints
- Data residency mandates:EU GDPR and India's data localization rules fragment cloud architecture requirements, forcing redundant infrastructure deployment.
- Biometric consent complexity:Cross-border regulatory inconsistency on facial recognition storage limits vendor scalability across jurisdictions.
- Core banking integration costs:Legacy system connectivity consumes 40-60% of implementation budgets for mid-tier financial institutions.
Strategic Opportunities
- Credit unions and community banks:Underpenetrated segments in the United States seek modular platforms with native core banking connectivity.
- EU AI Act compliance layers:Automated decision-making audit trails create premium service tiers for credit scoring and identity verification workflows.
- Convergence of blockchain identity and AI risk scoring:Self-sovereign identity pilots in Germany and Singapore open new verification paradigms.
Industry Challenges
- Regulatory technology talent scarcity:Shortage of engineers with combined AI/ML and AML/KYC domain expertise extends implementation timelines.
- Multi-jurisdiction certification overhead:Separate audits for SOC 2, ISO 27001, and regional banking licenses strain vendor operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Onboarding Platform Market |
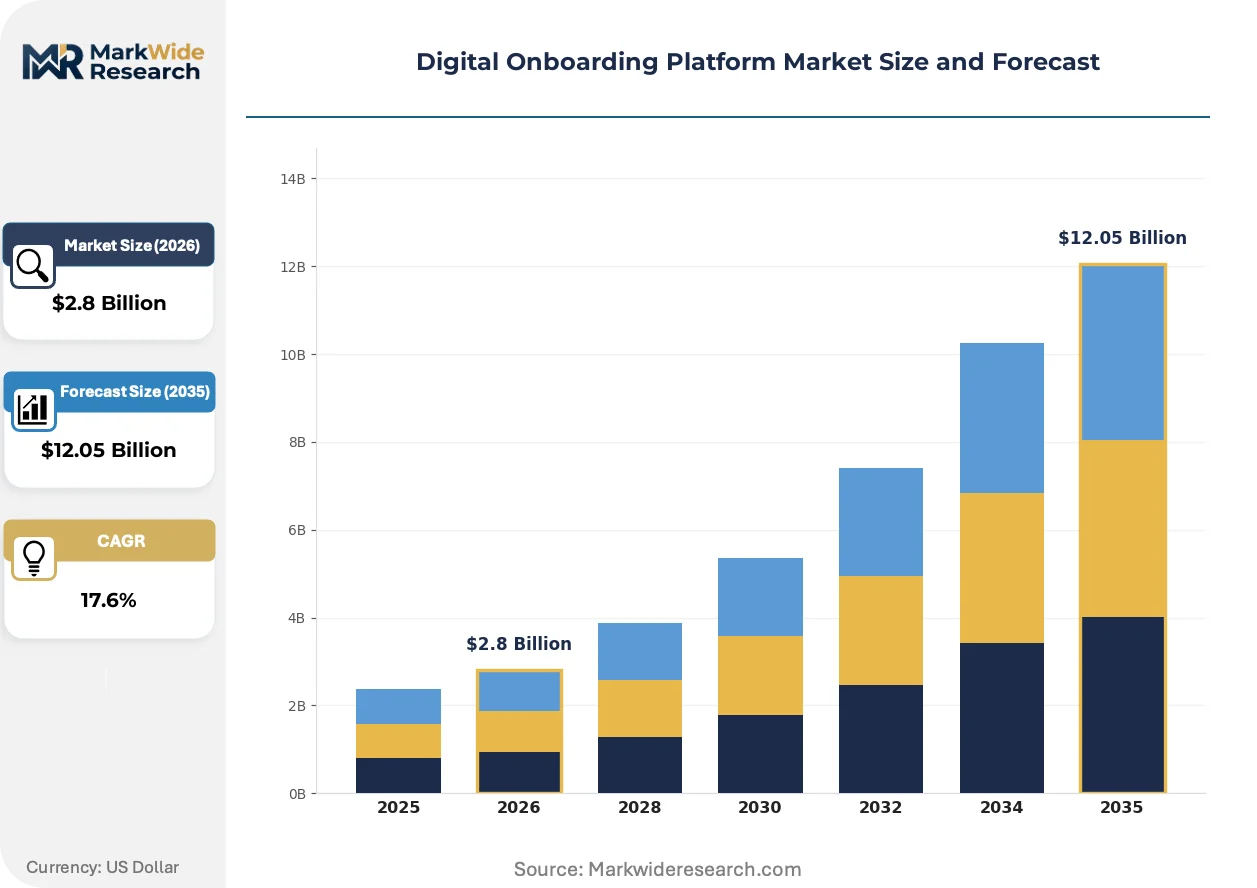
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.05 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-based Solutions, Mobile Applications, Integrated Platforms, Standalone Tools End User: Financial Institutions, Retailers, Healthcare Providers, Educational Institutions Technology: AI-driven Solutions, Cloud-based Software, Biometric Authentication, Blockchain Integration Deployment: On-premises, Cloud, Hybrid, SaaS |
| Companies Covered | OnRamp, Dock, Uniify, Fenergo, MANTL, Pendo, GuideCX, LiveOak Technologies, Onboard.io, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Onboarding Platform Market Trends and Innovations
Artificial intelligence is compressing identity verification from multi-day processes to real-time decisions, while regulatory pressure on algorithmic transparency forces architectural redesign across vendor roadmaps.
Unified data models spanning KYC, AML, and fraud detection is consolidating point solutions into integrated platforms. Regional banks in Germany and the United States are retiring standalone document verification tools in favor of orchestration layers that feed single customer risk profiles. This consolidation is reducing vendor count per institution from five to two in typical procurement cycles.
The EU AI Act's risk classification system for automated credit decisions is mandating explainability layers in machine learning pipelines. Vendors serving European financial institutions must now deploy interpretable models with auditable decision trails. This regulatory pressure is diverging product architecture between EU-facing and non-EU platform variants.
Agent-assisted onboarding via desktop workflows is yielding to mobile-first customer journeys in retail banking. Credit unions in the United States are deploying smartphone-native account opening to capture younger demographics. This channel pivot is visible most acutely in markets where branch density has declined below 20 locations per 100,000 adults.
Digital Onboarding Platform Market Segmentation
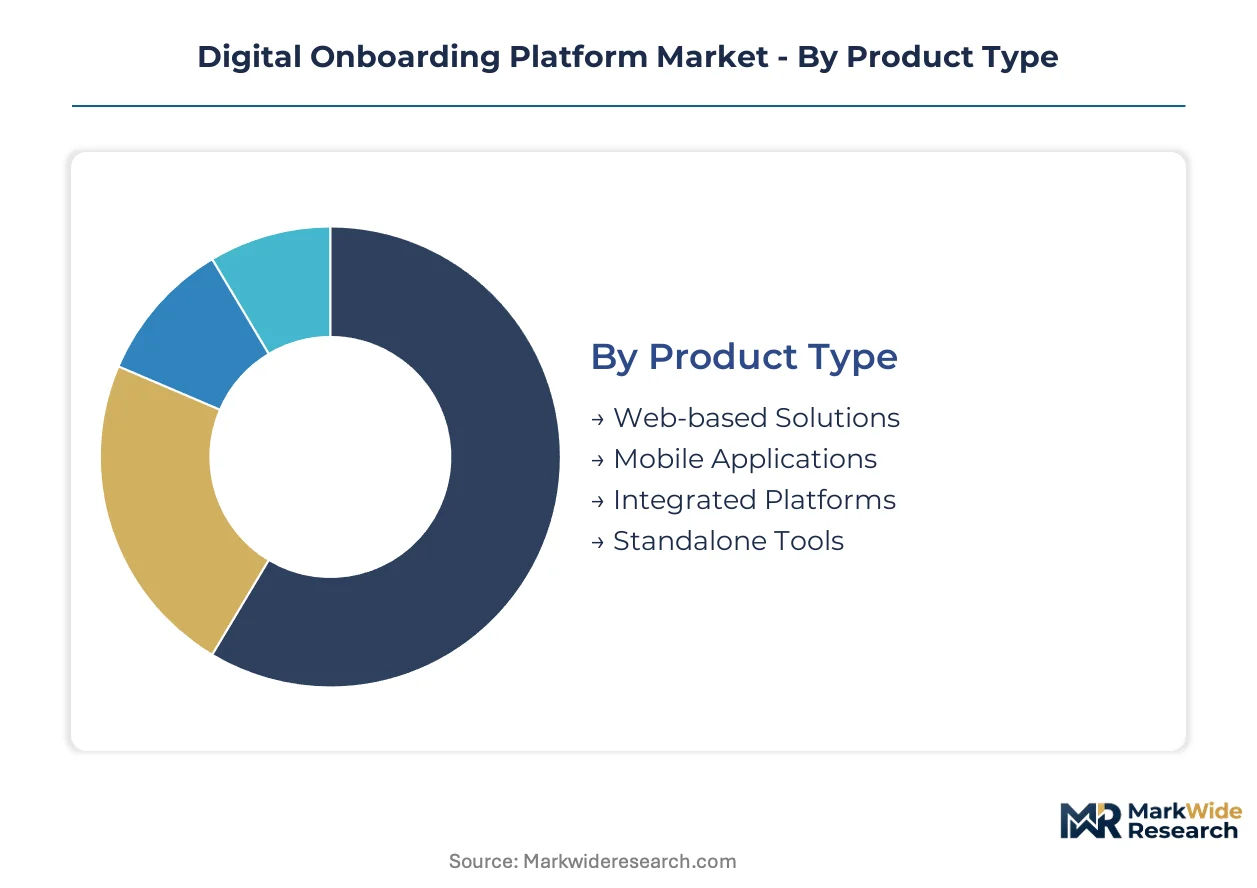
Platform architecture and deployment models determine compliance readiness and integration costs for financial institutions navigating fragmented regulatory requirements. Segmentation reveals where vendor R&D concentrates and which configurations capture premium pricing.
Product Type:
Capital intensity varies sharply across product architectures, with integrated platforms requiring the heaviest upfront engineering investment in unified data models and API orchestration layers.
- Integrated Platforms:Unified orchestration layers connect identity verification, risk scoring, and account provisioning through single customer profiles. Demand concentrates among regional banks in Germany and the United States retiring standalone point solutions for consolidated vendor relationships.
- Mobile Applications:Smartphone-native interfaces with embedded biometric capture and document scanning. Credit unions across the United States deploy these to reach younger demographics in markets where branch density has fallen below 20 locations per 100,000 adults.
- Web-based Solutions:Browser-accessible workflows retaining dominance in agent-assisted onboarding scenarios where desktop environments support complex document review.
- Standalone Tools:Modular components addressing single functions like document verification or liveness detection, increasingly subsumed into broader platform procurement cycles.
Most installed capacity flows through Web-based Solutions. Expansion is steepest in Integrated Platforms.
End User:
Procurement sophistication separates segments, with financial institutions demanding the most extensive compliance certification and audit trail capabilities.
- Financial Institutions:Banks, credit unions, and insurers requiring embedded AML/KYC workflows, regulatory examination support, and core banking system connectivity. India's RBI digital KYC guidelines are accelerating platform upgrades for video-based verification.
- Healthcare Providers:HIPAA-covered entities integrating patient intake with insurance eligibility verification and medical record system access.
- Retailers:Embedded finance partnerships with non-bank merchants and telecom operators demanding API-native infrastructure for white-label account opening.
- Educational Institutions:Student enrollment and financial aid verification workflows with lighter regulatory burdens but growing identity fraud exposure.
Financial Institutions command the deepest vendor engagement. Retailers are climbing the fastest as embedded finance partnerships multiply.
Technology:
Engineering talent scarcity and compute infrastructure costs create divergent investment profiles across technology stacks.
- AI-driven Solutions:Machine learning pipelines for real-time risk scoring and document classification, now requiring explainability layers under the EU AI Act's automated decision-making mandates.
- Cloud-based Software:Multi-tenant SaaS architectures capturing recurring revenue pools, though EU GDPR and India's data localization rules force redundant regional infrastructure deployment.
- Biometric Authentication:Facial recognition and liveness detection systems facing cross-border regulatory inconsistency on storage and consent protocols.
- Blockchain Integration:Self-sovereign identity pilots in Germany and Singapore exploring decentralized credential verification, still pre-commercial at scale.
Cloud-based Software carries the broadest installed base. AI-driven Solutions are gaining share fastest as real-time decisioning becomes standard.
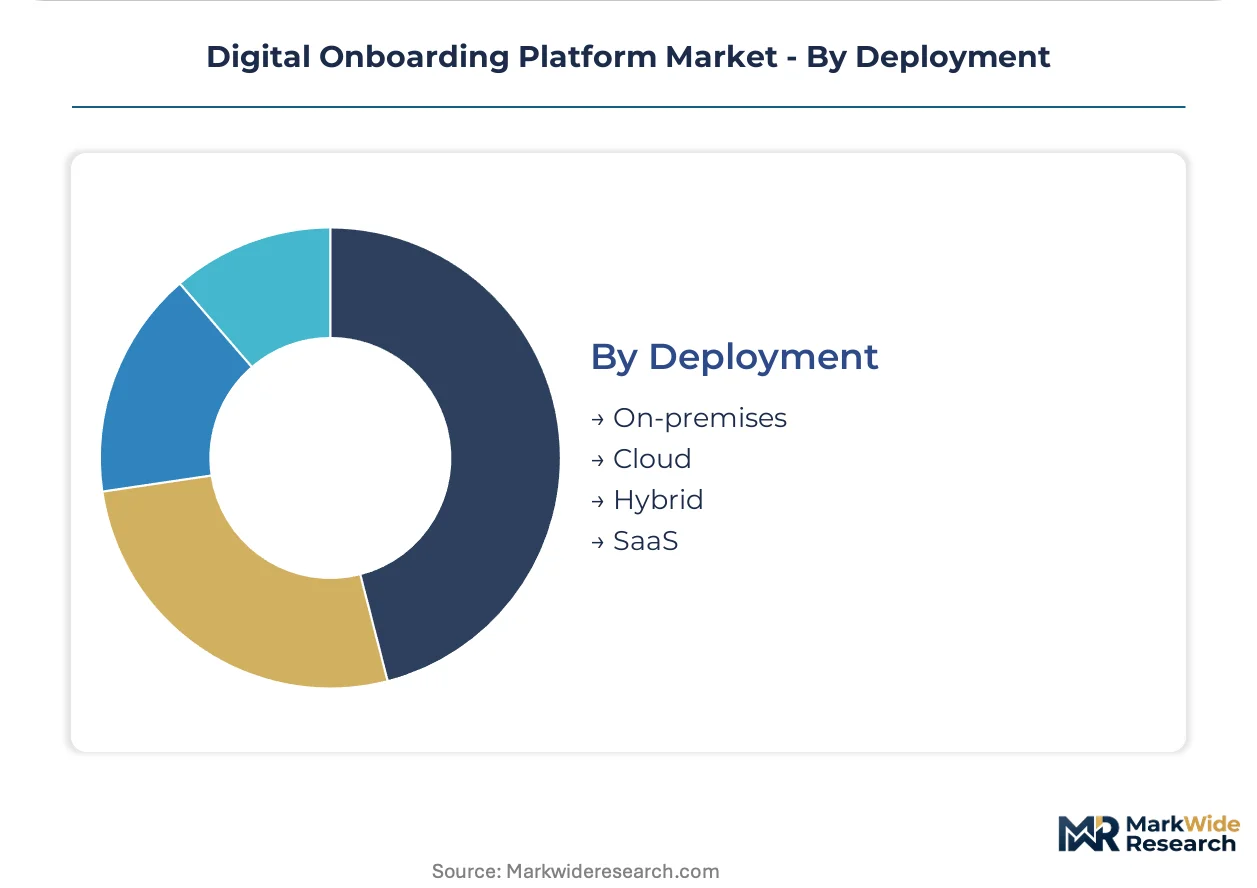
Deployment:
Operational control requirements and data residency mandates shape capital allocation between owned infrastructure and vendor-managed environments.
- SaaS:Fully managed multi-tenant deployments minimizing internal IT burden, preferred by mid-tier institutions lacking dedicated compliance engineering teams.
- Cloud:Single-tenant or private cloud configurations balancing scalability with data isolation, common among European banks navigating GDPR sovereignty requirements.
- Hybrid:Split architectures keeping sensitive biometric data on-premises while leveraging cloud compute for analytics, emerging in jurisdictions with strict localization rules.
- On-premises:Self-hosted installations retaining relevance for institutions with legacy core banking systems requiring direct network proximity.
SaaS deployments represent the dominant configuration. Hybrid models are expanding most quickly as data fragmentation pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and India demonstrate contrasting modernization trajectories, with German institutions consolidating around unified compliance platforms while Indian banks exploit video-based verification to penetrate underserved tier-2 cities.
United States
Regional banks and credit unions drive procurement of modular platforms with native core banking connectivity. The OCC and FDIC examination standards mandate audit trail capabilities that favor established vendors with examination-ready documentation. Texas and California host the densest concentration of fintech partnerships embedding white-label onboarding into retail and telecom channels.
Germany
Sparkassen and cooperative banks retire standalone document verification tools for orchestration layers feeding unified risk profiles. The EU AI Act's explainability mandates force architectural redesign of automated credit decision pipelines. Frankfurt's regulatory technology cluster anchors pilot programs for self-sovereign identity integration with traditional KYC workflows.
India
RBI digital KYC guidelines enable video-based identity verification, collapsing branch dependency for account acquisition in tier-2 and tier-3 cities. Mumbai and Bengaluru fintech ecosystems demand API-native infrastructure for embedded finance partnerships with non-bank distributors. Data localization rules under the Digital Personal Data Protection Act force redundant cloud infrastructure deployment.
United Kingdom
Open Banking mandates under the FCA accelerate platform upgrades supporting real-time account verification and consent management. London's financial services concentration drives demand for multi-jurisdiction compliance coverage spanning EU and Commonwealth regulatory frameworks. Scottish and Northern Irish regional institutions seek cost-effective SaaS deployments minimizing internal compliance engineering overhead.
Singapore
The Monetary Authority of Singapore's digital banking licenses create greenfield onboarding requirements for neobanks without legacy system baggage. Self-sovereign identity pilots with German technology partners explore decentralized credential verification for cross-border wealth management clients. The city-state's data center density supports hybrid deployments keeping biometric data on-premises while leveraging cloud analytics.
Digital Onboarding Platform Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement cycles that increasingly favor unified platforms over point solutions. Market structure tilts toward consolidation as financial institutions reduce vendor counts from five to two in typical implementations. Three archetypes dominate: banking workflow specialists, API-native infrastructure providers, and core-integrated credit union platforms. M&A activity concentrates on acquiring compliance engineering talent, while strategic partnerships with core banking vendors lock in distribution channels.
Within the banking workflow specialist tier, Fenergo and MANTL occupy differentiated positions—Fenergo exemplifying deep AML/KYC domain specialization for Tier-1 institutions, MANTL representing credit union-focused architectures with pre-built core integrations. Dock sits within the API-native infrastructure archetype, anchoring embedded finance distribution through fintech partnership channels rather than direct institutional sales. These three entities collectively illustrate how vendor selection criteria diverge between institutions prioritizing regulatory examination support versus those seeking rapid deployment flexibility.
| Leading Market Players |
|---|
| OnRamp |
| Dock |
| Uniify |
| Fenergo |
| MANTL |
| Pendo |
| GuideCX |
| LiveOak Technologies |
| Onboard.io |
| Others |
Pricing and Supply Chain Analysis
Regulatory technology engineering talent scarcity in Bengaluru and Frankfurt feeds labor-cost differentials that widen pricing-tier spreads between premium compliance-heavy deployments and modular SaaS configurations for mid-tier institutions.
Pricing Analysis
Capacity additions in India's cloud infrastructure zones are reshaping price floors for SaaS deployments as local data center buildouts reduce cross-border hosting premiums. Three-tier pricing structure across premium, standard, and economy levels separates institutions requiring EU AI Act explainability layers from credit unions seeking basic KYC automation. Cost compression in the standard tier is intensifying because hyperscaler competition for financial services workloads is eroding per-seat margins. Credit unions exhibit the highest price sensitivity, while Tier-1 banks absorbing implementation costs for core banking integration show minimal elasticity.
Supply Chain Analysis
Biometric algorithm development rests on specialized machine learning engineering concentrated in the United States, Germany, and Israel. Cloud compute infrastructure draws from hyperscaler regions in Virginia, Frankfurt, and Mumbai, while identity verification data sources feed from government registries and credit bureaus. Single-source vulnerability in liveness detection SDKs creates concentration risk where two vendors dominate facial recognition pipelines. Distribution runs through direct enterprise sales for integrated platforms and API marketplaces for embedded finance infrastructure providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification system for automated credit decisions functions as a regulatory compounder, mandating explainability investments that deepen vendor moats and expand addressable spend among European financial institutions.
For Market Incumbents: Acquire compliance engineering talent with dual AI/ML and AML/KYC domain expertise to compress implementation timelines that currently extend 40-60% over budget due to legacy core banking integration complexity. Anchor defensive positioning through pre-built connectors to Jack Henry and Fiserv cores that lock in credit union switching costs. Vertical integration into video-based identity verification pipelines counters API-native entrants threatening embedded finance channels. For New Entrants and Emerging Players: Begin with modular KYC microservices targeting United States community banks below $10 billion in assets, a segment where vendor consolidation has left white-space for API-first architectures with faster deployment than incumbent integrated platforms. Exploit underpenetration in tier-2 and tier-3 Indian cities where RBI digital KYC guidelines enable branch-light acquisition. Partner with telecom operators as non-bank distribution anchors for embedded finance onboarding volume. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone document verification tool vendors facing subsumption into broader platform procurement cycles as financial institutions reduce vendor counts from five to two. Long-term viability favors orchestration-layer platforms with unified data models spanning KYC, AML, and fraud detection. Watch RBI enforcement patterns on data localization and the EU AI Act's automated decision-making audit trail requirements as inflection indicators for compliance-tech premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies KYC, AML, and fraud detection into single orchestration layers that reduce vendor sprawl for regional banks. |
| Acquisition of Specialist Firm | Absorbs compliance engineering talent with dual AI/ML and regulatory domain expertise scarce in labor markets. |
| Strategic Partnership | Locks distribution through core banking vendor alliances with Jack Henry, Fiserv, and Temenos serving credit unions. |
| Geographic Expansion | Establishes redundant cloud infrastructure in EU and India to satisfy GDPR and Digital Personal Data Protection Act mandates. |
| Product Launch | Deploys EU AI Act-compliant explainability layers for automated credit decisioning that command premium pricing tiers. |
Research Methodology
Direct dialogue with chief technology officers at regional banks, compliance officers navigating OCC and FDIC examination standards, fintech integration specialists, and core banking platform engineers grounded qualitative findings. Secondary validation drew from SEC 10-K filings of publicly traded financial infrastructure providers, RBI circulars on digital KYC implementation, EU AI Act regulatory texts, and hyperscaler financial services vertical disclosures. Bottom-up and top-down triangulation cross-checked deployment volume estimates against aggregate SaaS revenue disclosures.
Top-down macroeconomic drivers and bottom-up vendor capacity assessments converged across the analysis window. Segmentation dimensions modeled include platform architecture type, deployment model, end-user institution category, technology stack, and regional regulatory cluster. CAGRs derived from curve-fitting historical adoption patterns against regulatory mandate timelines and cloud infrastructure investment cycles. Forecast inputs incorporated RBI digital KYC penetration trajectories and EU AI Act compliance cost assumptions.
Caveats apply where enforcement delays in biometric consent protocols or core banking vendor consolidation could materially shift the outlook. Forecasts reflect assumptions on regulatory technology talent availability and hyperscaler data center buildout schedules. A small set of named triggers warrants ongoing watch: RBI data localization enforcement intensity, EU AI Act audit trail mandate timing, and Tier-1 bank core modernization cycle commencement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Restaurant POS Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Global Document Management Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Clinical Communication and Collaboration Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Data Visualization Software Market
Software & Services
Global Student Information System Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Global Virtualization Software Market
Software & Services
Global ERP Software Market
Software & Services
Email Applications Market
Software & Services
Online Lottery Software Market
Software & Services
Pay-Per-Click (PPC) Software Market