
 3D Animation Production Software Market | 2026-2036
3D Animation Production Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Animation Production Software Market Insights
A widening capability gap between cloud-native and legacy on-premise toolchains is reorganizing competitive dynamics among vendors. Autodesk Inc. leverages its Maya and 3ds Max ecosystems to anchor high-budget film and game production pipelines. Adobe Inc. competes through Substance and After Effects integration that extends creative workflow continuity. Maxon Computer GmbH specializes in motion graphics through Cinema 4D, occupying a distinct niche between broadcast design and visualization markets.
3D animation production software encompasses digital toolsets for modeling, rigging, animation, rendering, and compositing of three-dimensional assets, typically requiring GPU acceleration and supporting frame rates from 24 fps cinematic to 60 fps real-time interactive output. The primary commercial purpose centers on enabling studios and independent creators to generate photorealistic or stylized moving imagery for entertainment, advertising, simulation, and immersive media applications. Animation software and rendering software command the deepest margin pools where subscription renewal rates and render-farm compute monetization concentrate value capture. Cloud-based deployment represents the fastest-expanding segment as studios prioritize elastic scaling for peak production cycles and distributed team collaboration across time zones.
The U.S. FCC governs broadcast content standards that shape delivery format requirements for animation outputs, while the EU AI Act introduces compliance obligations for generative AI-assisted animation tools deployed across European production houses. ISO standards for media asset management and interchange formats further constrain product architecture decisions for vendors seeking cross-platform interoperability. Stakeholders must monitor how real-time engine convergence with traditional DCC pipelines reshapes talent requirements and software procurement criteria.
Market Dynamics
Real-time rendering pipelines are compressing production timelines and collapsing the distinction between previsualization and final output, forcing vendors to rearchitect toolsets around GPU-native workflows.
Growth Catalysts
- EU AI Act compliance frameworks:European production houses are procuring generative AI-assisted animation tools with built-in audit trails, creating demand for software with embedded compliance documentation.
- Elastic cloud compute scaling:Studios in Los Angeles and Vancouver are abandoning fixed render-farm infrastructure for consumption-based models that align costs with project peaks.
- Game engine convergence:Unreal Engine and Unity are penetrating film and episodic production, pulling DCC vendors into interoperability partnerships.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in datacenter and workstation accelerators creates procurement risk for studios scaling real-time pipelines.
- Subscription cost accumulation:Per-seat SaaS pricing across multiple specialized tools strains mid-tier studio operating budgets.
- Interchange format friction:Proprietary file formats between Autodesk Maya, SideFX Houdini, and Blender impede asset portability across vendor ecosystems.
Strategic Opportunities
- India's VFX service expansion:Mumbai and Bangalore studios are upgrading from outsourcing execution to full pipeline ownership, requiring enterprise-grade seat licenses.
- Virtual production stage integration:LED volume cinematography is merging live-action and CG workflows, opening tool sales to broadcast and commercial producers.
- ISO 20607 asset management standards:Standardized media interchange protocols are enabling multi-vendor pipeline architectures that reduce single-vendor lock-in.
Industry Challenges
- Real-time technical artist scarcity:The hybrid skill set bridging traditional animation and engine-based lighting is concentrated among senior practitioners in Los Angeles and London.
- Legacy pipeline migration friction:Established studios with decades of scripted automation face rewrite costs when transitioning to cloud-native toolchains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Animation Production Software Market |
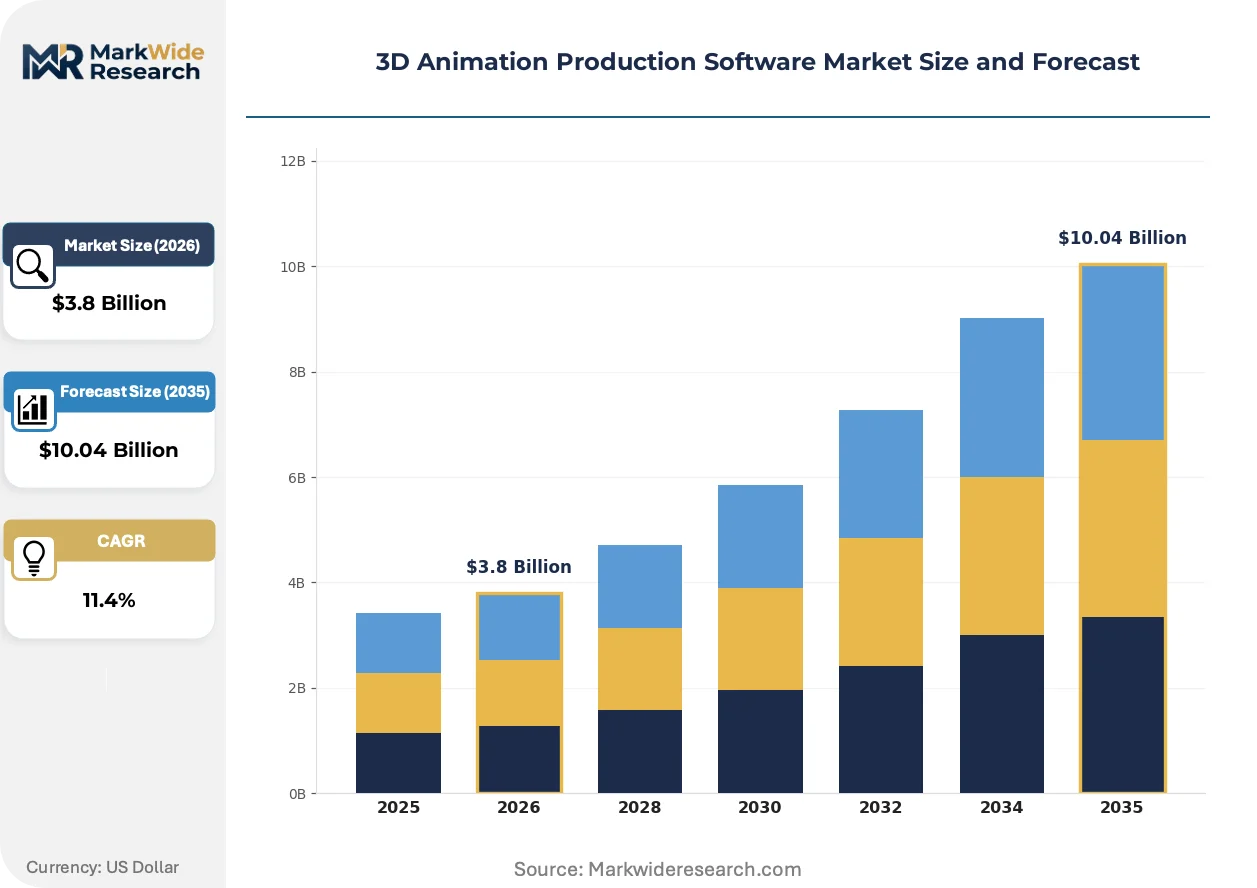
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modeling Software, Animation Software, Rendering Software, Compositing Software End User: Film Studios, Game Developers, Advertising Agencies, Educational Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Subscription Feature: 3D Modeling, Rigging, Motion Capture, Visual Effects |
| Companies Covered | Autodesk Inc., Adobe Inc., Maxon Computer GmbH, SideFX, Corel Corporation, Toon Boom Animation Inc., NewTek Inc., Blender Foundation, Pixologic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Animation Production Software Market Trends and Innovations
Neural rendering and procedural generation are compressing manual asset production hours while regulatory pressure on AI training data is reshaping vendor development priorities.
Neural radiance fields (NeRF) and Gaussian splatting are decomposing the traditional modeling-texturing-lighting pipeline into capture-based workflows. Indie game developers and virtual production supervisors are adopting these techniques faster than established VFX houses. The technology is decomposing the asset creation bottleneck that historically consumed 40-60% of pre-production schedules.
The EU AI Act's transparency obligations for generative training data are forcing European vendors to document source material provenance. Software procurement committees in German and French broadcasters now require audit trails for AI-assisted features. Vendors are responding by segmenting product editions between EU-compliant and unrestricted international builds.
Enterprise buyers are consolidating seat procurement through studio-wide platform agreements rather than departmental point solutions. The channel disruption favors direct vendor relationships over traditional reseller networks for accounts above 500 seats. This pattern is most visible in California and New York where major entertainment conglomerates centralize technology purchasing decisions.
3D Animation Production Software Market Segmentation
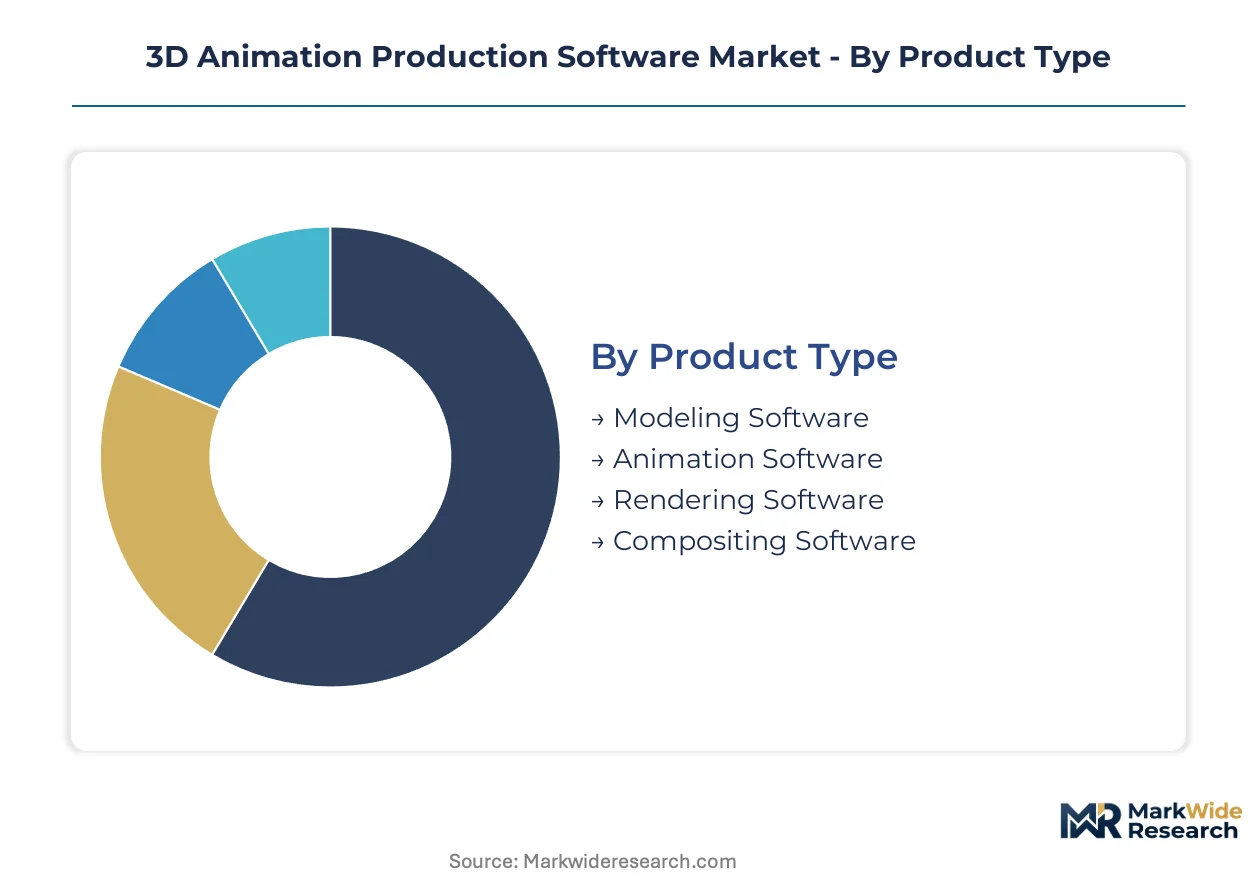
3D animation production software segments by product type, end user, deployment mode, and feature set. Each dimension channels differently through direct vendor relationships versus reseller networks, with enterprise procurement patterns reshaping how Autodesk, Adobe, and Maxon position their offerings.
Product Type:
Channel mix varies sharply across product categories, with rendering and compositing tools flowing through cloud marketplaces while modeling and animation software move via direct enterprise agreements.
- Rendering Software:GPU-accelerated compute engines process ray-traced illumination and final output generation. Los Angeles and Vancouver studios drive elastic render-farm consumption, with peak project cycles forcing procurement toward usage-based cloud models rather than perpetual licenses.
- Animation Software:Timeline-based keyframe and procedural animation systems form the creative core of production pipelines. Game developers in Austin and Montreal are accelerating adoption of real-time-capable toolsets that collapse distinctions between previsualization and final delivery.
- Modeling Software:Polygonal, NURBS, and sculpting toolsets for asset creation.
- Compositing Software:Layer-based image assembly and color correction systems.
Rendering software dominates installed base. Animation software is where expansion concentrates.
End User:
Customer type determines pricing architecture, with film studios negotiating platform-wide agreements while educational institutions access steeply discounted academic tiers.
- Film Studios:High-budget theatrical and episodic production houses operating LED volume stages and traditional green-screen pipelines. California-based majors are consolidating vendor relationships to reduce interchange friction between Maya, Houdini, and Unreal Engine workflows.
- Game Developers:Interactive entertainment studios spanning AAA publishers to indie teams. Real-time engine convergence is pulling this segment fastest toward GPU-native rendering and away from offline farm dependencies.
- Advertising Agencies:Commercial and branded content producers with compressed delivery timelines.
- Educational Institutions:University and vocational programs training next-generation technical artists.
Film studios command the deepest seat volumes. Game developers are gaining share fastest.
Deployment:
Delivery model selection tracks studio infrastructure maturity, with legacy facilities resisting cloud migration while greenfield operations skip on-premise investment entirely.
- Cloud-Based:Browser-accessible or thin-client applications with compute offloaded to vendor-managed infrastructure. Mumbai and Bangalore VFX houses are leapfrogging fixed render-farm investments, adopting consumption-based scaling for peak production cycles.
- Hybrid:Mixed architectures keeping sensitive pre-production on-premise while bursting final rendering to cloud. European broadcasters favor this model to satisfy GDPR data residency requirements while accessing elastic capacity.
- On-Premise:Perpetual-licensed software running on studio-owned workstations and servers.
- Subscription:SaaS pricing with term-based access rather than perpetual ownership.
On-premise retains legacy lock-in. Cloud-based is climbing the fastest.
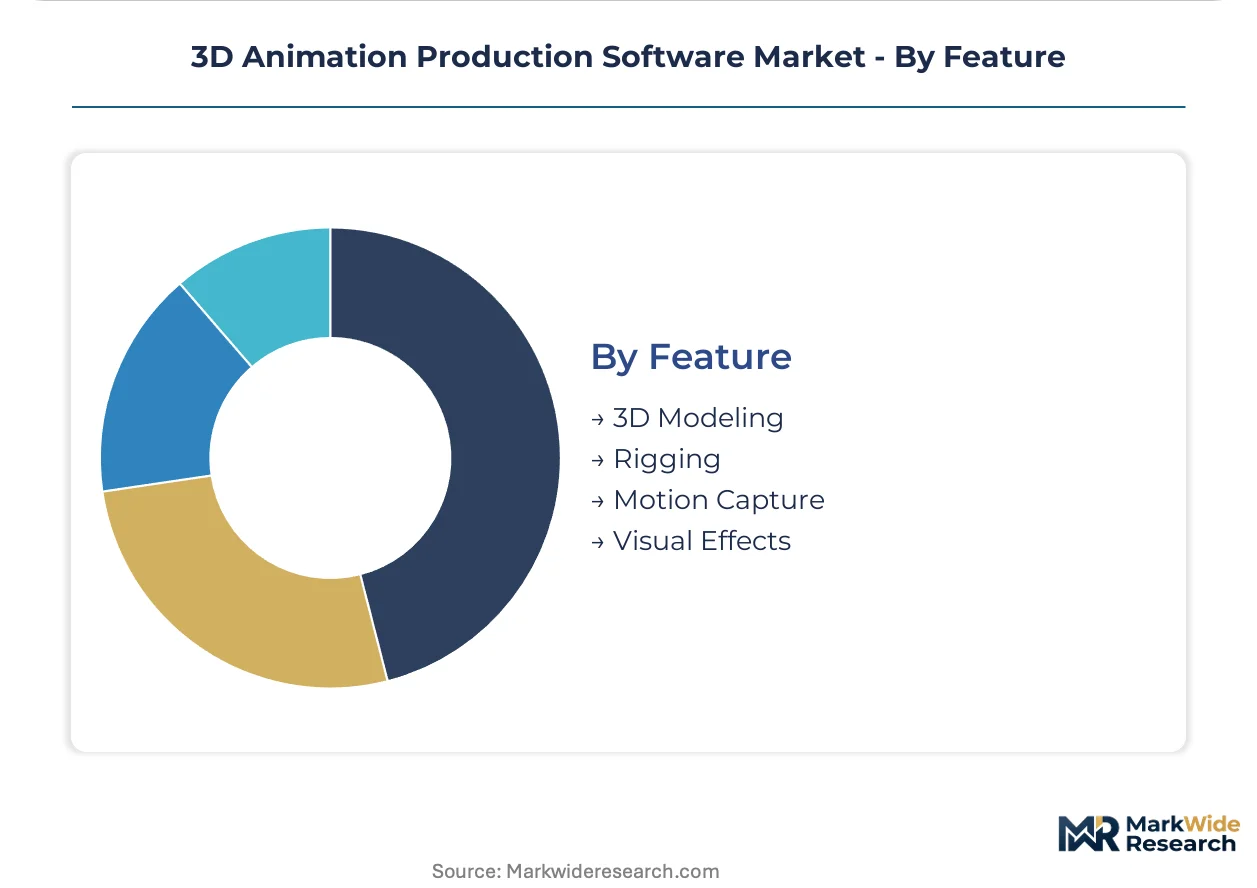
Feature:
Capability bundling reflects workflow integration priorities, with motion capture and visual effects commanding premium pricing due to specialized hardware dependencies.
- Visual Effects:Particle systems, fluid simulation, and destruction toolsets for photorealistic phenomena. London and Wellington facilities specializing in creature work and environmental effects drive concentrated demand for Houdini-integrated solutions.
- Motion Capture:Optical and inertial tracking systems for performance-driven animation. Virtual production stages in Atlanta and London are expanding hardware-software bundled procurement for LED volume cinematography.
- 3D Modeling:Asset creation and sculpting capabilities.
- Rigging:Skeletal systems and deformation controls for character articulation.
Visual effects anchors high-end production. Motion capture is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Los Angeles exceeds that in Mumbai by a factor of three to four, reflecting the concentration of premium studio budgets in California against the cost-optimized service economy of Indian VFX houses. This asymmetry shapes vendor go-to-market strategies across both territories.
United States
Major film studios and technology hubs in California and New York drive premium software procurement for high-budget theatrical production. The U.S. FCC governs broadcast content standards that shape delivery format requirements for animation outputs. Los Angeles facilities specializing in LED volume cinematography are consolidating vendor relationships to reduce interchange friction between toolchains.
United Kingdom
London facilities specializing in creature work and environmental effects concentrate demand for high-end visual effects solutions. The UK Information Commissioner's Office enforces GDPR-aligned data residency requirements that favor hybrid cloud deployment architectures. Soho-based post-production houses are expanding hardware-software bundled procurement for motion capture stages.
Germany
German broadcasters require audit trails for AI-assisted animation features under EU AI Act transparency obligations. The country's national media regulator enforces content standards that influence software compliance documentation requirements. Munich and Hamburg studios are procuring generative AI-assisted tools with embedded provenance tracking.
India
Mumbai and Bangalore VFX houses are upgrading from outsourcing execution to full pipeline ownership, requiring enterprise-grade seat licenses. The country's central bank monitors foreign exchange flows for software import payments affecting procurement timing. Hyderabad facilities are leapfrogging fixed render-farm investments for consumption-based cloud scaling.
Canada
Vancouver studios are abandoning fixed render-farm infrastructure for elastic cloud compute models that align costs with project peaks. Health Canada regulates workplace safety standards affecting motion capture stage operations. Montreal game developers are accelerating adoption of real-time-capable toolsets that collapse previsualization and final delivery distinctions.
3D Animation Production Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium tool developers commanding subscription renewal rates while open-source alternatives capture price-sensitive indie segments. The vendor base organizes around three strategic archetypes: ecosystem incumbents anchoring high-budget pipelines, specialized motion graphics developers occupying broadcast niches, and community-driven projects disrupting mid-tier pricing. Competitive moves center on interoperability partnerships with game engine platforms and cloud marketplace distribution expansion.
Within the ecosystem incumbent tier, Autodesk Inc. and Adobe Inc. represent the anchored position around which high-budget film and game production pipelines organize. Maxon Computer GmbH exemplifies the specialized archetype, occupying a distinct niche between broadcast design and visualization markets with German corporate structure.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Adobe Inc. |
| Maxon Computer GmbH |
| SideFX |
| Corel Corporation |
| Toon Boom Animation Inc. |
| NewTek Inc. |
| Blender Foundation |
| Pixologic Inc. |
| Others |
Pricing and Supply Chain Analysis
Project-based licensing with milestone deliverables locks in supply access for peak production cycles while anchoring price visibility for Los Angeles and Vancouver studios negotiating enterprise agreements. This contract pattern aligns vendor revenue recognition with studio cash flow, reducing procurement friction for cloud render-farm capacity during high-intensity production windows.
Pricing Analysis
The customization-premium spread separates enterprise-configured pipeline integrations from standard seat licenses. Subscription SaaS-tiered models dominate, with price differentiation driven by ISO 20607 certification compliance and render-farm burst capacity allocation. Pricing pressure stems from open-source Blender adoption among indie developers compressing mid-tier margins. Educational institutions exhibit highest price sensitivity; film studios with consolidated vendor relationships show lowest.
Supply Chain Analysis
The United States and Taiwan anchor GPU accelerator fabrication and workstation component assembly for animation production hardware. Software licensing draws from NVIDIA datacenter silicon, cloud hyperscaler infrastructure, and proprietary render engine IP. Single-source vulnerability concentrates around NVIDIA's datacenter accelerator dominance. Distribution runs through direct vendor enterprise agreements for accounts above 500 seats, with cloud marketplaces capturing rendering and compositing tool sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in managed render-farm operations and compliance-documentation layers expand faster than perpetual license sales, creating recurring revenue architectures that improve customer lifetime value. Cloud consumption monitoring and EU AI Act audit-trail services represent the fastest-growing attach categories.
For Market Incumbents: Compound ecosystem lock-in through deeper Unreal Engine and Unity interoperability partnerships that collapse previsualization-to-final-output workflows. Defend against open-source displacement by embedding proprietary AI-assisted features with documented training provenance. Prioritize vertical integration into cloud render-farm infrastructure to capture compute monetization margins. For New Entrants and Emerging Players: Lead with neural radiance field and Gaussian splatting capture-based workflows targeting indie game developers and virtual production supervisors in Atlanta and London. India's upgrading VFX houses from outsourcing to pipeline ownership represent the most penetrable geography. Position through consumption-based cloud pricing that leapfrogs fixed infrastructure investments. For Investors and Strategic Acquirers: Capital is best deployed toward specialized motion-capture hardware-software bundles with LED volume stage integration capabilities. Long-term viability across the next decade hinges on real-time engine convergence and regulatory-compliant AI tooling. Monitor EU AI Act enforcement patterns as the critical inflection signal for vendor compliance investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Autodesk's Maya-Unreal Engine live link reduces interchange friction for Los Angeles studios. |
| Cloud Marketplace Expansion | Adobe's Substance distribution through AWS and Azure captures elastic scaling demand from Vancouver. |
| Compliance Edition Segmentation | EU AI Act audit-trail builds unlock German and French broadcaster procurement committees. |
| Strategic Partnership | SideFX Houdini and Unity interoperability targets Montreal real-time game development pipelines. |
| Acquisition of Specialist Firm | Motion-capture stage operators in London and Atlanta consolidate hardware-software bundled procurement. |
Research Methodology
A spread of perspectives from VFX pipeline supervisors, studio technology officers, cloud infrastructure procurement leads, and game engine integration specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Autodesk and Adobe, hyperscaler capex disclosures, and ISO standards documentation. Bottom-up seat-license modeling triangulated against top-down studio budget allocation surveys.
Segmentation dimensions modeled span deployment mode, organization size, vertical application, integration complexity with game engines, and regional regulatory adoption patterns. CAGRs were derived from elasticity-adjusted demand curves across the projection horizon. Neural rendering adoption curves and virtual production stage deployment rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU AI Act implementation and FCC broadcast standards; material policy shifts would require re-modeling compliance cost burdens and audit-trail documentation requirements. Recalibration cycles align with material shifts in GPU supply availability, real-time engine penetration rates, and cloud consumption billing model adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Stock Footage Software Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
Automated Testing Software Market
Software & Services
Global Microscope Software Market
Software & Services
E-Invoicing Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Vertical Software Market
Software & Services
Design Collaboration Software Market
Software & Services
Global Portal Software Market
Software & Services
Time and Attendance Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Global Membership Management Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Global Proposal Management Software Market