
 Stock Footage Software Market | 2026-2036
Stock Footage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Stock Footage Software Market Insights
North American platform aggregators is repositioning around AI-powered search and automated rights clearance. Shutterstock leverages its proprietary contributor network across multiple content verticals. Adobe Stock anchors its ecosystem through native Creative Cloud integration. Artlist competes on flat-rate subscription models that reduce per-project licensing friction for high-volume users.
Stock footage software comprises digital platforms that license pre-recorded video clips, motion graphics, and archival media through searchable repositories with metadata tagging, resolution scaling, and rights-managed or royalty-free frameworks. These systems serve commercial producers requiring rapid asset acquisition without original filming overhead. Subscription-based service types dominate recurring revenue pools, while enterprise licensing captures the highest per-contract values from broadcast networks and studio conglomerates. Cloud-based deployment is displacing on-premises installations as post-production teams distribute across remote workflows.
The EU AI Act and GDPR shape how automated tagging and facial recognition indexing operate within European platform deployments. The FCC's transparency requirements in the United States influence how sponsored and editorial content must be distinguished in licensed footage. Platform operators must monitor evolving copyright liability frameworks across multiple jurisdictions while calibrating their compliance infrastructure against the pace of generative video synthesis.
Market Dynamics
Cloud-native delivery architectures are compressing production timelines for advertising agencies and post-production houses. The shift from download-and-store workflows to browser-based asset streaming is restructuring how licensed video content moves through creative pipelines.
Growth Catalysts
- EU AI Act compliance frameworks:Automated metadata tagging and facial recognition indexing under GDPR-aligned protocols is accelerating platform investment in European deployments. Broadcast networks require these tools for rapid archival retrieval.
- Subscription monetization models:Flat-rate licensing structures reduce per-project friction for high-volume content creators. Streaming platform producers favor predictable cost structures over per-clip negotiations.
- Remote post-production distribution:Cloud-based collaboration tools enable geographically dispersed editing teams. Post-production houses in the United States, the United Kingdom, and Germany are standardizing on these architectures.
Market Restraints
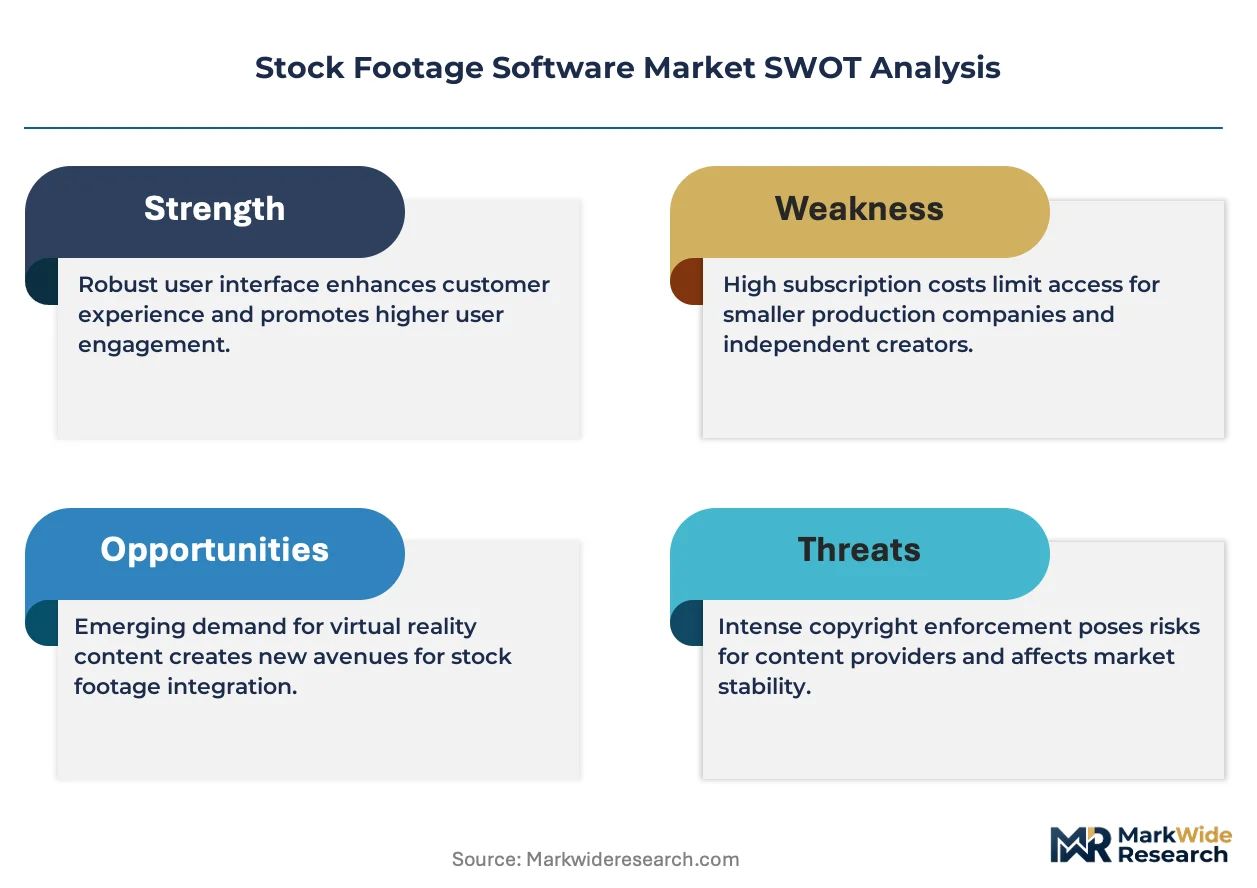
- Contributor network concentration:Exclusive talent agreements with top videographers limit supply elasticity. Shutterstock's proprietary contributor pool creates sourcing bottlenecks for competing platforms.
- Rights clearance complexity:Multi-territorial licensing frameworks generate legal overhead. The FCC's transparency requirements for sponsored content create additional compliance layers for US-distributed footage.
- Generative video substitution:Synthetic media tools threaten demand for traditional stock footage. Adobe's Firefly integration demonstrates how Creative Cloud ecosystems may displace conventional asset licensing.
Strategic Opportunities
- Underpenetrated German mid-market:Regional advertising agencies outside Berlin and Munich lack dedicated stock footage procurement workflows. Localized German-language interfaces capture this whitespace.
- Archival documentary convergence:Historical footage licensing intersects with streaming platform original content strategies. Partnerships with national film archives in the United Kingdom unlock exclusive period content.
- API-first distribution channels:Direct integration with video editing software bypasses traditional marketplace discovery. Artlist's plugin architecture for DaVinci Resolve and Final Cut Pro illustrates this channel innovation.
Industry Challenges
- AI training data provenance:Platform operators face IP disputes over whether contributor-submitted footage was used to train generative models. Contributor contracts require renegotiation to clarify synthetic media rights.
- Resolution scaling infrastructure:4K and 8K delivery demands strain cloud storage and bandwidth economics. Post-production houses in the United States report transcoding bottlenecks during peak campaign periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stock Footage Software Market |
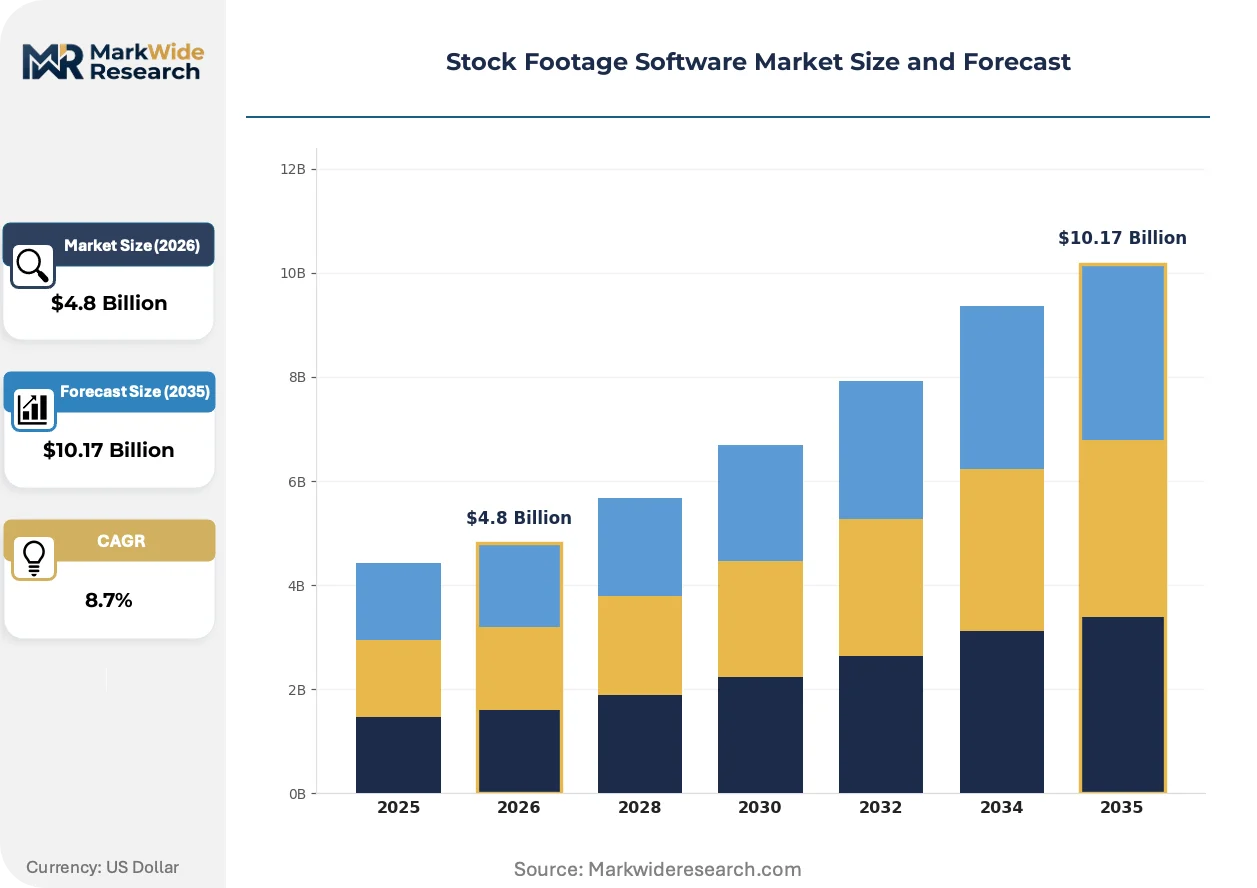
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription Based, One-Time Purchase, Pay-Per-Clip, Enterprise Licensing End User: Filmmakers, Advertisers, Content Creators, Educators Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Feature: Search Filters, Previews, Licensing Options, Download Formats |
| Companies Covered | Shutterstock, Adobe Stock, Getty Images, Storyblocks, Vecteezy, 123RF, Dissolve, FilmHERO, Artlist, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stock Footage Software Market Trends and Innovations
Automated content indexing and rights verification technologies are restructuring how video assets surface in search workflows. Platform operators are racing to deploy machine learning tools that compress the gap between creative intent and licensed footage retrieval.
Neural search algorithms are consolidating keyword-based discovery into semantic understanding systems. Advertising agencies in London and New York are adopting these tools to locate footage by mood, color palette, or narrative context rather than literal tags. The technology is consolidating multiple metadata layers—visual, audio, and temporal—into unified retrieval interfaces that bypass traditional taxonomy limitations.
The EU AI Act's transparency requirements for automated decision-making are reshaping how European platforms deploy recommendation engines. Facial recognition indexing must now expose confidence thresholds and training data sources to comply with GDPR accountability principles. German post-production houses are restructuring their compliance workflows to document algorithmic tagging decisions for broadcast regulator review.
Creative teams are abandoning perpetual licensing in favor of project-based subscription tiers. High-volume streaming producers in Los Angeles and London are negotiating enterprise agreements that bundle footage access with editorial tool licenses. The United Kingdom's independent production sector shows the strongest migration toward these consolidated procurement models, driven by cash flow management pressures from commissioning delays.
Stock Footage Software Market Segmentation
Segmentation in stock footage software reveals how procurement patterns diverge between high-volume streaming producers and sporadic commercial users. Each dimension—service model, end-user workflow, infrastructure preference, and functional capability—creates distinct competitive battlegrounds for platform operators.
Service Type:
Upgrade cycles in stock footage procurement accelerate as creative teams abandon perpetual licenses for fluid consumption models that match project cadence.
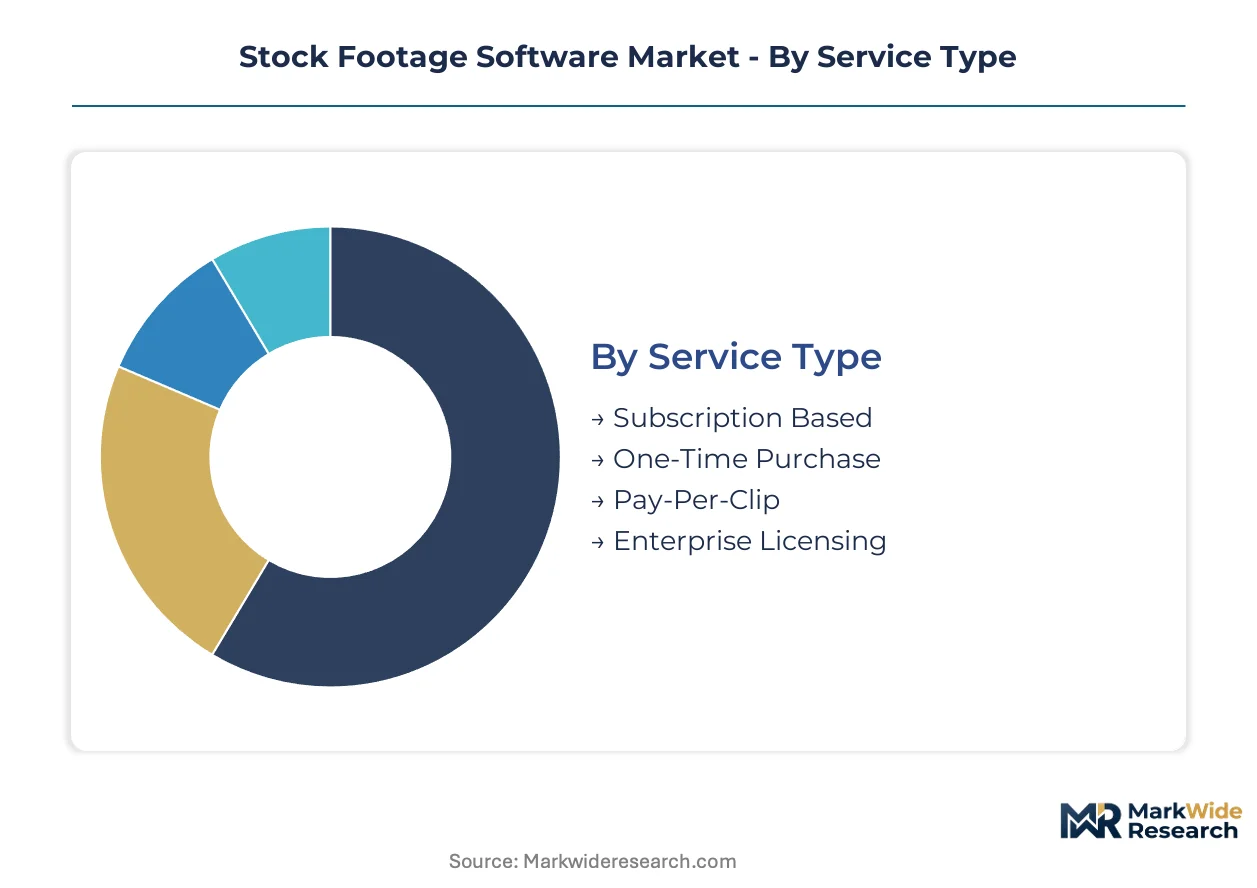
- Subscription Based:Flat-rate monthly or annual plans bundle unlimited or capped downloads across resolution tiers. Streaming platform producers in Los Angeles and London favor these structures for cash flow predictability amid commissioning delays.
- Enterprise Licensing:Multi-year agreements with broadcast networks and studio conglomerates capture the highest per-contract values. These arrangements include custom indemnification terms and dedicated account management for high-stakes productions.
- One-Time Purchase:Perpetual licenses for specific clips suit occasional users with sporadic project needs.
- Pay-Per-Clip:Micro-transaction models serve freelancers requiring single assets without recurring commitments.
Subscription Based sits at the top of the volume ranking, with Enterprise Licensing climbing the fastest as broadcast networks consolidate procurement.
End User:
Cost tier differentiation separates professional production houses from individual practitioners who prioritize accessibility over feature depth.
- Advertisers:Agencies in New York and London drive demand for rapid turnaround tools with brand-safe content curation. Campaign compression timelines force investment in AI-powered search and automated rights clearance.
- Content Creators:YouTube and TikTok producers constitute the fastest-expanding user base. These operators favor mobile-optimized interfaces and social-native aspect ratio libraries over traditional broadcast formats.
- Filmmakers:Independent directors and documentary producers seek archival and cinematic footage with narrative specificity.
- Educators:Universities and e-learning platforms require simplified licensing for classroom and distribution use.
Advertisers command the highest revenue per seat, while Content Creators are expanding most quickly across emerging platform economies.
Deployment:
Geographic distribution of post-production talent is forcing infrastructure decisions that balance latency against data sovereignty requirements.
- Cloud-Based:Browser-native asset streaming eliminates local storage overhead and enables real-time collaboration across dispersed editing teams. Post-production houses in Germany standardize on these architectures to support remote workflows.
- SaaS:Fully managed platforms with automatic feature updates reduce IT overhead for mid-market agencies. These deployments integrate directly with editing software through API connections.
- Hybrid:Mixed environments preserve sensitive assets on-premises while leveraging cloud for general stock libraries.
- On-Premises:Legacy installations persist in broadcast facilities with strict content security protocols.
Cloud-Based deployment dominates new implementations, with SaaS gaining share fastest among agencies without dedicated IT staff.
Feature:
Customer maturity determines which functional capabilities command premium positioning versus baseline expectations.
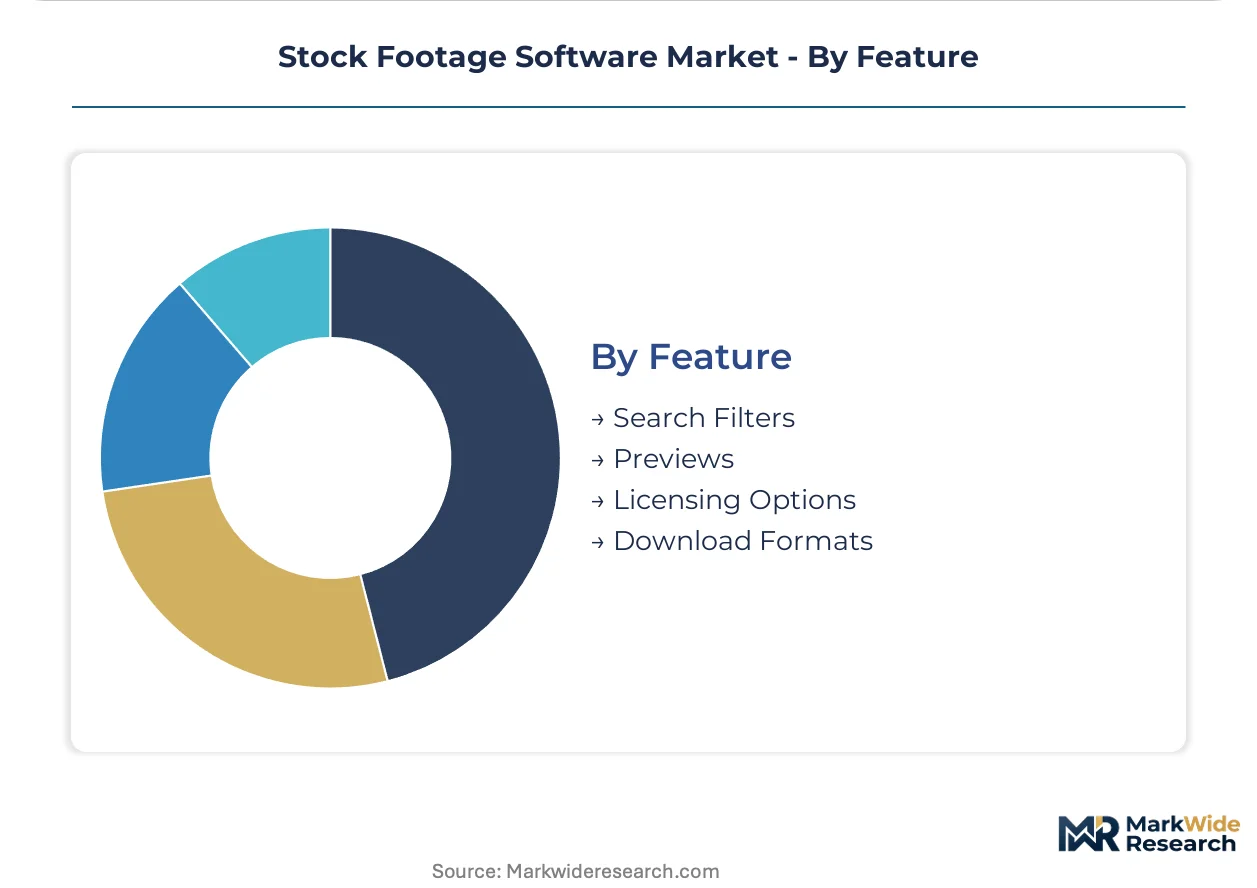
- Search Filters:Neural algorithms now consolidate keyword, visual, and audio metadata into semantic retrieval systems. Advanced implementations support mood, color palette, and narrative context queries beyond literal tagging.
- Licensing Options:Rights-managed and royalty-free frameworks with automated territory detection reduce legal review cycles. These tools must expose confidence thresholds to satisfy EU AI Act transparency mandates.
- Previews:Watermarked low-resolution streaming enables creative evaluation before purchase commitment.
- Download Formats:Resolution scaling from proxy to 8K with codec flexibility serves diverse delivery requirements.
Search Filters represent the primary differentiation battleground, with Licensing Options showing the steepest investment trajectory as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between the EU AI Act and US disclosure frameworks is creating compliance-cost arbitrage that favors platform investment in jurisdictions with clearer AI governance rules. Production procurement is migrating toward markets where automated rights clearance operates within settled legal boundaries.
United States
Advertising agencies in New York and Los Angeles drive platform subscription growth through compressed campaign timelines. The FCC's transparency requirements for sponsored content create additional compliance layers for footage distributed across broadcast and streaming channels. Post-production houses in California standardize on cloud-native architectures to support remote editorial teams.
Germany
Broadcast networks in Berlin and Munich require GDPR-aligned automated tagging for archival retrieval systems. The EU AI Act mandates confidence threshold disclosure for facial recognition indexing, accelerating platform compliance investment. Regional advertising agencies outside the capital cities lack dedicated procurement workflows, creating whitespace for localized German-language interfaces.
United Kingdom
Independent production companies in London favor consolidated procurement models bundling footage access with editorial tools. The country's national film archive partnerships unlock exclusive period content for streaming platform original strategies. Post-production clusters in Soho and Manchester are restructuring compliance workflows to document algorithmic decisions for regulator review.
India
Content creators on YouTube and TikTok constitute the fastest-expanding user base for mobile-optimized stock footage interfaces. The country's central bank guidelines on digital payment infrastructure influence subscription billing architecture for platforms targeting the mid-market. Production houses in Mumbai and Bengaluru are adopting cloud-based collaboration tools to support geographically dispersed editing teams.
Japan
Broadcast facilities in Tokyo maintain strict content security protocols that slow cloud migration relative to Western markets. METI guidelines on AI system transparency shape how platforms deploy recommendation engines for domestic users. Post-production specialists in Osaka are negotiating enterprise agreements that bundle footage licensing with local editing software integration.
Stock Footage Software Market Competitive Landscape
United States producers anchor the subscription-based tier; European specialists hold positions in rights-managed archival content. The vendor base clusters around three strategic archetypes: platform aggregators with proprietary contributor networks, ecosystem-anchored providers with native creative tool integration, and flat-rate subscription specialists reducing per-project friction. M&A activity concentrates on API-first distribution channels and automated metadata technology licensing.
Within the platform aggregator tier, Shutterstock and Getty Images exemplify network-effect positioning built on exclusive contributor relationships. Adobe Stock occupies the ecosystem-anchored position through Creative Cloud integration, while Artlist represents the flat-rate subscription model targeting high-volume production workflows. These three archetypes capture divergent procurement preferences across advertising agencies, streaming producers, and independent filmmakers.
| Leading Market Players |
|---|
| Shutterstock |
| Adobe Stock |
| Getty Images |
| Storyblocks |
| Vecteezy |
| 123RF |
| Dissolve |
| FilmHERO |
| Artlist |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up platform aggregators dominate the stock footage software landscape, concentrating contributor network ownership across fewer holding structures and compressing pricing discipline through standardized subscription tiers. This ownership pattern feeds directly into supply behavior: exclusive talent agreements with top videographers create artificial scarcity that props up enterprise licensing premiums, while flat-rate subscription models mask underlying cost structures from high-volume users in Los Angeles and London.
Pricing Analysis
Distributor margins in the enterprise licensing channel capture substantial value from broadcast networks requiring custom indemnification terms. Three-tier pricing structure across premium, standard, and economy levels segments buyers by resolution requirements and usage rights breadth, with 8K cinematic footage commanding substantial premiums over proxy-grade social content. Cost compression in the mid-market subscription tier is intensifying because Artlist and Storyblocks compete aggressively on flat-rate positioning. Freelancers and individual YouTube producers exhibit the highest price sensitivity, while studio conglomerates negotiating multi-year enterprise agreements prioritize legal risk transfer over per-clip economics.
Supply Chain Analysis
Direct-to-OEM API channels handle hyperscale demand from video editing software integrations, bypassing traditional marketplace discovery layers. Contributor networks concentrate in the United States, the United Kingdom, and Germany, where dense advertising agency clusters sustain professional videographer livelihoods. Raw material dependencies include cloud storage infrastructure, transcoding compute capacity, and metadata tagging labor pools. Single-source vulnerability runs through proprietary contributor exclusives held by Shutterstock and Getty Images, creating sourcing bottlenecks when competing platforms seek comparable cinematic quality. Distribution runs through browser-native streaming architectures that eliminate local storage overhead for post-production houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stock footage software market reads as a late-cycle quality story where buyer procurement is migrating toward premium specifications—AI-powered semantic search, automated rights clearance, and 8K delivery infrastructure—that separate professional-grade platforms from commodity alternatives.
For Market Incumbents: To counter generative video substitution from Adobe Firefly and synthetic media tools, Shutterstock and Getty Images should deepen exclusive contributor network lock-in through revenue-sharing improvements and expedited payment terms. Backward integration into automated metadata technology—proprietary neural search algorithms—preserves differentiation against ecosystem-anchored competitors. Channel control through API-first distribution partnerships with DaVinci Resolve and Final Cut Pro anchors high-volume user workflows. For New Entrants and Emerging Players: The price-point gap between premium enterprise licensing and economy subscription tiers opens whitespace for mid-market specialists targeting regional advertising agencies outside Berlin and Munich. German-language interfaces with GDPR-aligned compliance documentation capture underserved procurement workflows in secondary cities. Mobile-optimized interfaces for India's YouTube and TikTok creator economy represent the most penetrable geography, with social-native aspect ratio libraries as the specific go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among archival documentary specialists with exclusive national film archive partnerships in the United Kingdom. Long-term viability across the next decade hinges on regulatory moats—platforms with documented EU AI Act compliance infrastructure and GDPR-aligned algorithmic transparency. The signal to watch is contributor contract renegotiation velocity: platforms clarifying synthetic media training rights fastest will avoid IP disputes that stall platform development.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Distribution Partnership | Direct Final Cut Pro integration locks in Los Angeles post-production house workflows. |
| Contributor Network Exclusivity Expansion | Revenue-sharing improvements with top German videographers block competitor access to cinematic quality. |
| EU AI Act Compliance Infrastructure | Documented algorithmic tagging transparency satisfies Berlin broadcast regulator review requirements. |
| Archival Documentary Partnership | United Kingdom national film archive access unlocks exclusive period content for streaming originals. |
| Neural Search Algorithm Development | Semantic mood and color palette retrieval bypasses traditional keyword taxonomy limitations for New York agencies. |
Research Methodology
Multiple input streams — platform operator interviews, post-production house procurement leads, advertising agency creative directors, and cloud infrastructure specialists — were reconciled against secondary validation from SEC filings of publicly traded content platforms, EU regulatory documentation on AI Act implementation, and trade association data from advertising production guilds. Bottom-up triangulation across contributor network economics and top-down assessment of enterprise licensing contract structures anchored volume estimates.
Historical subscription growth patterns were cross-referenced against panel input from streaming platform producers and broadcast network procurement officers. Segmentation dimensions modeled include service type, end-user workflow, deployment architecture, and feature capability depth, with additional granularity on resolution tier adoption patterns across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating remote post-production distribution trends and generative video substitution risk.
The model assumes a particular technology adoption path; alternative pathways for synthetic media tools displacing traditional stock footage would alter the outlook substantially. Forecasts reflect documented assumptions about regulatory compliance timelines and contributor contract renegotiation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Movie Editing Software Market
Software & Services
Time and Attendance Software Market
Software & Services
Virtual Fitting Software Market
Software & Services
Global Microscope Software Market
Software & Services
Lead Mining Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Network Documentation Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Design Engineering Software Market
Software & Services
Load Balancing Software Market
Software & Services
Global HVAC Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Construction Estimating Software Market
Software & Services
Systems Administration Management Tools Market