
 Data Governance Market | 2026-2036
Data Governance Market Size, Share, and Industry Trends Forecast 2026-2036
Data Governance Market Intelligence
GDPR enforcement is rebalancing the cost-of-entry calculus for data governance vendors across Europe and beyond. Collibra leverages its metadata management lineage to anchor enterprise deployments in heavily regulated sectors. IBM competes through deep integration with hybrid cloud infrastructure and legacy data estates. Alation specializes in data catalog intelligence, differentiating through automated lineage discovery that reduces manual stewardship overhead.
Data governance encompasses the organizational frameworks, technical protocols, and policy mechanisms that ensure data availability, usability, integrity, and security across enterprise systems, typically implemented through metadata repositories, business glossaries, and automated quality scoring engines that enforce defined standards at ingestion and consumption points. Its primary commercial purpose is to reduce regulatory exposure while accelerating trusted analytics for operational and strategic decision-making. Cloud-based deployment models represent the fastest-expanding segment as organizations migrate stewardship functions away from capital-intensive on-premise infrastructure. Metadata management solutions command concentrated investment from enterprises seeking to map sprawling data estates, while compliance management applications draw sustained spending as jurisdictional privacy requirements multiply.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules collectively reshape product roadmaps and procurement criteria for data governance platforms, with the EU AI Act mandating risk classification documentation that feeds directly into governance workflows. ISO 27001 and NIST frameworks further harden baseline security expectations for vendor qualification. Stakeholders must monitor the divergence between EU AI Act risk tiers and emerging U.S. state-level algorithmic accountability requirements to avoid compliance architecture fragmentation.
Market Dynamics
Regulatory fragmentation across jurisdictions is forcing enterprises to deploy adaptive governance architectures capable of simultaneous multi-framework compliance, with automated policy enforcement replacing manual interpretation workflows.
Growth Catalysts
- EU AI Act risk classification:Mandated documentation requirements for automated decision systems are pulling governance platform investment into European financial services and healthcare sectors.
- US state privacy law proliferation:California's CCPA amendments and Virginia's CDPA are compelling multi-state operators to unify consent management and data subject rights fulfillment.
- Metadata automation:Machine learning-powered lineage discovery is compressing time-to-insight for data stewards managing petabyte-scale cloud estates.
Market Restraints
- Implementation cost structure:Enterprise-wide governance deployments require substantial professional services expenditure for legacy system integration.
- Technical debt accumulation:Decades of unstructured data proliferation in on-premise data lakes creates mapping complexity that automation cannot fully resolve.
- Regulatory friction:Divergent SEC cybersecurity disclosure timelines and EU AI Act enforcement calendars create compliance calendar conflicts for multinational corporations.
Strategic Opportunities
- India's digitization mandate:RBI data localization requirements and the Digital Personal Data Protection Act are opening governance platform demand in banking and insurance.
- Healthcare data liquidity:HIPAA information blocking rules and 21st Century Cures Act interoperability mandates are creating governance tool requirements for patient data exchange.
- Edge-to-cloud convergence:IoT data governance at manufacturing sites is driving demand for distributed policy enforcement architectures.
Industry Challenges
- Data steward talent scarcity:Shortage of professionals combining domain expertise with technical metadata management skills is extending implementation timelines.
- Legacy ERP entanglement:SAP and Oracle systems with custom data models require bespoke connector development, inflating integration budgets.
- Cross-border transfer complexity:Schrems II invalidation of Privacy Shield and emerging data sovereignty laws are fragmenting cloud deployment strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Governance Market |
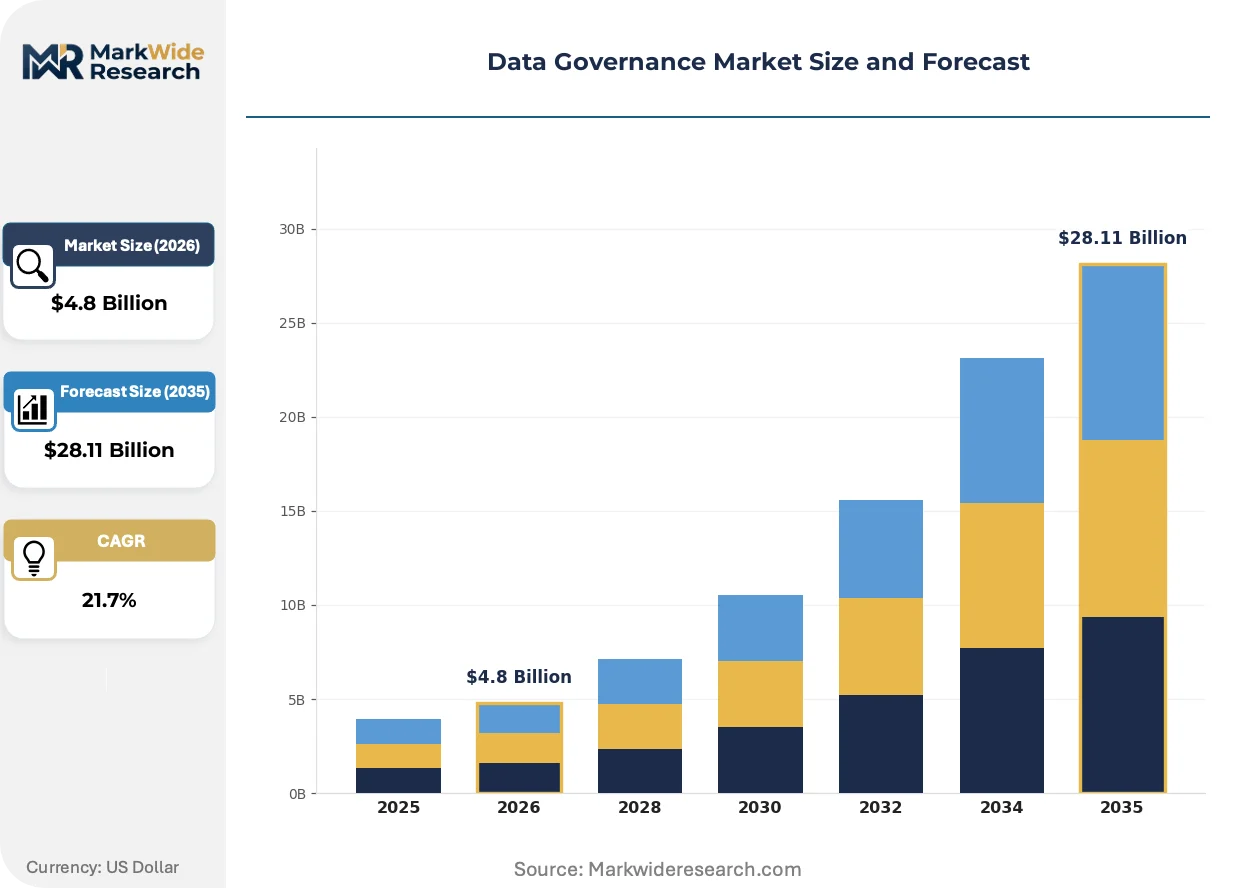
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $28.11 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
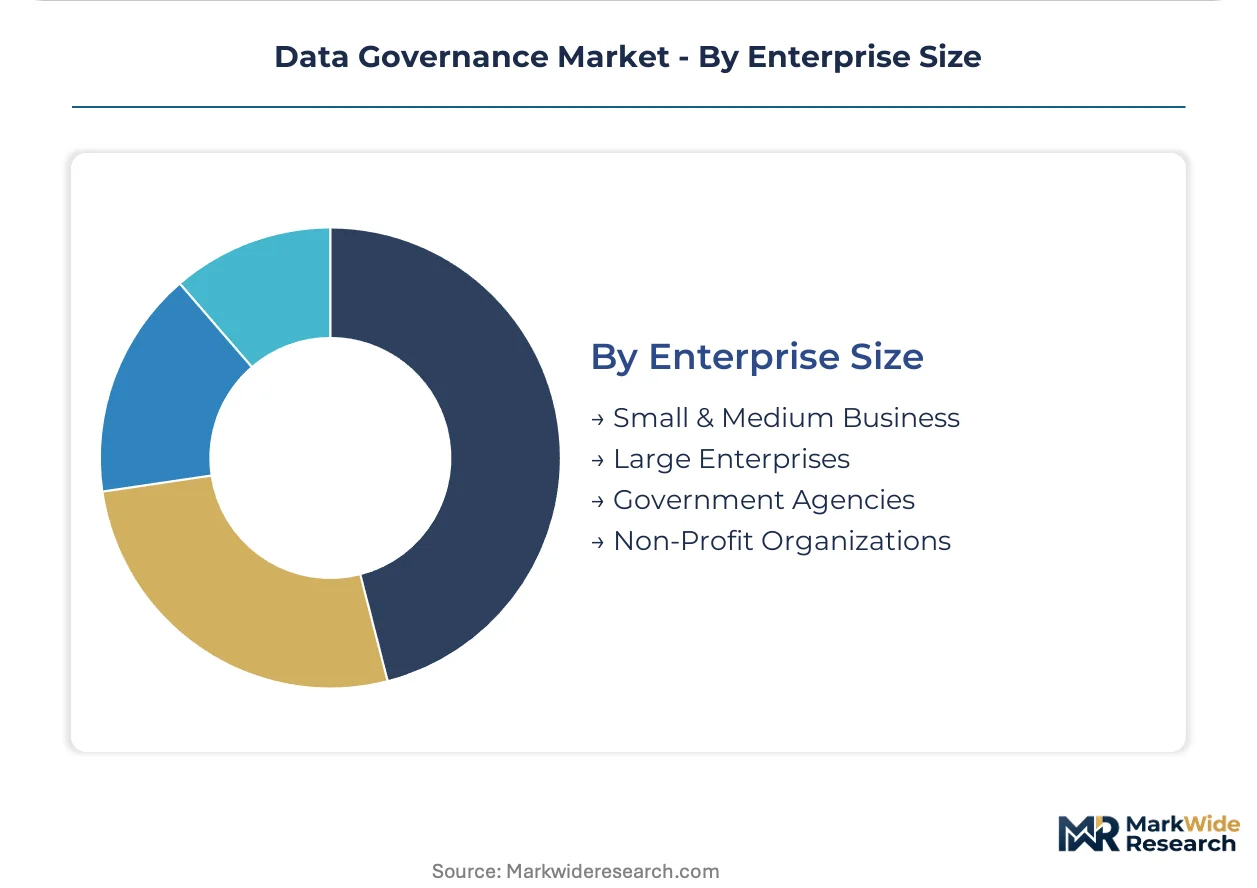
| Segmentation | Solution Type: Data Quality, Metadata Management, Master Data Management, Data Security, Compliance Management, Data Catalog Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services Application Area: Risk Management, Regulatory Compliance, Operational Efficiency, Data Privacy, Customer Insights, Fraud Detection Enterprise Size: Small & Medium Business, Large Enterprises, Government Agencies, Non-Profit Organizations |
| Companies Covered | Alation, Databricks, Collibra, OneTrust, BigID, Informatica, Microsoft, IBM, Atlan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Governance Market Strategic Shifts & Innovations
Active metadata management is displacing passive catalog approaches, with real-time policy enforcement embedding governance directly into data pipelines rather than treating it as a post-hoc documentation exercise.
Automated data quality scoring is electrifying trust establishment in analytics workflows. Financial services firms are deploying these engines at ingestion points to flag anomalous records before they enter downstream systems. The compression of manual validation cycles is reallocating analyst capacity from data preparation to insight generation.
The EU AI Act's risk-based classification system is hardening documentation requirements for high-risk automated decision systems. Deployers must maintain technical logs and human oversight protocols that feed directly into governance repositories. German automotive manufacturers and French healthcare AI developers are restructuring model governance workflows to satisfy conformity assessment obligations.
Chief Data Officers are consolidating vendor relationships, favoring platforms integrating catalog, quality, and policy functions over point solutions. This preference compression is pressuring specialized vendors to expand capability breadth or accept acquisition. The consolidation pattern is most visible in US healthcare and European banking procurement cycles.
Data Governance Market Segmentation
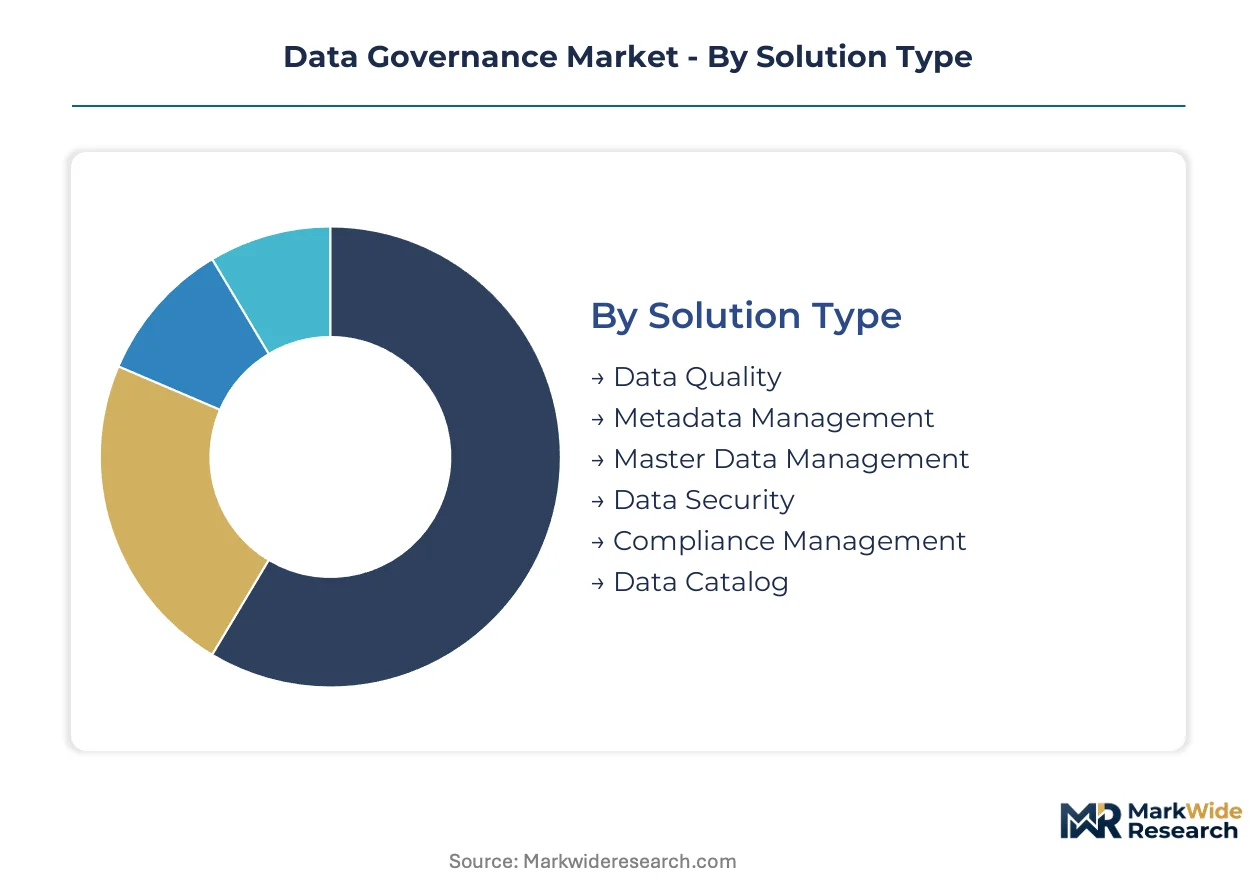
Data governance platforms segment across technical capability, infrastructure posture, and organizational scale. Procurement patterns diverge sharply between regulated incumbents retrofitting legacy estates and cloud-native entrants building governance into greenfield architectures.
Solution Type:
Standardization dominates data quality and security modules, while metadata management and master data management require heavy customization to align with enterprise data models.
- Data Quality:Automated profiling engines scan incoming datasets against predefined business rules, flagging anomalies before downstream consumption. Financial services firms in Germany and the United States deploy these engines at ingestion points to satisfy BaFin and SEC data integrity expectations.
- Metadata Management:Active metadata repositories map technical schemas to business glossaries, enabling lineage tracing across fragmented cloud estates. European banks facing ECB stress test data requirements are consolidating investment here to compress audit preparation cycles.
- Master Data Management:Golden record consolidation for customer, product, and supplier domains.
- Data Security:Access control, encryption governance, and classification tagging for sensitive datasets.
- Compliance Management:Workflow automation for GDPR subject access requests and consent lifecycle management.
- Data Catalog:Self-service discovery interfaces with automated stewardship recommendations.
Most installed capacity flows through Data Quality modules. Expansion is steepest in Metadata Management.
Deployment Model:
Cost tier structures separate capital-intensive on-premise deployments from operational expenditure cloud models, with hybrid architectures commanding premium professional services margins.
- Cloud-Based:Multi-tenant SaaS platforms with API-first policy enforcement embedded directly into data pipelines. Healthcare systems in the United States are migrating here to satisfy HIPAA scalability requirements without datacenter expansion.
- Hybrid:Sensitive data remains on-premise while analytics workloads shift to cloud, with unified policy orchestration across both domains. Japanese automotive manufacturers favor this model to protect proprietary design data while leveraging cloud ML infrastructure.
- On-Premise:Single-tenant installations for air-gapped environments with strict data residency mandates.
- Managed Services:Outsourced stewardship and policy administration with SLA-backed quality metrics.
Cloud-Based deployments now carry the majority of new bookings. Hybrid architectures are gaining share fastest among regulated multinationals.
Application Area:
Customer type differentiation separates risk-averse financial compliance buyers from operational efficiency seekers in manufacturing and retail.
- Regulatory Compliance:Automated evidence collection and audit trail maintenance for multi-jurisdictional frameworks. EU AI Act documentation requirements are pulling investment from French healthcare AI developers and German automotive deployers.
- Risk Management:Data lineage documentation for model risk management and stress testing workflows. US banks facing CCAR submission deadlines prioritize this application to streamline Federal Reserve examination preparation.
- Operational Efficiency:Reduced data preparation overhead through automated quality scoring and catalog curation.
- Data Privacy:Consent management and subject rights fulfillment across fragmented state and national laws.
- Customer Insights:Trusted data foundations for segmentation and personalization analytics.
- Fraud Detection:Real-time anomaly flagging in transaction streams through governance-validated data pipelines.
Regulatory Compliance absorbs the largest share of enterprise procurement. Risk Management is climbing the fastest as Basel III and DORA implementation timelines compress.
Enterprise Size:
Maturity curves separate governance-native digital enterprises from legacy organizations confronting decades of technical debt.
- Large Enterprises:Multi-domain governance programs spanning hundreds of data sources with dedicated Center of Excellence structures. S&P 500 companies in the United States are consolidating vendor relationships here, favoring integrated platforms over point solutions.
- Government Agencies:Citizen data protection with strict sovereignty and classification requirements. India's Digital Personal Data Protection Act is catalyzing state-level procurement for UIDAI-adjacent systems.
- Small & Medium Business:Lightweight cloud-native catalogs with templated policy frameworks.
- Non-Profit Organizations:Donor data stewardship and grant compliance documentation.
Large Enterprises command the deepest per-customer revenue. Government Agencies are expanding most quickly as data localization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data governance platforms originated in US financial services and technology hubs during the post-crisis regulatory expansion of the 2010s, then diffused to European banking centers confronting GDPR implementation and Basel III stress testing requirements.
United States
Fragmented state privacy laws and SEC cybersecurity disclosure mandates are accelerating enterprise procurement of unified governance platforms. The CCPA amendments and Virginia CDPA create multi-jurisdictional compliance complexity for national operators. New York and San Francisco financial services firms are deploying automated lineage discovery to streamline Federal Reserve examination preparation.
Germany
BaFin data integrity expectations and ECB stress test requirements are concentrating investment in metadata management solutions among Frankfurt-headquartered banks. The EU AI Act risk classification system mandates documentation workflows for automated credit scoring and insurance pricing systems. Munich automotive manufacturers are restructuring model governance to satisfy conformity assessment obligations for autonomous driving algorithms.
United Kingdom
Post-Brexit divergence from EU data protection frameworks is forcing London-based financial institutions to maintain dual compliance architectures. The Financial Conduct Authority's operational resilience requirements are pulling governance platform investment into risk management applications. Edinburgh and Manchester insurance clusters are deploying automated quality scoring to compress Solvency II reporting cycles.
India
RBI data localization mandates and the Digital Personal Data Protection Act are catalyzing governance platform demand in Mumbai and Bangalore banking centers. SEBI's cybersecurity guidelines for market infrastructure institutions mandate audit trail capabilities that feed directly into governance repositories. Hyderabad's pharmaceutical exporters are implementing consent management workflows to satisfy EU GDPR requirements for clinical trial data.
Japan
METI's data free flow with trust initiative is creating governance requirements for cross-border enterprise data sharing. The amended Act on Protection of Personal Information mandates breach notification timelines that compress incident response workflows. Toyota City automotive suppliers and Osaka pharmaceutical manufacturers are deploying hybrid architectures to protect proprietary design data while leveraging cloud analytics infrastructure.
Data Governance Market Key Industry Players
The competitive structure tilts toward integrated platform providers over point solution specialists. Consolidation pressure is intensifying as Chief Data Officers favor unified catalog-quality-policy bundles over fragmented vendor relationships. Two strategic archetypes dominate: cloud-native entrants building governance into greenfield data estates, and legacy infrastructure incumbents retrofitting hybrid orchestration capabilities. M&A activity and strategic partnerships represent the primary competitive vectors as specialized vendors seek capability breadth.
Among platform specialists, Collibra and Alation exemplify contrasting positioning archetypes within the metadata intelligence tier, while IBM anchors the legacy infrastructure integration segment. Collibra occupies a position emphasizing business glossary lineage for regulated European deployments. Alation represents the automated discovery vector reducing manual stewardship overhead. IBM sits within the hybrid cloud orchestration space, leveraging deep legacy data estate integration. These three companies illustrate the competitive spectrum from cloud-native specialization to incumbent infrastructure breadth.
| Leading Market Players |
|---|
| Alation |
| Databricks |
| Collibra |
| OneTrust |
| BigID |
| Informatica |
| Microsoft |
| IBM |
| Atlan |
| Others |
Cost & Logistics Intelligence
Chief Data Officers at S&P 500 enterprises concentrate procurement authority for unified governance platforms, compressing vendor relationships into subscription-based SaaS contracts with tiered capability bundles. This buyer concentration shifts pricing power toward integrated platform providers capable of spanning catalog, quality, and policy functions under single master agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the data governance market, with premium tiers bundling active metadata management and automated lineage discovery while economy tiers offer passive catalog functionality. Price differentiation hinges on integration complexity with legacy ERP systems and compliance certification depth for EU AI Act and SEC cybersecurity frameworks. Cost compression in standard tiers is intensifying because cloud-native entrants are undercutting incumbent professional services margins. Mid-market healthcare systems exhibit highest price sensitivity due to constrained IT budgets, while Frankfurt-headquartered banks facing ECB stress test deadlines show lowest sensitivity to secure audit-ready metadata repositories.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for data governance platforms, with vendor professional services teams embedding directly into customer data estates for legacy system integration. Platform development concentrates in the United States, Germany, and India, with engineering talent pools anchored in Silicon Valley, Berlin, and Bangalore. Cloud infrastructure draws from AWS, Azure, and Google Cloud hyperscaler networks, while specialized ML components for automated lineage discovery rest on proprietary algorithm development. Single-source vulnerability in legacy ERP connector development—particularly for SAP and Oracle custom data models—inflates implementation timelines and professional services expenditure. Distribution runs through vendor direct sales organizations with certified implementation partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data governance market has matured into a late-cycle quality story where procurement criteria favor platforms demonstrating automated policy enforcement and real-time metadata activation over passive documentation tools. Demand is shifting toward premium specifications as EU AI Act risk classification mandates harden documentation requirements for high-risk automated decision systems.
For Market Incumbents: Deepen hybrid cloud orchestration capabilities to capture regulated multinational demand for unified policy enforcement across on-premise and cloud estates. Invest in automated connector development for SAP and Oracle legacy systems to reduce implementation timeline overruns that erode professional services margins. Consolidate catalog-quality-policy functions into single platforms before Chief Data Officers complete vendor rationalization cycles. For New Entrants and Emerging Players: Mid-market healthcare systems in the United States represent the most penetrable buyer archetype, as HIPAA scalability requirements drive migration from capital-intensive on-premise infrastructure without demanding bespoke legacy integration. Target cloud-native catalog deployments with templated policy frameworks that compress time-to-value against incumbent professional services-heavy implementations. Pursue channel partnerships with regional healthcare IT consultants to bypass direct sales cost structures. For Investors and Strategic Acquirers: Cloud infrastructure hyperscalers are the most active acquirer in this space, seeking governance layer integration to differentiate data platform offerings. Long-term viability favors vendors with demonstrated EU AI Act conformity assessment workflows and automated lineage discovery IP. Monitor procurement cycle consolidation at S&P 500 enterprises as the inflection signal—accelerated Chief Data Officer vendor rationalization indicates tipping point toward integrated platform dominance over point solution fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Collibra and Alation consolidation pressure favors unified catalog-quality-policy bundles over fragmented point solutions. |
| Acquisition of Specialist Firm | Automated lineage discovery startups attract premium valuations from incumbents seeking to reduce manual stewardship overhead. |
| Geographic Expansion | India's RBI data localization mandates and Digital Personal Data Protection Act open governance platform demand in Mumbai banking centers. |
| Strategic Partnership | Healthcare systems partner with governance vendors to satisfy HIPAA information blocking rules and 21st Century Cures Act interoperability mandates. |
| Product Launch | Active metadata management products displace passive catalog approaches by embedding real-time policy enforcement directly into data pipelines. |
Research Approach
Direct dialogue with Chief Data Officers, enterprise data stewards, vendor product managers, and regulatory compliance officers anchored the qualitative foundation for this analysis. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, ECB stress test data requirements, and cloud hyperscaler earnings disclosures. Bottom-up and top-down triangulation reconciled vendor booking data with enterprise procurement survey patterns across the analysis window.
Bottom-up modeling segmented the data governance market by solution type, deployment model, application area, and enterprise size, with additional granularity for regulatory framework adoption patterns. Top-down validation cross-checked aggregate vendor revenue disclosures against macro-level IT spending surveys. CAGRs were derived from trend extrapolation of cloud migration timelines and compliance mandate enforcement calendars, with particular weighting for EU AI Act risk classification implementation phases and US state privacy law proliferation trajectories.
Inputs from vendor financial disclosures and regulatory implementation schedules were available through the study window; gaps in private company booking data and early-stage cloud-native entrant revenue figures introduce uncertainty bands around segment-level estimates. Forecasts reflect assumptions regarding enforcement timeline adherence and cloud migration acceleration that could shift materially with regulatory delay or macroeconomic contraction. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Ad Network Software Market
Digital Solutions
Real Time Store Monitoring Platform Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Equipment Tracking Software Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Application Performance Management Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
China Digital Twin Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Cloud Logistics Software Market
Digital Solutions
Product As a Service Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Digital Workplace Technologies Market