
 Generative Design Software Market | 2026-2036
Generative Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Generative Design Software Market Analytics
Enterprise software procurement is rewriting how engineering teams access generative design capabilities. Autodesk Inc. leverages its Fusion 360 ecosystem to anchor cloud-native generative workflows for mid-market manufacturers. Siemens AG dominates industrial deployments through its Xcelerator portfolio and deep integration with factory automation systems. Dassault Systèmes SE competes via its 3DEXPERIENCE platform, which sustains high R&D intensity in aerospace and automotive verticals.
Generative design software applies algorithmic optimization, physics-based simulation, and machine learning to automatically produce and evaluate thousands of design permutations against specified constraints. The technology ingests material properties, load conditions, and manufacturing parameters to output geometries that minimize weight, cost, or production time. SaaS delivery models are capturing the fastest expansion as engineering teams demand scalable compute without capital infrastructure. On-premises deployments retain strength in defense and regulated industries where data sovereignty requirements restrict cloud migration. Machine Learning and AI technology layers command premium pricing due to their role in accelerating convergence toward optimal solutions.
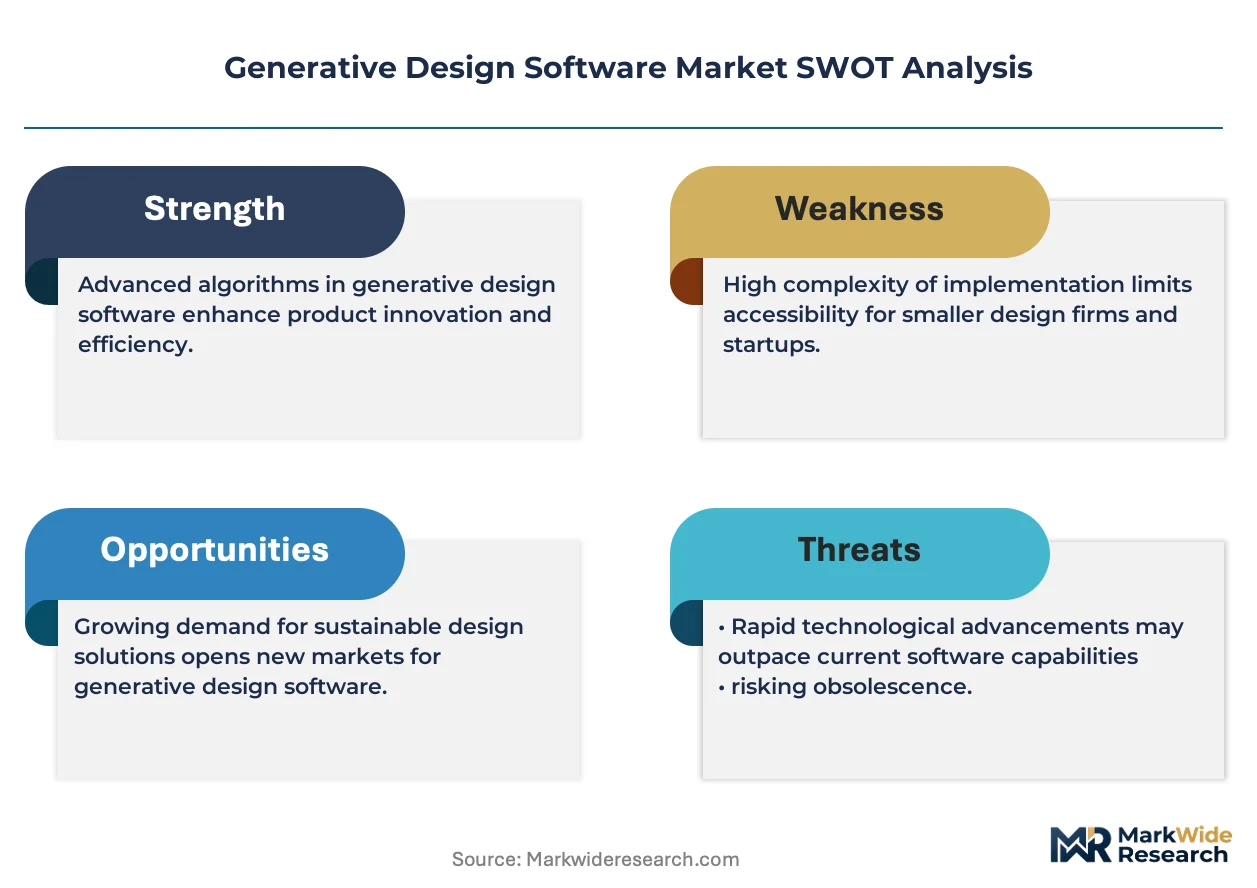
The EU AI Act imposes transparency and risk-classification obligations on automated decision systems used in safety-critical product development, directly affecting how vendors validate generative outputs. The FDA's software-as-a-medical-device framework and ISO 13485 quality management standards shape demand in healthcare device engineering, where generative tools must demonstrate traceable design rationale. China's MIIT algorithmic recommendation provisions and GB standards for industrial software create additional compliance thresholds for market entry. Stakeholders must monitor whether regulatory divergence fragments platform architectures or drives consolidation around interoperable compliance modules.
Market Dynamics
The EU AI Act is collapsing traditional validation workflows for automated design systems, forcing vendors to rebuild compliance architectures around risk-classification tiers and audit trails before algorithms enter safety-critical production environments.
Growth Catalysts
- Aerospace Topology Optimization:Commercial aviation manufacturers deploy generative tools to lightweight structural components under FAA airworthiness mandates, cutting material waste in wing rib and bracket assemblies.
- EU AI Act Compliance Demand:The regulation's transparency obligations for high-risk automated systems create mandatory upgrade cycles among European engineering software buyers seeking pre-certified platforms.
- SaaS Compute Scaling:Cloud-native delivery removes capital barriers for mid-market manufacturers in Germany's automotive clusters, accelerating adoption beyond Fortune 500 engineering departments.
Market Restraints
- GPU Compute Cost Volatility:Training and inference workloads for physics-ML hybrids expose buyers to NVIDIA supply constraints and cloud instance pricing spikes that distort three-year TCO models.
- Data Sovereignty Fragmentation:Defense primes and national security contractors in the US, France, and China maintain on-premises mandates that block SaaS penetration in high-margin segments.
- Topology-to-Manufacturing Gap:Optimized lattice structures often exceed current CNC, casting, or additive production tolerances, requiring costly design rework or capital equipment upgrades.
Strategic Opportunities
- Healthcare Device Engineering:FDA's software-as-a-medical-device framework and ISO 13485 traceability requirements create white space for generative platforms that automate design rationale documentation.
- China MIIT Algorithmic Provisions:GB standards for industrial software and algorithmic recommendation rules favor domestic vendors with embedded compliance modules, opening partnership pathways for foreign platforms.
- Digital Twin Convergence:Integration with real-time factory telemetry and predictive maintenance systems extends generative design into operational optimization, capturing lifetime value beyond initial geometry generation.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Shortages of engineers fluent in thermal-structural-fluid coupling slow deployment velocity and force vendors to build automated expertise into product interfaces.
- Legacy PLM Integration Friction:Siemens Teamcenter, Dassault ENOVIA, and PTC Windchill environments require custom API development and data model mapping that extends implementation timelines by 6-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generative Design Software Market |
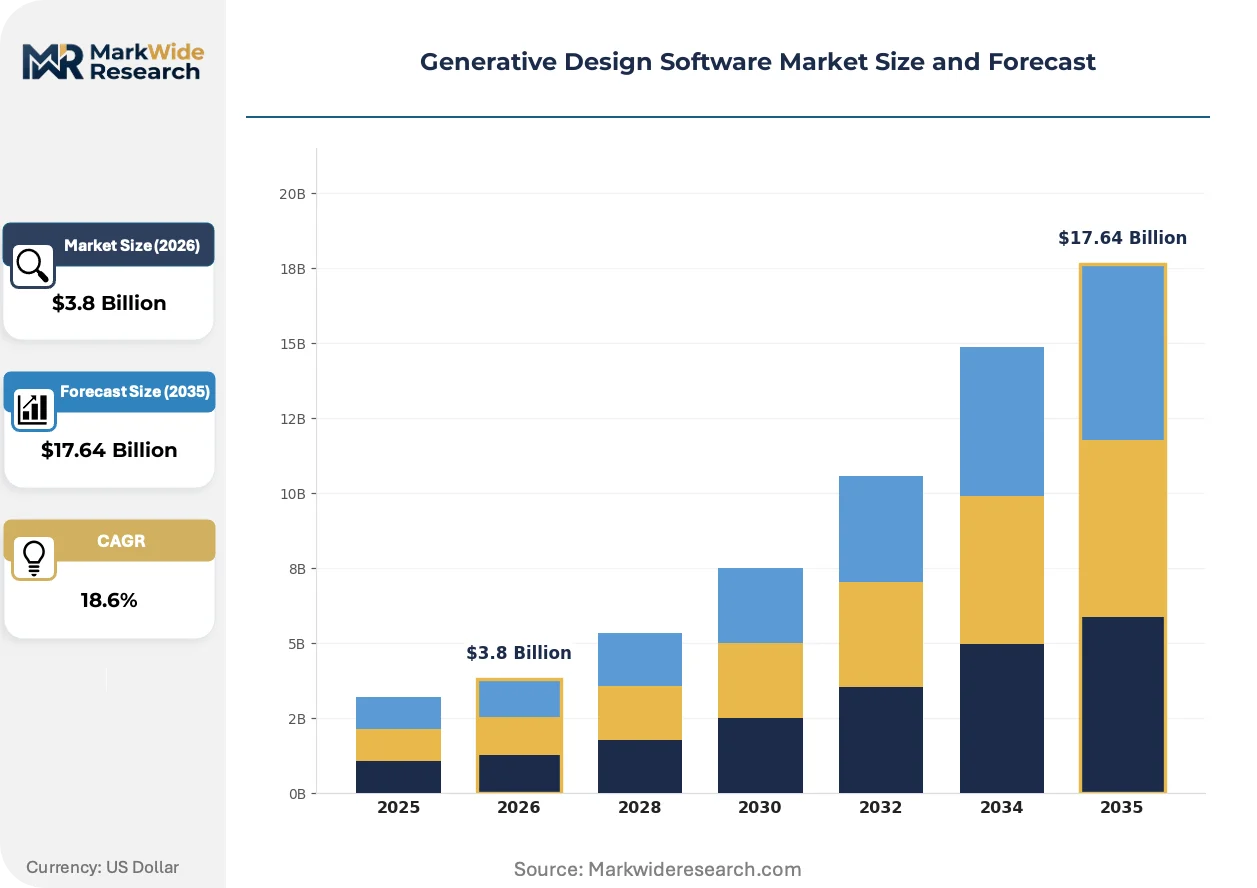
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, SaaS, Platform, Tool End User: Manufacturers, Designers, Engineers, Architects Technology: Machine Learning, AI, Simulation, Cloud-Based Deployment: On-Premises, Cloud, Hybrid, Subscription |
| Companies Covered | Autodesk Inc., Dassault Systèmes SE, PTC Inc., Siemens AG, Hexagon AB, Bentley Systems, Incorporated, Altair Engineering Inc., ANSYS Inc., nTopology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generative Design Software Market Evolving Landscape
Algorithmic design automation is collapsing the boundary between conceptual engineering and production-ready geometry, compressing iteration cycles from weeks to hours while embedding compliance validation directly into generative workflows.
Physics-informed neural networks are collapsing the computational cost of high-fidelity simulation, enabling real-time exploration of design spaces that previously required overnight batch processing on HPC clusters. Automotive powertrain engineers at BMW and Porsche now evaluate thousands of thermal management configurations during single design sessions. The structural consequence is collapsing hardware procurement cycles as cloud inference substitutes for dedicated simulation workstations.
The EU AI Act's risk-based classification system is mandating explainability layers and human-in-the-loop checkpoints for generative outputs used in safety-critical product development. Industrial software vendors must now document training data provenance, model performance benchmarks, and failure mode analyses to maintain CE marking eligibility. German automotive suppliers and French aerospace subcontractors are prioritizing platforms with pre-validated compliance modules to accelerate procurement approvals.
Engineering software procurement is fragmenting from perpetual enterprise licenses toward consumption-based SaaS tiers with embedded professional services. Mid-market manufacturers in Italy and Spain now access generative capabilities through monthly subscriptions rather than seven-figure capital commitments. The shift is most visible among industrial machinery producers seeking flexible scaling for project-specific optimization campaigns without long-term vendor lock-in.
Generative Design Software Market Segmentation
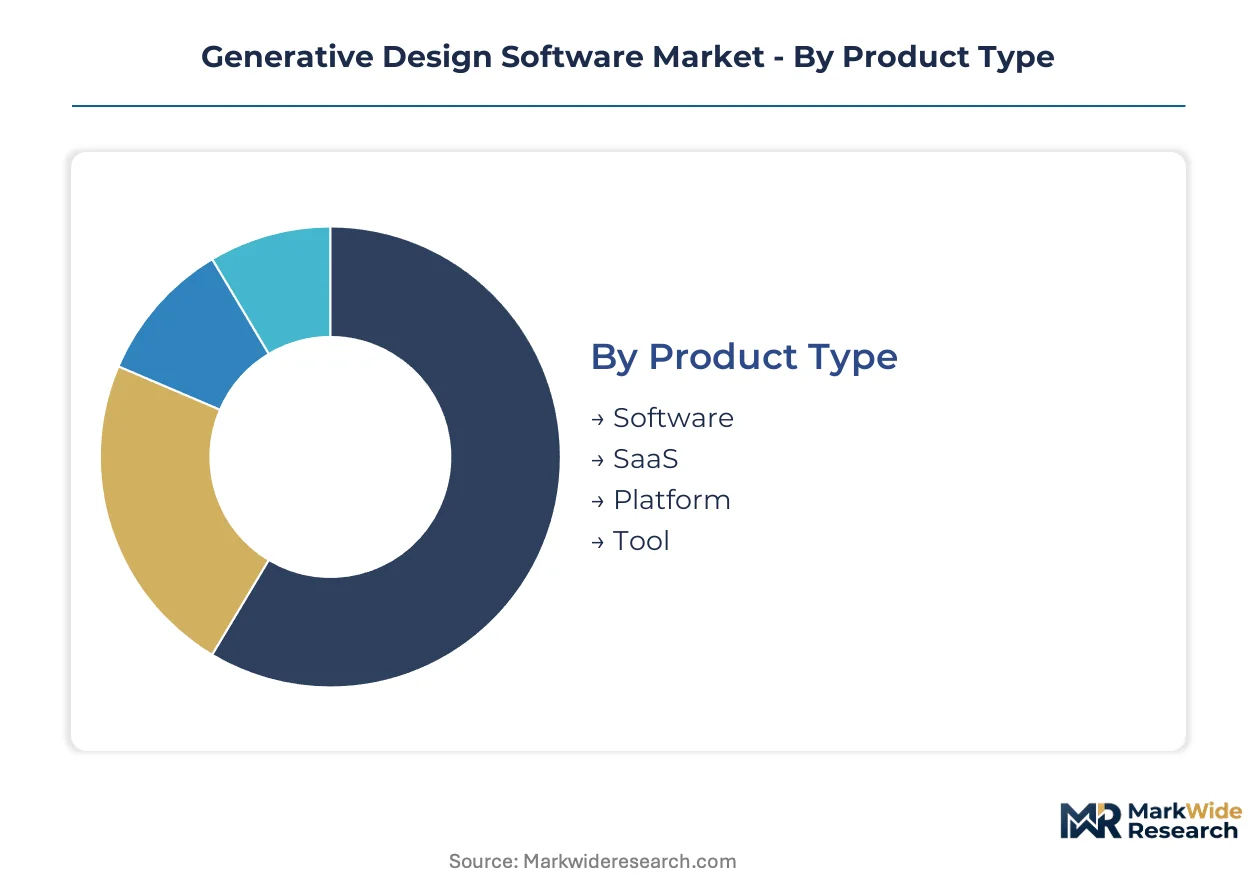
Generative design software segments reflect divergent buyer capabilities, regulatory constraints, and compute infrastructure maturity. Procurement patterns split between capital-intensive perpetual licenses and consumption-based cloud tiers, while deployment choices trace data sovereignty requirements across defense, healthcare, and cross-border engineering collaborations.
Product Type:
Mature on-premises installations coexist with emerging cloud-native architectures as buyers balance customization depth against operational agility.
- Software:Perpetual-license packages deliver deep CAD integration and offline operation for air-gapped defense facilities. German automotive suppliers favor these for Teamcenter-connected workflows where data residency is non-negotiable.
- SaaS:Browser-delivered generative engines eliminate hardware procurement cycles and scale compute elastically for project-specific optimization campaigns. Italian industrial machinery producers access topology optimization through monthly subscriptions rather than seven-figure capital commitments.
- Platform:Integrated 3DEXPERIENCE-type environments bundle generative modules with PLM, simulation, and manufacturing execution. Aerospace primes in France deploy these for end-to-end traceability under EU AI Act documentation requirements.
- Tool:Point solutions address narrow use cases such as lattice generation or structural validation. Mid-market manufacturers in Spain adopt these for targeted bracket and heat sink optimization without enterprise platform overhead.
Software retains volume leadership; SaaS holds the steepest expansion curve.
End User:
Technical sophistication and procurement authority vary sharply across user types, shaping interface complexity and pricing tier design.
- Manufacturers:Factory-floor engineering teams prioritize direct CAM output and production feasibility validation. Tier-1 suppliers in Stuttgart's automotive cluster demand generative outputs that map cleanly to existing CNC and additive equipment.
- Designers:Industrial design studios emphasize aesthetic control and material expression alongside structural efficiency. Furniture and consumer product developers in Milan leverage generative tools for organic form exploration with rapid prototyping integration.
- Engineers:Deep-domain specialists require multiphysics coupling and failure mode analysis for safety-critical applications. Powertrain engineers at BMW and Porsche evaluate thousands of thermal management configurations during single design sessions.
- Architects:Building designers apply generative methods to structural shells and facade systems under material cost and code compliance constraints. Practices in Barcelona use these tools for complex geometry rationalization with embedded fabrication logic.
Engineers command the highest per-seat pricing; manufacturers represent the broadest addressable base.
Technology:
Underlying algorithmic approaches differentiate solution capabilities, convergence speed, and explainability for regulated environments.
- Machine Learning:Neural surrogate models accelerate design space exploration by orders of magnitude versus traditional simulation. Physics-informed architectures now enable real-time evaluation of configurations that previously required overnight HPC batch processing.
- AI:Broader cognitive automation layers handle constraint parsing, design rationale generation, and compliance documentation. EU AI Act transparency obligations force vendors to expose training data provenance and failure mode analyses for high-risk system outputs.
- Simulation:Finite element and computational fluid dynamics engines provide ground-truth validation for generative proposals. Defense contractors in the US maintain on-premises simulation clusters for classified geometry development.
- Cloud-Based:Elastic infrastructure removes capital barriers and enables massive parallel exploration of design permutations. German mid-market manufacturers access scalable compute without dedicated IT infrastructure investments.
Simulation anchors trust in regulated industries; cloud-based delivery is climbing the fastest as procurement shifts to operational expenditure models.
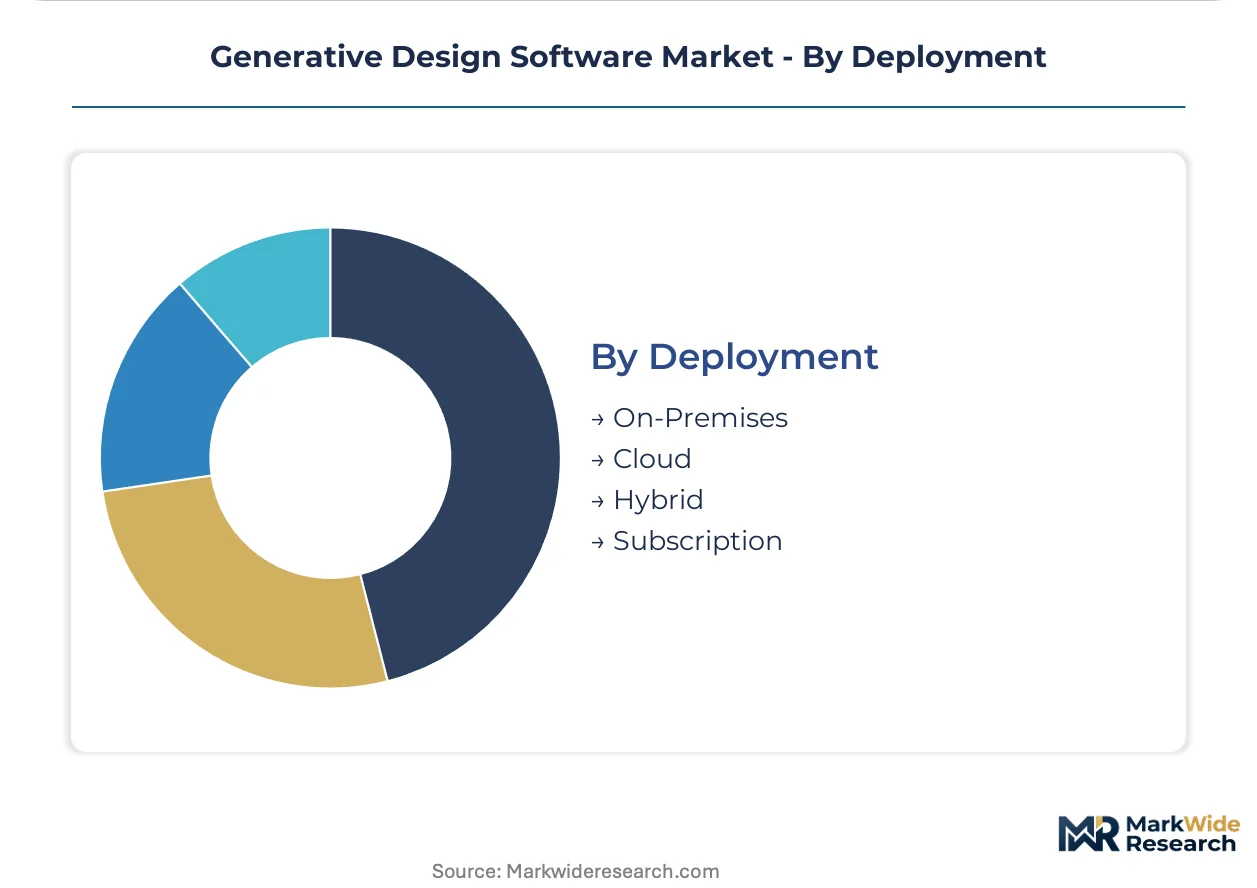
Deployment:
Infrastructure location and commercial structure reflect data sensitivity, integration depth, and buyer cash flow preferences.
- On-Premises:Air-gapped installations serve national security contractors and classified aerospace programs where cloud connectivity is prohibited. French defense primes maintain these configurations for DGA compliance.
- Cloud:Fully managed services abstract hardware procurement and maintenance for engineering teams without IT specialization. Spanish industrial machinery producers scale generative capabilities project-by-project without long-term vendor lock-in.
- Hybrid:Split architectures keep sensitive IP on-premises while bursting compute-intensive optimization workloads to cloud infrastructure. Healthcare device developers in Switzerland use this model for FDA software-as-a-medical-device submissions.
- Subscription:Recurring revenue models align vendor incentives with customer success and reduce upfront capital requirements. Italian automotive suppliers favor monthly arrangements for flexible scaling across product development cycles.
On-premises defends high-margin regulated segments; subscription pricing is gaining share fastest among mid-market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine fiber cables linking Frankfurt to Singapore and transatlantic routes landing at Marseille and New York anchor the data infrastructure underwriting generative design software distribution. These digital arteries enable real-time cloud compute access for engineering teams across manufacturing clusters.
Germany
Automotive powertrain optimization and aerospace structural validation drive procurement among Stuttgart and Munich engineering clusters. The EU AI Act mandates algorithmic transparency documentation for safety-critical design outputs. Siemens AG anchors industrial deployments through its Xcelerator portfolio integrated with factory automation systems in Baden-Württemberg.
United States
Defense primes and commercial aviation manufacturers sustain demand for air-gapped, on-premises installations. The FAA airworthiness mandates shape topology optimization requirements for wing rib and bracket assemblies. Boeing and Lockheed Martin operations in Washington State and Texas maintain classified geometry development on dedicated simulation clusters.
France
Aerospace subcontractors prioritize platforms with pre-validated EU AI Act compliance modules to accelerate DGA procurement approvals. The EASA regulatory framework extends transparency obligations to automated design systems in aviation. Dassault Systèmes SE sustains high R&D intensity through its 3DEXPERIENCE platform serving Toulouse and Paris-Saclay clusters.
China
MIIT algorithmic recommendation provisions and GB standards for industrial software create compliance thresholds favoring domestic vendors with embedded modules. Dual carbon goals accelerate lightweighting demand in electric vehicle battery enclosure design. BYD and CATL engineering teams in Shenzhen and Ningbo deploy generative tools for thermal management optimization.
Japan
Precision machinery and robotics manufacturers seek lattice generation capabilities for actuator housing miniaturization. METI industrial digitization incentives subsidize cloud migration for mid-tier suppliers. Toyota and Honda engineering centers in Nagoya and Tokyo evaluate generative outputs against JIS structural validation standards.
Generative Design Software Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform ecosystems rather than point solutions. Three archetypes dominate: diversified industrial software conglomerates with PLM integration depth, specialized topology optimization vendors with manufacturing-native outputs, and cloud-native challengers attacking mid-market subscription tiers. Competitive dynamics center on strategic partnerships with hardware OEMs and vertical integration into simulation compute infrastructure.
Within the diversified platform tier, Autodesk Inc., Dassault Systèmes SE, and Siemens AG occupy positions defined by CAD-PLM integration breadth rather than generative specialization alone. These firms exemplify the archetype of industrial software incumbents leveraging existing manufacturing customer relationships to embed algorithmic design capabilities. Their geographic footprints—California, France, and Germany respectively—mirror the concentration of aerospace and automotive engineering demand they serve.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Dassault Systèmes SE |
| PTC Inc. |
| Siemens AG |
| Hexagon AB |
| Bentley Systems, Incorporated |
| Altair Engineering Inc. |
| ANSYS Inc. |
| nTopology Inc. |
| Others |
Value Network & Pricing Analysis
Submarine fiber cables linking Frankfurt to Singapore anchor cloud compute cost dynamics that concentrate supply-side pricing power among hyperscale infrastructure providers while forcing downstream differentiation between premium compliance-certified tiers and economy SaaS offerings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by EU AI Act certification grade and integration depth with legacy PLM systems. Cost compression in the economy tier is intensifying because mid-market manufacturers in Italy and Spain demand flexible monthly subscriptions without enterprise platform overhead. Manufacturers represent the most price-sensitive buyer archetype, while aerospace primes in France and defense contractors in the United States absorb premium pricing for air-gapped, compliance-validated installations.
Supply Chain Analysis
GPU supply concentration between Taiwan and South Korea dominates upstream vulnerability for physics-ML hybrid workloads that generative design platforms depend on. The technology stack draws from NVIDIA silicon, cloud hyperscaler infrastructure, and specialized simulation compute clusters. Single-source vulnerability in advanced semiconductor fabrication threatens delivery timelines for training-intensive deployments. Distribution runs through direct enterprise sales for on-premises platforms and self-serve SaaS marketplaces for mid-market subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative design software demand tracks aerospace procurement cycles, with commercial aviation fleet renewal programs and defense modernization budgets creating cyclical expansion windows.
For Market Incumbents: Insulate platform ecosystems against cloud-native challengers by deepening backward integration into simulation compute infrastructure and accelerating EU AI Act pre-certification modules. Siemens AG and Dassault Systèmes SE must defend their PLM integration moats as Autodesk Inc. pushes Fusion 360 generative workflows downstream. Priority investment belongs to automated multiphysics expertise layers that offset talent scarcity in thermal-structural-fluid coupling. For New Entrants and Emerging Players: Establish a beachhead in healthcare device engineering where FDA software-as-a-medical-device traceability requirements create compliance friction that incumbent platforms have not fully addressed. Mid-market industrial machinery producers in Spain and Italy offer the most penetrable geography due to subscription pricing acceptance and limited legacy PLM entanglement. A channel partnership strategy with specialized CAM and additive manufacturing hardware vendors accelerates time-to-revenue against direct enterprise sales models. For Investors and Strategic Acquirers: EU AI Act implementation deadlines reshape the acquisition landscape toward platforms with pre-validated risk-classification architectures and audit trail capabilities. Long-term viability across the next decade favors vendors that capture operational optimization value beyond initial geometry generation through digital twin convergence. Watch for inflection signals in MIIT algorithmic compliance module adoption rates among China-based engineering teams.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens PLM connectivity for Siemens Teamcenter and Dassault ENOVIA environments in German automotive clusters. |
| Regulatory Pre-Certification | Accelerates procurement approvals under EU AI Act risk-classification tiers for French aerospace subcontractors. |
| Cloud-Native SaaS Expansion | Captures mid-market manufacturers in Italy and Spain seeking scalable compute without capital infrastructure. |
| Healthcare Compliance Module Development | Opens FDA software-as-a-medical-device market for traceable design rationale automation. |
| Digital Twin Convergence | Extends lifetime value through real-time factory telemetry integration in Stuttgart production environments. |
Research Methodology
A spread of perspectives from aerospace procurement officers, automotive platform engineers, cloud infrastructure architects, and regulatory compliance leads converged on the working assumptions. Primary fieldwork combined structured interviews with engineering software buyers and secondary validation through SEC filings, hyperscaler capex disclosures, and EU regulatory documentation. Bottom-up sizing of deployment volumes across on-premises, cloud, and hybrid architectures triangulated against top-down market value estimates.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across deployment model, organization size, vertical application, and regional adoption pattern. CAGRs emerged from iterative convergence testing against historical procurement cycle patterns and infrastructure investment trajectories. Physics-informed neural network adoption curves and EU AI Act compliance upgrade timelines served as industry-specific forecast inputs.
Stress conditions across GPU supply availability, cloud compute pricing volatility, and regulatory implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about aerospace fleet renewal intensity and mid-market SaaS migration velocity. Material shifts in MIIT algorithmic enforcement posture or FAA airworthiness mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Cloud Testing Market
Software & Services
Hadoop Market
Software & Services
Global Retail Execution Software Market
Software & Services
Jobsite Management Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Recruitment Software Market
Software & Services
United States Donation Management Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Interview Scheduling Software Market
Software & Services
Global Test Data Management Market
Software & Services
EDA Tools Market
Software & Services
Global Animation Software Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
Global Fixed Asset Management Software Market