
 Technology CAD Software Market | 2026-2036
Technology CAD Software Market Size, Share, and Industry Trends Forecast 2026-2036
Technology CAD Software Market Intelligence
Cloud-native architecture is fragmenting the traditional desktop CAD stack into modular, API-first components that integrate with factory automation and digital-twin platforms. Autodesk leverages its construction cloud footprint to extend parametric design into building-information workflows. Siemens anchors its position through deep integration with industrial IoT and semiconductor process simulation. Dassault Systèmes differentiates by sustaining high-end multiphysics capabilities for aerospace and automotive OEMs.
Technology CAD Software encompasses computational tools used to model, simulate, and optimize semiconductor device fabrication processes, lithography patterns, and material behavior at nanometer scales, typically operating across process nodes from micrometer to sub-3nm geometries. These platforms enable foundries and IDMs to reduce silicon prototyping cycles by predicting electrical characteristics before mask production. Cloud-based CAD deployments are capturing the fastest expansion as foundries distribute simulation workloads across elastic compute clusters, while on-premises installations retain dominance among defense-aerospace contractors with stringent data-sovereignty requirements. Simulation features command the deepest margin pools due to their dependency on specialized solver licensing and HPC infrastructure.
The EU Chips Act and REACH chemical-compliance frameworks are tightening substrate-material documentation requirements that TCAD vendors must embed in process libraries. The FDA's software-as-medical-device guidance and ISO 26262 automotive functional-safety standards are extending validation protocols into CAD tools used for chip designs in life-critical applications. Stakeholders should monitor how export-control expansions on advanced-node EDA tools reshape customer eligibility and regional licensing structures.
Market Dynamics
Cloud-native TCAD architectures are fragmenting the traditional desktop simulation stack, forcing vendors to restructure licensing models around elastic compute consumption rather than perpetual seats. Foundries in Taiwan and South Korea now distribute lithography simulation workloads across distributed clusters, compressing silicon prototyping cycles from months to weeks.
Growth Catalysts
- Sub-3nm Process Migration:Leading foundries require predictive doping profiles and quantum transport models that only advanced TCAD platforms deliver, pulling simulation spending ahead of tape-out schedules.
- REACH Chemical-Compliance Frameworks:European substrate-material documentation mandates force process libraries to embed traceability metadata, expanding TCAD module attach rates for environmental compliance.
- Automotive Functional-Safety Standards:ISO 26262 validation protocols extend into chip-design tools for life-critical applications, requiring fault-simulation capabilities that standard EDA suites lack.
Market Restraints
- HPC Infrastructure Concentration:Elastic simulation workloads depend on hyperscaler compute pools concentrated in US and East Asian data center corridors, creating geographic lock-in and latency penalties for European users.
- Specialized Solver Licensing Costs:Poisson-Boltzmann and Monte Carlo transport solvers carry per-core fees that scale non-linearly with node complexity, pricing mid-tier IDMs out of advanced-node simulation.
- Legacy Tool Inertia:Defense-aerospace contractors with TS/SCI clearance requirements maintain on-premises installations, fragmenting vendor R&D across incompatible deployment architectures.
Strategic Opportunities
- EU Chips Act Domestication:European foundry construction in Dresden and Leuven creates demand for TCAD tools compliant with EU data-sovereignty rules, favoring vendors with regional cloud presences.
- Digital-Twin Convergence:Integration between TCAD process simulation and factory IoT platforms enables real-time etch-rate calibration, opening attach revenue in smart-manufacturing stacks.
- Photonics Process Extension:Silicon photonics foundries require coupled electro-optical solvers that semiconductor TCAD vendors are repurposing, creating cross-selling paths into datacom transceiver supply chains.
Industry Challenges
- Multiphysics Talent Scarcity:Converged thermal-electrical-mechanical simulation requires expertise spanning solid-state physics, numerical methods, and HPC optimization that university pipelines undersupply.
- Export-Control Compliance:Expanding US BIS restrictions on advanced-node EDA tools force vendors to implement customer-eligibility screening that delays sales cycles and complicates multinational licensing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technology CAD Software Market |
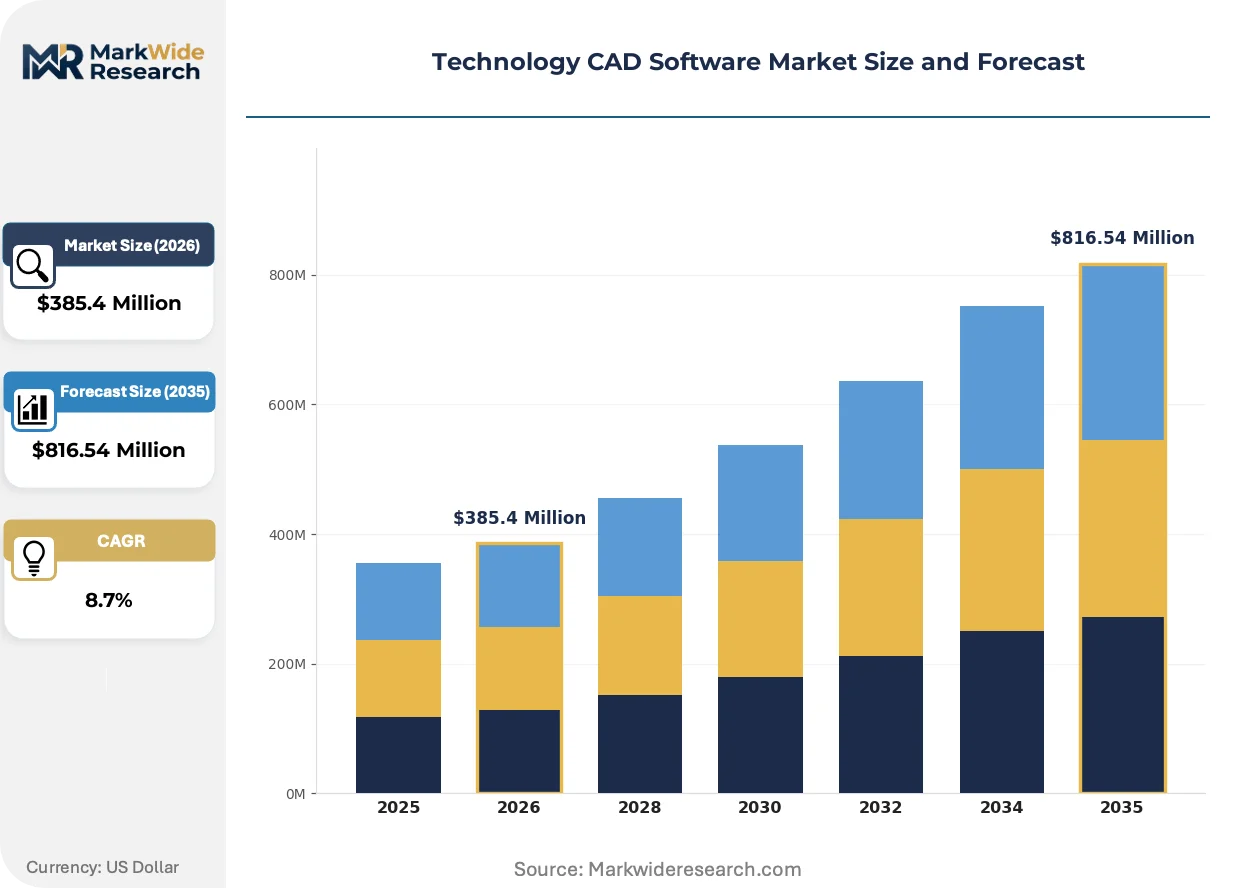
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D CAD, 3D CAD, Cloud-Based CAD, Open-Source CAD Deployment: On-Premises, SaaS, Hybrid, Desktop End User: Aerospace, Automotive, Manufacturing, Construction Feature: Parametric Design, Simulation, Collaboration Tools, Integrated Workflow |
| Companies Covered | Siemens, Gstarsoft, Autodesk, Kubotek3D, MecSoft Corporation, Dassault Systèmes, Zuken, DraftSight, PTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technology CAD Software Market Strategic Shifts & Innovations
Artificial intelligence is penetrating TCAD workflows at three distinct points: surrogate model generation, inverse design optimization, and automated mesh refinement. These capabilities are compressing the trade-off between simulation accuracy and computational cost that has governed foundry tool selection for two decades.
Machine-learning surrogate models are digitizing the traditional finite-element simulation pipeline for doping and diffusion processes. Samsung Foundry and TSMC now train neural operators on historical wafer data to predict electrical characteristics without full drift-diffusion solves. This compression enables real-time process-window exploration during development, shifting TCAD from verification to predictive design.
The EU AI Act's risk-classification framework is imposing documentation requirements on simulation tools used for safety-critical chip design. Vendors must now maintain model-card registries explaining training data provenance and uncertainty quantification for AI-augmented solvers. Automotive and medical-device segments are responding by demanding vendor-provided conformity assessments before tool procurement.
Consumption-based licensing is displacing perpetual-seat contracts as the dominant procurement model for cloud-deployed TCAD. Foundries negotiate simulation-hour credits against committed cloud spend, unbundling solver access from hardware ownership. This shift is most visible in Taiwan and South Korea, where foundry consolidation has concentrated buyer power and forced vendors to absorb infrastructure risk.
Technology CAD Software Market Segmentation
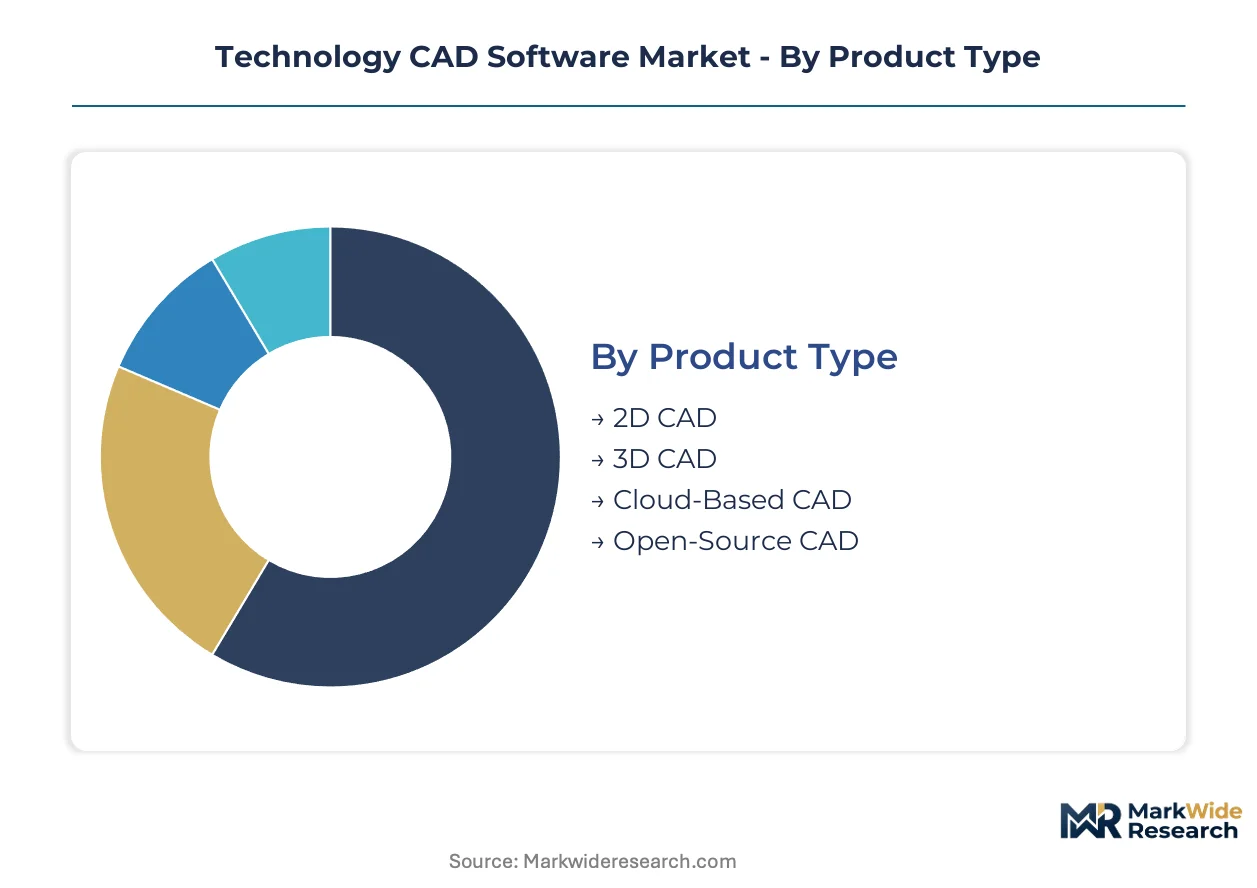
Technology CAD Software segmentation reveals how foundry procurement priorities diverge across simulation fidelity requirements, data sovereignty constraints, and integration depth with factory automation stacks. Understanding these fault lines enables vendors to align licensing architectures with customer infrastructure maturity and compliance exposure.
Product Type:
Use-case spectrum spans legacy mask-layout verification through quantum-transport prediction, with dimensional capability and compute elasticity determining addressable customer tiers.
- 2D CAD:Layout-centric tools for planar device geometry and lithography mask verification retain dominance among mature-node foundries in Taiwan and South Korea. Demand concentrates where photolithography simulation requirements stay within established optical proximity correction frameworks.
- 3D CAD:FinFET and gate-all-around transistor architectures require volumetric meshing for parasitic extraction and thermal profiling. TSMC and Samsung Foundry deploy these platforms for sub-5nm node development, pulling spending toward multi-physics solver bundles.
- Cloud-Based CAD:Elastic compute pools enable distributed process-window exploration without capital-intensive HPC ownership.
- Open-Source CAD:Academic and early-stage IDM adoption favors community-developed mesh generators and device simulators.
Established volume favors 2D CAD; emerging adoption favors Cloud-Based CAD.
Deployment:
Cost tier segmentation separates capital-intensive infrastructure ownership from operational expenditure models, with regulatory clearance requirements fragmenting procurement patterns.
- On-Premises:Air-gapped installations serve defense-aerospace contractors with TS/SCI clearance mandates and EU data-sovereignty requirements under GDPR and EU Chips Act domestication clauses. BAE Systems and Thales maintain captive simulation farms for export-controlled node access.
- SaaS:Consumption-hour licensing aligns foundry spending with tape-out cycles rather than perpetual seat commitments. Taiwan Semiconductor Manufacturing Company negotiates elastic solver credits against committed cloud infrastructure spend.
- Hybrid:Split architectures isolate sensitive doping profiles on-premises while pushing mesh-intensive solves to external clusters.
- Desktop:Individual engineer workstations persist for rapid geometry prototyping and educational deployment.
On-Premises retains margin concentration; SaaS climbs the fastest.
End User:
Application-driven segmentation reflects divergent safety-validation requirements and process-node migration timelines across industrial verticals.
- Aerospace:DO-254 and DO-178C avionics standards extend into semiconductor design-tool qualification. Boeing and Airbus suppliers demand fault-simulation capabilities for radiation-hardened device development.
- Automotive:ISO 26262 functional-safety mandates require TCAD platforms with fault-injection and failure-mode coverage documentation. Bosch and Continental foundry partnerships specify validated solver versions for power-device prototyping.
- Manufacturing:Discrete and power semiconductor producers leverage TCAD for yield optimization in analog process flows.
- Construction:Building-systems chip design for HVAC and lighting control draws simplified simulation requirements.
Automotive commands premium pricing; Manufacturing holds volume concentration.
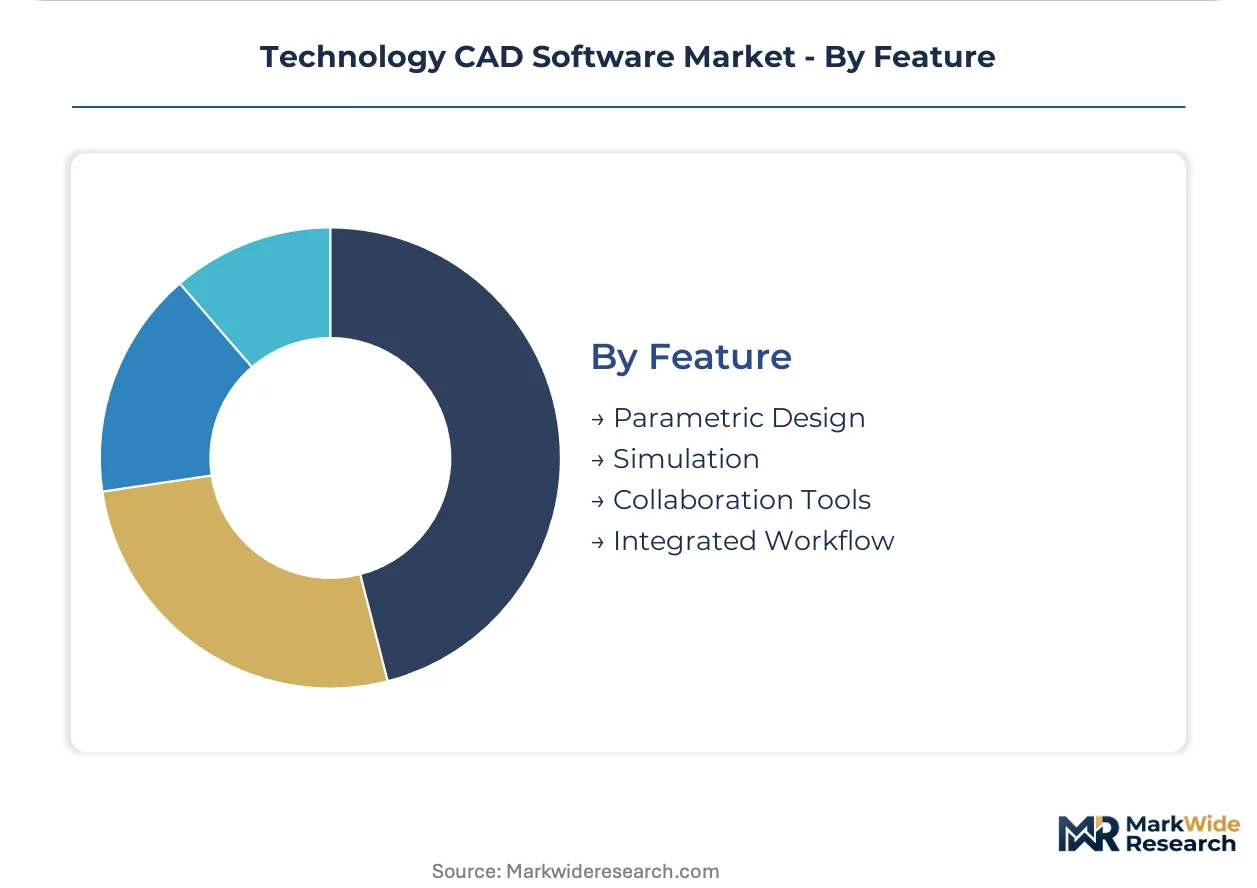
Feature:
Margin structure concentrates in specialized solver modules where numerical-method IP creates differentiation against commoditized geometry engines.
- Simulation:Poisson-Boltzmann drift-diffusion and Monte Carlo transport solvers carry per-core licensing fees scaling non-linearly with node complexity. These capabilities enable predictive doping profile extraction that reduces silicon prototyping cycles.
- Parametric Design:Scriptable geometry kernels allow process engineers to automate device-variant generation across design-of-experiment matrices. Foundries in Dresden and Leuven deploy these capabilities for EU-funded research consortia.
- Collaboration Tools:Version-controlled process-library sharing supports distributed engineering teams across multinational IDM sites.
- Integrated Workflow:EDA tool-chain connectivity compresses handoff friction between TCAD verification and mask synthesis.
Simulation captures deepest margin pools; Integrated Workflow gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean TCAD vendors export process-simulation licenses to European foundry projects in Dresden and Leuven, while Taiwanese cloud providers distribute elastic compute clusters across Southeast Asian manufacturing corridors.
United States
Defense-aerospace contractors in California and Texas drive demand for air-gapped, on-premises TCAD installations with TS/SCI clearance protocols. The Department of Commerce's Bureau of Industry and Security (BIS) restricts advanced-node EDA tool exports, forcing domestic vendors to implement customer-eligibility screening. The Silicon Valley-Pasadena corridor hosts captive simulation farms serving radiation-hardened device programs.
Germany
Automotive power-semiconductor foundries in Stuttgart and Munich require ISO 26262-validated TCAD platforms for fault-injection documentation. The EU Chips Act domestication clauses mandate EU data-sovereignty compliance for process libraries. Dresden's emerging foundry cluster attracts vendors establishing regional cloud presences under REACH chemical-compliance frameworks.
South Korea
Samsung Foundry and SK Hynix compress silicon prototyping cycles through machine-learning surrogate models trained on historical wafer data. The Ministry of Trade, Industry and Energy (METI-aligned Korean policy) subsidizes HPC infrastructure for sub-3nm node development. The Suwon-Giheung corridor distributes lithography simulation workloads across elastic compute clusters.
Taiwan
TSMC negotiates consumption-hour licensing credits against committed cloud infrastructure spend, unbundling solver access from hardware ownership. The National Science and Technology Council prioritizes domestic TCAD capability under semiconductor self-sufficiency programs. The Hsinchu Science Park concentrates foundry consolidation that forces vendors to absorb infrastructure risk.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor demand for materials-characterization modules within TCAD process libraries. METI's semiconductor revitalization strategy funds university-industry consortia for quantum-transport solver development. The Kyoto-Osaka corridor hosts precision-equipment manufacturers integrating TCAD with factory IoT platforms.
Technology CAD Software Market Key Industry Players
Channel-controlling players compete with product-specialist players across deployment architectures, licensing models, and integration depth. The vendor base clusters around three tiers: diversified industrial-software conglomerates with construction and IoT footprints, semiconductor-focused simulation specialists with deep solver IP, and emerging cloud-native entrants offering elastic compute consumption. Dominant competitive moves include restructuring perpetual-seat contracts into simulation-hour credits and establishing regional cloud presences to satisfy EU data-sovereignty requirements.
Within the diversified industrial-software tier, Siemens and Autodesk exemplify channel-controlling strategies that leverage existing construction cloud and factory automation footprints to extend parametric design into adjacent workflows. Dassault Systèmes occupies a position among multiphysics-capable vendors sustaining high-end solver differentiation for aerospace and automotive OEMs. These three companies represent distinct archetypes: infrastructure-anchored platform expansion, cloud-native modular fragmentation, and premium physics fidelity specialization.
| Leading Market Players |
|---|
| Siemens |
| Gstarsoft |
| Autodesk |
| Kubotek3D |
| MecSoft Corporation |
| Dassault Systèmes |
| Zuken |
| DraftSight |
| PTC |
| Others |
Cost & Logistics Intelligence
Overcapacity in mature-node simulation tools across Taiwan and South Korea is compressing license fees for 2D CAD suites while elevating pricing power for sub-3nm solver bundles, forcing vendors to cross-subsidize advanced-node development through consumption-hour premiums on elastic compute clusters.
Pricing Analysis
Process-node pricing gaps separate legacy 2D layout verification at economy tiers from quantum-transport simulation suites commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by solver complexity and certification grade, with ISO 26262-validated platforms extracting brand premiums from automotive IDMs. Pricing pressure stems from foundry consolidation in Hsinchu and Suwon concentrating buyer leverage. Mid-tier IDMs exhibit highest price sensitivity, while defense-aerospace contractors with TS/SCI mandates show lowest elasticity due to captive procurement protocols.
Supply Chain Analysis
Extended payment terms now stretch 90-120 days as South Korean and Taiwanese foundries leverage supply-chain finance facilities to defer solver licensing costs until tape-out milestones. HPC infrastructure concentrates in the United States, Taiwan, and South Korea, with Poisson-Boltzmann solver modules drawing from specialized numerical-method IP held by German and Japanese specialists. Single-source vulnerability permeates quantum-transport algorithm libraries, where university pipeline constraints limit qualified developer availability. Distribution runs through direct enterprise sales teams serving consolidated foundry accounts, supplemented by cloud marketplace listings for consumption-hour credits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology CAD Software is restructuring as a service-attach opportunity, with simulation-hour consumption credits and compliance-documentation subscriptions expanding faster than perpetual-seat license revenue across Taiwanese and South Korean foundry accounts.
For Market Incumbents: Harden data-sovereignty positioning by establishing EU cloud presences in Dresden and Leuven before EU Chips Act domestication clauses harden procurement eligibility. Defend solver IP moats through backward integration into HPC infrastructure partnerships that lock in elastic compute pricing. Cloud-native entrants with API-first architectures threaten traditional desktop stack margins; incumbents must accelerate modular fragmentation of their own platforms to neutralize this substitution risk. For New Entrants and Emerging Players: Build out photonics process-extension capabilities for silicon photonics foundries serving datacom transceiver supply chains, where coupled electro-optical solvers remain undersupplied by incumbent semiconductor TCAD vendors. Target European research consortia in Dresden and Leuven for initial reference deployments, leveraging EU funding visibility to establish credibility before scaling to commercial foundry accounts. Position through open-source mesh generator integration to lower adoption friction among academic and early-stage IDM segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native TCAD architectures as vendors absorb infrastructure risk through consumption-hour licensing, improving cash conversion cycles relative to on-premises perpetual-seat models. Acquire specialists with machine-learning surrogate model capabilities trained on historical wafer data, which compress simulation accuracy-cost trade-offs and enable real-time process-window exploration. Monitor export-control expansion signals from the US Bureau of Industry and Security as inflection indicators for customer-eligibility screening costs that could delay multinational licensing velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep TCAD-EDA tool-chain connectivity compresses handoff friction for TSMC tape-out schedules. |
| Geographic Expansion | Regional cloud presences in Dresden satisfy EU Chips Act data-sovereignty compliance for Bosch partnerships. |
| Strategic Partnership | HPC infrastructure alliances with Taiwanese cloud providers lock in elastic compute pricing for Samsung Foundry. |
| Acquisition of Specialist Firm | Machine-learning surrogate model capabilities trained on wafer data enable real-time process-window exploration. |
| Product Launch | Silicon photonics solver modules open attach revenue in datacom transceiver supply chains serving Meta and Google. |
Research Approach
The analysis maps process simulation, lithography modeling, and device characterization sub-sectors, each validated through semiconductor foundry process engineers, EDA procurement officers, and cloud infrastructure architects. Primary interviews with TCAD vendor product managers, IDM R&D directors, and hyperscaler compute specialists combined with secondary validation against SEC filings, hyperscaler capex disclosures, and EU Chips Act implementation guidance. Bottom-up triangulation across solver licensing volumes and top-down reconciliation against foundry capital expenditure patterns anchored market sizing.
Assumption sets held fixed the current export-control regime and EU data-sovereignty framework while varying foundry consolidation velocity and machine-learning surrogate model adoption curves across the analysis window. Segmentation dimensions modeled span deployment architecture, process node complexity, end-use vertical safety requirements, and regional regulatory cluster. CAGRs derived from elasticity-adjusted price-volume relationships and solver attach-rate projections, with inputs including tape-out cycle compression metrics and HPC infrastructure expansion schedules from Taiwanese and South Korean cloud providers.
Stress conditions across export-control expansion severity, EU cloud-presence buildout timelines, and quantum-transport talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume continuation of current regulatory and competitive structures; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Cloud-Based Dental Practice Management Software Market
Software & Services
Application Server Market
Software & Services
Global Help Desk Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Remote Sensing Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
App Development Software Market
Software & Services
Lifecycle Management Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Calorie Metering Software Market
Software & Services
Global Job Evaluation Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Preschool Education Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Drone Mapping Software Market
Software & Services
Global Managed Application Services Market